ID_BYAN: H1 profit up 17.5%, but Q1 revenue fell 7.7%
Today ID_BYAN released its results for the first half of 2026. Revenue came in at $1,740.1 million, net profit at $410.3 million, and operating cash flow at $488.1 million. Year on year, revenue rose 7.3% and net profit 17.5%, with the net margin improving to 23.6% from 21.5%. However, in the standalone first quarter of 2026, revenue declined 7.7% year on year, contrasting with the half-year growth. At the current price, the stock trades at 25.1 times trailing earnings and offers a dividend yield of 2.6%; our model puts fair value just 3% below the market, so we view the shares as neutral.
Key takeaways
— H1 revenue rose 7.3%, but Q1 revenue fell 7.7% year on year
— Net profit increased 17.5% on margin expansion to 23.6% from 21.5%
— Operating cash flow for H1 was $488.1 million, exceeding net profit
— Dividend yield of 2.6% with a payout ratio of about 66% of earnings
— P/E of 25.1 is a neutral valuation; the portal model's fair value is 3% below the market
— Return on equity of 30.0% supports dividend payments
Attractiveness
Key figures, USD bn
| Metric | H1 2025 | H1 2026 | Change |
|---|---|---|---|
| Revenue | 1.62 | 1.74 | +7.3% |
| Net profit | 0.35 | 0.41 | +17.5% |
| Operating cash flow | 0.58 | 0.49 | -16.1% |
| Net margin | 21.5% | 23.6% | +2.1 pp |
H1 revenue rose 7.3%, but Q1 revenue fell 7.7% year on year
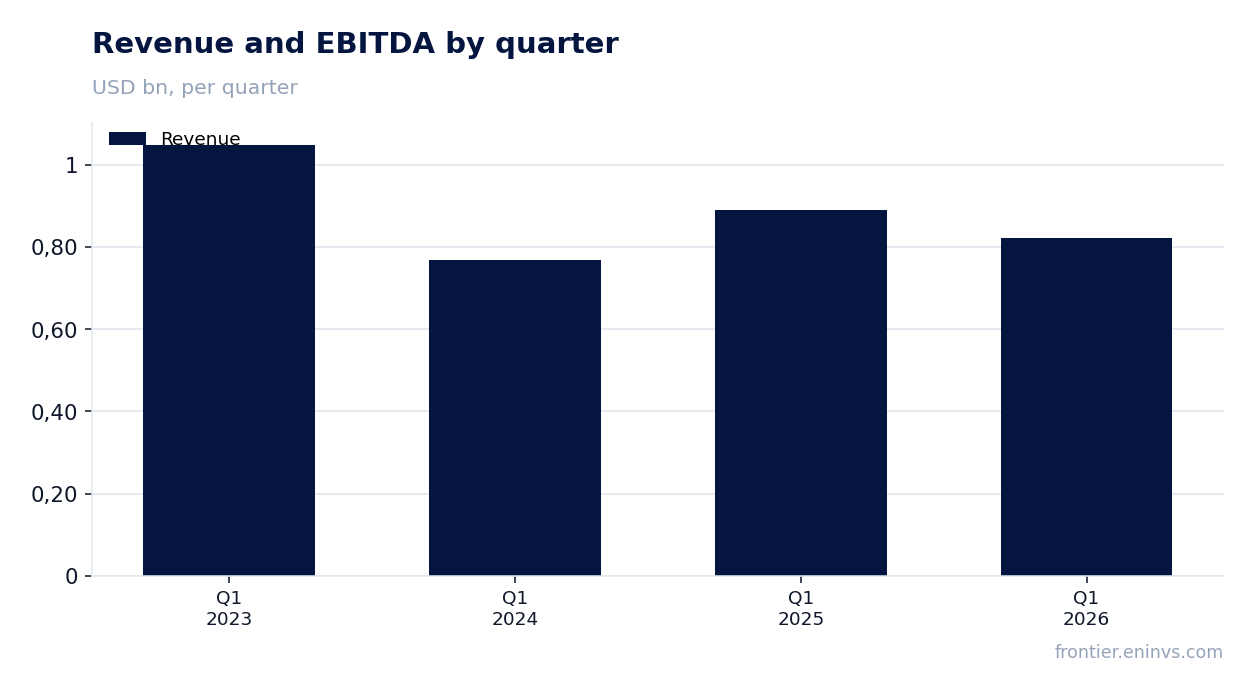
In the first half of 2026, ID_BYAN's revenue reached $1,740.1 million, up 7.3% from the same period last year. However, in the standalone first quarter of 2026, revenue declined 7.7% year on year to $821.7 million. This discrepancy is explained by an acceleration in the second quarter that offset the quarterly decline.
Quarterly dynamics show instability: in Q1 2024 revenue fell 26.7%, then in Q1 2025 it grew 15.7%, and in Q1 2026 it declined again by 7.7%. The half-year growth of 7.3% was achieved thanks to the second quarter, for which separate data is not disclosed but which apparently showed significant growth.
For an investor, it is important that the company can grow revenue for the half-year despite a weak start. However, quarterly volatility persists, and the sustainability of the recovery in the second half is not yet confirmed.
Net profit increased 17.5% on margin expansion to 23.6% from 21.5%
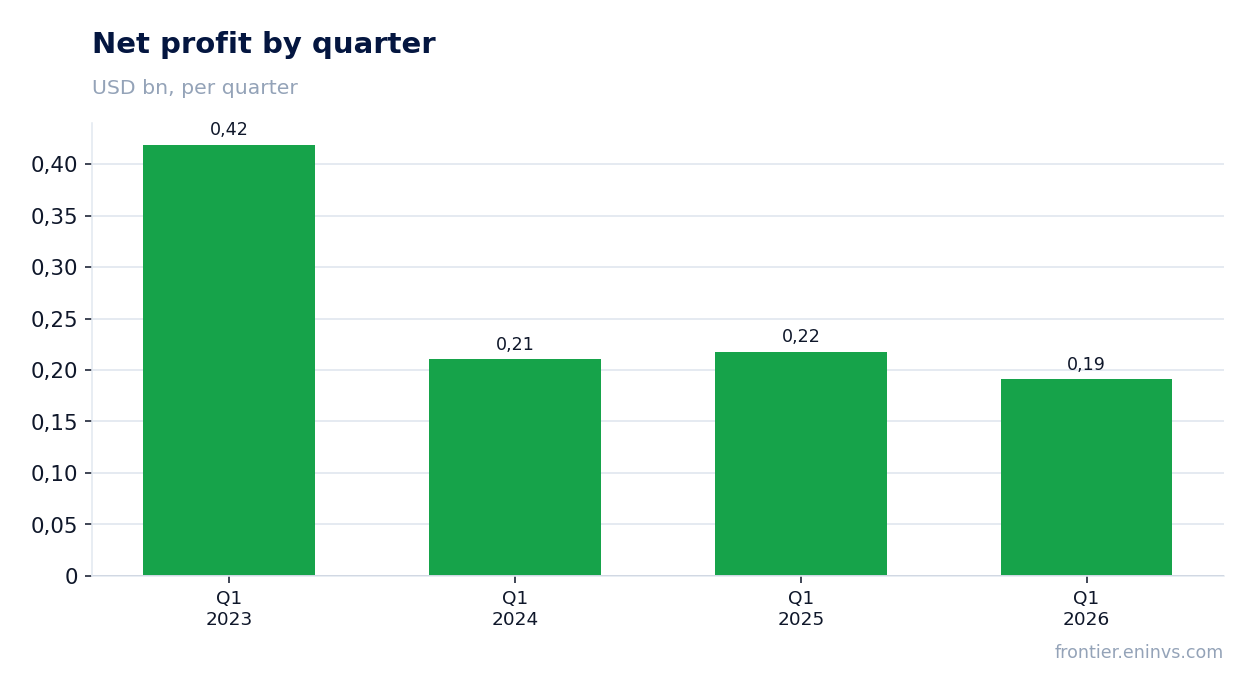
Net profit for the first half of 2026 was $410.3 million, up 17.5% from a year earlier. The net margin rose to 23.6% from 21.5% in the first half of 2025. Thus, profit grew faster than revenue, indicating improved cost control or a change in business mix.
In the standalone first quarter of 2026, net profit was $190.8 million, down 12.4% from $217.9 million in Q1 2025. This decline is consistent with the revenue drop in the quarter, but the half-year margin still improved, suggesting a positive contribution from the second quarter.
Profit growth amid a revenue decline in one quarter could be due to one-off factors or changes in the tax burden, but details are not disclosed. For sustainability, it is important that the margin improvement continues.
Operating cash flow for H1 was $488.1 million, exceeding net profit
Operating cash flow for the first half of 2026 reached $488.1 million, exceeding net profit for the same period by 19.0%. This indicates high earnings quality and the company's ability to generate cash. In the standalone first quarter of 2026, operating cash flow was $215.8 million, also above quarterly net profit ($190.8 million).
The excess of operating cash flow over net profit may be explained by depreciation and other non-cash items, as well as efficient working capital management. This is a positive signal for dividend payments and investments.
However, capital expenditure data is not available, so free cash flow cannot be assessed. For a complete picture, it is important that operating cash flow remains stable and covers investment needs.
Dividend yield of 2.6% with a payout ratio of about 66% of earnings
ID_BYAN's dividend yield over the trailing twelve months is 2.6%. With trailing twelve-month net profit of $767.9 million and a market capitalisation of $19,252.5 million, this corresponds to a payout ratio of about 66% of earnings. This level of payout is moderate and leaves the company room for investment and maintaining financial stability.
For comparison, the key rate in the economy is unknown, but a yield of 2.6% may be less attractive for income-oriented investors, especially considering that the company does not disclose its dividend policy. However, stable operating cash flow and high return on equity (30.0%) support the ability to pay dividends.
A risk to dividends is a possible decline in profit, as happened in the standalone first quarter of 2026, when net profit fell 12.4% year on year. If this trend continues, the payout ratio may rise, limiting the scope for dividend increases.
P/E of 25.1 is a neutral valuation; the portal model's fair value is 3% below the market
The price-to-earnings ratio for the trailing twelve months (P/E LTM) is 25.1. This is a moderate level that appears neither clearly overvalued nor attractive. According to our model, the fair value of the share is 3% below the current market price, indicating it is close to fair valuation.
It is impossible to compare the current P/E with the three-year average, as the FACTS do not contain historical data on the multiple. However, a return on equity of 30.0% and stable operating cash flow support the current valuation.
A change in valuation would require either an acceleration in profit growth or a reduction in risks associated with revenue volatility. For now, the stock is fairly valued, and upside potential is limited.
Return on equity of 30.0% supports dividend payments
ID_BYAN's return on equity (ROE) is 30.0%. This is a high figure, indicating efficient use of capital and the company's ability to generate profit for shareholders. With such profitability, the company can sustain dividend payments even with some decline in profit.
A high ROE also means the company can finance growth from internal resources without resorting to a significant increase in debt. This reduces financial risks and supports business sustainability.
However, to maintain ROE at this level, it is necessary to sustain net margin and asset turnover. In the standalone first quarter of 2026, net profit declined, which could put pressure on the annual ROE if the trend does not reverse.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 19.3 bn USD |
| P/E (LTM) | 25.1 |
| P/B | 7.14 |
| Operating cash flow (LTM) | 0.98 bn |
| ROE | 30.0% |
| Dividend yield (12m) | 2.6% |
Bottom line
ID_BYAN delivered strong results for the first half of 2026: revenue rose 7.3%, net profit 17.5%, and the margin reached 23.6%. However, these gains are overshadowed by a weak first quarter, when revenue fell 7.7% and profit 12.4%. Operating cash flow remains high, exceeding net profit, confirming earnings quality. A dividend yield of 2.6% and P/E of 25.1 appear neutral, and the portal model's fair value is just 3% below the market. For an investor, the key question is whether the company can restore revenue growth in the second half to justify the current valuation.
Open the company's financial profile BYAN →
See also: market overview · valuation map · stock screeners