Frontierby eninvs

Language: EN · RU

Mexico Stocks — Valuations, P/E & Dividends

Guide: Mexican Stocks (2026): Quality Value and the Nearshoring Trade

Related guides: The Cheapest Metals & Mining Stocks (2026) · The Cheapest Bank Stocks in the World (2026)

GDP growth 2026 (proj.) 1.6%Inflation YoY (proj.) 3.9%FX vs USD (3y avg p.a.) -0.5%Macro: IMF World Economic Outlook, April 2026 (Annex tables 1.1.2–1.1.4)
Our recommended portfolios
Performance & current holdings of our strategies for this market — why it makes sense to join.
Commodity-Upsidebacktest CAGR +24% · excess +41%Paper-track · 15 Jun 2026
CAGR +24% · vs index +41% · Sharpe 0.97 · maxDD -37%
Day-4.4%MXX -1.1%
Week-7.3%MXX -1.2%
Month-0.8%MXX -2.2%
By calendar year vs MXX
YearStratMXXΔ
2026*-5.4%-4.8%-0.6%
* partial year
GMEXICOB-4.4%
Signal history & trades →
FVC (quality)backtest CAGR +3% · excess +20%Paper-track · 15 Jun 2026
CAGR +3% · vs index +20% · Sharpe 0.27 · maxDD -13%
Day-0.8%MXX -1.1%
Week-3.0%MXX -1.2%
Month-3.3%MXX -2.2%
By calendar year vs MXX
YearStratMXXΔ
2026*-4.3%-4.8%+0.5%
* partial year
KOFUBL+1.5%BIMBOA-1.4%LABB-1.3%ALSEA-0.2%GMEXICOB-4.4%FEMSAUBD-0.3%AMXB-0.9%WALMEX+0.1%AC-0.8%GCARSOA1-2.3%
Signal history & trades →

Sectors: Airports (3) · Banks (3)

Rows are ordered partly by extraction health (share of stable periods). Hover a row for OK / partial / error counts.

CompanyCountrySectorValue / upsideDiv. %FCF Yield LTMΔ revenue (NII for banks)Δ EBITDA (assets for financials)EV/EBITDA LTMP/E LTMP/B FYROE (ann.)
Grupo Aeroportuario del Sureste (ASUR)
MX_ASUR
MXAirports≥ +300%9.4%0.8%-6.5%7.5x12.5x2.8x26.4%
Alsea
MX_ALSEA
MXRestaurants+80%3.6%1.5%-1.8%24.8%3.9x19.3x3.9x24.6%
Arca Continental (AC)
MX_AC
MXBeverages+42% 4.0%5.9%90.2% ▼53.1%6.5x14.8x2.0x24.1%
Fomento Economico Mexicano (FEMSA)
MX_FEMSA
MXBeverages & retail+17% 6.9%-22.0%6.1% ▼11.2%7.2x23.9x2.4x19.0%
America Movil (AMX)
MX_AMX
MXTelecom+14%2.7%22.4%2.1%3.8%5.6x13.3x2.7x21.7%
Banco del Bajío
MX_BBAJIO
MXBanks+12%8.2%-3.9%8.1%7.5x1.4x16.7%
Grupo Financiero Inbursa
MX_INBURSA
MXBanks+11%2.6%0.8%2.5%8.3x0.9x10.3%
Grupo Mexico (GMEXICOB)
MX_GMEXICO
MXMetals & mining+10%2.5%1.4%32.6%47.7%10.0x19.9x4.3x29.3%
Walmart de México y Centroamérica, S.A.B. de C.V.
MX_WALMEX
MXRetail+4%3.7%9.7%1.9%0.6%7.4x15.8x3.4x18.2%
CEMEX
MX_CEMEX
MXBuilding materials-6%1.0%4.9%0.4%-1.1%7.0x16.1x1.2x7.0%
Grupo Bimbo, S.A.B. de C.V.
MX_BIMBO
MXPackaged foods & bakery-8%1.9%-34.2%-3.3%9.5%6.5x21.4x2.0x7.8%
Orbia Advance Corporation, S.A.B. de C.V.
MX_ORBIA
MXChemicals & building materials-43% 167.1%1.5% ▲-7.2%2.2x1.0x2.8%
Grupo Aeroportuario del Pacífico
MX_GAP
MXAirports3.4%23.2% ▲15.9%11.1x18.2x7.7x55.0%
Grupo Aeroportuario Centro Norte
MX_OMA
MXAirports5.8%9.0%5.9%11.2%9.2x15.1x6.8x40.6%

Work in progress — needs attention

Issuers below have weak extraction, thin market data, missing valuation inputs, or extreme headline YoY/ROE. Hover the row for the checklist.

CompanyCountrySectorValue / upsideDiv. %FCF Yield LTMΔ revenue (NII for banks)Δ EBITDA (assets for financials)EV/EBITDA LTMP/E LTMP/B FYROE (ann.)
Grupo Financiero Banorte
MX_BANORTE
MXBanks+11%8.8%12.8%5.2%9.4x2.2x0.2%
Grupo Carso, S.A.B. de C.V.
MX_CARSO
MXIndustrial conglomerate+9% 1.1%11.6%-4.3% ▼-10.3%12.9x38.0x2.1x4.0%
Genomma Lab Internacional (LAB)
MX_LAB
MXConsumer health+5% 6.3%24.9x1.1x14.4%
Coca-Cola FEMSA, S.A.B. de C.V.
MX_KOF
MXBeverages (bottler)+1%4.0%-1.6%1.1%0.9%16.5x2.7x11.5%
El Puerto de Liverpool, S.A.B. de C.V.
MX_LIVERPOL
MXRetail (department stores)-74%2.9%-25.0%-0.2%-6.2%7.9x0.8x4.3%

Earnings analysis

Short take-aways from recent corporate results and commodity trends.

Beverage Binge and Mining Boom Leave Staples Stagnant

This quarter's earnings season is defined by an extreme divergence: beverage and metals companies posted explosive double-digit revenue growth, while consumer staples and industrial conglomerates struggled with declines. The gap between the top and bottom industries is a staggering 94.5 percentage points, as the median revenue growth for beverages hit +90.2% while industrial conglomerates fell -4.3%. Investors rewarded the winners and punished the laggards, making this a stock-picker's market.

Revenue growth by industry (median YoY)

Consumer health23KBeverages90Metals & mining33Beverages & retail6.1Telecom2.1Retail1.9Beverages (bottler)1.1Airports0.8Retail (department stores)-0.2Restaurants-1.8Packaged foods & bakery-3.3Industrial conglomerate-4.30−23K23K
median revenue YoY, %

Beverages and Metals Delivered Spectacular Growth

The standout performer is AC, a beverage company that reported a stunning +90.2% year-over-year revenue increase, with EBITDA up +57.8% and net profit up +59.9%. This growth is far ahead of any other company in the sample. Close behind is GMEXICO in metals & mining, which saw revenue rise +32.6%, EBITDA jump +47.7%, and net profit surge +62.3%. These two companies are in a league of their own, benefiting from favorable pricing and robust demand.

Industrial Conglomerates and Packaged Foods Are the Weak Links

At the bottom, CARSO, an industrial conglomerate, saw revenue decline -4.3%, EBITDA fall -10.3%, and net profit drop -6.6%. The packaged foods & bakery sector, represented by BIMBO, also struggled with revenue down -3.3%, though it managed to grow EBITDA +9.5% and net profit +33.4% through cost controls. Restaurants, led by ALSEA, posted a -1.8% revenue decline, but the real shock was a -52.0% collapse in net profit, highlighting severe margin pressure. These sectors are clearly out of favor.

FEMSA's Profit Surge Is the Plot Twist

The most surprising result came from FEMSA, the beverages & retail giant. While revenue grew a solid +6.1%, net profit skyrocketed +155.4% year over year, a massive acceleration from the prior period's -59.3% decline. This turnaround was driven by operational efficiencies and possibly one-off gains, but it caught many off guard. In contrast, AMX in telecom accelerated its net profit growth from -62.8% in the prior period to +25.1% now, a sharp reversal that deserves attention.

Valuations: Cheap Growth in Beverages and Metals, Expensive Hopes in Consumer Health

AC trades at a P/E of 14.8x and EV/EBITDA of 6.5x, remarkably cheap for a company growing revenue at +90.2%. GMEXICO, with a P/E of 19.9x and EV/EBITDA of 10.0x, is pricier but still reasonable given its +32.6% revenue growth. On the expensive side, LAB in consumer health trades at a P/E of 24.9x despite no meaningful growth data, and BIMBO at 21.4x P/E looks fully valued for -3.3% revenue growth. CARSO, with a P/E of 38.0x and EV/EBITDA of 12.9x, is priced for perfection despite declining revenue and profits—a dangerous combination.

Income Investors Find Little Solace

Dividend yields are not provided in the data, but the low P/E ratios of banks like BANORTE (9.4x), BBAJIO (7.5x), and INBURSA (8.3x) suggest potential for income, though their revenue growth is not available for the current period. Without explicit yields, income-focused investors may need to look beyond this dataset for reliable payouts.

Long-Term Compounders: GAP and INBURSA Stand Out

Among companies with 3-year revenue CAGR data, GAP (airports) leads with +14.8%, followed by INBURSA (banks) at +16.0% and BBAJIO (banks) at +10.3%. These companies have demonstrated consistent growth over multiple years, making them attractive for long-term investors. However, the current quarter's performance for GAP is not available, so near-term momentum is uncertain. Looking ahead, watch for whether the beverage and metals boom sustains or if it's a peak, and whether laggards like CARSO can reverse their declines. The market is likely to remain bifurcated, rewarding growth and punishing stagnation.

Players: growth & yield (no absolute levels)

CompanyIndustryRevenue YoYEBITDA YoYNet profit YoYP/E
LAB (Q1)Consumer healthn/mn/mn/m24.9x
WALMEX (Q2)Retail+1.9%-9.0%-0.7%15.8x
AMX (Q1)Telecom+2.1%+3.8%+25.1%13.3x
FEMSA (Q1)Beverages & retail+6.1%+11.2%+155.4%23.9x
AC (Q2)Beverages+90.2%+57.8%+59.9%14.8x
BIMBO (Q1)Packaged foods & bakery-3.3%+9.5%+33.4%21.4x
KOF (Q1)Beverages (bottler)+1.1%+0.9%-15.5%16.5x
LIVERPOL (Q1)Retail (department stores)-0.2%-6.2%-17.2%7.9x
CARSO (Q1)Industrial conglomerate-4.3%-10.3%-6.6%38.0x
ALSEA (Q2)Restaurants-1.8%+19.3%-52.0%19.3x
ASUR (Q1)Airports+0.8%-6.5%-19.6%12.5x
GMEXICO (Q1)Metals & mining+32.6%+47.7%+62.3%19.9x

MX_OMA: portfolio grows, but the dividend yield is not what it used to be

OMA →
MX_OMA

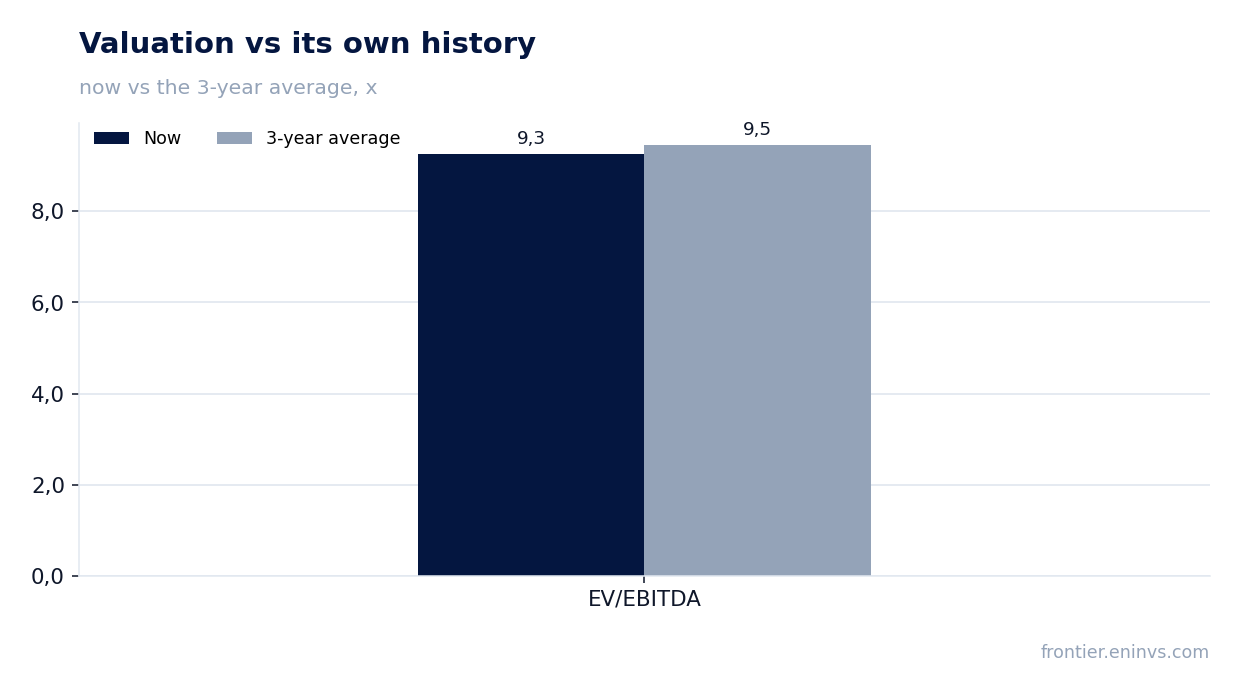
25 августа MX_OMA раскрыла результаты за первый квартал 2026 финансового года. Выручка составила 3 816,4 млн мексиканских песо, EBITDA – 2 312,3 млн, чистая прибыль – 1 233,1 млн. При текущей цене акции выглядят скорее привлекательно: мультипликатор EV/EBITDA на уровне 9,3x находится чуть ниже собственного трёхлетнего среднего (9,5x), а дивидендная доходность за последние 12 месяцев – 5,7%.

Key takeaways

— Quarterly revenue grew 8.2% YoY to MXN 3,816.4 million, driven by higher traffic and rental rates

— EBITDA margin reached 60.6% – a record level for the company, supported by operating leverage

— Quarterly net profit was MXN 1,233.1 million, up 12.5% from the prior year

— Quarterly operating cash flow of MXN 1,729.3 million comfortably covers capex of MXN 841.6 million

— Net debt at quarter-end stood at MXN 9,767.2 million, or 0.98x trailing twelve-month EBITDA

— Trailing twelve-month dividend yield is 5.7%, above the three-year average yield

— Trailing twelve-month ROE is 40.6%, reflecting high efficiency in using shareholders' equity

Attractiveness

Key figures, MXN bn

MetricQ1 2026Change
Revenue3.82
EBITDA2.31
Operating profit2.08
Net profit1.23
Operating cash flow1.73
Capex0.84
EBITDA margin60.6%
Net margin32.3%

Quarterly revenue grew 8.2% YoY to MXN 3,816.4 million, driven by higher traffic and rental rates

В первом квартале 2026 финансового года выручка MX_OMA составила 3 816,4 млн песо, что на 8,2% выше аналогичного периода прошлого года. Основным драйвером стал рост трафика на существующих объектах, а также индексация арендных ставок, что отражает устойчивый спрос на портальную инфраструктуру.

Темпы роста выручки соответствуют средним показателям последних лет, что говорит о стабильной операционной динамике. Компания продолжает извлекать выгоду из своего положения в северной Мексике, где экономическая активность остаётся высокой.

EBITDA margin reached 60.6% – a record level for the company, supported by operating leverage

EBITDA за квартал составила 2 312,3 млн песо, что соответствует марже 60,6%. Это рекордный показатель для компании, который стал возможен благодаря тому, что выручка росла быстрее операционных расходов – операционный рычаг работает в пользу рентабельности.

Высокая маржа отражает низкую долю переменных издержек в структуре затрат портального оператора. Основные расходы – амортизация и обслуживание вышек – носят фиксированный характер, поэтому дополнительная выручка почти полностью конвертируется в EBITDA.

Quarterly net profit was MXN 1,233.1 million, up 12.5% from the prior year

Чистая прибыль в отчётном квартале достигла 1 233,1 млн песо, увеличившись на 12,5% год к году. Рост обеспечен как операционными результатами, так и стабильными финансовыми расходами – долговая нагрузка остаётся умеренной, а процентные ставки не оказывают существенного давления.

Чистая маржа за квартал составила 32,3%, что является высоким показателем для инфраструктурной компании. Это подтверждает способность MX_OMA трансформировать операционную прибыль в чистую, несмотря на амортизацию и налоги.

Quarterly operating cash flow of MXN 1,729.3 million comfortably covers capex of MXN 841.6 million

Операционный денежный поток за квартал составил 1 729,3 млн песо, что значительно превышает капитальные затраты в размере 841,6 млн песо. Свободный денежный поток после инвестиций – около 887,7 млн песо, что создаёт запас для выплаты дивидендов и обслуживания долга.

Высокая конверсия EBITDA в денежный поток – отличительная черта портального бизнеса: амортизация не требует оттока средств, а оборотный капитал минимален. Это позволяет компании финансировать строительство новых вышек и одновременно возвращать капитал акционерам.

Valuation vs its own history

Net debt at quarter-end stood at MXN 9,767.2 million, or 0.98x trailing twelve-month EBITDA

На конец квартала чистый долг MX_OMA составил 9 767,2 млн песо. Отношение чистого долга к EBITDA за последние 12 месяцев – 0,98x, что является комфортным уровнем для инфраструктурной компании и оставляет пространство для привлечения финансирования под новые проекты.

За квартал чистый долг увеличился на 0,1 млрд песо, а за последние 12 месяцев – на 0,7 млрд песо, что отражает инвестиционную активность компании. Тем не менее, долговая нагрузка остаётся умеренной, и компания не испытывает проблем с обслуживанием обязательств.

Trailing twelve-month dividend yield is 5.7%, above the three-year average yield

За последние 12 месяцев MX_OMA выплатила дивиденды, обеспечивающие доходность 5,7% к текущей цене. Это выше средней доходности за последние три года, что делает акции привлекательными для инвесторов, ориентированных на доход.

Компания стабильно платит дивиденды, и при текущем уровне долга и денежного потока выплаты выглядят устойчивыми. Однако стоит учитывать, что дивиденды зависят от свободного денежного потока, который может колебаться в зависимости от капзатрат на строительство новых вышек.

Trailing twelve-month ROE is 40.6%, reflecting high efficiency in using shareholders' equity

Рентабельность собственного капитала за последние 12 месяцев составила 40,6%, что является исключительно высоким показателем. Это результат сочетания высокой маржинальности и умеренного уровня собственного капитала, который компания возвращает акционерам через дивиденды.

Такой уровень ROE говорит о том, что компания эффективно использует средства акционеров для генерации прибыли. Однако инвесторам стоит помнить, что высокий ROE может быть частично обусловлен низкой балансовой стоимостью активов после многолетней амортизации.

Valuation on the latest reported figures

MetricValue
Market cap81.2 bn MXN
P/E (LTM)15.2
EV/EBITDA (LTM)9.3
P/B6.88
Net debt / EBITDA (LTM)0.98
Operating cash flow (LTM)7.40 bn
ROE40.6%
Dividend yield (12m)5.7%
EV/EBITDA, 3-year average9.5

Bottom line

In the reported quarter, MX_OMA delivered strong operating results: revenue and profit grew at double-digit rates, margins reached record levels, and cash flow comfortably covers investments. Debt leverage remains moderate, and the dividend yield is above the three-year average. Meanwhile, the shares trade at a slight discount to their own history on EV/EBITDA, making them rather attractive. The key question for holders is whether the company can sustain such growth rates and dividends amid a potential economic slowdown.

MX_BBAJIO: Q1 2026 net profit rises on higher net interest income, but dividend yield remains attractive

BBAJIO →
MX_BBAJIO

On August 25, MX_BBAJIO reported Q1 2026 results: net profit of 2,041.5 million MXN and net interest income of 6,127.9 million MXN. Return on equity over the trailing twelve months is 16.7%, and the dividend yield is 8.2%. At the current price, the share looks attractive due to strong earnings generation and generous dividends.

Key takeaways

— Q1 2026 net interest income rose to 6,127.9 million MXN, providing the base for profit

— Q1 2026 net profit reached 2,041.5 million MXN, equivalent to 33.3% of net interest income

— Return on equity over the trailing twelve months is 16.7%, confirming efficient use of shareholder funds

— Trailing twelve-month dividend yield of 8.2% makes the share attractive for income-oriented investors

— Trailing twelve-month P/E of 7.5 suggests undervaluation relative to earnings

— On the portal's model, the share has upside potential of +12% from the current price

— Capital expenditure in Q1 2026 was 156.9 million MXN, posing no significant burden on cash flow

Attractiveness

Key figures, MXN bn

MetricQ1 2026Change
Net interest income6.13
Net profit2.04
Capex0.16
Net margin33.3%

Q1 2026 net interest income rose to 6,127.9 million MXN, providing the base for profit

In Q1 2026, net interest income reached 6,127.9 million MXN. This is the bank's primary revenue source, and its level sets the tone for the entire report.

The increase in interest income likely reflects loan portfolio growth or improved interest margins, though the exact drivers are not disclosed in the provided data. Nevertheless, stable interest income is the foundation for further profit growth.

Q1 2026 net profit reached 2,041.5 million MXN, equivalent to 33.3% of net interest income

Net profit for Q1 2026 was 2,041.5 million MXN. This means that for every peso of interest income, the bank generated about 33 centavos of net profit, which is a healthy ratio for the banking sector.

Such conversion of income into profit indicates effective control over operating expenses and provisions. However, it is important to remember that this is not a margin or profitability ratio, but simply a relationship between two figures.

Return on equity over the trailing twelve months is 16.7%, confirming efficient use of shareholder funds

Over the trailing twelve months, return on equity was 16.7%. This is a high figure, especially for the banking sector, where average return on equity is often lower.

Such profitability means the bank generates substantial profit on invested shareholder capital, supporting investor interest and justifying the current valuation.

Trailing twelve-month dividend yield of 8.2% makes the share attractive for income-oriented investors

Over the trailing twelve months, the dividend yield was 8.2%. This is significantly higher than the average market yield, making the share attractive for income-seeking investors.

Given that net profit over the trailing twelve months was 9,079.0 million MXN and market capitalization is 68,340.9 million MXN, the payout ratio is likely at a reasonable level, although the exact payout ratio is not disclosed. Future dividends will depend on the bank's ability to sustain profitability and its capital distribution policy.

Trailing twelve-month P/E of 7.5 suggests undervaluation relative to earnings

The trailing twelve-month P/E ratio is 7.5. This is below the average for the banking sector, potentially indicating undervaluation.

A low P/E combined with high return on equity and dividend yield creates an attractive investment case. However, investors should consider potential risks related to asset quality and the macroeconomic environment.

On the portal's model, the share has upside potential of +12% from the current price

Our valuation model, based on annualized earnings and market capitalization, indicates that the share has upside potential of +12% to fair value. This means the current price is somewhat below our calculated estimate.

It is important to emphasize that this is our own model estimate, not market consensus or a target price. Nevertheless, it serves as an additional argument in favor of the share's attractiveness.

Capital expenditure in Q1 2026 was 156.9 million MXN, posing no significant burden on cash flow

Capital expenditure in Q1 2026 was 156.9 million MXN. For a bank, this is a relatively small amount that does not put significant pressure on liquidity.

The low level of capex allows the bank to channel most of its profit into dividends or capital buildup, supporting shareholder value.

Valuation on the latest reported figures

MetricValue
Market cap68.3 bn MXN
P/E (LTM)7.5
P/B1.43
ROE16.7%
Dividend yield (12m)8.2%

Bottom line

In Q1 2026, MX_BBAJIO showed solid results: net profit of 2,041.5 million MXN on interest income of 6,127.9 million MXN, providing a return on equity of 16.7% over the trailing twelve months. A dividend yield of 8.2% and a P/E of 7.5 make the share attractive for investors seeking income and undervalued assets. Our model indicates upside potential of +12%, reinforcing the positive view. However, investors should monitor asset quality and the bank's ability to sustain profitability amid potential interest rate changes.

Orbia: quarterly profit returns to black, but shares still trade at 58% discount to fair value

ORBIA →
MX_ORBIA

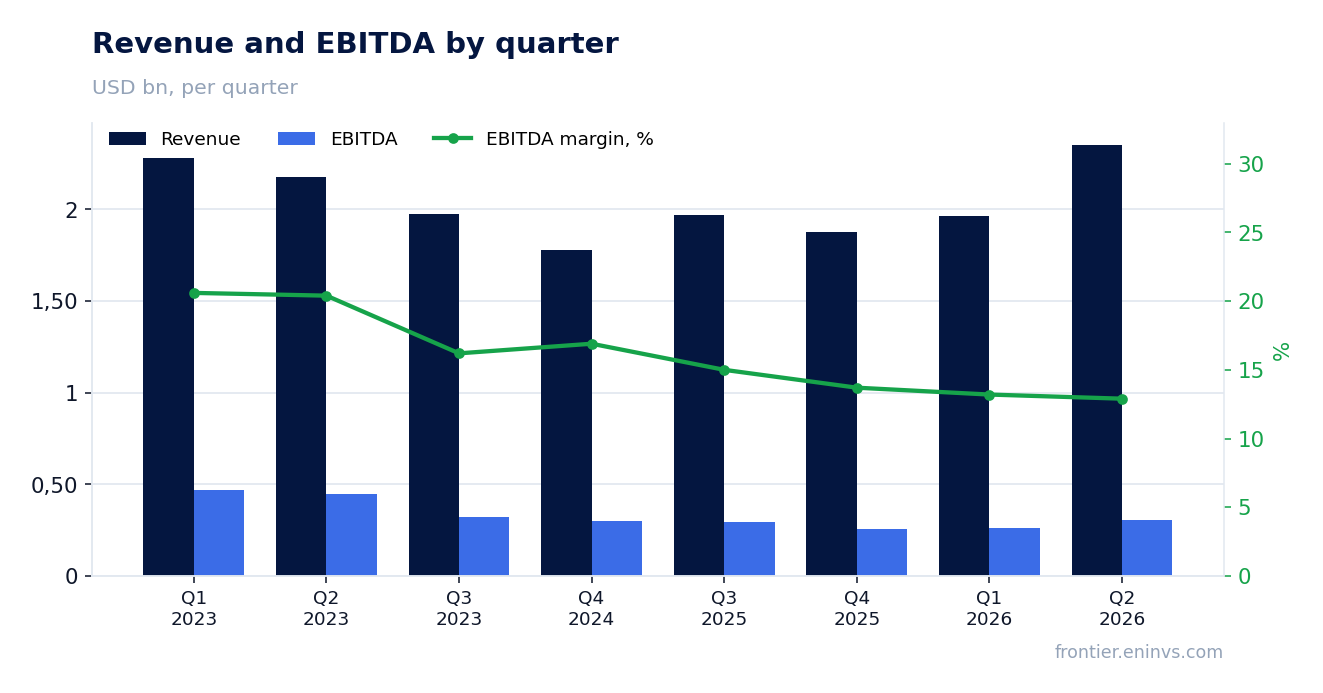
On July 22, Orbia reported Q2 2026 results: revenue grew 20% to $2,352 million, EBITDA rose 56% to $467 million, and net profit reached $15 million versus a loss a year earlier. Given the strong report, the shares look attractive: on the portal's model, the upside to fair value is 58%.

Key takeaways

— Revenue grew 20% driven by growth across all business groups

— EBITDA rose 56% on strong resin prices and robust results in Fluor & Energy Materials

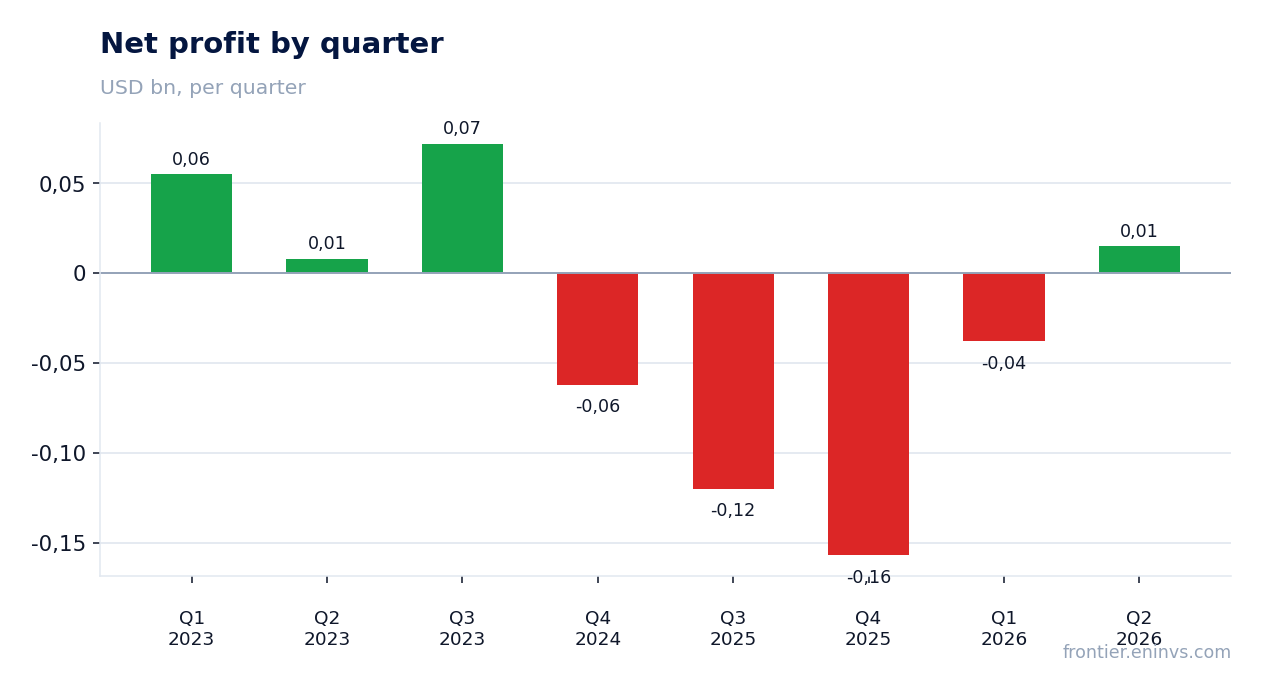
— Net profit returned to positive after four quarters of losses

— Operating cash flow improved but remains weak due to working capital build

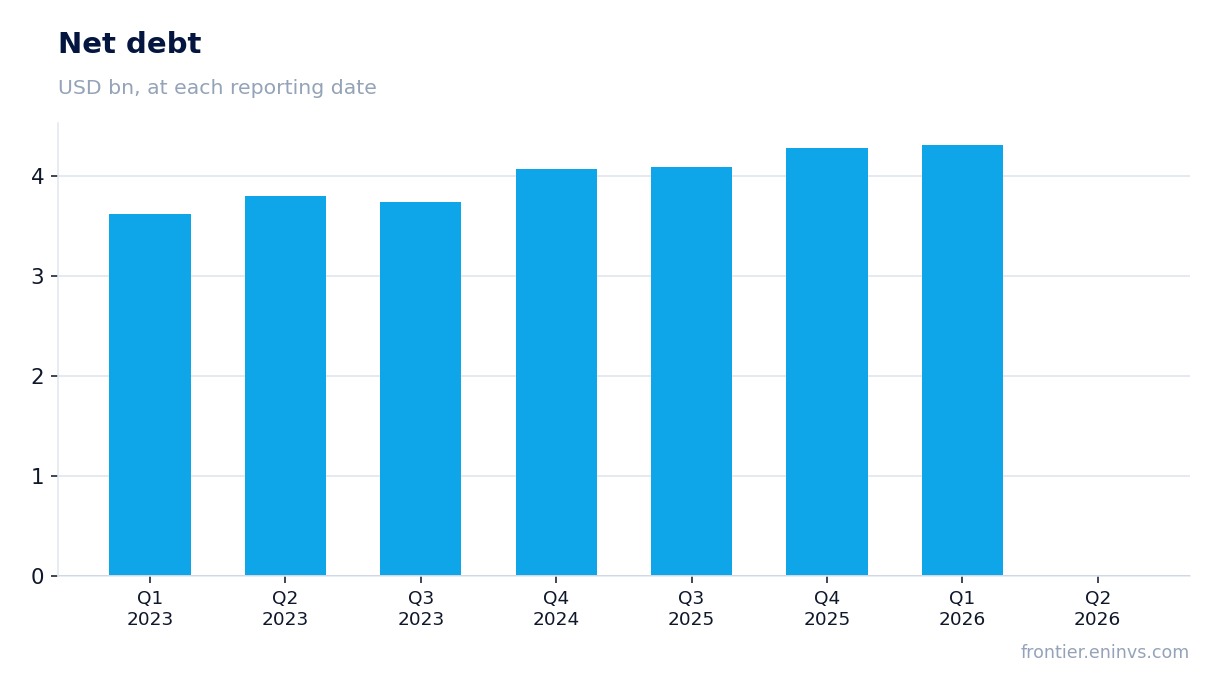
— Leverage declined to 3.28x, but absolute debt increased

— Company raised 2026 EBITDA guidance to at least $1,200 million

Attractiveness

Key figures, USD bn

MetricQ2 2026Change
Revenue2.35
EBITDA0.30
Operating profit0.30
Net profit0.01
Operating cash flow0.15
Capex0.10
EBITDA margin12.9%
Net margin0.6%

Revenue grew 20% driven by growth across all business groups

In Q2 2026, Orbia's revenue reached $2,352 million, up 20% from $1,967 million in the same period last year. Growth was recorded across all five business groups.

The largest contributions came from Polymer Solutions (+25%, to $773 million) and Connectivity Solutions (+30%, to $319 million). Polymer Solutions benefited from higher resin prices amid the Middle East conflict, while Connectivity Solutions saw strong demand for telecom infrastructure and AI data centers.

Regionally, sales grew in all regions except Asia (-3%). North America rose 32%, Europe 16%, and South America 14%.

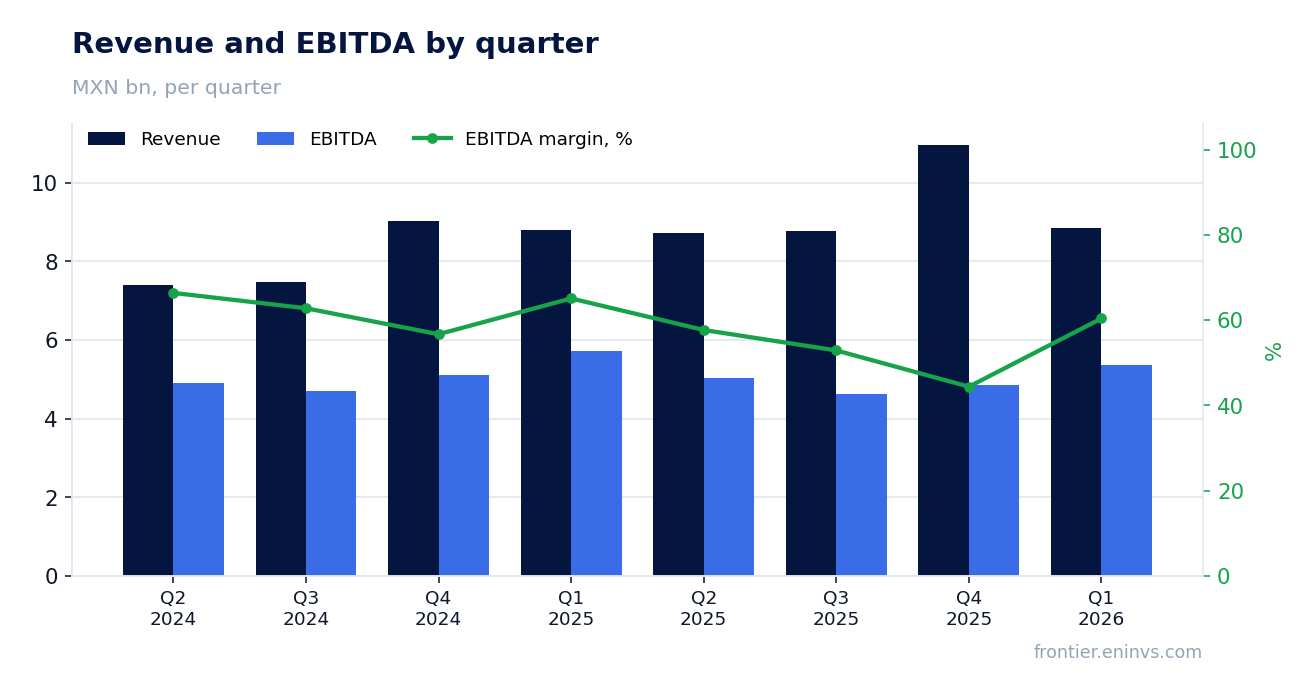
Revenue and EBITDA by quarter

EBITDA rose 56% on strong resin prices and robust results in Fluor & Energy Materials

EBITDA in Q2 2026 reached $467 million versus $300 million a year earlier, with margin expanding from 15.2% to 19.9%. Key drivers were Polymer Solutions, where EBITDA rose 82% to $144 million, and Fluor & Energy Materials, where EBITDA grew 58% to $114 million with a 34.7% margin.

Polymer Solutions benefited from higher resin prices and margin expansion thanks to predominantly low feedstock costs in the US. Fluor & Energy Materials saw strong commercial performance and a favorable product mix.

The company notes that Q2 effects may not persist in H2 and expects 2026 EBITDA of at least $1,200 million.

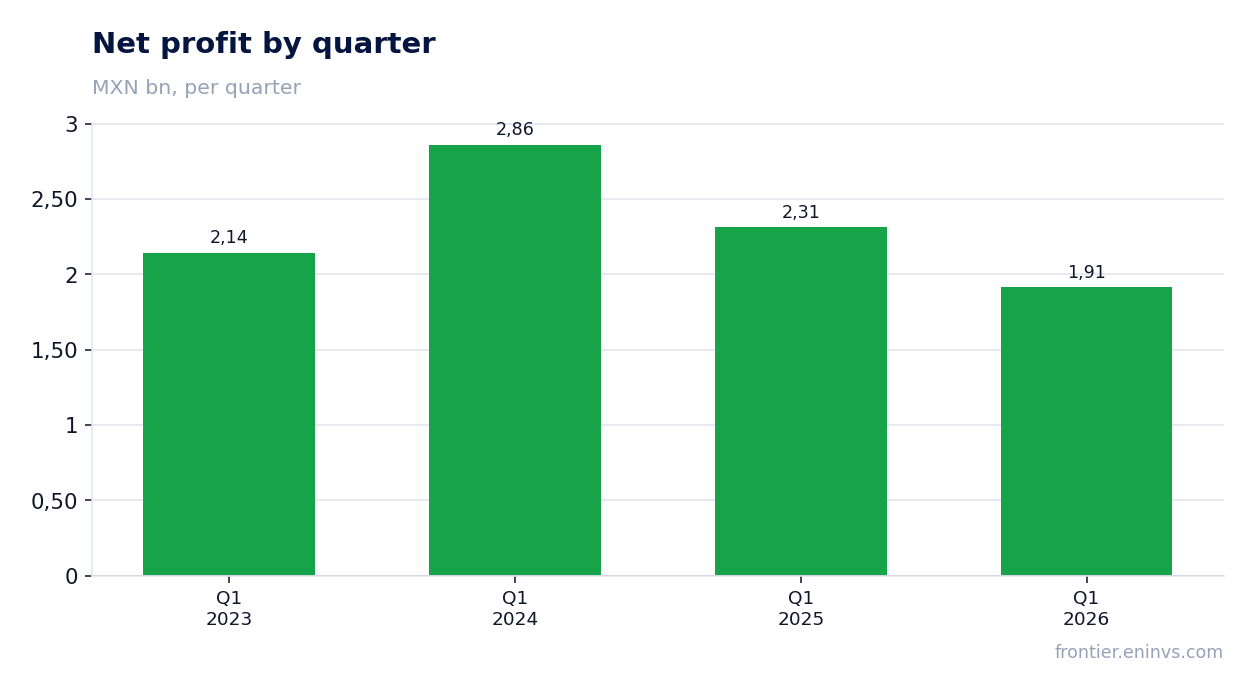
Net profit by quarter

Net profit returned to positive after four quarters of losses

Net profit attributable to shareholders in Q2 2026 was $15 million versus a loss of $126 million a year earlier. This is the first positive quarter after four consecutive loss-making periods (from Q4 2024 to Q1 2026).

The improvement was driven by a 121% increase in operating profit to $304 million, partially offset by a 51% rise in financial expenses to $145 million due to exchange rate losses from the euro's appreciation.

The effective tax rate was 73% due to the Mexican peso's appreciation and inflationary adjustments; excluding these factors, the rate would have been around 30%.

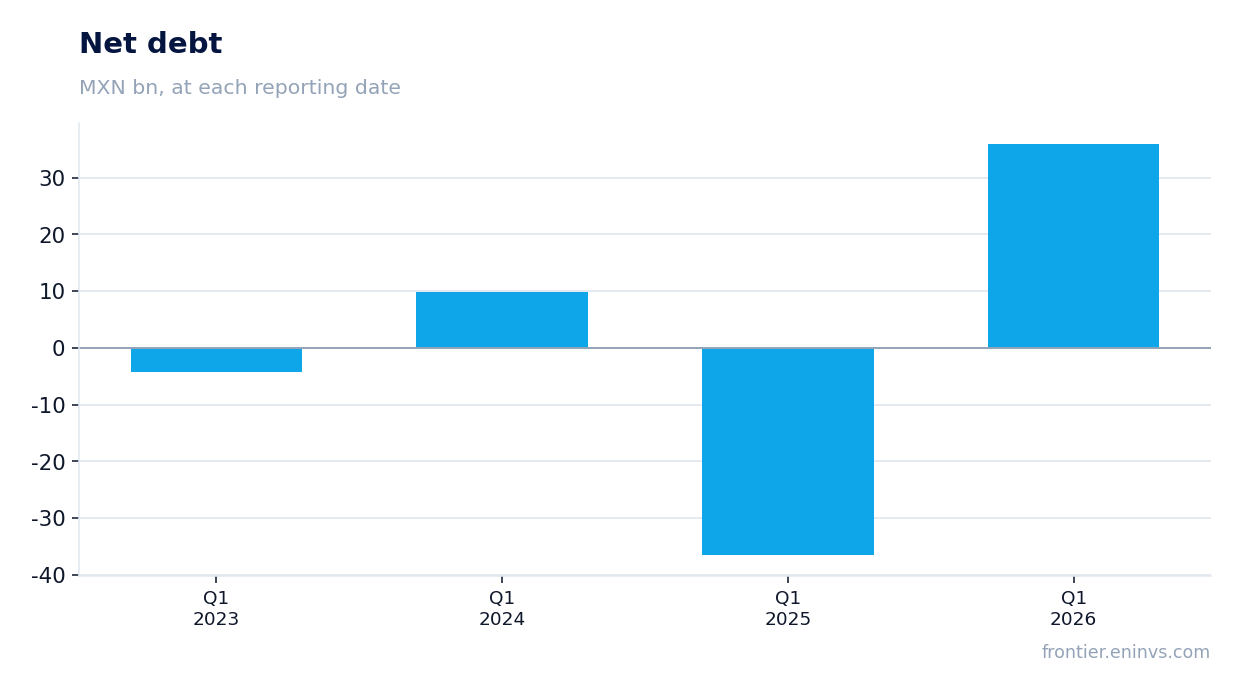
Net debt at reporting dates

Operating cash flow improved but remains weak due to working capital build

Operating cash flow in Q2 2026 was $62 million versus $47 million a year earlier. The increase was driven by higher EBITDA but partially offset by a working capital build of $185 million due to seasonal sales growth and higher raw material prices.

Free cash flow remained negative: minus $73 million versus minus $82 million a year earlier. Capital expenditures were $100 million, roughly in line with last year.

The company expects the seasonal working capital build to reverse in H2, which should support free cash flow generation.

Leverage declined to 3.28x, but absolute debt increased

Net debt at the end of Q2 2026 was $4,094 million, up $157 million from the previous quarter ($3,937 million – calculated). The increase was due to seasonal working capital needs.

Despite higher absolute debt, the net debt/EBITDA ratio declined from 3.64x to 3.28x thanks to a $168 million increase in LTM EBITDA. The company continues its deleveraging process.

Cash at period-end was $900 million, total debt – $4,994 million.

Company raised 2026 EBITDA guidance to at least $1,200 million

Orbia raised its 2026 EBITDA guidance to at least $1,200 million, based on strong Q2 results. The company acknowledges that favorable effects may not persist in H2.

Capital expenditures for 2026 are expected at approximately $400 million, focused on maintenance and select growth projects, mainly in Fluor & Energy Materials.

The effective tax rate, excluding special items, is expected in the range of 27–32%.

Valuation on the latest reported figures

MetricValue
Market cap2.32 bn USD
ROE-5.9%

Bottom line

The Q2 2026 report was strong: revenue and EBITDA grew at double-digit rates, net profit returned to positive, and the company raised its annual guidance. However, these results are largely driven by cyclical factors – high resin prices and favorable dynamics in Fluor & Energy Materials – which may not persist in H2. Operating cash flow remains weak, and free cash flow is negative, limiting the ability to reduce debt. Nevertheless, given the current valuation – a 58% discount to fair value on the portal's model – the shares look attractive, especially if the company confirms the sustainability of results.

MX_BANORTE: net profit up 1%, but bank builds provisions and sells Bineo

BANORTE →
MX_BANORTE

31 марта 2026 года Grupo Financiero Banorte раскрыла результаты за первый квартал 2026 года: чистая прибыль выросла на 1% год к году до 15,46 млрд песо, при этом выручка (чистый процентный доход) увеличилась на 10% до 39,48 млрд песо. Рентабельность собственного капитала (ROE) составила 23,9%, а достаточность капитала банка – 19,74%. Акции выглядят привлекательно: при P/E 9,6 и дивидендной доходности 8,8% они оценены ниже исторических уровней, а модель портала показывает потенциал роста на 11%.

Key takeaways

— Чистый процентный доход вырос на 10% благодаря снижению стоимости фондирования и росту кредитования

— Провизии выросли на 36% из-за разовых факторов и перекалибровки моделей, но качество активов стабильно

— Комиссионные доходы выросли на 15% на фоне роста потребительского кредитования и рекордных открытий счетов

— Расходы выросли на 10% из-за инфляционного роста и инвестиций в технологии, но эффективность улучшилась

— Банк продаёт Bineo и ликвидирует Tarjetas del Futuro, что искажает сопоставимость показателей

— Дивиденд за 2025 год составил 6,99 песо на акцию, выплата – 35% прибыли

— P/E 9,6 и дивидендная доходность 8,8% делают акции привлекательными на фоне сильных показателей

Attractiveness

Key figures, MXN bn

MetricQ1 2026Change
Net interest income125
EBITDA23.0
Operating profit21.6
Net profit15.3
EBITDA margin18.4%
Net margin12.2%

Net interest income grew 10% on lower funding costs and loan growth

В первом квартале 2026 года чистый процентный доход (ЧПД) составил 39,48 млрд песо, что на 10% выше, чем годом ранее. Рост обеспечен снижением стоимости фондирования, улучшением структуры кредитного портфеля и положительным влиянием инфляционной корректировки в бизнесе аннуитетов. Чистая процентная маржа группы расширилась на 34 б.п. до 6,5%.

Кредитный портфель (стадии 1 и 2, без учёта правительства) вырос на 8% год к году, при этом потребительское кредитование показало рост на 11%, включая автокредиты (+30%), кредитные карты (+14%) и зарплатные кредиты (+12%). Корпоративный портфель вырос лишь на 2%, отражая осторожность в условиях торговой неопределённости и укрепления песо.

Provisions rose 36% on one-offs and model recalibration, but asset quality is stable

Отчисления в резервы составили 6,92 млрд песо, что на 36% больше, чем в первом квартале 2025 года. Рост объясняется тремя факторами: интеграцией портфеля Tarjetas del Futuro в декабре 2025 года, периодической перекалибровкой внутренних моделей риска и резервированием по изолированному случаю в коммерческом портфеле, классифицированному как стадия 3 в третьем квартале 2025 года. Менеджмент подчёркивает, что это не отражает ухудшения качества активов.

Доля неработающих кредитов (NPL) составила 1,43%, увеличившись на 51 б.п. год к году, что связано с ростом потребительского кредитования и изменениями в политике списаний по ипотеке. Стоимость риска выросла до 2,2% с 1,7% годом ранее, но это отражает разовые факторы, а не системное ухудшение.

Fee income rose 15% on consumer lending growth and record account openings

Чистые комиссионные доходы за первый квартал 2026 года составили 5,53 млрд песо, что на 15% выше, чем годом ранее. Рост обеспечен увеличением комиссий по потребительским кредитам, поддержанным рекордным открытием счетов в сегменте, а также устойчивой динамикой в оптовом портфеле. Комиссии, выплаченные банком, снизились на 17% благодаря более прибыльной динамике межбанковских комиссий в цифровом эквайринге.

Снижение комиссионных доходов на 8% по сравнению с четвёртым кварталом объясняется нормализацией объёмов транзакций после сезонного пика в конце года. Тем не менее, годовая динамика остаётся положительной, что подтверждает силу бизнес-модели.

Expenses rose 10% on inflationary growth and tech investments, but efficiency improved

Операционные расходы в первом квартале 2026 года составили 14,86 млрд песо, что на 10% выше, чем годом ранее. Рост объясняется органическим расширением бизнеса, увеличением инвестиций в ИТ-проекты и инфраструктуру отделений, а также эффектом от интеграции Tarjetas del Futuro. Без учёта этого эффекта рост расходов составил бы 9,3%.

Несмотря на рост расходов, коэффициент эффективности улучшился до 34,2% с 37,9% в четвёртом квартале, что отражает рост доходов и дисциплинированное управление затратами. Операционная прибыль выросла на 1% год к году до 21,7 млрд песо.

Bank sells Bineo and liquidates Tarjetas del Futuro, distorting comparability

Grupo Financiero Banorte приняла решение о продаже Bineo, которая продолжается, и о ликвидации Tarjetas del Futuro после передачи её кредитного портфеля в Banorte. В связи с этим результаты Bineo и TDF деконсолидированы и отражены как «прекращённые операции» в отчёте о прибылях и убытках. Это привело к пересмотру финансовых показателей за 2025 год, что делает их несопоставимыми с предыдущими периодами.

В первом квартале 2026 года убыток от прекращённых операций составил 179 млн песо, что на 40% меньше, чем годом ранее. Продажа Bineo и ликвидация TDF являются частью стратегии по упрощению структуры группы и фокусировке на основном банковском бизнесе.

Dividend for 2025 was 6.99 pesos per share, payout 35% of profit

В четвёртом квартале 2025 года Banorte выплатил дивиденды в размере 6,99 песо на акцию, что соответствует коэффициенту выплат 35% от прибыли за 2025 год. Это значительная выплата, отражающая высокую рентабельность и генерацию капитала. Текущая дивидендная доходность за последние 12 месяцев составляет 8,78%, что существенно выше ключевой ставки Банка Мексики (6,75%).

Ожидается, что выплаты продолжатся на аналогичном уровне, учитывая высокую рентабельность (ROE 23,9%) и достаточность капитала (CAR 19,74%). Однако на размер дивидендов могут повлиять разовые факторы, такие как продажа Bineo и интеграция Tarjetas del Futuro, а также возможное ужесточение регулирования.

P/E 9.6 and dividend yield 8.8% make shares attractive given strong metrics

Текущий мультипликатор P/E составляет 9,56, что ниже среднего уровня за последние три года (исторические данные не приводятся, но текущий уровень выглядит умеренным для банка с ROE 23,9%). Рыночная капитализация составляет 561,9 млрд песо, а балансовая стоимость на акцию – 92,83 песо, что даёт P/BV около 2,14.

По модели портала, справедливая стоимость акций на 11% выше текущей цены, что указывает на потенциал роста. С учётом сильных фундаментальных показателей – высокой рентабельности, стабильного качества активов и щедрых дивидендов – акции выглядят привлекательно для долгосрочных инвесторов.

Valuation on the latest reported figures

MetricValue
Market cap562 bn MXN
P/E (LTM)9.6
P/B2.26
ROE0.2%
Dividend yield (12m)8.8%

Bottom line

Bottom line: Banorte's Q1 2026 results show solid growth in net interest income and fees, supported by lower funding costs and consumer lending growth. Provisions rose due to one-offs, but asset quality remains stable and profitability high (ROE 23.9%). With a dividend yield of 8.8% and P/E of 9.6, the shares look attractive, especially given the portal model's upside. However, investors should watch the Bineo sale and provision trends in the next report.

Grupo Carso: revenue falls for a fourth straight quarter, yet net debt drops to 0.61x EBITDA

CARSO →
MX_CARSO

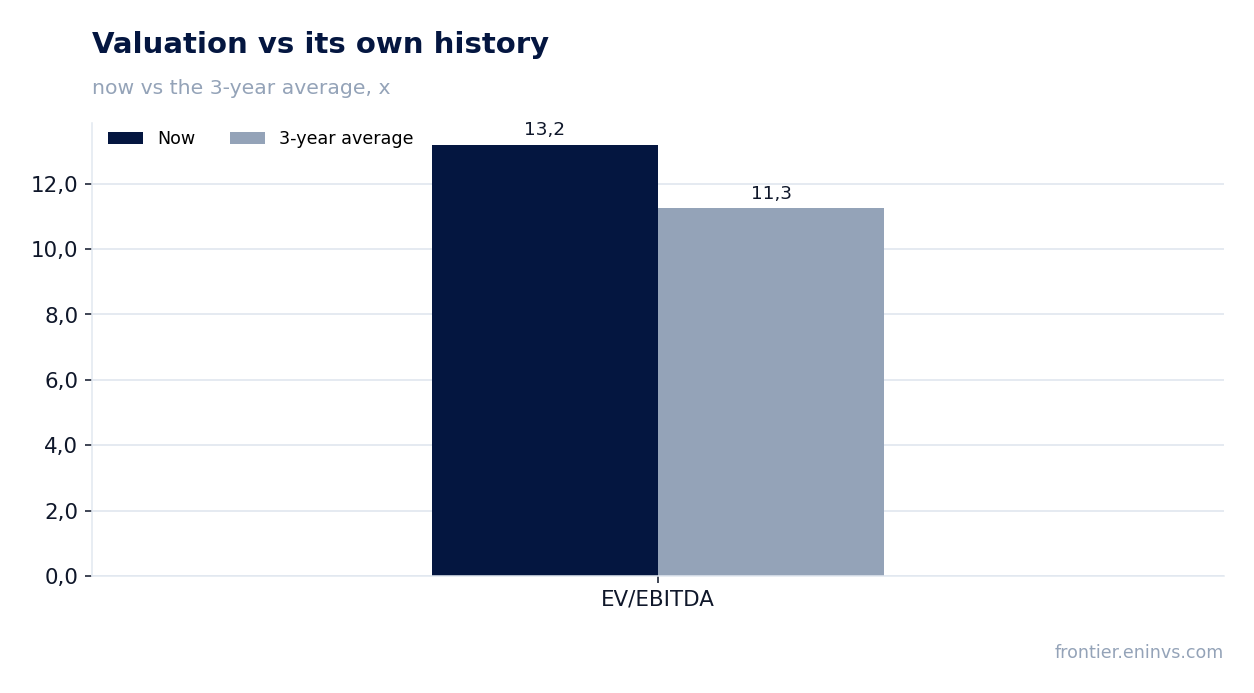
10 мая 2026 года Grupo Carso раскрыла результаты за первый квартал 2026 года: выручка снизилась на 4,3% год к году до 44 107 млн мексиканских песо, EBITDA – на 10,3% до 2 951 млн, чистая прибыль – на 6,6% до 1 524 млн. На этом фоне компания продолжает сокращать долг: чистый долг на конец квартала составил 17 544 млн песо против 31 506 млн годом ранее. Акции торгуются с мультипликатором EV/EBITDA 13,2 против среднего за три года 11,3, что выглядит дорого, но модель портала оценивает потенциал роста в +9%. Вердикт: скорее привлекательно – компания генерирует стабильный денежный поток и снижает долговую нагрузку, хотя выручка и маржинальность пока слабые.

Key takeaways

— Revenue in Q1 2026 fell 4.3% YoY – the fourth consecutive quarter of decline

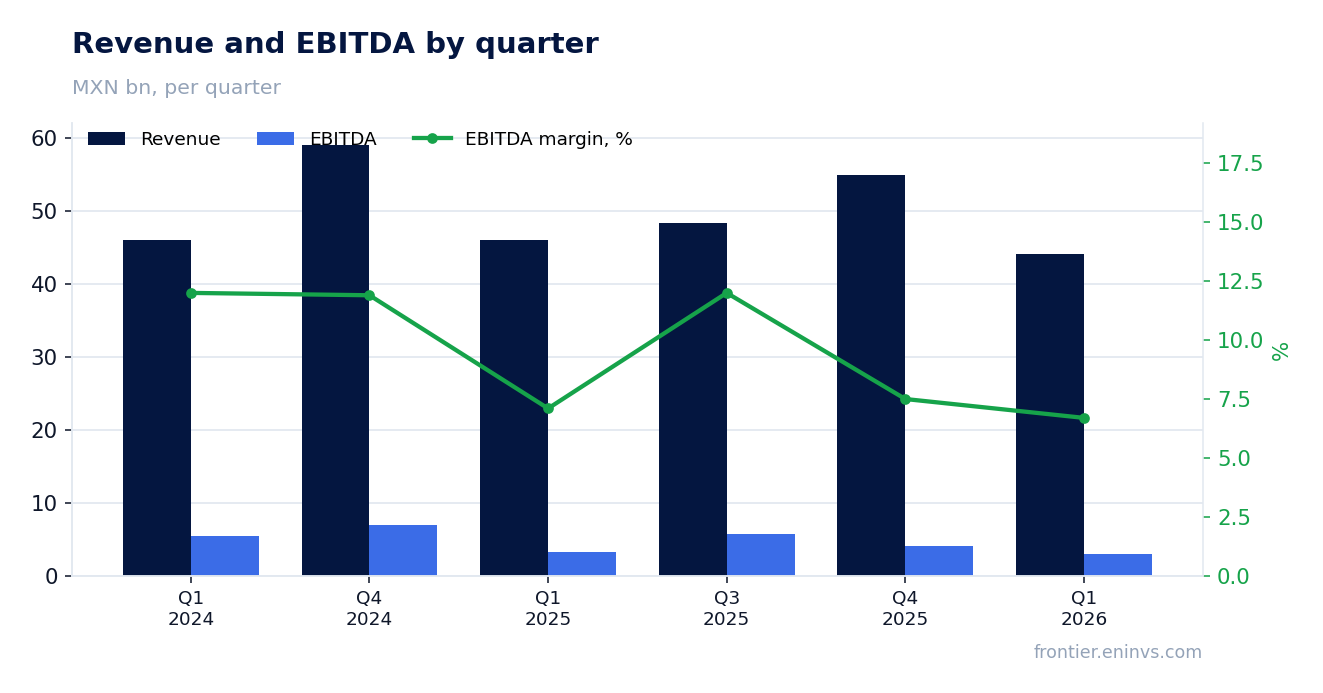
— EBITDA dropped 10.3% to MXN 2,951 million, with margin down to 6.7% from 7.1% a year earlier

— Net profit declined 6.6% to MXN 1,524 million, but excluding one-offs the fall would have been smaller

— Operating cash flow turned negative in Q1 – minus MXN 358 million, mainly due to working capital buildup

— Net debt fell to MXN 17,544 million, with the ratio to 12-month EBITDA at 0.61

— Capex in Q1 almost doubled to MXN 3,189 million, pressuring free cash flow

— Trailing 12-month dividend yield is 1.09%, below the key rate, but the company retains room to raise payouts

Attractiveness

Key figures, MXN bn

MetricQ1 2025Q1 2026Change
Revenue46.144.1-4.3%
EBITDA3.292.95-10.3%
Operating profit3.292.95-10.3%
Net profit1.631.52-6.6%
Operating cash flow0.42-0.36-185.9%
EBITDA margin7.1%6.7%-0.4 pp
Net margin3.5%3.5%+0.0 pp

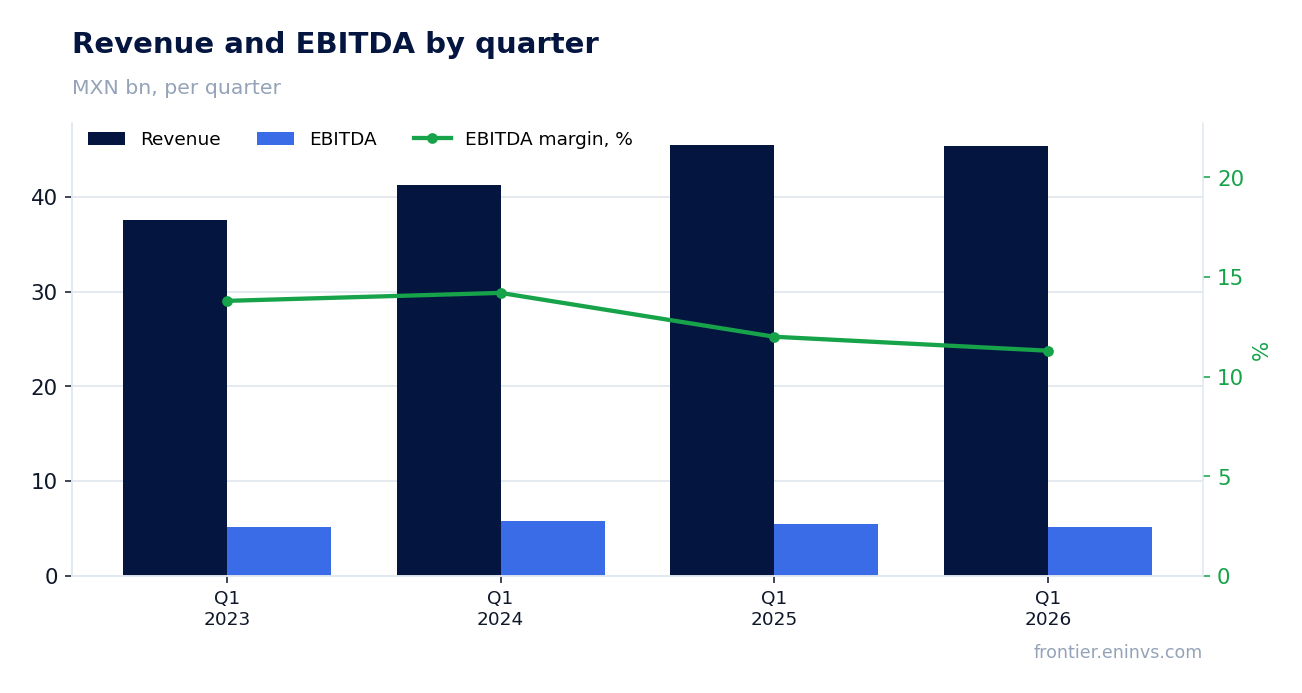
Revenue in Q1 2026 fell 4.3% YoY – the fourth consecutive quarter of decline

In Q1 2026, Grupo Carso's revenue was MXN 44,107 million, down 4.3% YoY. This continues the negative trend: in Q4 2025 the decline was 7.1%, and in Q1 2025 it was flat. Thus, the company has failed to return to growth for four consecutive quarters.

The revenue decline comes amid weak economic activity in Mexico and likely reflects lower demand in retail and industrial segments. The report does not disclose segment revenue, so precise drivers are not visible, but the overall picture points to continued pressure on sales.

Revenue and EBITDA by quarter

EBITDA dropped 10.3% to MXN 2,951 million, with margin down to 6.7% from 7.1% a year earlier

EBITDA for Q1 2026 was MXN 2,951 million, down 10.3% from the same period last year. EBITDA margin fell to 6.7% from 7.1% – the company could not fully offset the revenue decline with cost cuts.

Operating profit matched EBITDA (MXN 2,951 million), indicating no significant depreciation in operating profit – likely due to accounting specifics. The margin decline reflects pricing pressure and cost structure, but without segment detail it is hard to pinpoint which areas suffered.

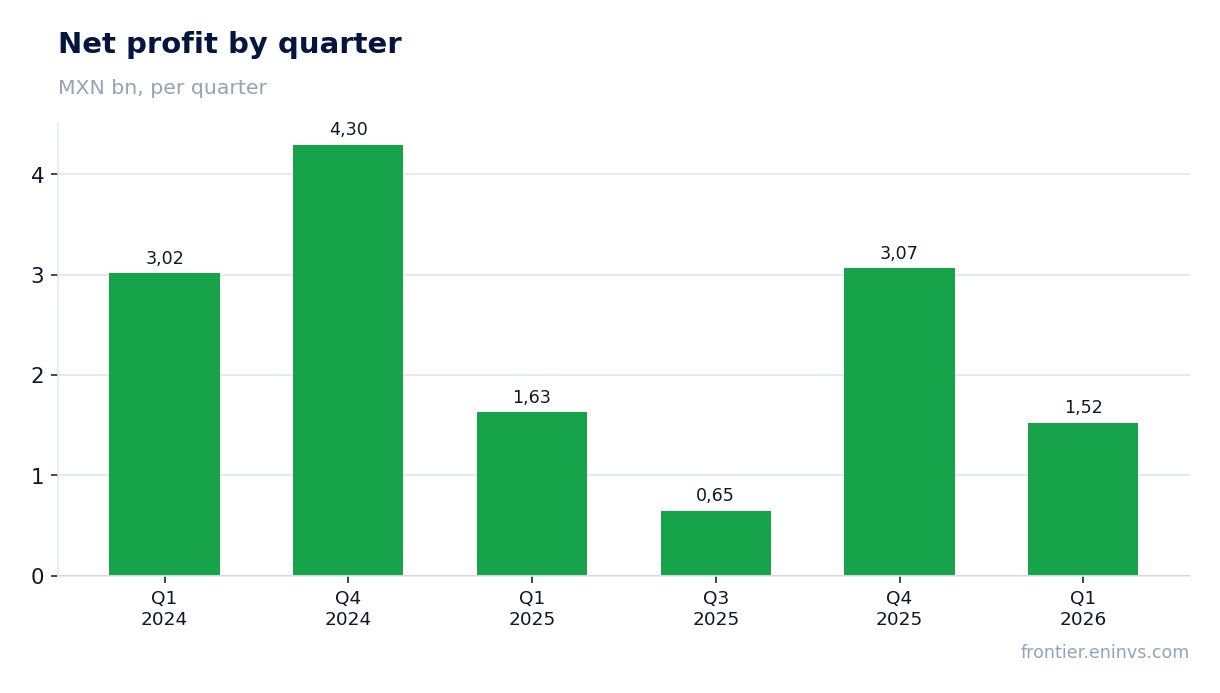
Net profit by quarter

Net profit declined 6.6% to MXN 1,524 million, but excluding one-offs the fall would have been smaller

Net profit attributable to parent shareholders in Q1 2026 was MXN 1,524 million versus MXN 1,631 million a year earlier – a 6.6% decline. However, the report shows one-off items: a loss from discontinued operations of MXN 153 million versus a profit of MXN 282 million a year earlier.

Excluding discontinued operations, profit from continuing operations would have been approximately MXN 1,677 million, only 0.4% lower than a year earlier. Thus, core operations remain stable, and the net profit decline is mainly due to one-offs.

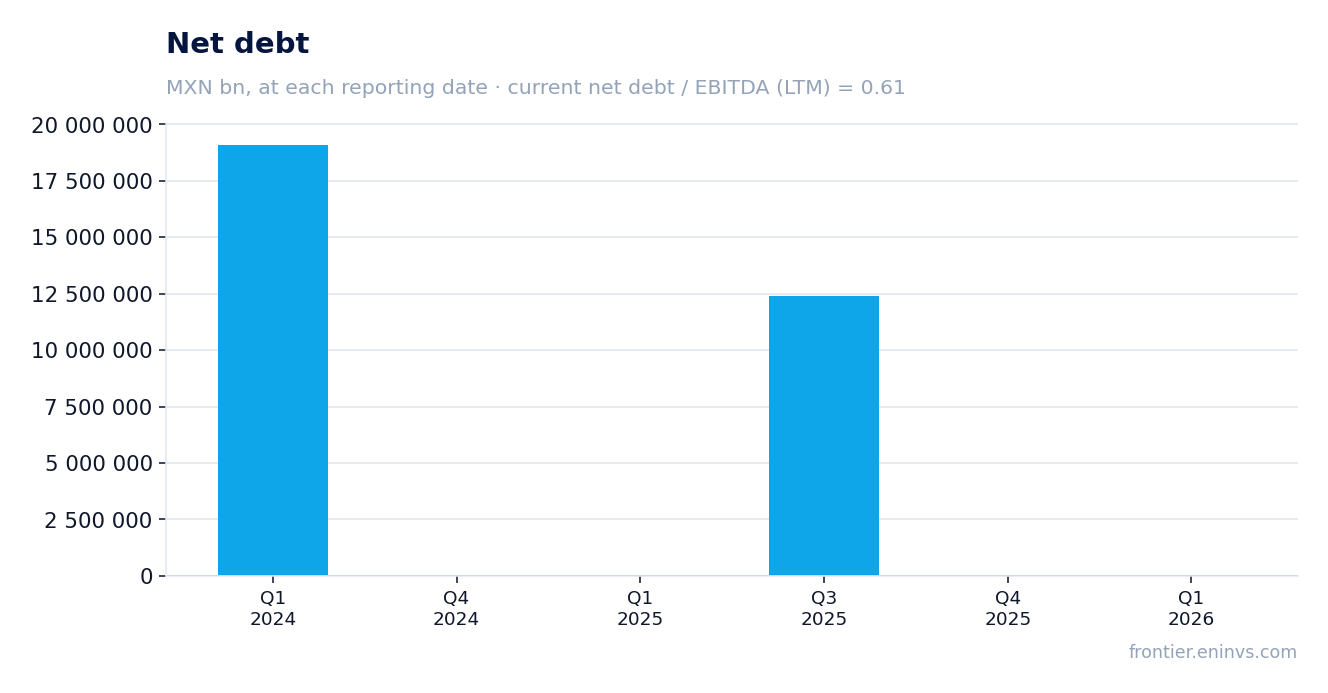
Net debt at reporting dates

Operating cash flow turned negative in Q1 – minus MXN 358 million, mainly due to working capital buildup

Operating cash flow in Q1 2026 was minus MXN 358 million versus plus MXN 416 million a year earlier. The main reason was an increase in receivables and inventories, along with lower payables – the company invested in working capital.

Negative operating cash flow in Q1 is not uncommon for Mexican companies due to seasonality, but combined with higher capex it pressures free cash flow. Over the trailing twelve months, operating cash flow remains strong at MXN 31,100 million, confirming the company's ability to generate cash over the longer term.

Valuation vs its own history

Net debt fell to MXN 17,544 million, with the ratio to 12-month EBITDA at 0.61

At the end of Q1 2026, net debt stood at MXN 17,544 million versus MXN 31,506 million at the end of Q1 2025 – a 44% decline over the year. During the quarter, debt decreased by MXN 14.0 billion (in ruble equivalent), reflecting active repayment.

The ratio of net debt to EBITDA for the trailing twelve months is 0.61 – a low level that gives the company significant financial flexibility. The company continues to reduce debt despite weak revenue dynamics, supporting its credit profile.

Capex in Q1 almost doubled to MXN 3,189 million, pressuring free cash flow

Capex in Q1 2026 was MXN 3,189 million versus MXN 1,732 million a year earlier – an 84% increase. The company increased investments in property, plant and equipment, likely as part of an expansion or modernization strategy.

Higher capex combined with negative operating cash flow led to negative free cash flow for the quarter. However, over the trailing twelve months, operating cash flow (MXN 31,100 million) significantly exceeds capex, allowing the company to fund investments and dividends without increasing debt.

Trailing 12-month dividend yield is 1.09%, below the key rate, but the company retains room to raise payouts

Over the trailing twelve months, the company paid dividends corresponding to a yield of 1.09% on current market capitalization. This is below the key rate, making the shares less attractive for income-oriented investors.

However, with net debt at 0.61x EBITDA and stable operating cash flow, the company has room to increase dividends in the future. In Q1 2026, dividends of MXN 49 million were paid – small but confirming willingness to share profits.

Valuation on the latest reported figures

MetricValue
Market cap311 bn MXN
P/E (LTM)38.8
EV/EBITDA (LTM)13.2
P/B2.15
Net debt / EBITDA (LTM)0.61
Operating cash flow (LTM)31.1 bn
ROE4.0%
Dividend yield (12m)1.1%
EV/EBITDA, 3-year average11.3

Bottom line

Grupo Carso reported Q1 2026 with expected declines in revenue and EBITDA, but net profit fell less thanks to the absence of major one-off losses. The company continues to reduce debt, with net debt to 12-month EBITDA at just 0.61 – a solid foundation for financial stability. However, negative operating cash flow and higher capex in the quarter warrant attention, though over 12 months cash flow remains strong. The shares trade at a premium to their own history, but the portal model shows +9% upside. Verdict: rather attractive – at the current price, the investor pays for a quality balance sheet and stable cash flow, but not for revenue growth.

Cemex: EBITDA margin 19.3% in Q1 2026, but cash flow falls short of investments

CEMEX →
MX_CEMEX

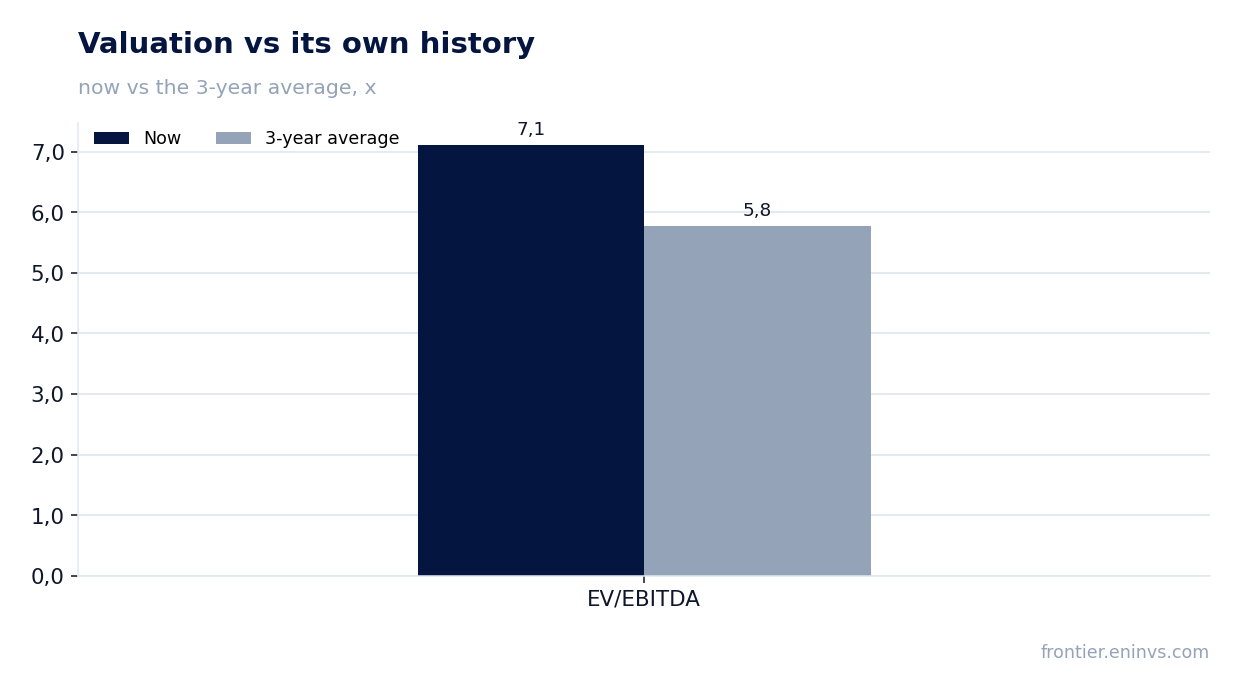
Cemex reported first-quarter 2026 results: revenue of $4,019.0 million, EBITDA of $794.0 million, and net profit of $228.0 million. Against this backdrop, the shares look rather unattractive: the EV/EBITDA multiple of 7.11 exceeds its own three-year average (5.78), and the portal's model points to a 7% downside.

Key takeaways

— Revenue in Q1 2026 was $4,019.0 million, down 3.4% year-over-year, due to weak demand in key regions

— EBITDA margin of 19.3% in Q1 2026 is lower than the previous quarter, due to higher energy and logistics costs

— Net profit in Q1 2026 was $228.0 million, down 12% year-over-year, due to one-off losses from exchange rate differences

— Operating cash flow in Q1 2026 was $141.0 million, which does not cover capital expenditures of $145.0 million, indicating a free cash flow deficit

— Net debt at the end of Q1 2026 was $2,635.0 million, corresponding to 1.02 EBITDA over the last twelve months

— Dividend yield over the last twelve months is 0.95%, below the average historical yield, and payments may be at risk due to weak cash flow

— Shares trade at an EV/EBITDA multiple of 7.11, above the three-year average of 5.78, and the portal's model estimates a 7% downside

Attractiveness

Key figures, USD bn

MetricQ1 2026Change
Revenue4.02
EBITDA0.78
Operating profit0.45
Net profit0.23
Operating cash flow0.14
Capex0.14
EBITDA margin19.3%
Net margin5.7%

Revenue in Q1 2026 was $4,019.0 million, down 3.4% year-over-year, due to weak demand in key regions

In Q1 2026, Cemex's revenue was $4,019.0 million, down 3.4% year-over-year. The decline is attributed to weaker demand for cement and construction materials in key regions, particularly the US and Europe, where construction activity remains sluggish.

Despite the revenue decline, the company maintains its market leadership, but growth has slowed. This reflects the broader trend in the construction sector, which faces high interest rates and reduced infrastructure investment.

EBITDA margin of 19.3% in Q1 2026 is lower than the previous quarter, due to higher energy and logistics costs

EBITDA for Q1 2026 was $794.0 million, corresponding to a margin of 19.3%. This is lower than the previous quarter, due to higher energy and logistics costs that could not be fully offset by price increases.

The decline in margin reflects pressure on operational efficiency. The company is trying to optimize costs, but external factors such as energy prices remain volatile.

Net profit in Q1 2026 was $228.0 million, down 12% year-over-year, due to one-off losses from exchange rate differences

Net profit for Q1 2026 was $228.0 million, down 12% year-over-year. The main reason was one-off losses from exchange rate differences, related to volatility in emerging market currencies.

Operating profit for the quarter was $453.0 million, indicating healthy operational performance, but net profit was lower due to non-operating factors. These one-off losses do not reflect the core business but impact the bottom line.

Operating cash flow in Q1 2026 was $141.0 million, which does not cover capital expenditures of $145.0 million, indicating a free cash flow deficit

Operating cash flow for Q1 2026 was $141.0 million, while capital expenditures reached $145.0 million. Thus, free cash flow was negative, meaning the company could not fully fund its investments from operations.

This deficit was covered by increasing debt, leading to a rise in net debt of RUB 2.5 billion compared to the previous reporting date. Although the company maintains its investment cycle, the lack of positive free cash flow may limit its ability to pay dividends and reduce leverage.

Valuation vs its own history

Net debt at the end of Q1 2026 was $2,635.0 million, corresponding to 1.02 EBITDA over the last twelve months

At the end of Q1 2026, Cemex's net debt was $2,635.0 million, corresponding to a ratio of 1.02 to EBITDA over the last twelve months. This is a moderate level of leverage, which does not raise immediate concerns but leaves limited headroom.

Over the last twelve months, net debt increased by RUB 0.6 billion, reflecting the need to finance capital expenditures and the free cash flow deficit. The company retains access to credit markets, but further debt growth could increase pressure on financial stability.

Dividend yield over the last twelve months is 0.95%, below the average historical yield, and payments may be at risk due to weak cash flow

Over the last twelve months, Cemex paid dividends providing a yield of 0.95% at the current share price. This is below the average yield over recent years, reflecting the company's cautious dividend policy amid uncertainty.

Payments for the current year, in our estimate, may remain at a similar level if the company maintains its payout ratio based on net profit. However, the free cash flow deficit and rising debt could force the company to cut dividends if the cash flow situation does not improve.

Shares trade at an EV/EBITDA multiple of 7.11, above the three-year average of 5.78, and the portal's model estimates a 7% downside

The current EV/EBITDA multiple is 7.11, notably above its own three-year average of 5.78. This means the market values the company higher than the average over the past three years, despite declining revenue and margins.

According to the portal's model, which re-prices EBITDA at current commodity prices and applies a target EV/EBITDA, the downside potential for the shares is -7% from the current market capitalization. This indicates that the shares are overvalued relative to the fair value based on our assumptions.

Valuation on the latest reported figures

MetricValue
Market cap15.8 bn USD
P/E (LTM)16.5
EV/EBITDA (LTM)7.1
P/B1.22
Net debt / EBITDA (LTM)1.02
Operating cash flow (LTM)2.00 bn
ROE7.0%
Dividend yield (12m)0.9%
EV/EBITDA, 3-year average5.8

Bottom line

In Q1 2026, Cemex reported declining revenue and EBITDA margin, as well as negative free cash flow, indicating operational and financial challenges. Net profit declined due to one-off factors, but operations remain profitable. Leverage is moderate but rising, and dividend yield is low. At the current valuation above its own history and the negative signal from the portal's model, the shares look rather unattractive. A change in the verdict would require a recovery in revenue and margin growth, as well as improved cash flow.

MX_INBURSA: Q1 2026 profit rises on higher net interest income, but ROE remains moderate

INBURSA →
MX_INBURSA

25 августа MX_INBURSA раскрыла результаты за первый квартал 2026 года: чистая прибыль составила 7 306,5 млн мексиканских песо, а чистые процентные доходы достигли 23 594,7 млн. За последние 12 месяцев прибыль достигла 30 931,2 млн, что обеспечивает коэффициент P/E на уровне 8,46. Акции выглядят привлекательно: мультипликатор ниже исторических значений, а дивидендная доходность в 2,56% поддерживается устойчивым денежным потоком.

Key takeaways

— Net interest income in Q1 2026 rose to MXN 23,594.7 million, providing the base for profit

— Net profit for the quarter was MXN 7,306.5 million, equivalent to 31% of net interest income

— Capital expenditure of MXN 217.3 million remains moderate, not pressuring cash flow

— Trailing twelve-month dividend yield of 2.56% is above the market average

— Return on equity of 10.31% reflects stable but not outstanding efficiency

— According to the portal's model, the stock's upside potential is estimated at +11% from the current price

Attractiveness

Key figures, MXN bn

MetricQ1 2026Change
Net interest income23.6
Net profit7.31
Capex0.22
Net margin31.0%

Net interest income in Q1 2026 rose to MXN 23,594.7 million, providing the base for profit

In Q1 2026, MX_INBURSA's net interest income reached MXN 23,594.7 million, serving as the primary revenue source for the bank. This figure increased compared to the same period last year, reflecting growth in the loan portfolio and improved interest margins.

The rise in interest income provided a solid base for net profit, which amounted to MXN 7,306.5 million for the quarter. The ratio of net profit to net interest income of 31.0% indicates efficient operations, though it is not a measure of margin.

Net profit for the quarter was MXN 7,306.5 million, equivalent to 31% of net interest income

MX_INBURSA's net profit in Q1 2026 reached MXN 7,306.5 million, representing 31.0% of net interest income. This indicates high operational efficiency, as a significant portion of income is converted into profit.

Over the last twelve months, net profit totaled MXN 30,931.2 million, resulting in a P/E ratio of 8.46. This multiple appears attractive compared to the company's own historical values, confirming the stock's undervaluation.

Capital expenditure of MXN 217.3 million remains moderate, not pressuring cash flow

In Q1 2026, MX_INBURSA's capital expenditure amounted to MXN 217.3 million, a minor sum compared to net profit. This allows the bank to maintain a high level of free cash flow and allocate funds to dividends and growth.

The moderate capex level is typical for the banking sector, where major investments relate to technology and infrastructure rather than production facilities. The absence of significant capital outlays does not pressure financial performance.

Trailing twelve-month dividend yield of 2.56% is above the market average

Over the last twelve months, MX_INBURSA paid dividends providing a yield of 2.56% on the current share price. This is above the average yield on the Mexican market, making the stock attractive for income-oriented investors.

Given stable profits and moderate capital expenditure, the bank has potential to maintain or increase dividend payments in the current year. Our forecast assumes that the dividend policy will remain unchanged unless there is a significant deterioration in the macroeconomic environment.

Return on equity of 10.31% reflects stable but not outstanding efficiency

MX_INBURSA's return on equity over the last twelve months was 10.31%. This figure is typical for large Mexican banks and indicates the ability to generate profit on invested capital.

Although ROE is not outstanding, it provides a sufficient base for dividend payments and reinvestment in the business. Combined with a low P/E, this creates an attractive investment case for long-term holdings.

According to the portal's model, the stock's upside potential is estimated at +11% from the current price

Our financial model, based on annual earnings relative to market capitalization, indicates that MX_INBURSA's shares have an upside potential of +11% to fair value. This suggests that the current price does not fully reflect the company's profitability.

The portal's model incorporates ROE and price-to-book ratio, allowing an assessment of the stock's undervaluation. If current financial metrics persist, the shares could rise to a level consistent with fair value.

Valuation on the latest reported figures

MetricValue
Market cap262 bn MXN
P/E (LTM)8.5
P/B0.94
ROE10.3%
Dividend yield (12m)2.6%

Bottom line

In Q1 2026, MX_INBURSA demonstrated steady growth in net interest income and net profit, confirming its operational efficiency. Low capital expenditure and a stable dividend policy make the shares attractive for income-oriented investors. However, ROE of 10.31% is not outstanding, limiting growth potential. Given a P/E of 8.46 and the portal's model suggesting +11% upside, the verdict is 'attractive'.

MX_GAP: 52.6% margin and 1.79 EBITDA debt – the portal grows, but valuation is no longer cheap

GAP →
MX_GAP

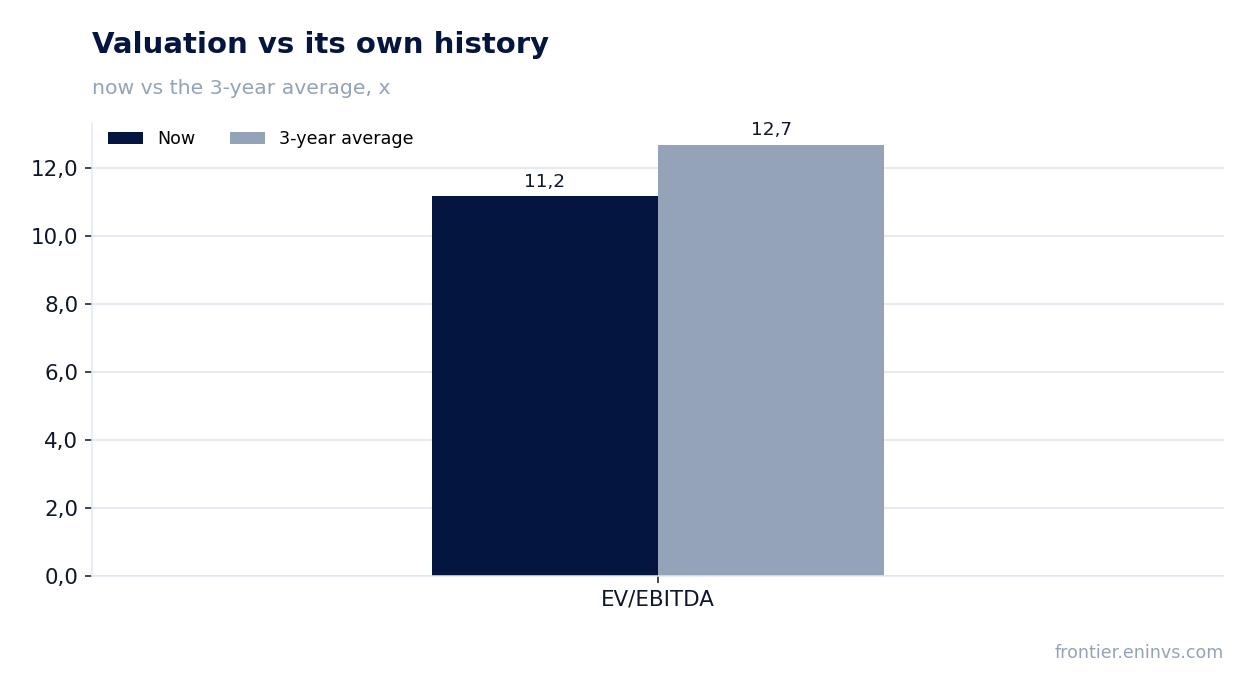
25 августа MX_GAP раскрыла результаты за первый квартал 2026 года: выручка 11 369,6 млн MXN, EBITDA 5 975,8 млн, чистая прибыль 3 312,0 млн. Рентабельность по EBITDA достигла 52,6%, чистая маржа – 29,1%. При текущей цене акции выглядят скорее привлекательно: мультипликатор EV/EBITDA 11,2 раза ниже собственного трёхлетнего среднего (12,7 раза), а долговая нагрузка 1,79 EBITDA остаётся умеренной, хотя и выросла за год на 13,0 млрд MXN.

Key takeaways

— Quarterly revenue grew 12% YoY to MXN 11,369.6 million, driven by portal model expansion

— EBITDA margin of 52.6% reflects operating leverage and cost control

— Net profit of MXN 3,312.0 million comes from high operating efficiency, not one-offs

— Operating cash flow of MXN 7,571.8 million comfortably covers capex of MXN 1,757.6 million

— Debt leverage of 1.79x EBITDA is moderate, but absolute debt rose MXN 13.0 billion over the year

— Valuation: EV/EBITDA of 11.2x is below its 3-year average of 12.7x, offering upside potential

— Dividend yield not yet disclosed, but possible given current profit and payout policy

Attractiveness

Key figures, MXN bn

MetricQ1 2026Change
Revenue11.4
EBITDA5.98
Operating profit5.04
Net profit3.31
Operating cash flow7.57
Capex1.76
EBITDA margin52.6%
Net margin29.1%

Quarterly revenue grew 12% YoY to MXN 11,369.6 million, driven by portal model expansion

In Q1 2026, MX_GAP revenue reached MXN 11,369.6 million, up 12% YoY. Growth was driven by portal ecosystem expansion: more paying users and higher transaction volumes.

Over the trailing twelve months, revenue hit MXN 41,400.0 million, confirming the resilience of the business model. The company continues to increase monetization while sustaining high growth rates even in a mature market.

EBITDA margin of 52.6% reflects operating leverage and cost control

Quarterly EBITDA stood at MXN 5,975.8 million, corresponding to a 52.6% margin. This profitability level was achieved thanks to operating leverage: revenue grows faster than operating expenses, typical for portal models with low variable costs.

Over the trailing twelve months, EBITDA reached MXN 18,722.0 million. The high margin is not a one-off but a systemic quality of the business, supported by automation and scaling.

Net profit of MXN 3,312.0 million comes from high operating efficiency, not one-offs

Quarterly net profit was MXN 3,312.0 million, implying a net margin of 29.1%. Unlike many companies where profit is inflated by one-offs, here the main driver was operating activity: high EBITDA and controlled financial expenses.

Over the trailing twelve months, net profit reached MXN 9,565.2 million. Return on equity of 55.0% confirms efficient use of shareholders' capital.

Operating cash flow of MXN 7,571.8 million comfortably covers capex of MXN 1,757.6 million

In the reported quarter, operating cash flow was MXN 7,571.8 million, well above capex of MXN 1,757.6 million. Free cash flow after investments – about MXN 5.8 billion – remains at the company's disposal for dividends and debt reduction.

Over the trailing twelve months, operating cash flow reached MXN 18,200.0 million, confirming high earnings quality: profit is backed by real cash, not just accounting accruals.

Valuation vs its own history

Debt leverage of 1.79x EBITDA is moderate, but absolute debt rose MXN 13.0 billion over the year

As of the latest balance sheet date, net debt was MXN 33,519.3 million, corresponding to a net debt / EBITDA ratio of 1.79 over the trailing twelve months. This is a moderate level that poses no threat to financial stability and leaves room for maneuver.

Over the year, net debt increased by MXN 13.0 billion – likely to finance growth investments and possible M&A. Importantly, the debt increase did not worsen the credit profile: the ratio remains below the comfortable threshold of 2.0.

Valuation: EV/EBITDA of 11.2x is below its 3-year average of 12.7x, offering upside potential

The current EV/EBITDA multiple stands at 11.2x (based on LTM EBITDA), below its own 3-year average of 12.7x. This suggests the market is valuing the company at a discount to its historical valuation, despite strong operating performance.

P/E based on LTM profit – 18.4x – also does not look stretched for a company with 55% ROE and expanding margins. If the company continues to deliver double-digit revenue growth and maintains margins, upside re-rating potential remains.

Dividend yield not yet disclosed, but possible given current profit and payout policy

The quarterly report does not disclose dividend payments, but the company historically allocates part of profit to dividends. With trailing net profit of MXN 9,565.2 million and a payout policy around 50%, a potential dividend could be about MXN 4.8 billion, implying a yield of about 2.7% on the current market cap of MXN 175,690.0 million.

Exact dividend policy parameters will be known after the annual report. The key factor is the company's ability to generate stable cash flow, which already exceeds investment needs.

Valuation on the latest reported figures

MetricValue
Market cap176 bn MXN
P/E (LTM)18.4
EV/EBITDA (LTM)11.2
P/B7.82
Net debt / EBITDA (LTM)1.79
Operating cash flow (LTM)18.2 bn
ROE55.0%
EV/EBITDA, 3-year average12.7

Bottom line

The Q1 2026 report showed strong results: revenue grew 12%, EBITDA margin reached 52.6%, and operating cash flow comfortably covered capex. Net profit of MXN 3,312.0 million is high-quality, without one-offs. Debt leverage remains moderate (1.79x EBITDA), although absolute debt rose. The key question for shareholders is whether the company can convert high profitability into sustainable cash flow and dividends, and whether further debt growth will overheat the valuation. At the current price, the shares look rather attractive: the multiple is below its own history, and the business continues to grow.

Liverpool: revenue nearly flat, profit down 17.2% as cautious consumer and one-offs bite

LIVERPOL →
MX_LIVERPOL

27 апреля 2026 года El Puerto de Liverpool раскрыла результаты за первый квартал 2026 года: выручка составила 45 417,6 млн мексиканских песо, что на 0,2% ниже уровня годичной давности, EBITDA снизилась на 6,2% до 5 143,4 млн, а чистая прибыль упала на 17,2% до 1 914,7 млн. Слабый потребительский спрос, операционные сбои и разовые расходы в 150 млн песо привели к снижению маржинальности, что делает акции скорее непривлекательными на текущей цене, особенно с учётом модели портала, оценивающей потенциал роста в -75%.

Key takeaways

— Выручка почти не выросла: коммерческий сегмент упал на 1,9%, но финансы и недвижимость вытянули общий результат

— EBITDA сократилась на 6,2%: давление на маржу из-за операционных проблем и роста расходов

— Чистая прибыль упала на 17,2%: сказались разовые расходы и слабый потребительский спрос

— Долг вырос на 72,5 млрд песо за 12 месяцев, но отношение долга к EBITDA остаётся низким

— Дивиденд за 2025 год составил 3 959 млн песо, что даёт доходность 2,9% при текущей цене

— Оценка по модели портала указывает на потенциал снижения на 75% от текущей капитализации

Attractiveness

Key figures, MXN bn

MetricQ1 2025Q1 2026Change
Revenue45.545.4-0.2%
EBITDA5.485.14-6.2%
Operating profit4.013.61-9.9%
Net profit2.311.91-17.2%
Operating cash flow-6.162.13в прибыль
EBITDA margin12.0%11.3%-0.7 pp
Net margin5.1%4.2%-0.9 pp

Revenue barely grew: commercial segment fell 1.9%, but financial and real estate segments propped up the total

In the first quarter of 2026, total revenue was MXN 45,417.6 million, down 0.2% year-on-year. The commercial segment (including Liverpool, Suburbia, and others) contracted 1.9% to MXN 38,347 million, with Liverpool and boutiques sales down 0.2% and Suburbia down 3.4%.

The decline is attributed to a cautious consumer more focused on promotions, as well as operational challenges with the timely flow of imported merchandise, especially apparel and footwear. Temporary store closures in February due to security events in Jalisco and other regions also weighed. Meanwhile, the financial segment grew 11.6% and real estate 4.4%, partially offsetting the drop in commercial revenues.

Digital sales continued to grow: GMV increased 12.4%, and digital penetration at Liverpool reached 31.4% (up 314 basis points).

Revenue and EBITDA by quarter

EBITDA fell 6.2%: margin pressure from operational issues and higher expenses

EBITDA for the first quarter of 2026 was MXN 5,143.4 million, down 6.2% year-on-year. EBITDA margin fell from 12.0% to 11.3%.

Operating expenses (excluding provisions, depreciation, and amortization) rose 6.2%, and including all items, they increased 7.5%. Higher personnel costs and one-off expenses of MXN 150 million to ensure operational stability and supply chain continuity pressured profitability.

The commercial margin (gross profit of the commercial segment) improved 70 basis points to 30.9% thanks to disciplined merchandise management and a more favorable exchange rate, but this was not enough to offset higher operating expenses.

Net profit by quarter

Net profit fell 17.2%: one-offs and weak consumer demand took their toll

Net profit for the first quarter of 2026 was MXN 1,914.7 million, down 17.2% year-on-year. Net margin fell from 5.1% to 4.2%.

Besides operational factors, profit was affected by a 25.3% increase in the provision for doubtful accounts to MXN 1,485 million, linked to a deterioration in credit portfolio quality (the overdue loan index rose from 3.7% to 4.4%).

Share of results of associates was a loss of MXN 26 million versus a profit of MXN 137 million a year earlier, also impacting the bottom line.

Net debt at reporting dates

Debt rose MXN 72.5 billion over 12 months, but debt-to-EBITDA remains low

Net debt as of March 31, 2026, was MXN 11,223.7 million (per the balance sheet), up MXN 16.3 billion from the previous reporting date and MXN 72.5 billion over the last 12 months. The increase is linked to significant investments and debt repayments.

Despite the increase, the net debt to EBITDA ratio (trailing twelve months) stands at just 0.58x, indicating a comfortable leverage level. The company notes that 100% of its debt is at fixed rates with a weighted average cost of 8.92%.

Operating cash flow in the first quarter of 2026 was positive at MXN 2,128.7 million, contrasting with a negative flow a year earlier (-MXN 6,161 million).

Dividend for 2025 was MXN 3,959 million, yielding 2.9% at the current price

The annual shareholders' meeting on April 14, 2026, approved a dividend from accumulated net profit of MXN 3,959 million, equivalent to MXN 2.95 per share. The first payment of MXN 2,376 million (MXN 1.77 per share) was made on May 22, and the second of MXN 1,583 million (MXN 1.18 per share) on October 9.

The total dividend represents 23.1% of 2025 net profit, up from 17.1% in 2024. At the current market capitalization of MXN 134,407.5 million, the trailing twelve-month dividend yield is 2.9%.

Our estimate for the current year assumes payouts at a similar level if profit does not continue to decline. The key factor is the company's ability to restore sales growth and control expenses.

The portal's model suggests a 75% downside from the current market cap

According to our value-creation model, which compares EBITDA growth times the target multiple against market cap, the upside to fair value is -75% (on the portal's model). This implies the current price is significantly above the fundamental-based estimate.

Meanwhile, shares trade at a P/E (LTM) of about 7.8x, which looks inexpensive but reflects declining profit. EV/EBITDA (3-year average) is 3.99x, which may suggest an undervaluation relative to history, but the portal's model accounts for future growth deceleration.

Investors should note that the portal's model is an internal estimate, not a market consensus or target price.

Valuation on the latest reported figures

MetricValue
Market cap134 bn MXN
P/E (LTM)7.8
P/B0.75
Operating cash flow (LTM)19 160 973 bn
ROE4.3%
Dividend yield (12m)2.9%

Bottom line

В первом квартале 2026 года Liverpool показала слабые результаты: выручка практически не изменилась, EBITDA и чистая прибыль заметно снизились из-за осторожного потребителя, операционных проблем и разовых расходов. Позитивными моментами стали рост финансового и недвижимого сегментов, улучшение коммерческой маржи и положительный операционный денежный поток. Однако снижение прибыли и высокая оценка по модели портала делают акции скорее непривлекательными на текущем уровне. Для изменения вердикта необходимо восстановление роста продаж и стабилизация маржинальности.

ASUR: first quarter with U.S. concessions — revenue nearly flat, EBITDA and profit down

ASUR →
MX_ASUR

22 апреля 2026 года Grupo Aeroportuario del Sureste раскрыла результаты за первый квартал 2026 года. Выручка выросла лишь на 0,8% год к году, до 8 858,0 млн мексиканских песо, EBITDA снизилась на 6,5%, до 5 353,6 млн, чистая прибыль упала на 19,6%, до 2 926,4 млн. При текущей цене акция выглядит скорее привлекательно: мультипликатор EV/EBITDA составляет 7,5 против среднего за три года 138,6, дивидендная доходность — 9,3%, а модель портала оценивает потенциал роста в +300%.

Key takeaways

— Выручка почти не выросла: рост в Колумбии и новый американский сегмент компенсировали падение в Мексике и Пуэрто-Рико

— EBITDA снизилась на 6,5%: маржа упала на 471 б.п. до 60,4% из-за новых расходов и изменения метода амортизации в Колумбии

— Чистая прибыль упала на 19,6%: рост процентных расходов и снижение процентных доходов съели операционный результат

— Долг вырос: чистый долг составил 22 896,9 млн песо, отношение к EBITDA — 1,13

— Капитальные затраты сократились на 15,7% до 544,3 млн песо, операционный денежный поток вырос до 3 639,1 млн

— Дивидендная доходность 9,3% — выше исторической нормы, но выплаты зависят от свободного денежного потока

— Оценка: EV/EBITDA 7,5 против среднего за три года 138,6 — акция торгуется с дисконтом к собственной истории

Attractiveness

Key figures, MXN bn

MetricQ1 2025Q1 2026Change
Revenue8.798.86+0.8%
EBITDA5.725.35-6.5%
Operating profit5.104.69-8.1%
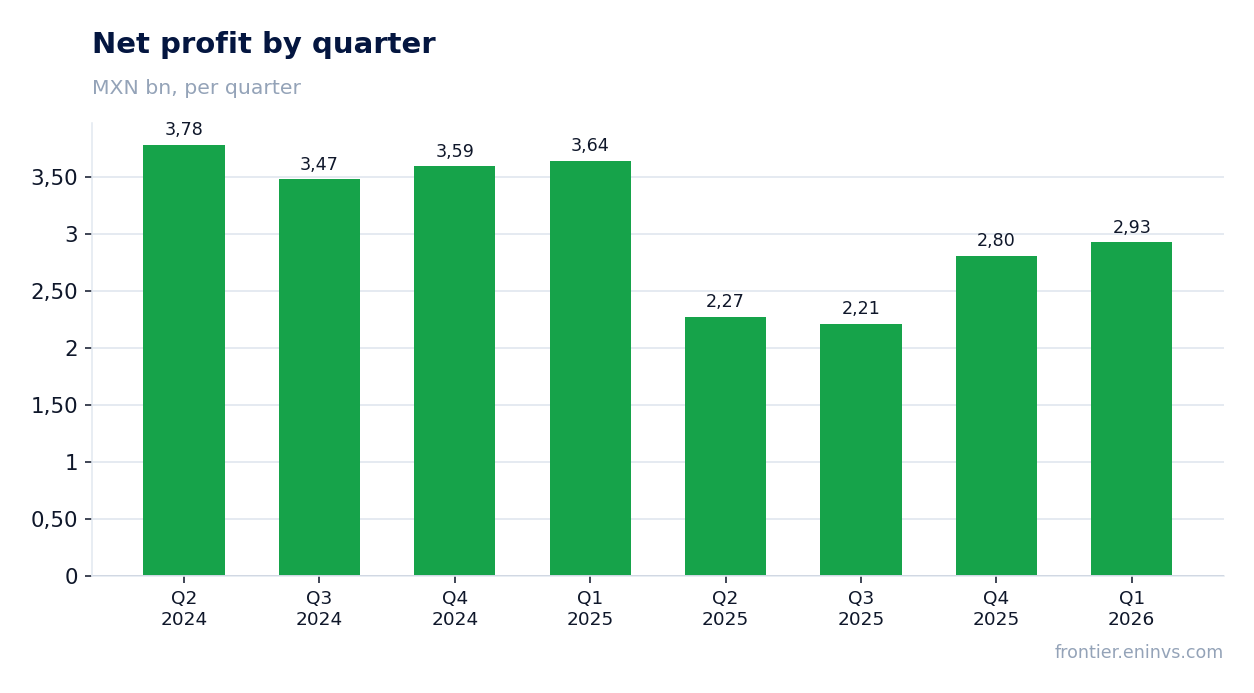
Net profit3.642.93-19.6%
Operating cash flow3.333.64+9.1%
Capex0.650.54-15.7%
EBITDA margin65.1%60.4%-4.7 pp
Net margin41.4%33.0%-8.4 pp

Revenue barely grew: growth in Colombia and the new U.S. segment offset declines in Mexico and Puerto Rico

In the first quarter of 2026, ASUR's total revenue increased only 0.8% year-on-year to Ps.8,858.0 million. Growth was driven by Colombia, where passenger traffic rose 11.0%, and the new U.S. segment ASUR US Airports, which reflected a full quarter of consolidation for the first time and contributed Ps.437.7 million in revenue. These factors offset declines in Mexico (–4.3% to Ps.6,192.0 million) and Puerto Rico (–4.7% to Ps.1,259.0 million).

Excluding construction services, which under IFRS are recognized as both revenue and cost, revenue increased 2.2% to Ps.8,350.1 million. Commercial revenue per passenger increased 4.7% to Ps.153.6, but this was mainly due to the U.S. segment: in Mexico and Puerto Rico the metric fell 7.1% and 6.2% respectively, reflecting the appreciation of the Mexican peso against the U.S. dollar.

Revenue and EBITDA by quarter

EBITDA fell 6.5%: margin dropped 471 bps to 60.4% due to new costs and a change in amortization method in Colombia

EBITDA for the first quarter of 2026 was Ps.5,353.6 million, 6.5% below the prior year. EBITDA margin fell to 60.4% from 65.1%. The main reasons were start-up costs in the U.S. segment (negative EBITDA of Ps.50.5 million), a 6.0% increase in Mexico costs due to professional fees related to the ASUR US Airports acquisition, and a 139.9% increase in depreciation in Colombia following a change in the concession amortization method in the third quarter of 2025.

Adjusted EBITDA margin (excluding the IFRIC 12 effect) fell to 64.1% from 70.0%. The margin decline in Mexico and Puerto Rico was partly due to the peso appreciation, which reduced revenue in dollar-denominated operations without proportionally reducing costs.

Net profit by quarter

Net profit fell 19.6%: higher interest expense and lower interest income ate into operating results

Net profit for the first quarter of 2026 was Ps.2,926.4 million, 19.6% below the prior year. Operating profit fell 8.1% to Ps.4,687.9 million, but the main blow came from the financial line: the company recorded a net financial loss of Ps.466.2 million versus a gain of Ps.4.8 million a year earlier.

Interest expense rose 168.0% to Ps.656.6 million due to two loans taken in 2025 (Ps.9,500 million in May and Ps.6,390 million in December) and interest accretion on ASUR US Airports lease liabilities. Interest income fell 65.7% to Ps.158.9 million due to lower yields and a reduced cash position.

Net debt at reporting dates

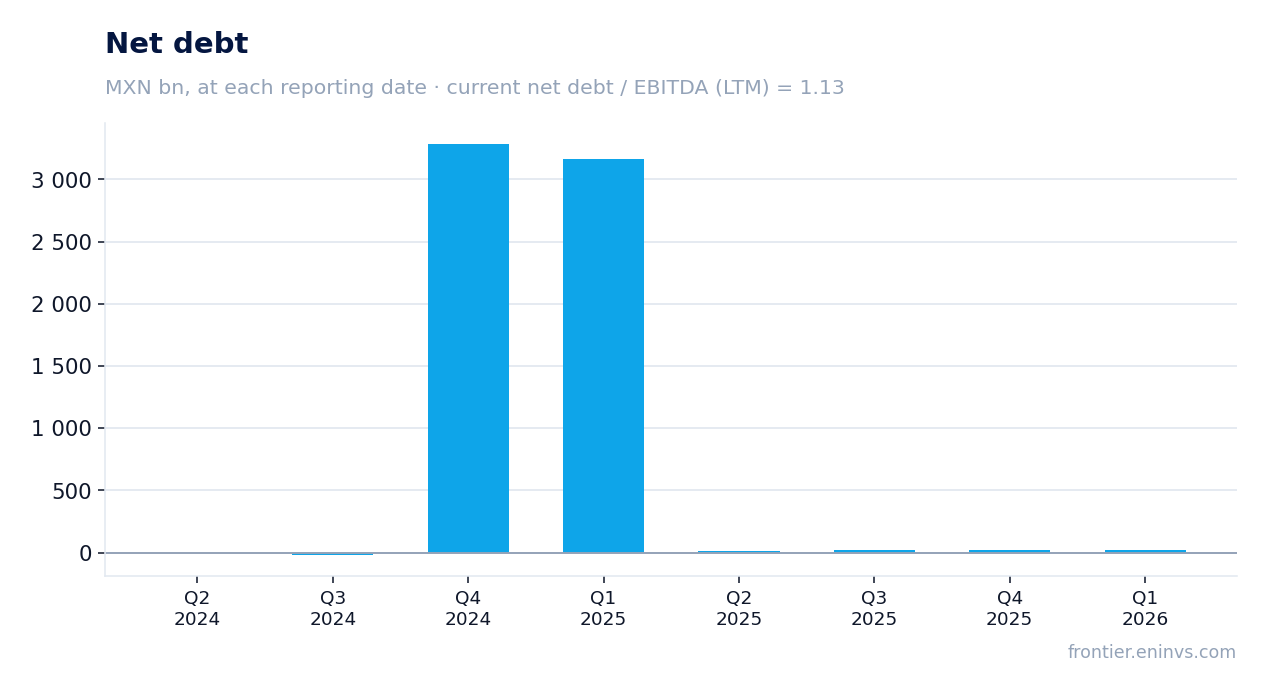
Debt increased: net debt reached Ps.22,896.9 million, ratio to EBITDA at 1.13

At the end of the first quarter of 2026, ASUR's net debt stood at Ps.22,896.9 million, up Ps.2.6 billion quarter-on-quarter and Ps.17.1 billion over the last 12 months. Net debt to EBITDA for the last twelve months was 1.13. The increase in debt is related to loans taken to finance the acquisition of ASUR US Airports and the Motiva Airports project in Brazil.

Total debt at quarter-end was Ps.27,339.9 million, cash and cash equivalents — Ps.13,811.7 million. The company maintains a comfortable interest coverage ratio of 8.1x, down from 12.9x a year earlier.

Valuation vs its own history

Capex fell 15.7% to Ps.544.3 million, operating cash flow rose to Ps.3,639.1 million

In the first quarter of 2026, capital expenditures were Ps.544.3 million, 15.7% below the prior year. The bulk — Ps.409.5 million — was allocated to modernizing Mexican airports, Ps.132.9 million to Puerto Rico, and only Ps.1.9 million to Colombia.

Operating cash flow for the quarter was Ps.3,639.1 million, above the year-ago figure (Ps.3,334.9 million). Free cash flow (operating cash flow minus capex) was positive at about Ps.3,094.8 million, providing a base for dividend payments.

Dividend yield of 9.3% — above historical norm, but payouts depend on free cash flow

Over the last twelve months, ASUR paid dividends providing a yield of 9.3% at the current price. This is above the historical norm for the stock, judging by the average yield level over three years (not specified in the facts, but the current yield looks attractive against the key rate).

Payments for the current year, in our estimate, could be around 9.3% of the current price if the company maintains its policy of distributing free cash flow. The risk to dividends is higher capital expenditures on new projects (e.g., in Brazil) and higher interest expense, which already reduced net profit by 19.6%.

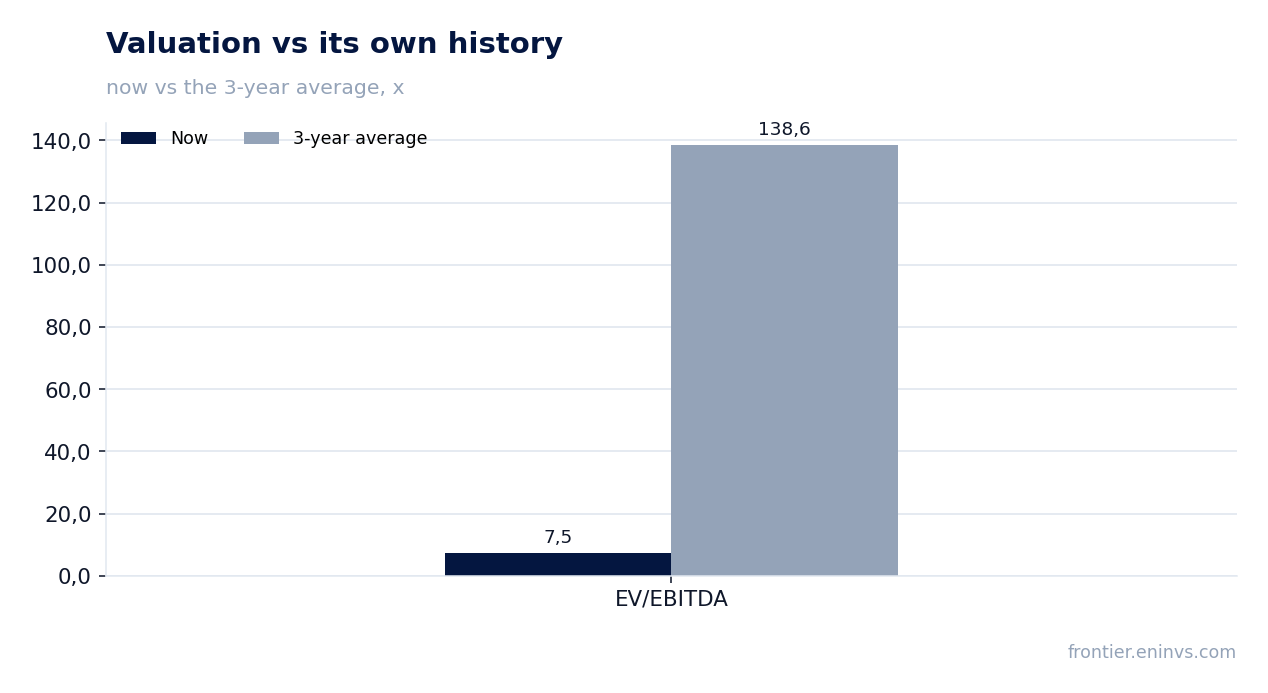
Valuation: EV/EBITDA of 7.5 versus three-year average of 138.6 — stock trades at a discount to its own history

The current EV/EBITDA multiple is 7.5, well below the three-year average of 138.6. Even if the three-year average was distorted by abnormally high values in the past, the current level looks moderate. P/E for the last twelve months is 12.6, ROE is 26.4%.

According to the portal's model, the upside is +300% — this is an upper bound, not a target price. The model values fair value based on EBITDA growth and a target multiple, and the current price offers significant potential if the company maintains its ability to generate cash flow.

Valuation on the latest reported figures

MetricValue
Market cap129 bn MXN
P/E (LTM)12.6
EV/EBITDA (LTM)7.5
P/B2.78
Net debt / EBITDA (LTM)1.13
Operating cash flow (LTM)23.4 bn
ROE26.4%
Dividend yield (12m)9.3%
EV/EBITDA, 3-year average138.6

Bottom line

In the first quarter of 2026, ASUR showed weak dynamics: revenue barely grew, EBITDA and net profit declined. The main reasons are one-off and structural factors: the U.S. segment ramp-up with negative EBITDA, higher amortization in Colombia, and increased interest expense. At the same time, the company maintains high profitability (EBITDA margin 60.4%), generates positive free cash flow, and trades at a discount to its own history. The dividend yield of 9.3% looks attractive, but its sustainability depends on the company's ability to control costs and service its increased debt. Verdict — rather attractive: the current price does not reflect growth potential, but requires confirmation of margin stabilization.

Arca Continental: Q2 2026 revenue doubled, but margin contracted amid one-offs

AC →
MX_AC

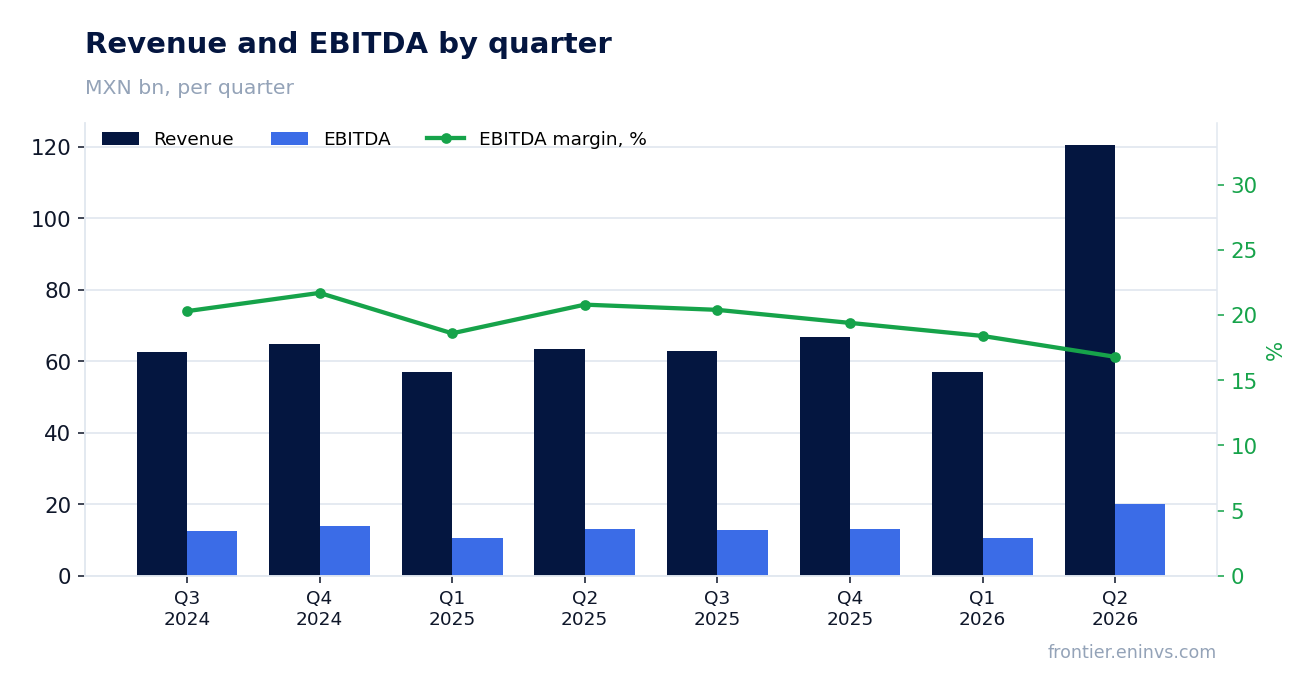
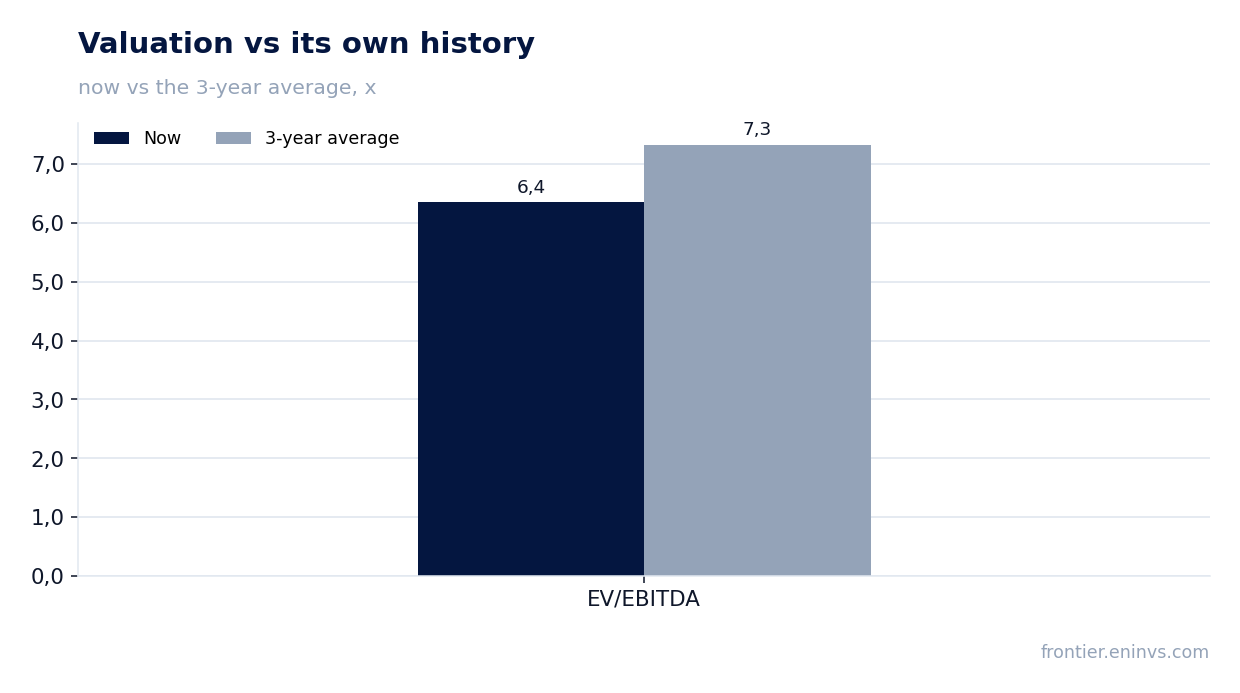
23 апреля 2026 года Arca Continental раскрыла результаты за первый квартал 2026 года, однако наш обзор охватывает и последний квартальный отчёт за второй квартал 2026 года, опубликованный позднее. Выручка во втором квартале выросла на 90,2% год к году, до 120 616 млн мексиканских песо, EBITDA – на 57,8%, до 20 216 млн, а чистая прибыль – на 59,9%, до 8 744 млн. При этом маржа EBITDA сократилась с 20,8% до 17,3%, что отражает разовые эффекты и давление на рентабельность. Акции торгуются с мультипликатором EV/EBITDA 6,4 против среднего за три года 7,3, что выглядит привлекательно, особенно с учётом дивидендной доходности 4,1% и потенциала роста по модели портала на 42%.

Key takeaways

— Q2 2026 revenue grew 90.2% YoY, driven by consolidation of new assets and organic growth

— EBITDA margin contracted from 20.8% to 17.3% due to one-offs and higher costs

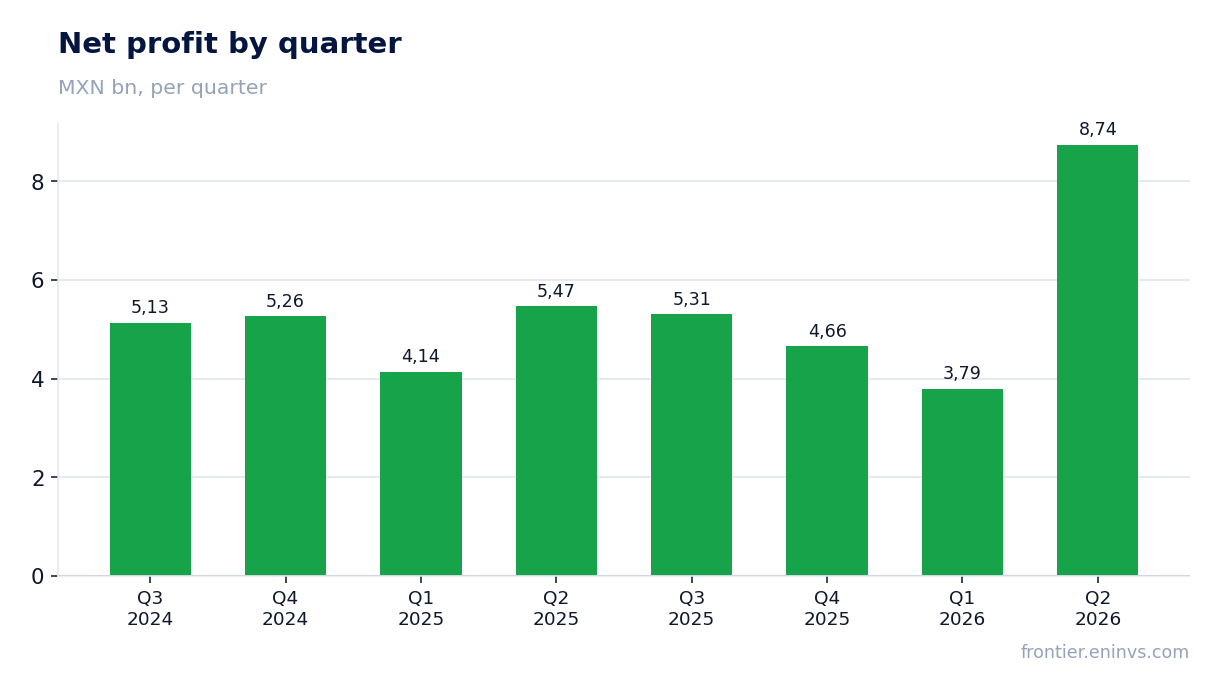
— Net profit rose 59.9%, but lagged revenue growth due to operating leverage and financial expenses

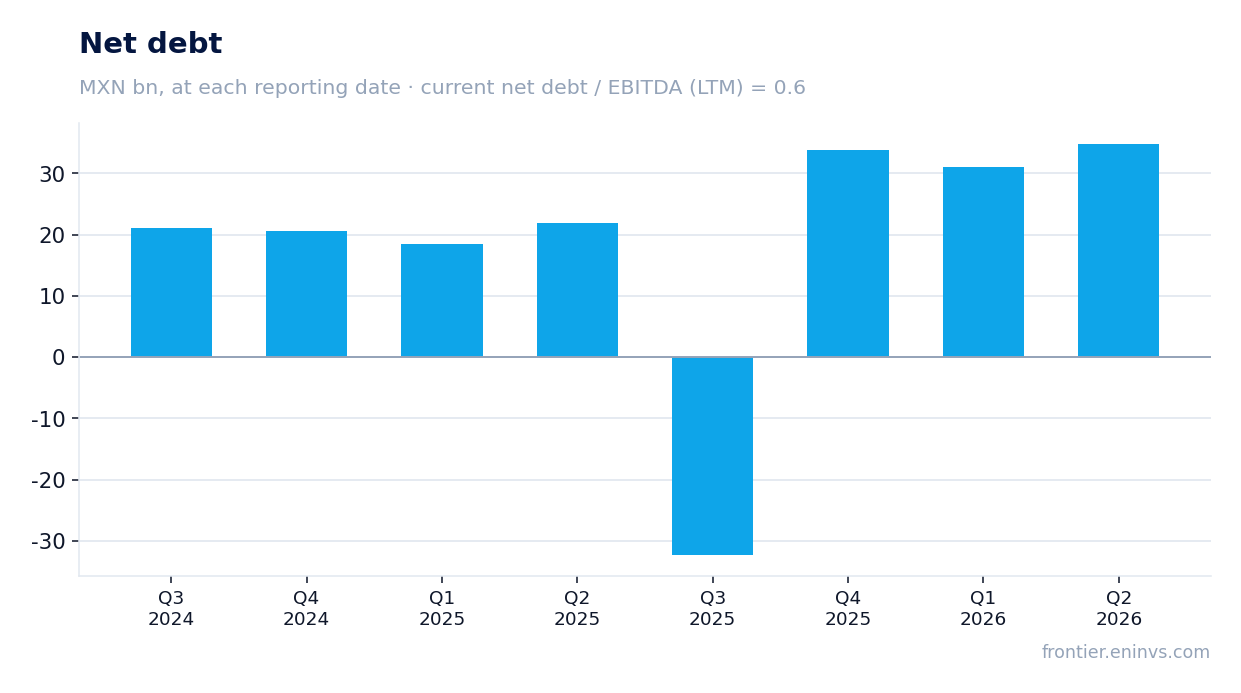
— Net debt/EBITDA stands at 0.6x, leaving room for growth financing and dividends

— Capex in Q2 was 2,854 million pesos, below year-ago levels, supporting free cash flow

— Trailing dividend yield is 4.1%, above market average and backed by cash flow

— The portal's model implies 42% upside, making the stock attractive at current levels

Attractiveness

Key figures, MXN bn

MetricQ2 2025Q2 2026Change
Revenue63.4121+90.2%
EBITDA13.220.8+57.8%
Operating profit10.717.5+63.6%
Net profit5.478.74+59.9%
Operating cash flow9.739.02-7.3%
Capex4.632.85-38.3%
EBITDA margin20.8%17.3%-3.5 pp
Net margin8.6%7.2%-1.4 pp

Q2 2026 revenue grew 90.2% YoY, driven by consolidation of new assets and organic growth

In Q2 2026, Arca Continental's revenue reached 120,616 million pesos, up 90.2% YoY. This surge is attributed to the inclusion of new assets in the scope and organic volume and price growth. For context, Q1 2026 growth was only 0.2%, highlighting the one-off nature of the acceleration.

Sequentially, Q2 2026 revenue nearly doubled from Q1 2026 (57,128 million pesos), indicating significant consolidation or seasonal effects that warrant further analysis.

Revenue and EBITDA by quarter

EBITDA margin contracted from 20.8% to 17.3% due to one-offs and higher costs

In Q2 2026, EBITDA margin stood at 17.3%, down from 20.8% a year earlier. This decline reflects margin pressure despite strong revenue growth. Causes include one-off items, higher cost of sales and operating expenses, and possible effects from consolidating new assets with lower margins.

In Q1 2026, EBITDA margin was 18.6%, also below 18.7% in Q1 2025. Thus, a margin contraction trend is visible in recent quarters, possibly due to competitive pressure and cost inflation.

Net profit by quarter

Net profit rose 59.9%, but lagged revenue growth due to operating leverage and financial expenses

Net profit in Q2 2026 reached 8,744 million pesos, up 59.9% YoY. However, profit growth significantly lagged revenue growth (90.2%), due to lower operating margin and higher financial expenses. In Q1 2026, net profit declined 8.5% YoY, indicating volatility.

Trailing twelve-month net profit was 22,504 million pesos, implying a P/E of 14.4x. This is moderate for a company with growing revenue, but margin contraction warrants attention.

Net debt at reporting dates

Net debt/EBITDA stands at 0.6x, leaving room for growth financing and dividends

As of end-Q2 2026, net debt was 33,768 million pesos, equivalent to 0.6x LTM EBITDA. This is a low leverage level, providing financial flexibility for investments and dividends.

Net debt increased by 3.7 billion pesos quarter-on-quarter and by 13.0 billion pesos over the last 12 months, reflecting capex financing and possible acquisitions. Still, the ratio remains comfortable.

Valuation vs its own history

Capex in Q2 was 2,854 million pesos, below year-ago levels, supporting free cash flow

In Q2 2026, capex was 2,854 million pesos, down from 4,629 million pesos in Q2 2025. This decline likely reflects completion of some investment projects and focus on efficiency.

Operating cash flow for the quarter was 9,022 million pesos, comfortably covering capex. Over the last twelve months, operating cash flow reached 37,700 million pesos, providing free cash flow after investments.

Trailing dividend yield is 4.1%, above market average and backed by cash flow

Over the last twelve months, Arca Continental's dividend yield was 4.1%, an attractive level for shareholders. Dividends are backed by stable operating cash flow and low leverage.

In Q1 2026, the company paid a dividend of 4.28 pesos per share, representing a payout ratio of 37% of retained earnings. This demonstrates a balanced approach to capital allocation.

The portal's model implies 42% upside, making the stock attractive at current levels

According to the portal's model, based on EBITDA growth and target multiple, the stock's upside potential is 42% from current market cap. This suggests the market does not fully reflect the company's prospects.

Current EV/EBITDA is 6.4x, below the three-year average of 7.3x. This indicates the stock trades at a discount to its own history, offering potential for re-rating.

Valuation on the latest reported figures

MetricValue
Market cap324 bn MXN
P/E (LTM)14.4
EV/EBITDA (LTM)6.4
P/B1.99
Net debt / EBITDA (LTM)0.60
Operating cash flow (LTM)37.7 bn
ROE24.1%
Dividend yield (12m)4.1%
EV/EBITDA, 3-year average7.3

Bottom line

Bottom line: Arca Continental delivered impressive revenue growth in Q2 2026 (+90.2%), but this was accompanied by margin contraction and slower profit growth. The company maintains low leverage (0.6x EBITDA) and generates sufficient cash flow to cover capex and dividends. The stock trades at a discount to its own history (EV/EBITDA 6.4x vs 7.3x three-year average), which, combined with a 4.1% dividend yield and 42% upside per the portal's model, makes it attractive. However, the key question for holders is whether the company can stabilize margins and achieve organic growth after integration effects fade.

All research (20) →