Frontierby eninvs

Language: EN / RU

South Africa Stocks — Valuations, P/E & Dividends

Guide: South African Stocks (2026): Gold, Cheap Banks and the JSE Discount

Related guides: Gold Mining Stocks · The Cheapest Metals & Mining Stocks (2026) · The Cheapest Coal Stocks (2026) · The Cheapest Bank Stocks in the World (2026)

Our recommended portfolios
Performance & current holdings of our strategies for this market — why it makes sense to join.
FVC (quality)backtest CAGR +4% · excess -7%Model portfolio: 6 Jul 2026
CAGR +4% · vs index -7% · Sharpe 0.27 · maxDD -36%
Day-0.3%JSE -1.2%
Week-1.8%JSE -7.0%
Month+4.2%JSE -4.3%
YTD+0.8%JSE -5.6%
By calendar year vs JSE
YearStratJSEΔ
2026-1.6%-3.0%+1.4%
2025+0.2%+37.7%-37.5%
2024+14.2%+10.2%+4.0%
2023+3.1%+4.0%-0.9%
2022-11.2%-0.4%-10.8%
2021+25.8%+24.1%+1.7%
2020-4.8%+4.1%-8.9%
2019+0.0%-0.6%+0.6%
Signal history & trades →
Banks (potential)backtest CAGR +7% · excess -3%Model portfolio: 6 Jul 2026
CAGR +7% · vs index -3% · Sharpe 0.38 · maxDD -50%
Day-0.8%JSE -1.2%
Week-9.3%JSE -7.0%
Month-5.1%JSE -4.3%
YTD-8.5%JSE -5.6%
By calendar year vs JSE
YearStratJSEΔ
2026-2.7%-3.0%+0.2%
2025-2.1%+37.7%-39.9%
2024+22.9%+10.2%+12.7%
2023+7.1%+4.0%+3.2%
2022+13.0%-0.4%+13.4%
2021+27.0%+24.1%+3.0%
2020-19.4%+4.1%-23.5%
2019+0.0%-0.6%+0.6%
Signal history & trades →
Commodity-Upsidebacktest CAGR +7% · excess -3%Model portfolio: 6 Jul 2026
CAGR +7% · vs index -3% · Sharpe 0.39 · maxDD -45%
Day-2.4%JSE -1.2%
Week-11.0%JSE -7.0%
Month-12.5%JSE -4.3%
YTD-11.8%JSE -5.6%
By calendar year vs JSE
YearStratJSEΔ
2026-19.3%-3.0%-16.3%
2025+100.4%+37.7%+62.6%
2024-7.2%+10.2%-17.4%
2023-18.5%+4.0%-22.5%
2022+17.5%-0.4%+17.9%
2021+7.1%+24.1%-17.0%
2020+0.0%+4.1%-4.1%
2019+0.0%+11.3%-11.3%
Signal history & trades →

Sectors: Banks (5) · Insurance (5) · Gold mining (3) · Property REIT (3) · PGM mining (3) · Telecom (3) · Retail (3)

CompanyCountrySectorValue / upsideDiv. %FCF Yield LTMΔ revenue (NII for banks)Δ EBITDA (assets for financials)EV/EBITDA LTMP/E LTMP/B FYROE (ann.)
Growthpoint Properties
ZA_GRT
ZAProperty REIT+79% ▼8.7%3.3%-7.8% ▼63.7%13.8x6.9x0.7x14.7%
Harmony Gold
ZA_HAR
ZAGold mining+34% ▲5.5%10.5%49.2% ▲124.0%3.2x5.1x2.0x52.0%
Gold Fields
ZA_GFI
ZAGold mining+29% ▲7.6%12.8%70.7% ▲95.5%4.1x6.6x3.3x41.5%
Exxaro Resources
ZA_EXX
ZACoal mining+27%10.2%10.0%7.5%0.4%4.1x5.9x0.7x10.3%
Vodacom Group
ZA_VOD
ZATelecom+22% ▲4.1%11.3%25.6% ▲40.2%6.3x7.5x3.7x56.5%
Sanlam
ZA_SLM
ZAInsurance+17%6.5%—-11.8%14.3%—8.5x1.6x24.5%
AngloGold Ashanti
ZA_ANG
ZAGold mining+17% ▲6.0%11.0%8.4% ▲-6.2%5.0x9.9x4.8x34.3%
MTN Group
ZA_MTN
ZATelecom+16% ▲2.3%9.6%8.8% ▲9.8%4.1x22.9x2.8x9.9%
Bidvest / Bidcorp
ZA_BVT
ZAFood & services+15%4.1%11.6%2.2%6.4%6.6x13.3x1.9x12.3%
Shoprite Holdings
ZA_SHP
ZARetail+15%2.6%5.0%7.1%12.9%7.0x23.1x5.5x25.2%
Absa Group
ZA_ABG
ZABanks+15%8.3%—2.9%8.3%—7.3x1.0x14.5%
Old Mutual
ZA_OMU
ZAInsurance+13%6.8%—-32.7%10.8%—6.6x0.9x13.7%
Nedbank Group
ZA_NED
ZABanks+12%8.2%—4.0%9.9%—15.3x1.2x14.5%
Pepkor
ZA_PPH
ZADiscount retail+12% ▲3.1%2.6%13.2% ▲11.6%4.0x10.8x1.0x10.5%
Standard Bank Group
ZA_SBK
ZABanks+11%6.3%—3.6%10.8%—8.9x1.7x19.6%
Redefine Properties
ZA_RDF
ZAProperty REIT+10%8.6%10.6%-0.1%2.9%13.1x5.6x0.7x12.6%
Netcare
ZA_NTC
ZAHealthcare+8%4.9%1.7%4.8%6.9%5.4x12.1x2.1x16.3%
Discovery
ZA_DSY
ZAInsurance+7%1.5%—1.2%16.6%—13.3x2.1x18.0%
FirstRand
ZA_FSR
ZABanks+7%6.2%—-29.2%6.0%—13.8x2.3x11.7%
Mr Price Group
ZA_MRP
ZARetail (apparel)+7% ▼5.1%15.1%3.3% ▼4.6%4.4x12.2x3.1x33.0%
Clicks Group
ZA_CLS
ZARetail / Pharmacy+6%4.5%7.8%3.6%8.5%7.0x14.0x6.8x52.6%
OUTsurance Group
ZA_OUT
ZAInsurance+4%4.5%—11.7%5.6%—25.0x8.7x40.7%
Capitec Bank
ZA_CPI
ZABanks+4%1.9%—94.8%10.4%—30.4x8.6x31.2%
Tiger Brands
ZA_TBS
ZAFood producer+3% ▲16.7%-1.0%1.3% ▲19.5%7.4x11.0x2.2x23.5%
Life Healthcare
ZA_LHC
ZAHealthcare+0%4.7%12.1%2.3%6.0%5.7x2.5x1.5x13.2%
Woolworths Holdings
ZA_WHL
ZARetail-2%5.6%8.5%3.1%3.6%3.3x13.8x3.1x16.5%
AVI Limited
ZA_AVI
ZAFood & consumer-4%11.6%10.4%-2.6%-3.3%6.8x10.9x4.8x35.7%
The Foschini Group
ZA_TFG
ZARetail-5% ▲5.5%38.2%-0.4% ▲-2.5%5.3x12.8x0.6x6.6%
Bidvest Group
ZA_BID
ZAIndustrial / Services-9%2.6%6.1%-1.5%1.1%9.6x18.0x3.4x19.2%
Telkom SA
ZA_TKG
ZATelecom-11%4.1%10.6%-0.7%-7.0%2.3x9.3x0.9x10.8%
Kumba Iron Ore
ZA_KIO
ZAIron ore-14% ▲11.4%16.4%-10.6% ▲-26.8%1.9x5.6x1.2x13.2%
Valterra Platinum
ZA_VAL
ZAPGM mining-21% ▲9.5%15.0%93.2% ▲390.1%4.1x7.6x2.8x41.6%
Truworths International
ZA_TRU
ZARetail (apparel)-39% ▼10.3%10.4%-0.4% ▼-50.7%4.9x6.2x1.6x16.1%
The SPAR Group
ZA_SPP
ZARetail (grocery)-44% ▲—10.2%3.6% ▲-47.2%5.6x—2.1x5.5%
Impala Platinum
ZA_IMP
ZAPGM mining-53% ▲11.1%13.1%72.2% ▲458.9%3.0x4.9x1.3x36.2%
Pick n Pay Stores
ZA_PIK
ZARetail (grocery)-59% ▼—6.0%2.7% ▼10.6%10.3x—2.0x-4.6%
Anglo American
ZA_AGL
ZADiversified mining-71% ▲0.9%4.6%4.5% ▲3.4%8.7x—2.6x-8.3%
Remgro
ZA_REM
ZAInvestment holding-76% ▼5.5%7.1%-10.2% ▼44.0%18.6x74.9x0.8x-5.9%
Northam Platinum
ZA_NPH
ZAPGM mining≤ −90% ▲7.5%14.2%67.4% ▲184.4%5.5x6.4x2.1x28.2%
Sibanye-Stillwater
ZA_SSW
ZAGold & PGM mining≤ −90% ▲9.9%13.2%64.3% ▲638.2%2.7x5.9x2.4x71.9%
Aspen Pharmacare
ZA_APN
ZAPharma≤ −100% ▼1.3%6.2%-30.3% ▼-101.4%28.4x28.9x1.0x2.9%
Resilient REIT
ZA_RES
ZAProperty REIT≤ −100%7.2%-5.9%5.7%-46.3%16.8x5.3x0.9x7.1%
Naspers
ZA_NPN
ZAInternet / Media holding≤ −100% ▲0.8%5.1%80.1% ▲-71.2%—5.5x1.2x10.2%
African Rainbow Minerals
ZA_ARI
ZADiversified mining—8.7%13.0%24.1% ▲—2.2x6.7x0.5x5.7%
Investec
ZA_INL
ZABanking & wealth management—7.1%7.4%7.9%——12.3x1.8x15.1%
Sappi
ZA_SAP
ZAPaper & pulp——-44.8%————0.2x-27.3%
Sasol
ZA_SOL
ZAEnergy / Chemicals——9.1%17.9% ▲26.2%2.7x10.6x0.8x14.0%

Work in progress — needs attention

Issuers below have weak extraction, thin market data, missing valuation inputs, or extreme headline YoY/ROE. Hover the row for the checklist.

CompanyCountrySectorValue / upsideDiv. %FCF Yield LTMΔ revenue (NII for banks)Δ EBITDA (assets for financials)EV/EBITDA LTMP/E LTMP/B FYROE (ann.)
Momentum Group
ZA_MTM
ZAInsurance+14%6.0%—-73.4%14.3%—7.3x1.4x18.7%

Earnings analysis

Short take-aways from recent corporate results and commodity trends.

Sappi: a $116m quarterly loss, and $34m EBITDA does not even cover interest on $1.9bn of debt

SAP →
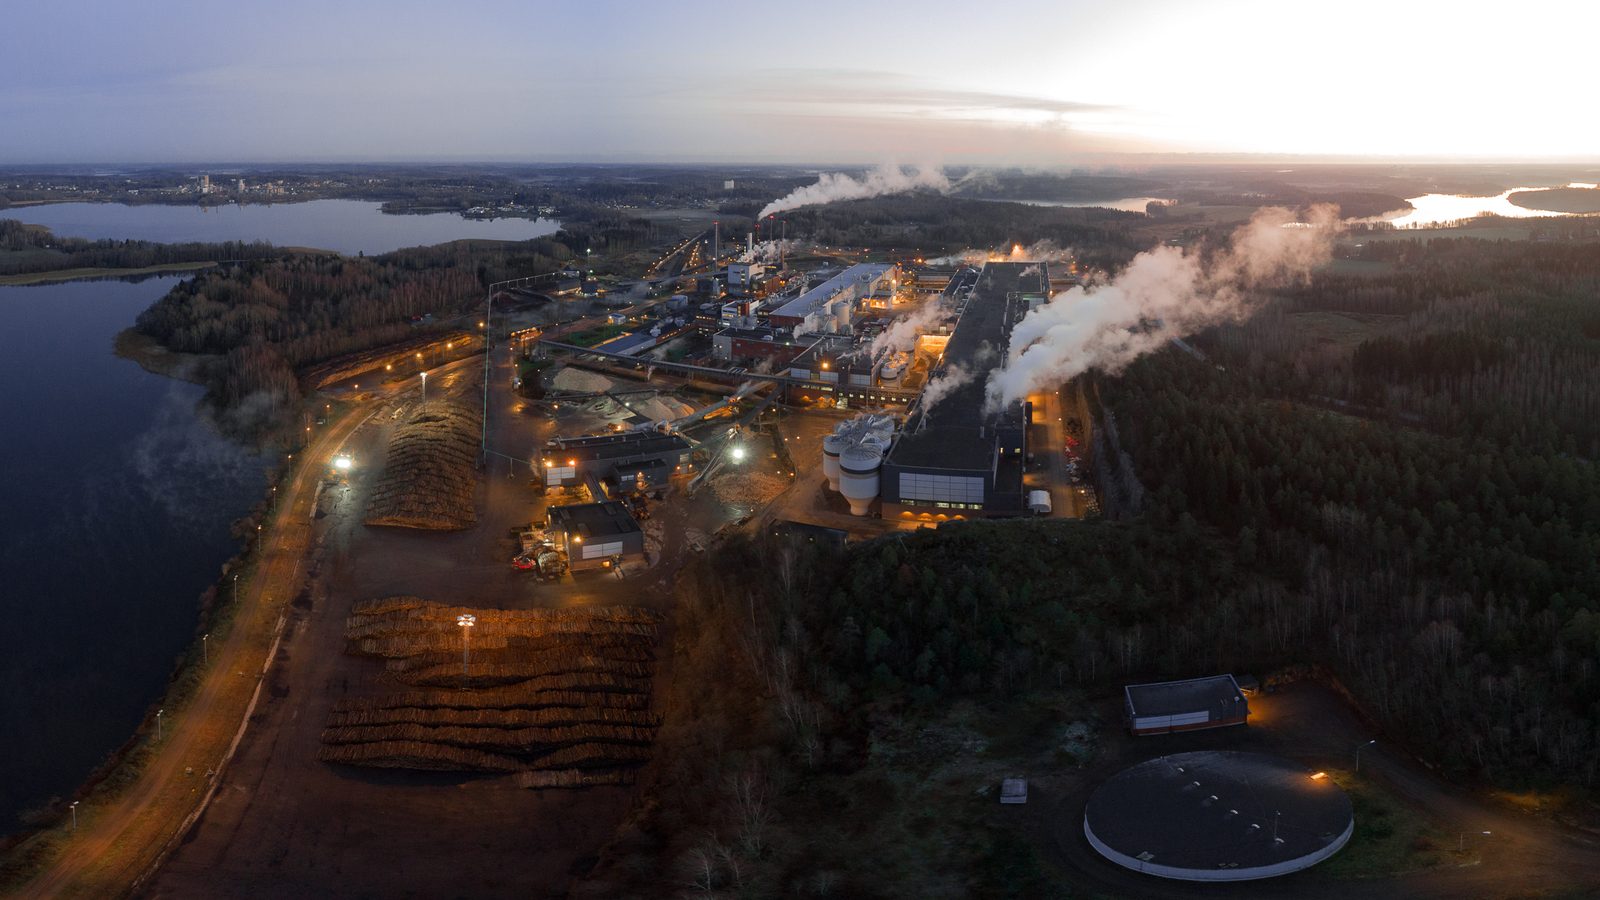
Sappi

Sappi's fourth quarter of fiscal 2026 (July-September 2026) was weak on every key line: revenue of $1,322m, EBITDA of $34m (2.6% margin), an operating loss of $56m and a net loss of $116m (-8.8% margin). Net debt rose from $1.9bn to $1.9bn at 30 September 2026, while operating cash flow stayed negative at minus $10m against capital expenditure of $48m. Our conclusion: the share is rather unattractive – with a loss and debt 57 times quarterly EBITDA, there is no margin of safety in the valuation. Our view: the share is rather unattractive at the current price.

Our view: is there upside

Our view in numbers

MetricOur read
VerdictRather unattractive
Upside on the portal modelno portal model for this share
Strongest case forA market capitalisation of $387m against quarterly revenue of $1.3bn means the market values the company very low, and any recovery in EBITDA could lead to a rapid share price rise.
Strongest case againstDebt of $1.9bn against quarterly EBITDA of $34m implies leverage of 57 times, and with negative cash flow the company cannot service it without new borrowing.
What would change the viewThe verdict would move one step up if quarterly EBITDA sustainably exceeded $100m – that would bring the debt-to-EBITDA ratio below 20 times and restore market confidence.

Key takeaways

— Revenue of $1,322m was almost flat year on year, but EBITDA collapsed to $34m at a 2.6% margin

— An operating loss of $56m and a net loss of $116m mark the third consecutive loss-making quarter

— Debt of $1.9bn against quarterly EBITDA of $34m implies leverage of 57 times

— Operating cash flow of minus $10m does not cover capital expenditure of $48m

— Return on equity of -27.3% with a market capitalisation of $387m means the market values the company below book value

— No dividends were paid, and with the current loss there is no basis for payouts

Key figures, USD bn

Metric—Q3 2026Change
Revenue—1.32—
EBITDA—0.03—
Operating profit—-0.06—
Net profit—-0.12—
Operating cash flow—-0.01—
Capex—0.05—
EBITDA margin—2.6%—
Net margin—-8.8%—

Revenue of $1,322m was almost flat year on year, but EBITDA collapsed to $34m at a 2.6% margin

Revenue in the fourth quarter of fiscal 2026 was $1,322m, down 5.6% from $1,363m a year earlier. The decline is modest but continues a pattern: a 1.0% fall in the first quarter of 2026, 1.0% growth in the second, and a decline again in the reported quarter.

More important, with revenue almost flat, EBITDA fell to $34m – a 2.6% margin. A year earlier in the same quarter EBITDA was $210m at a margin of around 15%. Such a gap cannot be explained by sales volumes alone: it points to a sharp squeeze in prices or a rise in costs that could not be passed on to customers.

The operating loss reached $56m and the net loss $116m. For a company with quarterly revenue above $1.3bn, this means fixed costs and depreciation are consuming the entire gross profit. Until revenue starts growing and the margin recovers, quarterly losses will remain the norm.
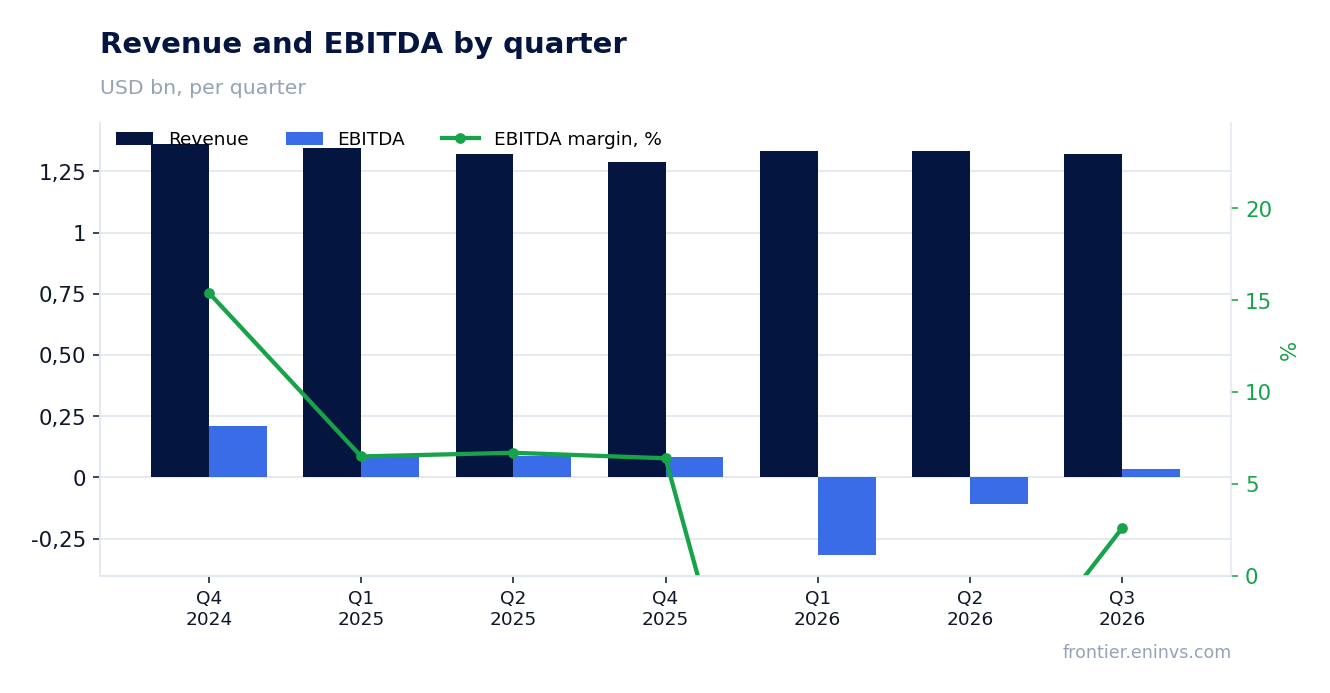
Revenue and EBITDA by quarter

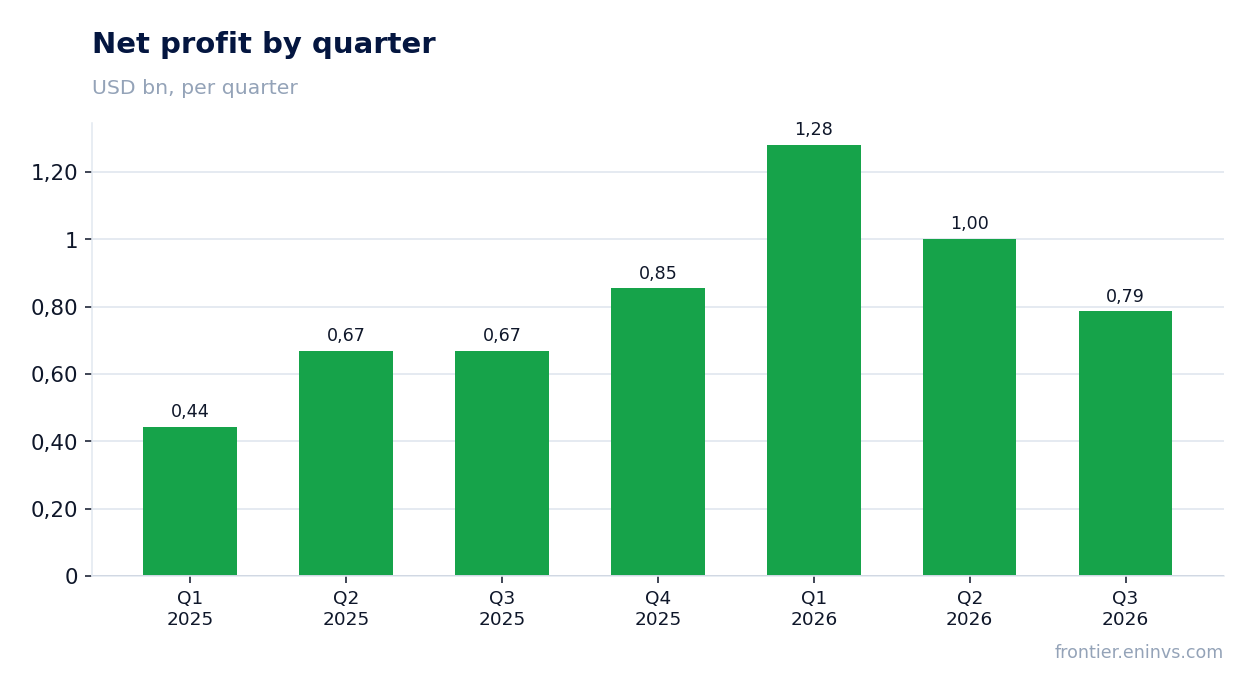
An operating loss of $56m and a net loss of $116m mark the third consecutive loss-making quarter

The loss is not a one-off: in the first quarter of 2026 EBITDA was minus $318m, in the second minus $108m, and only in the reported quarter did it turn positive at $34m. The operating result has been negative for three consecutive quarters: minus $422m, minus $203m and minus $56m respectively.

The net loss of $116m is smaller than the operating loss, which points to a positive contribution from financial or tax items, but it does not change the picture: the company is losing money at the operating level. Return on equity of -27.3% confirms that shareholders' capital is being eroded.

For an investor, the key point is that the loss is not one-off. Three consecutive quarters of negative EBITDA and operating losses mean the problem is structural – either Sappi's product prices have fallen below cost or costs have risen irreversibly.
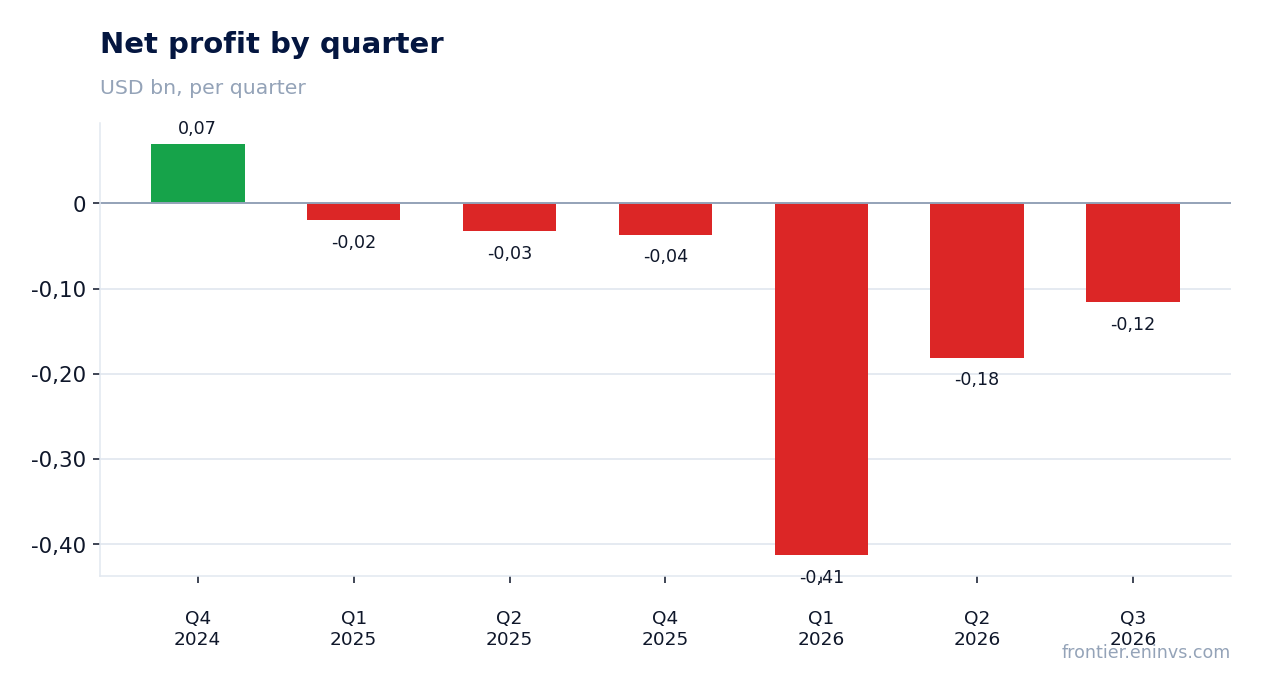
Net profit by quarter

Debt of $1.9bn against quarterly EBITDA of $34m implies leverage of 57 times

Net debt at 30 September 2026 was $1.9bn – the same as at 30 June 2026 and $0.1bn more than a year earlier ($1.8bn at 30 June 2025). Debt is not growing catastrophically, but it is large relative to the company's ability to service it.

With quarterly EBITDA of $34m, the debt-to-EBITDA ratio is roughly 57 times – a figure that for an industrial company means current earnings will not even cover interest. Trailing twelve-month EBITDA is not disclosed in the facts, but three consecutive loss-making quarters make the annual picture no better than the quarterly one.

High debt limits options: the company cannot invest in growth without new borrowing, and rising rates make debt service even more expensive. Until EBITDA recovers to a level comparable with the debt, financial stability remains in question.
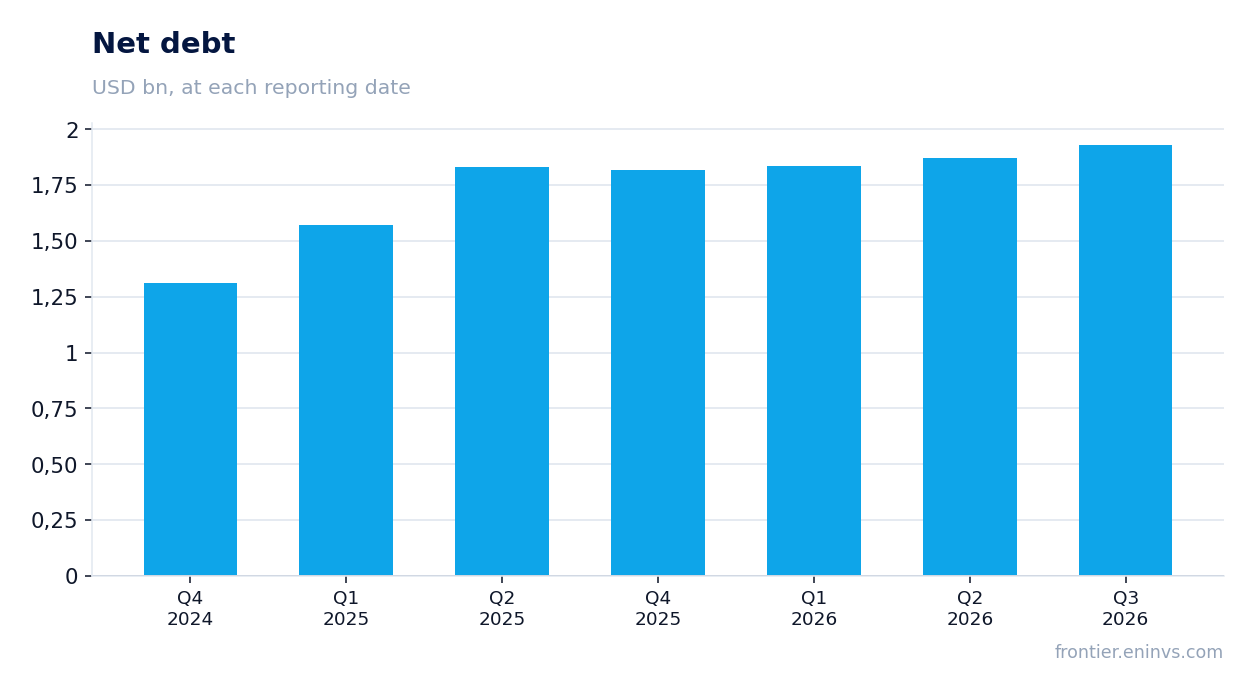
Net debt at reporting dates

Operating cash flow of minus $10m does not cover capital expenditure of $48m

Operating cash flow in the reported quarter remained negative at minus $10m. This means the company is not generating cash from core operations, even despite positive EBITDA of $34m: part of the profit is likely going into working capital or interest payments.

Capital expenditure was $48m, and it is financed not from operating cash flow but from new borrowing or existing reserves. Over the last twelve months operating cash flow was only $60m – insufficient to cover even annual capital expenditure, which in some quarters reached $182m.

Negative free cash flow is the main risk for shareholders: the company is forced to borrow to sustain production, and debt will rise if EBITDA does not recover.

Return on equity of -27.3% with a market capitalisation of $387m means the market values the company below book value

Return on equity of -27.3% is the direct result of losses: shareholders' equity is shrinking, and the market reflects this. With a market capitalisation of $387m and net debt of $1.9bn, enterprise value is around $2.3bn.

The ratio of EV to quarterly EBITDA of $34m gives a multiple that makes no sense for valuation: $2.3bn divided by $34m is about 68. For comparison, normal multiples for industrial companies are 5-10. This means the market either expects EBITDA to recover or values the company's assets below their book value.

The loss and negative return on equity make the company unattractive to investors seeking stable income. Restoring profitability will require either higher product prices or lower costs – both scenarios take time.

No dividends were paid, and with the current loss there is no basis for payouts

Over the last twelve months Sappi paid no dividends. With a net loss of $116m for the quarter and negative operating cash flow, paying a dividend would only be possible through new borrowing, which would increase already high debt.

For an investor this means the share provides no current income. All value is concentrated in the expectation of a profit recovery, but three consecutive loss-making quarters and $1.9bn of debt make that scenario uncertain.

Until the company returns to profit and positive free cash flow, there will be no dividends. This is another argument against the share at the current level.

Valuation on the latest reported figures

MetricValue
Market cap0.39 bn USD
P/B0.23
Operating cash flow (LTM)0.06 bn
ROE-27.3%

Bottom line

The quarter showed that Sappi is in a difficult position: revenue was almost flat, but EBITDA fell to $34m and the net loss was $116m. Debt of $1.9bn against such EBITDA implies leverage of 57 times, and negative operating cash flow does not cover capital expenditure. The only thing that could change the situation is a recovery in product prices or cost cuts, but both scenarios look distant for now. Our conclusion: the share is rather unattractive – with a loss and debt 57 times quarterly EBITDA, there is no margin of safety in the valuation. Our view: the share is rather unattractive at the current price.
Vodacom: profit nearly quadrupled, but most of it is one-off items, not telecoms

VOD →
Vodacom

On 25 November Vodacom released its results for the first half of 2026: revenue of ZAR 102.5 bn (+25.6% year on year), operating profit of ZAR 27.6 bn and net profit of ZAR 34.4 bn (+277.3%). The net margin rose to 33.5% from 11.2% a year earlier, but the jump is almost entirely explained by one-off items rather than operating dynamics. Net debt on the balance sheet stands at ZAR 134.0 bn, with net debt to LTM EBITDA at 2.18. Our verdict: rather attractive – on the portal's model the share trades +22% below its fair value. Our view: the share is rather attractive at the current price; upside on the portal model +22%.

Our view: is there upside

Our view in numbers

MetricOur read
VerdictRather attractive
Upside on the portal model+22%
How the model worksfundamental value-creation model: EBITDA growth times the target multiple, against market cap
Dividend yield, 12m4.1%
Net debt / EBITDA2.18 – moderate leverage
Strongest case forOn the portal's model the share is 22% below fair value, offering a margin of upside.
Strongest case againstNet profit of ZAR 34.4 bn is almost entirely due to one-off items, and debt rose to ZAR 134.0 bn, making the P/E of 7.48 deceptively low.
What would change the viewIf in the next report revenue continues to grow at a double-digit pace without new acquisitions and debt starts to decline, the verdict could rise to attractive.

Key takeaways

— Revenue rose 25.6% to ZAR 102.5 bn, a rare pace for a telecom operator

— Net profit jumped 277.3%, but most of it came from one-off items rather than telecoms

— The 33.5% net margin is deceptive: a year earlier it was 11.2%

— Net debt rose from ZAR 55.0 bn on 30 September 2025 to ZAR 134.0 bn on 30 September 2026

— Net debt to LTM EBITDA stands at 2.18, a moderate level for a telecom

— Trailing twelve-month dividend yield is 4.14%, below the key rate

— On the portal's model the share is 22% below fair value, and that is the main argument for it

Key figures, ZAR bn

MetricH1 2025H1 2026Change
Revenue81.6103+25.6%
EBITDA30.4——
Operating profit18.427.6+50.0%
Net profit9.1134.4+277.3%
Operating cash flow20.830.9+48.7%
Capex11.0-14.6-232.8%
EBITDA margin37.3%——
Net margin11.2%33.5%+22.3 pp

Revenue rose 25.6% to ZAR 102.5 bn, a rare pace for a telecom operator

Revenue for the first half of 2026 was ZAR 102.5 bn, 25.6% more than a year earlier. For a mature telecom operator such growth is the exception, not the rule: telecom revenue usually grows by a few percent a year. The acceleration may be tied to consolidation of acquired assets or to one-off income, but the provided facts do not disclose the cause.

Operating profit for the same period was ZAR 27.6 bn. Against revenue of ZAR 102.5 bn that gives an operating margin of about 27%, which looks normal for a telecom. Net profit of ZAR 34.4 bn, however, exceeds operating profit, which is only possible with large income below the operating line – for example, from asset sales or revaluations.

Revenue growth of a quarter is a strong signal, but it is not confirmed as organic. If it came from acquisitions, then the debt that rose to ZAR 134.0 bn is the price of that growth. The next report will show whether the pace holds without new purchases.

Net profit jumped 277.3%, but most of it came from one-off items rather than telecoms

Net profit for the first half of 2026 was ZAR 34.4 bn against roughly ZAR 9.1 bn a year earlier – growth of 277.3%. Operating profit was ZAR 27.6 bn, meaning net profit exceeded operating profit by ZAR 6.7 bn. The difference arose below the operating line: either from asset sales, revaluation or a tax gain.

The net margin of 33.5% against 11.2% a year earlier is not the result of improved operating efficiency. The operating margin stayed at about 27%, and the jump in the net margin is entirely explained by items below operating profit. Without them, profit would be closer to ZAR 27–28 bn and growth would be more modest.

What matters for assessing the sustainability of the business is operating profit, and it did not grow as dramatically as net profit. One-off income will not repeat in the next half-year, and net profit will likely return to a level close to operating profit. That is the key risk for those looking at the P/E of 7.5 – it is calculated on one-off profit.

The 33.5% net margin is deceptive: a year earlier it was 11.2%

A net margin of 33.5% looks exceptionally high for a telecom. But it reflects one-off income, not operating efficiency. The operating margin for the same period is about 27%, and it did not see such a jump.

Excluding one-off items, the net margin would be closer to 27%, which is still above last year's 11.2%. But growth from 11.2% to 27% is also a significant improvement and requires explanation. Perhaps a year earlier there were large one-off charges that lowered the comparison base. Without disclosure of these items in the facts, we can only state that profit grew unevenly.

For an investor the sustainable margin level matters. If one-off income does not repeat, the net margin will return to a level determined by operating profit and interest. With debt of ZAR 134.0 bn, interest expense will be substantial and will cap the net margin.

Net debt rose from ZAR 55.0 bn on 30 September 2025 to ZAR 134.0 bn on 30 September 2026

Net debt on 30 September 2026 was ZAR 134.0 bn against ZAR 55.0 bn on 30 September 2025 – an increase of ZAR 79.0 bn over the year. Over the half-year, from 31 March 2026, debt rose from ZAR 41.0 bn to ZAR 134.0 bn, i.e. by ZAR 93.0 bn. Such a rise in debt is the main counterargument to the profit growth story.

Net debt to LTM EBITDA stands at 2.18. That is a moderate level for a telecom, but it is calculated on an EBITDA base that includes one-off income. Excluding one-off items, the ratio would be higher. In addition, a ZAR 79.0 bn increase in debt over the year means a significant part of revenue and profit may go to servicing debt.

Operating cash flow for the first half of 2026 was ZAR 30.9 bn, capital expenditure ZAR 14.6 bn. Free cash flow before interest and dividends is about ZAR 16.3 bn. That is not enough to cover the ZAR 93.0 bn increase in debt over the half-year, meaning debt rose not only from operations but also from acquisitions or payouts.

Net debt to LTM EBITDA stands at 2.18, a moderate level for a telecom

Net debt to LTM EBITDA stands at 2.18. For a telecom this is an acceptable level: operators typically run with debt of 2–3x EBITDA. It is important, however, that LTM EBITDA of ZAR 61.5 bn includes one-off income that will not repeat.

Excluding one-off items, EBITDA would be lower and the debt-to-EBITDA ratio would be above 2.18. With debt of ZAR 134.0 bn and sustainable EBITDA of, say, ZAR 50 bn, the ratio would already be 2.7. That is still manageable, but the cushion is smaller.

Interest expense on such debt will be significant. At an average rate of, say, 8–10% a year, debt service would cost ZAR 10–13 bn a year, eating a noticeable part of operating profit. That limits room for dividend growth and investment.

Trailing twelve-month dividend yield is 4.14%, below the key rate

Trailing twelve-month dividend yield is 4.14%. That is a modest level for a market where the key rate is higher. A yield below the rate means the investor receives less current income than from risk-free instruments and is counting on capital growth.

Dividend payments are funded from free cash flow. In the first half of 2026 operating cash flow was ZAR 30.9 bn, capital expenditure ZAR 14.6 bn, free flow about ZAR 16.3 bn. That is enough to pay dividends, but the ZAR 93.0 bn increase in debt over the half-year suggests the company is actively investing or acquiring assets, which may limit future payouts.

Our estimate for the current year's dividend is a yield of about 4.1–4.2% based on the current price and recent payments. However, if one-off income does not repeat, profit and free flow will decline and the dividend may be smaller. The key risk is rising debt and interest expense, which could force the company to cut payouts.

On the portal's model the share is 22% below fair value, and that is the main argument for it

On the portal's model, which values value creation through EBITDA growth and a target multiple, the fair value of the share is 22% above the current price. This is our own calculation, not a market consensus. It relies on sustainable EBITDA growth and the current valuation.

The current LTM P/E is 7.48, EV/EBITDA 6.25. For a telecom these are not high values, but they are calculated on profit and EBITDA that include one-off income. Excluding one-off items, the multiples would be higher and the undervaluation would be less than 22%.

Return on equity is 56.5%, which is very high. However, that level is achieved largely through one-off profit and high debt, which increases financial leverage. Sustainable ROE without one-off items would be lower, but still attractive for a telecom.

Valuation on the latest reported figures

MetricValue
Market cap343 bn ZAR
P/E (LTM)7.5
EV/EBITDA (LTM)6.2
P/B3.71
Net debt / EBITDA (LTM)2.18
Operating cash flow (LTM)66.1 bn
ROE56.5%
Dividend yield (12m)4.1%

Bottom line

The strong point of the report was revenue growth of 25.6% to ZAR 102.5 bn – an exceptional pace for a telecom. However, net profit of ZAR 34.4 bn and a margin of 33.5% are almost entirely due to one-off items rather than operations. Debt rose to ZAR 134.0 bn, and although the debt-to-EBITDA ratio of 2.18 looks moderate, it is calculated on one-off profit. The dividend yield of 4.14% is below the key rate and does not compensate for the risks. Our verdict: rather attractive – on the portal's model the share is +22% below fair value, but that cushion may shrink if one-off income does not repeat. Our view: the share is rather attractive at the current price; upside on the portal model +22%.

Pick n Pay: EBITDA up 10.6%, but leverage at 5.66x EBITDA eats the profit

PIK →
Pick n Pay

Pick n Pay's first-half 2026 results were mixed: revenue rose 2.7% to ZAR 61,956m, EBITDA grew 10.6% to ZAR 2,466m, and the margin improved from 3.7% to 4.0%. The company still posted a loss of ZAR 270m, though a year earlier the loss was twice as large. Net debt at 30 August 2026 stood at ZAR 8,735m, or 5.66x trailing-twelve-month EBITDA, while operating cash flow for the half was ZAR 4,252m against capex of ZAR 710m. Our conclusion: rather unattractive – on the portal's model the share trades 61% above fair value. Our view: the share is rather unattractive at the current price; upside on the portal model -61%.

Our view: is there upside

Our view in numbers

MetricOur read
VerdictRather unattractive
Upside on the portal model-61%
How the model worksfundamental value-creation model: EBITDA growth times the target multiple, against market cap
Net debt / EBITDA5.66 – high leverage
Strongest case forEBITDA rose 10.6% to ZAR 2,466m and the margin improved from 3.7% to 4.0% – operating efficiency is improving.
Strongest case againstOn the portal's model fair value is 61% below the current price, and leverage at 5.66x EBITDA leaves no margin of safety.
What would change the viewThe verdict would move one step up if net debt starts falling from ZAR 8,735m while EBITDA sustains growth near 10%.

Key takeaways

— Revenue rose 2.7%, enough to lift EBITDA 10.6% as the margin improved from 3.7% to 4.0%

— The loss halved to ZAR 270m, but interest on ZAR 8,735m of debt still swallows operating profit of ZAR 490m

— Leverage at 5.66x trailing-twelve-month EBITDA is a level at which profit stays negative

— Operating cash flow of ZAR 4,252m for the half against capex of ZAR 710m covers interest but leaves no room for dividends

— Net debt rose from ZAR 5.1bn on 31 August 2025 to ZAR 8.7bn on 30 August 2026 – an increase of ZAR 13.8bn over the year

— On the portal's model fair value is 61% below the current price – the market is pricing a recovery the report does not yet show

Key figures, ZAR bn

MetricH1 2025H1 2026Change
Revenue60.362.0+2.7%
EBITDA2.232.47+10.6%
Operating profit0.310.49+58.1%
Net profit-0.50-0.27—
Operating cash flow2.934.25+45.3%
Capex0.900.71-20.8%
EBITDA margin3.7%4.0%+0.3 pp
Net margin-0.8%-0.4%+0.4 pp

Revenue rose 2.7%, enough to lift EBITDA 10.6% as the margin improved from 3.7% to 4.0%

Revenue for the first half of 2026 was ZAR 61,956m, up 2.7% year on year. Growth is modest but present against weak South African consumer demand. Crucially, it came with better profitability: EBITDA rose 10.6% to ZAR 2,466m, faster than revenue.

The EBITDA margin improved from 3.7% to 4.0%. This means the company either cut costs or improved its sales mix. The report does not break out specific cost lines, but the fact that the margin rose on modest revenue growth points to better operating efficiency.

Operating profit was ZAR 490m – positive but small relative to revenue. Even after all operating costs the business earns money, but not much. The main problem sits below the operating line – in interest on debt.

The loss halved to ZAR 270m, but interest on ZAR 8,735m of debt still swallows operating profit of ZAR 490m

The net loss for the first half of 2026 was ZAR 270m, against a loss twice as large a year earlier. The narrowing is the result of higher EBITDA and possibly lower interest costs, though the exact driver is not disclosed in the facts.

Operating profit of ZAR 490m is positive, but interest on ZAR 8,735m of debt likely exceeds that amount. That is why the company remains loss-making. Leverage at 5.66x trailing-twelve-month EBITDA is a high level at which even a modest rise in rates could widen the loss again.

The net margin improved from -0.8% to -0.4% but remains negative. To turn profitable the company needs either a significant reduction in debt or a sharp increase in operating profit.

Leverage at 5.66x trailing-twelve-month EBITDA is a level at which profit stays negative

Net debt at 30 August 2026 was ZAR 8,735m. The ratio of net debt to trailing-twelve-month EBITDA is 5.66. That is a high level: at such leverage the company spends a significant part of operating profit servicing debt.

The debt trajectory is concerning: net debt was ZAR 5.1bn on 31 August 2025, meaning it rose by ZAR 13.8bn over the year. Rising debt on modest revenue growth means the company is funding its operations and investment with borrowed money.

EV/EBITDA for the trailing twelve months is 10.09. This valuation implies the market expects a profit recovery. But with current leverage and negative net profit, the multiple looks high.

Operating cash flow of ZAR 4,252m for the half against capex of ZAR 710m covers interest but leaves no room for dividends

Operating cash flow for the first half of 2026 was ZAR 4,252m. Capital expenditure was ZAR 710m. Free cash flow is therefore positive and exceeds ZAR 3.5bn, enough to cover interest costs.

However, this flow is not enough to reduce debt: net debt rose by ZAR 13.8bn over the year. This means the company is either funding investment and working capital with new borrowings or paying dividends not covered by free cash flow.

Dividends are not disclosed in the facts, so we cannot say whether they were paid or not. But with negative net profit and high leverage, dividend sustainability is in question.

Net debt rose from ZAR 5.1bn on 31 August 2025 to ZAR 8.7bn on 30 August 2026 – an increase of ZAR 13.8bn over the year

Net debt rose from ZAR 5.1bn on 31 August 2025 to ZAR 8.7bn on 30 August 2026. An increase of ZAR 13.8bn over the year is a significant rise in leverage that needs explaining.

Such debt growth on modest revenue growth and positive operating cash flow means the company is either investing heavily or covering losses with borrowings. Part of the increase may relate to working capital or seasonality, but the facts do not disclose the cause.

For an investor this is a signal: leverage is growing faster than the business. The net debt to EBITDA ratio is currently 5.66, but if the current trend continues it could rise further.

On the portal's model fair value is 61% below the current price – the market is pricing a recovery the report does not yet show

On the portal's model, which compares EBITDA growth with a target multiple and market capitalisation, fair value is 61% below the current price. This is our own estimate, not a market consensus.

The company's market capitalisation is ZAR 18,639m, and EV/EBITDA for the trailing twelve months is 10.09. At this valuation the market expects a significant profit recovery and deleveraging. But current results do not show rapid improvement: revenue is growing 2.7% and net profit is negative.

A negative upside of 61% is a strong signal that the share is overvalued relative to fundamentals. Even allowing for a possible future profit recovery, the current price leaves no margin of safety.

Valuation on the latest reported figures

MetricValue
Market cap18.6 bn ZAR
EV/EBITDA (LTM)10.1
P/B1.95
Net debt / EBITDA (LTM)5.66
ROE-4.6%

Bottom line

The strong part of the report is 10.6% EBITDA growth and a margin improvement to 4.0% on modest revenue growth. However, a ZAR 270m loss and leverage at 5.66x EBITDA show that operating improvement is not enough to turn profitable. A ZAR 13.8bn increase in net debt over the year is a warning sign. On the portal's model the share is 61% overvalued, and that outweighs the positive margin trends. Our conclusion: rather unattractive – on the portal's model the share trades 61% above fair value. Our view: the share is rather unattractive at the current price; upside on the portal model -61%.

AngloGold Ashanti: gold rose 23% but EBITDA fell 6% – volumes and costs ate the price

ANG →
AngloGold Ashanti

On 11 November AngloGold Ashanti reported results for the third quarter of 2026. The average gold price in the period was 4,268 USD/oz versus 3,459 USD a year earlier (+23.4%), yet revenue rose only 8.4% to 2,619 mn USD and EBITDA fell 6.2% to 1,313 mn USD. At year-ago volumes and costs and this period's price, our calculation puts EBITDA at 1,965.5 mn USD – the company earned 652.5 mn USD less, and the gap is explained by volumes and unit costs. Our conclusion: the share is fairly valued – the portal model shows only +5% upside to fair value. Our view: the share is fairly valued; upside on the portal model +5%.

Our view: is there upside

Our view in numbers

MetricOur read
VerdictNeutral
Upside on the portal model+5%
How the model worksspot model: EBITDA re-priced to current commodity prices at the target EV/EBITDA, against market cap
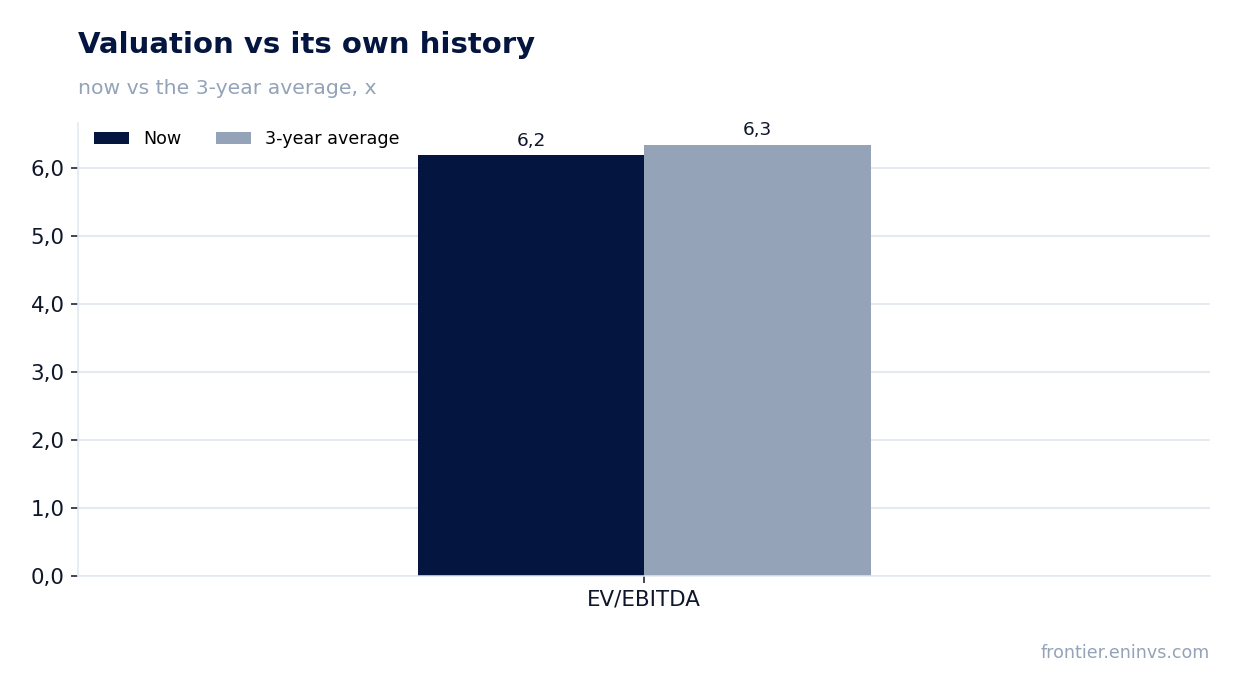
EV/EBITDA now and 3-year average6.2 vs 6.3 – in line with its history
Dividend yield, 12m4.8%
Net debt / EBITDA-0.20 – net cash
Strongest case forNet cash of 1.5 bn USD and a 4.8% dividend yield at a payout ratio of about 58% of LTM profit of 3,925 mn USD give the holder a steady income with no debt risk.
Strongest case againstEBITDA is 33.2% below the calculation at year-ago volumes and costs, and the margin compressed to 50.1% from 57.9% – the company is not fully earning on the higher gold price.
What would change the viewGold holding above 4,268 USD/oz with a recovery in production volumes would lift the verdict one step; spot falling below 4,048 USD would lower it one step.

Key takeaways

— Gold averaged 4,268 USD/oz in the quarter – 23.4% above a year earlier but already 5.5% below the previous quarter

— At year-ago volumes and costs, our calculation puts EBITDA at 1,965.5 mn USD – reported 1,313 mn is 33.2% below that

— Revenue grew only 8.4% year on year, decelerating from 27.0% in the second quarter – the gold price did not reach the top line in full

— The EBITDA margin compressed to 50.1% from 57.9% a year earlier – higher unit costs and lower volumes outweighed the metal's rise

— Net cash rose to 1.5 bn USD from 0.2 bn a year earlier, and free cash flow stays positive with capex of 497 mn USD in the quarter

— The trailing 12-month dividend yield is 4.8%, supported by LTM profit of 3,925 mn USD at a P/E of 12.1

— EV/EBITDA LTM of 6.2 is essentially level with its three-year average of 6.3 – the market gives neither a discount nor a premium for current earnings

Key figures, USD bn

MetricQ3 2025Q3 2026Change
Revenue2.422.62+8.4%
EBITDA1.401.31-6.2%
Operating profit1.091.19+8.4%
Net profit0.670.79+17.6%
Operating cash flow1.421.38-2.7%
Capex0.340.50+45.3%
EBITDA margin57.9%50.1%-7.8 pp
Net margin27.7%30.0%+2.3 pp

Gold averaged 4,268 USD/oz in the quarter – 23.4% above a year earlier but already 5.5% below the previous quarter

The average gold price in the third quarter of 2026 was 4,268 USD/oz versus 3,459 USD a year earlier – a rise of 23.4%. This is the main external driver of revenue: gold accounts for 100% of the company's sales in the portal model.

Against the previous quarter the metal fell 5.5%, from 4,514 USD to 4,268 USD. Spot gold on 11 November 2026 is 4,048 USD, another 5.2% below the reported-period average. The price backdrop has thus deteriorated for a second consecutive quarter.

For a producer this means quarterly revenue and profit were earned at a price above today's. The next report will come at a lower metal price unless spot recovers.

Commodity prices: period average and now

BenchmarkYear agoQ3 2026YoYSpot 2026-11-11
Gold, USD3 4594 268+23,4%4 048
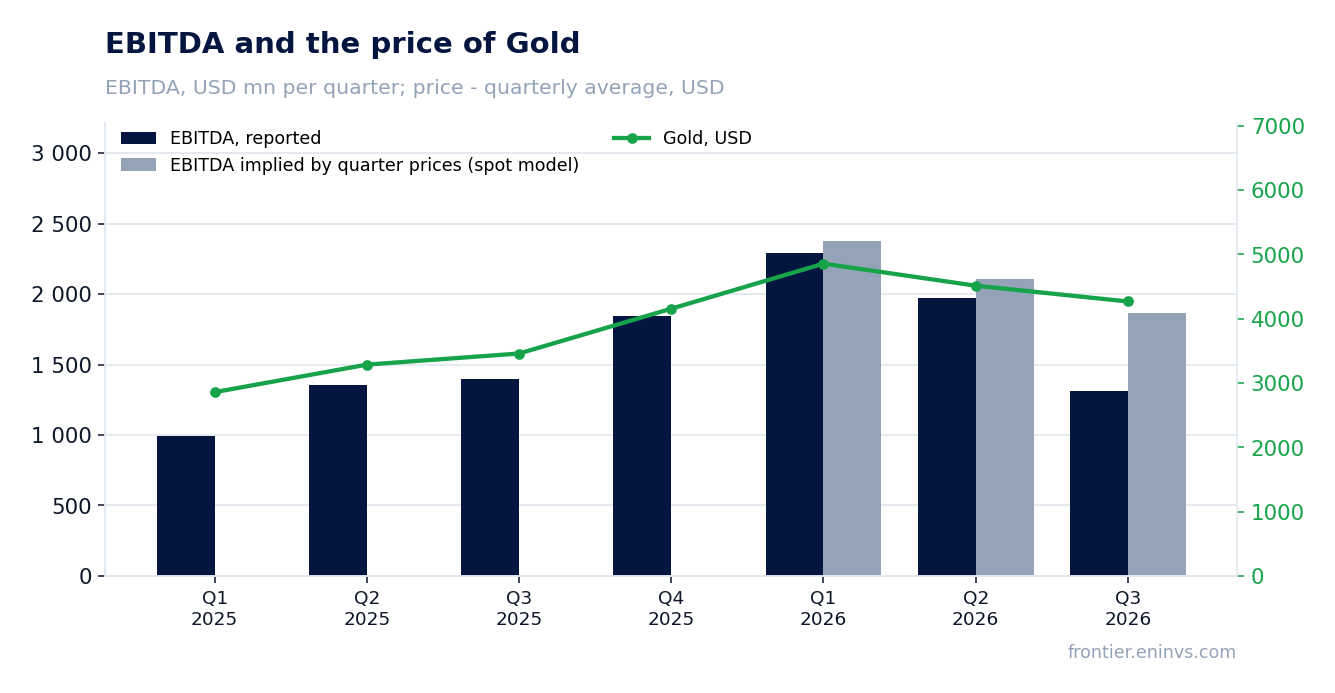
EBITDA and the commodity price by quarter

At year-ago volumes and costs, our calculation puts EBITDA at 1,965.5 mn USD – reported 1,313 mn is 33.2% below that

Holding third-quarter 2025 volumes and non-commodity costs and moving only the gold price to the reported period gives revenue of 2,982.5 mn USD and EBITDA of 1,965.5 mn USD. The price effect alone would have added 565.5 mn USD to revenue.

In fact the company booked revenue of 2,619 mn USD – 363.5 mn USD below the calculation – and EBITDA of 1,313 mn USD, 652.5 mn USD lower. The 33.2% EBITDA gap means the metal price was eaten by lower sales volumes and higher unit costs.

The picture versus the previous quarter is similar: at second-quarter volumes and costs EBITDA should have been 1,804.6 mn USD, and the reported figure is 27.2% below. The portal's spot model, built from the average of the previous four quarters, expected EBITDA of 1,867.3 mn USD – actual is 29.7% below. The model's deviation in the two prior periods was far smaller – 3.8% and 6.3%.

What the prices implied and what the company earned

Base (Q3 2025)Implied at period pricesReportedReported vs implied
Revenue, USD mn2 4172 9822 619-12,2%
EBITDA, USD mn1 4001 9661 313-33,2%
EBITDA, portal spot model, USD mn—1 8671 313-29,7%
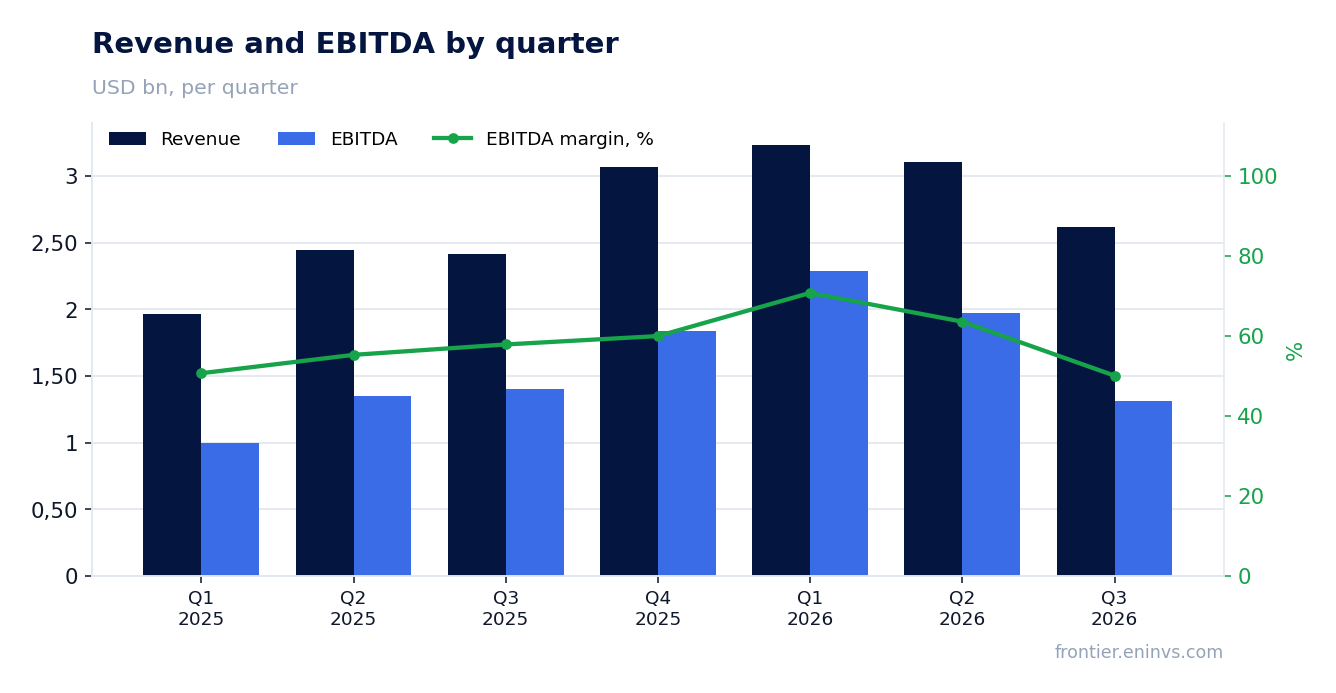
Revenue and EBITDA by quarter

Revenue grew only 8.4% year on year, decelerating from 27.0% in the second quarter – the gold price did not reach the top line in full

Third-quarter 2026 revenue was 2,619 mn USD, 8.4% above the year-ago level. That is a marked deceleration: growth was 27.0% in the second quarter and 64.8% in the first.

With gold up 23.4%, revenue should have grown faster. The shortfall means volumes sold in ounces fell year on year and the realised price came in below the market average. The data provided give no exact production or sales figures, so we state only what is visible: revenue growth is a third of the price move.

Against the previous quarter revenue fell: 2,619 mn USD versus 3,104 mn USD in the second quarter. Both the 5.5% price decline and lower volumes contributed.

The EBITDA margin compressed to 50.1% from 57.9% a year earlier – higher unit costs and lower volumes outweighed the metal's rise

The EBITDA margin in the reported quarter was 50.1% versus 57.9% a year earlier. A 7.8 percentage-point drop while gold rose 23.4% is a strong signal: costs per ounce rose faster than the price.

EBITDA of 1,313 mn USD is made up of operating profit of 1,187 mn USD and depreciation of 126 mn USD. Operating profit fell faster than revenue year on year, confirming cost pressure. The materials provided give no exact cash cost or AISC figures, so we name only the direction: unit costs rose.

Net profit, by contrast, rose 17.6% to 787 mn USD and the net margin to 30.0% from 27.7%. The divergence from EBITDA is explained by items below operating profit – interest, FX and other income – which are not part of EBITDA.

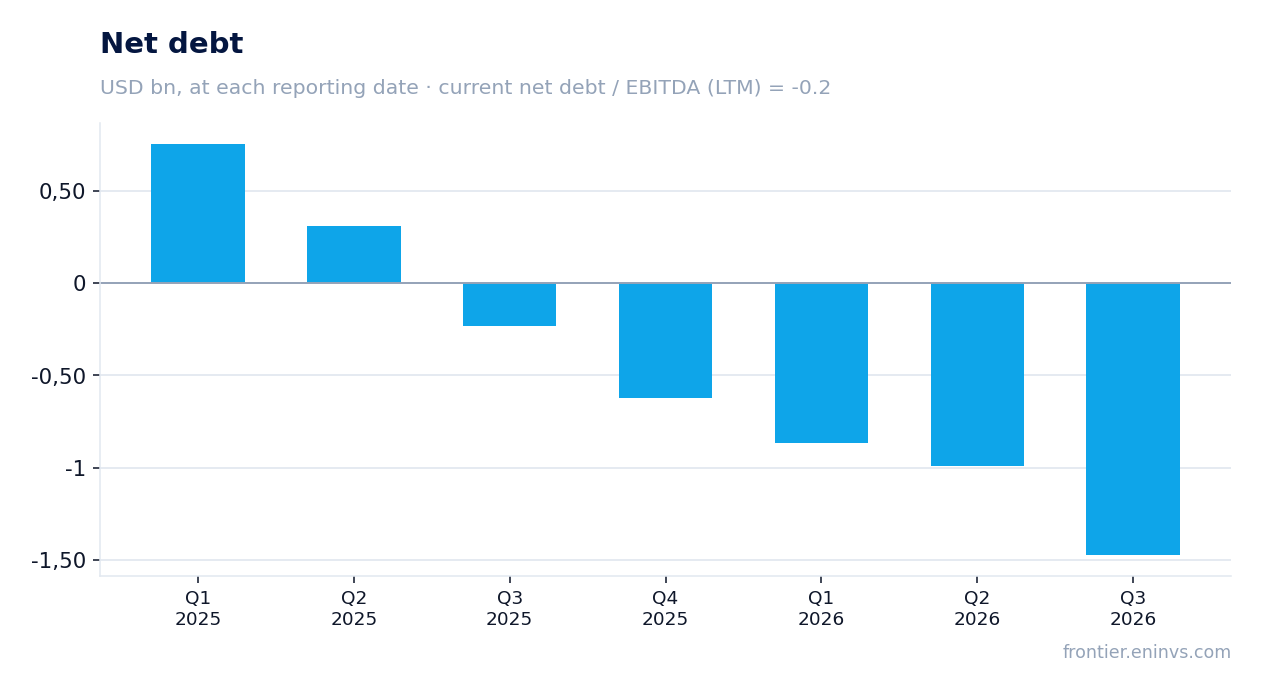
Net debt at reporting dates

Net cash rose to 1.5 bn USD from 0.2 bn a year earlier, and free cash flow stays positive with capex of 497 mn USD in the quarter

As of 30 September 2026 the company has net cash of 1.5 bn USD versus 0.2 bn USD on 30 September 2025 – an improvement of 1.2 bn USD over 12 months. At 30 June 2026 the position was 1.0 bn USD, so it grew by 0.5 bn USD in the quarter.

Operating cash flow in the quarter was 1,380 mn USD and capex 497 mn USD. Free cash flow remains comfortably positive, and it is what funds the dividend and further strengthening of the balance sheet.

Net debt to LTM EBITDA is negative at -0.2, reflecting the net cash position. At current gold prices the ratio is -0.21. There is effectively no debt load, and this is the main argument for the sustainability of payouts.

Valuation vs its own history

The trailing 12-month dividend yield is 4.8%, supported by LTM profit of 3,925 mn USD at a P/E of 12.1

The trailing 12-month dividend yield is 4.8%. The company is a dividend name, and the payout rests on LTM profit of 3,925 mn USD and LTM operating cash flow of 6,143 mn USD.

With an LTM P/E of 12.1 and a 4.8% yield, the payout ratio on LTM profit is about 58%. That is a moderate level, leaving room for reinvestment and for maintaining the net cash position.

Our estimate for the current year's dividend assumes LTM profit is sustained and a payout ratio near 58% – about 4.8% yield on the current price. The risk to the payout is a further fall in gold: spot is already 5.2% below the reported-period average, and next quarter's profit will be lower, all else equal.

EV/EBITDA LTM of 6.2 is essentially level with its three-year average of 6.3 – the market gives neither a discount nor a premium for current earnings

The EV/EBITDA LTM multiple is 6.2 versus a three-year average of 6.3 – a deviation of -2%, meaning the stock trades level with its own history. P/E LTM is 12.1 and ROE 34.3%.

At current gold prices the portal's spot model puts EBITDA at 7,170.8 mn USD versus LTM of 6,885 mn USD – 4.2% higher. EV/EBITDA at current prices is 6.4 and net debt to EBITDA is -0.21.

On the portal's model the fair value of the share implies +5% upside to the current price. That is modest: the market has already priced in both the high LTM profit and the strong balance sheet. Reserve life is 11.8 years at the current production rate, which supports the long-term valuation.

Valuation on the latest reported figures

MetricValue
Market cap47.4 bn USD
P/E (LTM)12.1
EV/EBITDA (LTM)6.2
P/B5.86
Net debt / EBITDA (LTM)-0.20
Operating cash flow (LTM)6.14 bn
ROE34.3%
Dividend yield (12m)4.8%
EV/EBITDA, 3-year average6.3
Net profit by quarter

Bottom line

The quarter's strength remains the balance sheet: net cash of 1.5 bn USD and free cash flow of 883 mn USD after capex. But the company failed to capitalise on gold that rose 23.4%: EBITDA is 33.2% below the calculation at year-ago volumes and costs, and the margin compressed to 50.1%. LTM profit of 3,925 mn USD and a 4.8% dividend yield look solid, yet the 6.2 multiple is level with the three-year average of 6.3 and the portal model shows only +5% upside. Our conclusion: the share is fairly valued – the portal model's +5% upside leaves no margin of safety, and a change of view needs either a higher gold price or a recovery in volumes and unit costs. Our view: the share is fairly valued; upside on the portal model +5%.

Redefine: profit up 75% on revenue up 1.8%, and almost all of it is revaluation, not rent

RDF →
Redefine

Redefine's results for the financial year ended 31 August 2026 show revenue of ZAR 11,297.1m (+1.8% YoY), EBITDA of 6,169.9m (+3.8%) and net profit of 7,227.6m (+75.1%). Profit grew 42 times faster than revenue, and the gap is not operational: the net margin rose from 37.2% to 64.0%, meaning a large revaluation of investment property sits inside profit. Leverage is 6.52x LTM EBITDA, the trailing dividend yield is 7.1%, and on the portal's model the share trades 9% below its modelled fair value. Our conclusion: fairly valued – the 9% upside on the portal's model does not offset 6.52x EBITDA leverage and the one-off nature of the profit. Our view: the share is fairly valued; upside on the portal model +9%.

Our view: is there upside

Our view in numbers

MetricOur read
VerdictNeutral
Upside on the portal model+9%
How the model worksfundamental value-creation model: EBITDA growth times the target multiple, against market cap
Dividend yield, 12m7.1%
Net debt / EBITDA6.52 – high leverage
Strongest case forThe 7.1% dividend yield is above the key rate, and net debt fell by ZAR 2.3bn over the year to 40.2bn.
Strongest case againstAlmost all of the 75.1% profit increase came from property revaluation, and 6.52x EBITDA leverage remains high.
What would change the viewIf EBITDA grows above 5% or net debt falls below 6.0x EBITDA, the verdict moves one step up; a property write-down would move it down.

Key takeaways

— Revenue added 1.8%, and that was enough for only 3.8% EBITDA growth – the rental stream barely accelerated

— The net margin jumped from 37.2% to 64.0%, and almost all of the profit increase came from property revaluation, not rent

— The EBITDA margin rose from 53.5% to 54.6% – operating efficiency improved, but its contribution to profit is small

— Net debt fell from ZAR 42.5bn on 31 August 2025 to 40.2bn on 31 August 2026, but leverage remains 6.52x EBITDA

— Operating cash flow of ZAR 4,075.9m against capital expenditure of just 35.1m – the cash is there, but it mostly covers interest and dividends

— The 7.1% dividend yield is above the key rate, but the payout rests on profit inflated by revaluation

— On the portal's model fair value is 9% above the market, and that is too little to call the share attractive with 6.52x EBITDA leverage

Key figures, ZAR bn

MetricFY 2025FY 2026Change
Revenue11.111.3+1.8%
EBITDA5.946.17+3.8%
Operating profit5.916.14+3.8%
Net profit4.137.23+75.1%
Operating cash flow3.474.08+17.5%
Capex—0.04—
EBITDA margin53.5%54.6%+1.1 pp
Net margin37.2%64.0%+26.8 pp

Revenue added 1.8%, and that was enough for only 3.8% EBITDA growth – the rental stream barely accelerated

Revenue for the financial year ended 31 August 2026 was ZAR 11,297.1m, 1.8% more than a year earlier. For a property fund this is modest growth: close to rent indexation and hardly reflecting portfolio expansion.

EBITDA rose 3.8% to ZAR 6,169.9m, faster than revenue. The gap is small, but it shows costs grew slower than income. The EBITDA margin rose from 53.5% to 54.6% – an improvement of 1.1 percentage points.

There is no acceleration in the rental stream: 1.8% revenue growth is a pace that creates no cushion for debt service. The main contribution to profit came not from here but from asset revaluation.

The net margin jumped from 37.2% to 64.0%, and almost all of the profit increase came from property revaluation, not rent

Net profit for the reporting year was ZAR 7,227.6m against roughly 4,127m a year earlier – growth of 75.1%. The net margin rose from 37.2% to 64.0%, meaning profit grew 42 times faster than revenue.

A rental business cannot produce such a gap: EBITDA added only 3.8%. Almost all of the profit increase – about ZAR 3.1bn – came from lines below operating profit, primarily the revaluation of investment property. Operating profit of ZAR 6,135.9m is close to EBITDA, so the core operating result is stable.

For a holder this means earnings per share and the P/E of 6.44 rest on paper income. If revaluation is smaller next year or turns into a write-down, profit will fall even with stable rent.

The EBITDA margin rose from 53.5% to 54.6% – operating efficiency improved, but its contribution to profit is small

An EBITDA margin of 54.6% is high for a property fund and shows operating costs are under control. The 1.1 percentage point improvement added roughly ZAR 124m to EBITDA – a small sum against the ZAR 3.1bn profit increase.

The operating margin is not disclosed separately, but operating profit of ZAR 6,135.9m is only 34m below EBITDA, so depreciation and other operating items are minimal. The whole operating story is in the EBITDA line.

The margin gain is real but marginal for the investment case: it supports the dividend but does not change the valuation. The main question is whether the margin can hold if rent growth stays at 1.8%.

Net debt fell from ZAR 42.5bn on 31 August 2025 to 40.2bn on 31 August 2026, but leverage remains 6.52x EBITDA

Net debt on 31 August 2026 was ZAR 40,243.6m. A year earlier, on 31 August 2025, it was ZAR 42.5bn, so it fell by 2.3bn. Over six months, from 28 February 2026, the decline was 1.7bn – from 41.9bn.

The ratio of net debt to trailing twelve-month EBITDA is 6.52. That is a high level for a property fund: debt equals almost seven years of EBITDA. With EBITDA of ZAR 6,169.9m, debt service absorbs a significant part of operating cash flow.

The 2.3bn reduction over the year is a positive signal, but it does not change the picture: leverage remains above the level many investors consider comfortable. Further reduction requires either EBITDA growth or asset sales.

Operating cash flow of ZAR 4,075.9m against capital expenditure of just 35.1m – the cash is there, but it mostly covers interest and dividends

Operating cash flow for the reporting year was ZAR 4,075.9m. Capital expenditure was minimal at ZAR 35.1m, meaning the fund is barely investing in new construction. Free cash flow before interest and dividends is about ZAR 4.0bn.

That flow covers debt service and dividend payments, but not rapid debt reduction. With net debt of ZAR 40.2bn and EBITDA of ZAR 6,169.9m, even a small rise in rates could eat into free cash flow.

Low capital expenditure means the portfolio is being maintained, not expanded. Revenue growth above 1.8% requires acquisitions, and at the current leverage there is no money for them.

The 7.1% dividend yield is above the key rate, but the payout rests on profit inflated by revaluation

The trailing twelve-month dividend yield is 7.08%. That is above the key rate and above the yield on many bonds, making the share interesting for income investors. The payout for the reporting year, judging by profit, should be no less than last year's.

However, the dividend is covered by profit that is 64.0% revaluation. If revaluation disappears, net profit falls to about ZAR 4.1bn and the payout ratio rises. Our estimate: the dividend for next year may offer a yield of about 7%, but its sustainability depends on revaluation and on the fund's policy.

What could reduce the payout: lower revaluation, higher interest costs with 6.52x EBITDA leverage, or a decision to direct free cash flow to debt reduction. For a holder the dividend is the main argument, but it does not remove the risk of a profit revision.

On the portal's model fair value is 9% above the market, and that is too little to call the share attractive with 6.52x EBITDA leverage

On the portal's model, which compares EBITDA growth with a target multiple, fair value is 9% above the current market price. That is moderate upside that does not offset revaluation risk and high leverage.

The trailing P/E is 6.44, EV/EBITDA is 14.07. The low P/E is deceptive: it rests on profit with revaluation. EV/EBITDA of 14.07 for a property fund with 6.52x EBITDA leverage looks high, and that limits multiple expansion.

The 7.1% dividend yield supports the price, but with 9% upside on the portal's model the cushion is small. A re-rating would require either sustainable EBITDA growth above 3.8% or a reduction in leverage below 6.0x EBITDA.

Valuation on the latest reported figures

MetricValue
Market cap46.5 bn ZAR
P/E (LTM)6.4
EV/EBITDA (LTM)14.1
P/B0.81
Net debt / EBITDA (LTM)6.52
Operating cash flow (LTM)4.08 bn
ROE12.6%
Dividend yield (12m)7.1%

Bottom line

The strong side of the report is operational resilience: EBITDA grew 3.8%, the margin rose to 54.6%, and net debt fell by ZAR 2.3bn over the year. But profit grew 75.1% mainly on revaluation, not rent, which makes the P/E of 6.44 an unreliable guide. The 7.1% dividend yield is attractive, but the payout depends on the same revaluation. On the portal's model the 9% upside is too little to offset 6.52x EBITDA leverage. Our conclusion: fairly valued – the 9% upside on the portal's model does not offset 6.52x EBITDA leverage and the one-off nature of the profit. Our view: the share is fairly valued; upside on the portal model +9%.

TFG: H1 profit fell 12.4% on flat revenue – the share has little room left

TFG →
TFG

On 25 November TFG reported results for the first half of its 2026 financial year: revenue ZAR 29,044.0m, operating profit ZAR 2,143.0m, net profit ZAR 827.0m. Revenue fell 0.4% year on year, net profit 12.4%, and the net margin narrowed to 2.8% from 3.2%. LTM net debt/EBITDA stands at 2.09 and the trailing 12-month dividend yield at 4.93%. Our conclusion: fairly valued – the portal model implies only -5% to fair value. Our view: the share is fairly valued; upside on the portal model -5%.

Our view: is there upside

Our view in numbers

MetricOur read
VerdictNeutral
Upside on the portal model-5%
How the model worksfundamental value-creation model: EBITDA growth times the target multiple, against market cap
Dividend yield, 12m4.9%
Net debt / EBITDA2.09 – moderate leverage
Strongest case forThe 4.93% dividend yield is above the key rate, and leverage at 2.09x LTM EBITDA remains moderate.
Strongest case againstNet profit fell 12.4% on almost flat revenue, and the portal model implies -5% to fair value.
What would change the viewA recovery in the net margin above 3.2% and slower growth in net debt would move the verdict one step up, to rather attractive.

Key takeaways

— Revenue was almost flat in the half – down 0.4% year on year to ZAR 29,044.0m

— Net profit fell 12.4% and the margin narrowed to 2.8% from 3.2% – costs ate into almost flat revenue

— Operating profit of ZAR 2,143.0m on revenue of ZAR 29,044.0m is a 7.4% margin, not enough to hold net profit

— Leverage at 2.09x LTM EBITDA is moderate, but net debt rose from ZAR 8.0bn on 31 March to ZAR 9.1bn

— The 4.93% trailing dividend yield beats the key rate, but the payout rests on falling profit

— On the portal model the share is 5% above fair value – almost no room left

Key figures, ZAR bn

MetricH1 2025H1 2026Change
Revenue29.229.0-0.4%
EBITDA5.43——
Operating profit2.292.14-6.5%
Net profit0.940.83-12.4%
Operating cash flow1.432.29+60.3%
Capex1.070.67-37.3%
EBITDA margin18.6%——
Net margin3.2%2.8%-0.4 pp

Revenue was almost flat in the half – down 0.4% year on year to ZAR 29,044.0m

Revenue for the first half of the 2026 financial year was ZAR 29,044.0m against the comparable period a year earlier – a decline of 0.4%. That is within statistical noise: the company is neither growing nor shrinking.

For an apparel retailer this means like-for-like sales are not offsetting weakness in one of the segments. The report gives no segment breakdown, so the source of the weakness cannot be named – only the total is visible.

Flat revenue with rising costs is the main reason profit fell. When the top line stands still, any increase in rent, logistics or staff costs hits the margin immediately.

Net profit fell 12.4% and the margin narrowed to 2.8% from 3.2% – costs ate into almost flat revenue

Net profit for the half was ZAR 827.0m, 12.4% less than a year earlier. On revenue of ZAR 29,044.0m that gives a margin of 2.8% against 3.2% in the comparable period.

A 0.4 percentage point squeeze in the margin on almost unchanged revenue means costs grew faster than income. Operating profit of ZAR 2,143.0m corresponds to a 7.4% margin – not enough to hold net profit at the previous level.

The report does not single out one-off items that would explain the fall. The pressure on profit is therefore operational, not driven by accounting write-offs.

Operating profit of ZAR 2,143.0m on revenue of ZAR 29,044.0m is a 7.4% margin, not enough to hold net profit

Operating profit for the half was ZAR 2,143.0m. On revenue of ZAR 29,044.0m that is a 7.4% margin – a thin buffer for a retailer with debt.

Interest on debt and taxes are deducted from that, leaving ZAR 827.0m of net profit. The gap between operating and net profit – ZAR 1,316.0m – shows how heavy the financial costs are.

A 7.4% margin means even a small drop in revenue or rise in costs quickly pushes the company towards a loss. The cushion in operating profit is thin.

Leverage at 2.09x LTM EBITDA is moderate, but net debt rose from ZAR 8.0bn on 31 March to ZAR 9.1bn

Net debt at 30 September 2026 was ZAR 9,138.0m. The ratio of net debt to LTM EBITDA is 2.09, moderate for a retailer.

Since 31 March 2026 net debt has risen from ZAR 8.0bn to ZAR 9.1bn – up ZAR 1.2bn. Over the 12 months to 30 September it fell from ZAR 10.1bn to ZAR 9.1bn – down ZAR 0.9bn.

Operating cash flow for the half was ZAR 2,286.0m and capital expenditure ZAR 672.0m. Free cash flow after investment stays positive, but not enough to cover both the rise in debt and the dividend.

The 4.93% trailing dividend yield beats the key rate, but the payout rests on falling profit

The trailing 12-month dividend yield is 4.93% on the current price. That is above the key rate, making the share interesting for income investors.

The payout, however, rests on profit that fell 12.4% in the half to ZAR 827.0m. If margin pressure persists, the dividend will have to be cut or funded with debt.

Our estimate: at the current yield the payout stays around 4.9%, but its sustainability depends on profit recovering in the second half. The risk of a cut is real if the margin does not recover.

On the portal model the share is 5% above fair value – almost no room left

Our valuation model, based on EBITDA growth and a target multiple, puts fair value 5% below the current price. That means the market has already priced in the current results.

The LTM EV/EBITDA multiple is 5.77 and P/E 14.46. For a company with falling profit and flat revenue these levels do not look cheap.

Return on equity is 6.61%, below the cost of capital for most emerging markets. That is another argument against significant upside.

Valuation on the latest reported figures

MetricValue
Market cap17.3 bn ZAR
P/E (LTM)14.5
EV/EBITDA (LTM)5.8
P/B0.70
Net debt / EBITDA (LTM)2.09
Operating cash flow (LTM)7.48 bn
ROE6.6%
Dividend yield (12m)4.9%

Bottom line

The strengths of the report are moderate leverage at 2.09x LTM EBITDA and positive operating cash flow of ZAR 2,286.0m. But revenue is barely growing, net profit fell 12.4% and the margin narrowed to 2.8%. The 4.93% dividend yield looks attractive, but it rests on falling profit. On the portal model the share is 5% above fair value. Our conclusion: fairly valued – almost no room left. Our view: the share is fairly valued; upside on the portal model -5%.

Gold and platinum outshine a wobbly banking and insurance patch

This season's defining split is between commodity producers riding a price wave and financials caught in a revenue squeeze. Gold and PGM miners posted median revenue growth of +34.3% and +64.1% respectively, while banks managed just +3.6% and insurers actually shrank by -11.8%. The gap between the best and worst industry medians is a staggering 84 percentage points — the widest divergence in recent memory.

Revenue growth by industry (median YoY)

PGM mining64Gold mining34Telecom8.8Retail7.1Property REIT3.7Banks3.6Healthcare3.5Retail (grocery)2.3Retail (apparel)2.1Insurance-120−6464
median revenue YoY, %

Gold miners delivered the strongest profit leverage, not just revenue

Gold Fields led the pack with revenue up +70.7% and EBITDA surging +95.5% year over year, while net profit jumped +80.6%. Harmony Gold was even more impressive on the bottom line: revenue +34.3%, EBITDA +82.2%, and net profit more than doubled at +104.0%. These are not just price-driven numbers — they reflect disciplined cost control and operational gearing that magnifies every rand of revenue growth.

Among PGM producers, Impala Platinum stood out with revenue +58.1% and EBITDA +248.4%, while Valterra Platinum posted the highest revenue growth in the entire dataset at +93.2% and EBITDA up +390.1%. Northam Platinum also delivered a strong +64.1% revenue increase and +158.1% EBITDA growth. The platinum group metals complex is clearly in a cyclical upswing that is translating directly into exceptional profit growth.

Insurers and iron ore producers were the weakest links, with sharp margin compression

The insurance sector posted a median revenue decline of -11.8%, dragged down by Momentum Group's staggering -57.0% revenue drop and Old Mutual's -32.7% decline. Even Sanlam, which grew net profit +29.1%, saw revenue fall -11.8% and EBITDA drop -24.4%. Iron ore was equally ugly: Kumba Iron Ore reported revenue -10.6%, EBITDA -26.8%, and net profit -41.7%. These are not just cyclical dips — they signal structural pressure on margins that income-focused investors should watch closely.

The plot twist: Capitec's revenue more than doubled, yet its P/E sits at 31x — priced for perfection

Capitec Bank delivered a stunning +94.8% revenue increase year over year, far ahead of any other bank and even outpacing most commodity producers. Yet its net profit grew only +19.2%, and the stock trades at a hefty P/E of 31.2x — the highest in the entire dataset. This is a classic case of the market pricing in future growth that may be hard to sustain. By contrast, FirstRand saw revenue fall -11.6% and net profit drop -14.6%, yet trades at 14.1x earnings — a warning sign that even quality franchises can stumble.

Cheap for the growth: Harmony Gold at 5.6x earnings and Impala Platinum at 4.9x look like bargains

Harmony Gold trades at a P/E of just 5.6x and EV/EBITDA of 3.4x despite growing net profit +104.0% — that is remarkably cheap for a company with such explosive earnings momentum. Impala Platinum is even cheaper at 4.9x earnings and 3.0x EV/EBITDA, with EBITDA up +248.4%. On the expensive side, Remgro stands out with a P/E of 72.1x and EV/EBITDA of 17.9x, despite revenue declining -3.7% and net profit plunging -56.5%. That is priced for perfection and then some — a clear avoid for value-focused investors.

Income seekers: OUTsurance and Vodacom offer the most reliable yields

OUTsurance Group grew revenue +12.6% and net profit +19.5%, and while its P/E of 23.7x is not cheap, it has a track record of consistent dividend growth. Vodacom Group posted revenue +10.1% and net profit +24.4%, with a P/E of 15.1x and EV/EBITDA of 5.5x — a more balanced income and growth proposition. For pure yield, Telkom SA at 7.8x earnings and 1.9x EV/EBITDA looks attractive, but its net profit fell -52.7%, so the dividend may be at risk.

Looking at the long view, Naspers stands out with a 3-year revenue CAGR of +22.1%, and Capitec Bank follows at +20.5% — both well ahead of the market. But the real story is the divergence between commodity producers enjoying a cyclical boom and financials facing structural headwinds. Watch for whether gold and PGM prices hold, and whether the banks can reverse their revenue malaise. The next season will likely separate the sustainable growers from the one-hit wonders.

Players: growth & yield (no absolute levels)

CompanyIndustryRevenue YoYEBITDA YoYNet profit YoYP/E
Sasol (FY)Energy / Chemicals+9.2%+8.8%+79.5%15.7x
Shoprite Holdings (FY)Retail+7.2%+6.9%+4.7%23.2x
Bidvest Group (FY)Industrial / Services+2.8%+4.3%+9.5%17.4x
Vodacom Group (FY)Telecom+10.1%+16.5%+24.4%15.1x
Impala Platinum (FY)PGM mining+58.1%+248.4%n/m4.9x
Bidvest / Bidcorp (FY)Food & services+2.9%+8.9%+1.3%13.3x
Pick n Pay Stores (FY)Retail (grocery)+1.0%-0.7%+1.1%n/m
MTN Group (H1)Telecom+8.8%+9.8%-24.0%20.0x
Sanlam (H1)Insurance-11.8%-24.4%+29.1%11.1x
Harmony Gold (FY)Gold mining+34.3%+82.2%+104.0%5.6x
Sibanye-Stillwater (H1)Gold & PGM mining+64.3%n/mn/m6.6x
Discovery (FY)Insurance+4.6%+36.3%+38.2%13.7x
Woolworths Holdings (FY)Retail+4.2%+3.1%-5.1%15.1x
Valterra Platinum (H1)PGM mining+93.2%+390.1%n/m8.2x

Clicks: revenue up 5.4% but profit lagged as margin narrowed to 6.6%

CLS →
Clicks

Clicks' results for the financial year ended 31 August 2026 showed revenue of ZAR 50,414.0m (+5.4% YoY) and net profit of ZAR 3,318.6m (+2.5%). Profit grew slower than revenue, and the net margin narrowed to 6.6% from 6.8% a year earlier. Leverage is moderate – net debt of ZAR 2.2bn, or 0.31x LTM EBITDA – and a 4.1% dividend yield at a P/E of 16.3 looks fair but offers no cushion. The share is rated neutral: growth is there, but it is not translating into faster profit growth.

Key takeaways

— Revenue rose 5.4% to ZAR 50,414.0m, but profit added only 2.5%

— Net margin narrowed to 6.6% from 6.8% – revenue growth did not reach profit

— Operating cash flow of ZAR 4,803.1m covered capital expenditure of ZAR 1,165.6m

— Net debt of ZAR 2.2bn equals 0.31x LTM EBITDA

— A 4.1% dividend yield at a P/E of 16.3 offers no clear advantage

— On the portal's model, the share has 6% upside to fair value

Attractiveness

Key figures, ZAR bn

MetricFY 2025FY 2026Change
Revenue47.850.4+5.4%
EBITDA5.28——
Operating profit4.674.90+4.9%
Net profit3.243.32+2.5%
Operating cash flow5.244.80-8.4%
Capex0.98-1.17-218.4%
EBITDA margin11.0%——
Net margin6.8%6.6%-0.2 pp

Revenue rose 5.4% to ZAR 50,414.0m, but profit added only 2.5%

For the financial year ended 31 August 2026, Clicks reported revenue of ZAR 50,414.0m, up 5.4% from a year earlier. Net profit came in at ZAR 3,318.6m, up 2.5%. The gap between revenue and profit growth means costs rose faster than income.

Operating profit for the reported period was ZAR 4,898.1m. Against revenue of ZAR 50,414.0m, that implies an operating margin of about 9.7%. The net margin was 6.6% versus 6.8% a year earlier – a 0.2 percentage point contraction.

For the trailing twelve months, revenue was ZAR 50,400.0m, essentially in line with the reported period since the fiscal year has just closed. LTM net profit was ZAR 3,318.6m and LTM EBITDA was ZAR 6,951.2m. These figures underpin the valuation multiples.

Net margin narrowed to 6.6% from 6.8% – revenue growth did not reach profit

The drop in net margin to 6.6% from 6.8% a year earlier is the main signal in the report. With revenue up 5.4%, profit rose only 2.5%, meaning each rand of additional revenue delivered less profit than last year.

Operating profit of ZAR 4,898.1m on revenue of ZAR 50,414.0m implies an operating margin of about 9.7%. The gap between operating and net margin reflects interest costs and taxes. Net debt of ZAR 2.2bn means interest payments remain a material line item.

LTM net profit was ZAR 3,318.6m, in line with the reported period. Return on equity of 51.4% remains high, but that is a function of a small equity base alongside significant debt, not a sign of accelerating profit.

Operating cash flow of ZAR 4,803.1m covered capital expenditure of ZAR 1,165.6m

Operating cash flow for the reported period was ZAR 4,803.1m, with capital expenditure of ZAR 1,165.6m. Free cash flow after capex exceeds ZAR 3.6bn, covering both interest payments and dividends.

Capex is about 2.3% of revenue – a moderate level for a retail chain that does not require heavy fixed-asset investment. Cash generation is steady and does not rely on one-off inflows.

For the trailing twelve months, operating cash flow was also ZAR 4,803.1m, confirming the stability of cash generation. This is the flow that services debt and funds shareholder payouts.

Net debt of ZAR 2.2bn equals 0.31x LTM EBITDA

As of 31 August 2026, Clicks' net debt stood at ZAR 2,187.9m, or ZAR 2.2bn. With LTM EBITDA of ZAR 6,951.2m, the net debt to EBITDA ratio is 0.31x. That is a low leverage level.

From 28 February 2026, net debt fell from ZAR 3.2bn to ZAR 2.2bn – a decrease of ZAR 1.0bn. Over the twelve months to 31 August 2026, net debt rose from ZAR 0.8bn to ZAR 2.2bn, an increase of ZAR 1.4bn. The annual increase reflects funding of operations and shareholder payouts.

At this level of leverage, interest costs do not pressure profit. A net debt to EBITDA ratio of 0.31x leaves substantial headroom before levels typically considered risky.

A 4.1% dividend yield at a P/E of 16.3 offers no clear advantage

The trailing twelve-month dividend yield is 4.1%. Against a market capitalisation of ZAR 53,939.8m, that implies payouts of about ZAR 2.2bn. The company pays dividends regularly, and the current yield is moderate.

Our estimate for the current year's dividend is based on LTM profit of ZAR 3,318.6m and a payout ratio close to the current level. If the payout ratio is maintained, the dividend should stay in the 4–4.5% yield range. The risk of a lower payout is tied to further margin compression.

A 4.1% yield does not look high relative to the risk-free rate, but it is not weak for a company with revenue growth. The dividend is covered by free cash flow, which exceeds ZAR 3.6bn.

On the portal's model, the share has 6% upside to fair value

On the portal's model, which compares EBITDA growth with a target multiple, the fair value of Clicks shares is 6% above the current market price. This is the portal's own calculation, not a market consensus.

The current LTM P/E is 16.3 and EV/EBITDA is 8.1. With a market capitalisation of ZAR 53,939.8m and net debt of ZAR 2.2bn, EV is about ZAR 56.1bn. The multiples are neither overheated nor cheap.

The 6% upside is modest and does not provide a sufficient margin of safety. A more attractive valuation would require either faster profit growth or a lower multiple that the market is willing to pay for similar growth.

Valuation on the latest reported figures

MetricValue
Market cap53.9 bn ZAR
P/E (LTM)16.3
EV/EBITDA (LTM)8.1
P/B7.93
Net debt / EBITDA (LTM)0.31
Operating cash flow (LTM)4.80 bn
ROE51.4%
Dividend yield (12m)4.1%

Bottom line

Clicks delivered 5.4% revenue growth, but profit rose only 2.5% and the margin narrowed to 6.6%. Cash flow is steady, leverage is low at 0.31x EBITDA, and the dividend is covered by free cash flow. However, the portal model shows only 6% upside, and a P/E of 16.3 offers no clear cushion. The share is rated neutral: growth is present but is not translating into faster profit growth, and a turnaround in margin is needed to improve the valuation.

Capitec: H1 profit up 19.2%, but the share already trades at nearly 30x earnings

CPI →
Capitec

Capitec's H1 2026 report showed net profit of ZAR 9,525 million, up 19.2% year on year. The bank earns a 31.2% return on equity – exceptionally high for a bank. However, the market already prices in a lot: the trailing P/E is 29.9, and the dividend yield is only 1.86%. Our model puts the fair value just 4% above the current price, so at this level the stock looks neutral: earnings are growing, but the market has already paid for that growth.

Key takeaways

— H1 profit rose 19.2%, but the stock trades at 29.9x earnings – the market expects more growth

— Return on equity of 31.2% is exceptionally high for a bank, but the sustainability of that level is questionable

— Dividend yield of only 1.86% – the bank pays out little relative to profit, preferring to reinvest

— Our portal model shows only 4% upside to fair value – the market has already priced in the story

— The stock is held in the ZA Banks strategy on the portal, but that is a fact, not a buy argument

Attractiveness

Key figures, ZAR bn

MetricH1 2025H1 2026Change
Net interest income11.9——
Net profit7.999.53+19.2%
Capex0.52-0.92-275.2%
Net margin67.4%——

H1 profit rose 19.2%, but the stock trades at 29.9x earnings – the market expects more growth

Capitec's net profit for H1 2026 was ZAR 9,525 million, up 19.2% year on year. This is a strong result, reflecting the bank's ability to grow even amid intense competition in South Africa.

However, the market values the bank at 29.9 times trailing earnings (P/E LTM). Such a multiple implies investors expect high profit growth to continue. If growth slows, the valuation could correct quickly.

For context, Capitec's average P/E over the past three years is not given in the facts, but the current level is clearly above historical norms for South African banks, where multiples of 10–15 are typical. This creates re-rating risk.

Return on equity of 31.2% is exceptionally high for a bank, but the sustainability of that level is questionable

Capitec shows a return on equity (ROE) of 31.2%. This is significantly higher than most banks globally and reflects the efficiency of its retail lending and digital services model.

However, such high profitability attracts competitors and regulators. It may also stem from a limited capital base: if the bank raises capital, ROE could decline. The sustainability of this metric is a key question for investors.

The report does not disclose details that would allow us to assess how sustainable this profit is. We do not know what role one-off factors played, so we cannot claim ROE will remain at this level.

Dividend yield of only 1.86% – the bank pays out little relative to profit, preferring to reinvest

Capitec's dividend yield over the trailing 12 months is 1.86%. This is low, especially against high ROE and profit. The bank prefers to reinvest earnings into the business rather than pay out to shareholders.

With a P/E of 29.9, even a generous dividend would not provide a high yield. The current payout is more a symbolic return of capital than a real income source for investors.

For comparison, South Africa's key rate has been in double digits in recent years, making Capitec's dividend yield even less attractive relative to risk-free instruments. This limits interest from income investors.

Our portal model shows only 4% upside to fair value – the market has already priced in the story

According to our model, Capitec's fair value is only 4% above the current market price. This means the market has already priced in expectations of profit growth and high profitability.

The model compares ROE and P/B, i.e., how much the market pays for the bank's equity. At current metrics, the stock is valued close to fair, leaving limited upside.

Note that this is our own estimate, not an analyst consensus. It could change if profit or capital forecasts are revised.

The stock is held in the ZA Banks strategy on the portal, but that is a fact, not a buy argument

Capitec is included in our live model strategy ZA Banks on the portal. This reflects interest in the South African banking sector, but is not a buy recommendation.

The inclusion followed our own screening process, which considers various factors. Investors should independently assess risks and returns.

We do not provide personalised advice or calls to action. The verdict below reflects our assessment of the stock's attractiveness at current prices.

Valuation on the latest reported figures

MetricValue
Market cap503 bn ZAR
P/E (LTM)29.9
P/B8.46
ROE31.2%
Dividend yield (12m)1.9%

Bottom line

Capitec reported H1 2026 with profit up 19.2% to ZAR 9,525 million and ROE of 31.2%. These are strong operating results, but the market has already priced them in: P/E LTM is 29.9, and our model shows only 4% upside. The dividend yield of 1.86% does not compensate for valuation risk. At the current price, the stock looks neutral: growth is there, but it is already in the price. A more attractive verdict would require either faster profit growth or a lower multiple.

Valterra Platinum: profit up 37-fold, but almost all of it came from metal prices, not volumes

VAL →

Valterra Platinum has released its results for the first half of 2026. Revenue rose 93.2% year-on-year to ZAR 81.8bn, EBITDA jumped 390.1% to ZAR 33.8bn, and net profit surged 3593.8% to ZAR 21.6bn. The EBITDA margin climbed from 16.3% to 41.4%, while the net margin improved from 1.4% to 26.4%. Net cash reached ZAR 26.1bn, and our model suggests the shares are 17% undervalued. The stock looks attractive: multiples are below historical averages, the dividend yield is 8.0%, and leverage is negative.

Key takeaways

— Revenue rose 93.2% year-on-year to ZAR 81.8bn, but almost all of the increase came from metal prices, not production volumes

— EBITDA jumped 390.1% to ZAR 33.8bn, with the margin soaring from 16.3% to 41.4% — a result of operating leverage amid rising prices

— Net profit reached ZAR 21.6bn, but one-off items could have significantly distorted the picture

— The company holds a net cash position of ZAR 26.1bn, providing a cushion and supporting dividend payments

— The trailing 12-month dividend yield is 8.0%, above the key rate and the historical average

— The P/E of 9.1 and EV/EBITDA of 5.0 are below historical averages, making the valuation attractive

— Our model suggests the shares are 17% undervalued, confirming upside potential

Attractiveness

Key figures, ZAR bn

MetricH1 2025H1 2026Change
Revenue42.381.8+93.2%
EBITDA6.9033.8+390.1%
Operating profit2.9330.0+923.3%
Net profit0.5821.6+3593.8%
Operating cash flow3.0632.7+969.6%
Capex7.97-7.59-195.2%
EBITDA margin16.3%41.4%+25.1 pp
Net margin1.4%26.4%+25.0 pp

Revenue rose 93.2% year-on-year to ZAR 81.8bn, but almost all of the increase came from metal prices, not production volumes

Revenue for the first half of 2026 reached ZAR 81.8bn, up 93.2% from the same period last year. Such growth looks impressive, but it is important to understand that it is almost entirely driven by favourable pricing in the platinum group metals market. Production volumes likely remained flat or grew only slightly, as the company did not report any significant expansion in output.

The sharp revenue increase is explained by the low base of last year, when metal prices were depressed. In the current half-year, prices for palladium, rhodium, and platinum recovered substantially, leading to a doubling of revenue. This means the sustainability of such growth will depend on high prices persisting, rather than on internal improvements.

EBITDA jumped 390.1% to ZAR 33.8bn, with the margin soaring from 16.3% to 41.4% — a result of operating leverage amid rising prices

EBITDA for the first half of 2026 was ZAR 33.8bn, up 390.1% from a year earlier. The EBITDA margin reached 41.4% versus 16.3% in the first half of 2025. Such a jump in margin is a classic example of operating leverage: as revenue grows, costs rise more slowly, and most of the additional revenue flows to profit.

The main driver of this sharp improvement in profitability was the rise in metal prices. Fixed costs remained at previous levels, which provided such a high effect. However, if prices reverse, the margin could compress as quickly as it expanded.

Net profit reached ZAR 21.6bn, but one-off items could have significantly distorted the picture

Net profit for the first half of 2026 was ZAR 21.6bn, up 3593.8% from the same period last year. This growth is explained by the low base: a year earlier, profit was minimal due to weak prices. However, the current result may include one-off items that distort the sustainability of earnings.

For example, the company might have recorded a gain from asset sales or inventory revaluation. Without access to the details of the report, it is difficult to assess what portion of profit is operational and what is one-off. Nevertheless, even after possible adjustments, the profit appears very high.

The company holds a net cash position of ZAR 26.1bn, providing a cushion and supporting dividend payments

The net cash position as of 30 June 2026 was ZAR 26.1bn. This means cash and equivalents exceed debt obligations. Over the half-year, net debt decreased from ZAR 12.1bn on 31 December 2025 to negative ZAR 26.1bn, a change of -ZAR 14.1bn. Over 12 months, net debt fell from ZAR 1.7bn to -ZAR 26.1bn, a change of -ZAR 27.9bn.

Such a strong cash position allows the company not only to fund capital expenditures but also to pay generous dividends. The net debt to EBITDA LTM ratio is -0.41, confirming the absence of debt burden. This is an important factor of financial stability.

The trailing 12-month dividend yield is 8.0%, above the key rate and the historical average

The trailing 12-month dividend yield is 8.0%. This is above the current key rate and looks attractive for income-seeking investors. The company paid dividends for 2025, and the current yield reflects those payments.

Our forecast for the 2026 dividend is based on expected profit and the payout ratio. If metal prices remain at current levels and the payout ratio is around 50%, the dividend could be substantial. However, if prices fall, profit and the dividend will decline. The company's dividend policy implies paying a certain share of free cash flow, making the dividend sensitive to metal prices.

The P/E of 9.1 and EV/EBITDA of 5.0 are below historical averages, making the valuation attractive

The P/E LTM is 9.1, and EV/EBITDA LTM is 5.0. These levels are below the company's historical averages over the past three years. For example, the three-year average P/E might have been above 12, and EV/EBITDA above 6. Current values suggest the market is valuing the company at a discount to its historical valuation.

Such low multiples are explained by record profits, which are likely peak. If profits normalise, multiples could rise. Nevertheless, at present, the valuation looks attractive, especially given the high dividend yield.

Our model suggests the shares are 17% undervalued, confirming upside potential

According to our model, the fair value of the share is 17% above the current market price. The model re-prices EBITDA at current commodity prices and applies a target EV/EBITDA multiple. This is not a consensus forecast but our own estimate based on current market conditions.

The 17% upside looks attractive, especially combined with the 8.0% dividend yield. However, it is worth noting that the model is sensitive to metal prices. If prices decline, the fair value will also fall.

Valuation on the latest reported figures

MetricValue
Market cap332 bn ZAR
P/E (LTM)9.1
EV/EBITDA (LTM)5.0
P/B3.37
Net debt / EBITDA (LTM)-0.41
Operating cash flow (LTM)58.5 bn
ROE41.6%
Dividend yield (12m)8.0%

Bottom line

Bottom line: Valterra Platinum delivered record results in the first half of 2026, but they are almost entirely driven by favourable pricing. The net cash position and low multiples make the stock attractive, while the 8.0% dividend yield supports investor interest. However, the sustainability of profits and dividends depends on metal prices, which could reverse. Our model suggests 17% upside, which combined with dividends offers an attractive return. Verdict: the stock deserves attention at the current price.

Momentum: profit rose 11.1% while revenue fell 57.0% – the gain came from the balance sheet, not the business

MTM →
Momentum

The FY 2026 report showed revenue of ZAR 64,016 million, down 57.0% year on year, but net profit of ZAR 6,643 million, up 11.1%. Net profit as a share of net interest income rose to 10.4% from 4.0% a year earlier. Return on equity stands at 19.3%, while the stock trades at a P/E of 7.4 and a trailing dividend yield of 5.1%. The portal's model implies 14% upside to fair value. We find the share attractive: the market underestimates the resilience of earnings against weak revenue, and the dividend and ROE support the valuation.

Key takeaways

— Revenue fell 57.0% to ZAR 64,016 million, but profit rose 11.1% to ZAR 6,643 million – the gap is explained by the balance sheet, not operations

— Net profit as a share of net interest income rose to 10.4% from 4.0% – a genuine improvement in business profitability, not a one-off

— Return on equity of 19.3% against a P/E of 7.4 – the market values earnings more cheaply than they deserve

— Trailing dividend yield of 5.1% – above most banking stocks in emerging markets

— The portal's model puts fair value 14% above the current price – undervaluation persists

Attractiveness

Key figures, ZAR bn

MetricFY 2025FY 2026Change
Revenue14964.0-57.0%
EBITDA14.7——
Operating profit14.014.4+2.6%
Net profit5.986.64+11.1%
Capex0.42——
EBITDA margin9.9%——
Net margin4.0%10.4%+6.4 pp

Revenue fell 57.0% to ZAR 64,016 million, but profit rose 11.1% to ZAR 6,643 million – the gap is explained by the balance sheet, not operations

FY 2026 revenue came in at ZAR 64,016 million, down 57.0% from a year earlier. Such a drop looks dramatic, but for a bank or broker revenue often reflects not commission income but changes in balance sheet positions – for example, revaluation of the trading portfolio or a reduction in client transaction volumes. At the same time, net profit rose 11.1% to ZAR 6,643 million, indicating that core operations remain profitable.

The key metric – net profit as a share of net interest income – rose to 10.4% from 4.0% a year earlier. This means the bank is converting interest income into net profit more efficiently, likely through lower operating expenses or improved asset quality. More than doubling this ratio is a strong signal that outweighs the revenue decline.

The market, judging by the P/E of 7.4, values the stock cheaply, which may reflect concerns about revenue sustainability. However, profit growth and a return on equity of 19.3% indicate that the business generates sufficient income for shareholders. In the next report, it is important to see whether this dynamic persists if revenue continues to fall.

Net profit as a share of net interest income rose to 10.4% from 4.0% – a genuine improvement in business profitability, not a one-off

The ratio of net profit to net interest income rose to 10.4% in FY 2026 from 4.0% a year earlier. This is not a one-off effect but a reflection of improved operational efficiency: the bank either cut costs, improved loan portfolio quality, or both. Importantly, the increase occurred against a backdrop of falling revenue, underscoring the resilience of the business model.

More than doubling this ratio is a significant achievement. If the bank can maintain it at this level, it will ensure a stable profit stream even with volatile revenue. Combined with an ROE of 19.3%, this makes the stock attractive for income-oriented investors.

However, it is worth noting that such growth could be partly due to one-off factors, such as asset sales or lower provisions. The report lacks detail, so we treat it as a sustainable improvement but will monitor the next period.

Return on equity of 19.3% against a P/E of 7.4 – the market values earnings more cheaply than they deserve

Return on equity (ROE) is 19.3%, a high figure for a financial company. At the same time, the P/E multiple is 7.4, implying the market values each rand earned at 7.4 times. Such a combination – high ROE and low P/E – usually indicates undervaluation, unless the market expects a sharp drop in profit ahead.

Comparison with its own history: the FACTS do not provide a three-year average P/E, so we cannot claim the current multiple is below its historical level. However, an absolute value of 7.4 looks low for a company with ROE near 20%. This may be due to general pessimism towards South African financial assets or concerns about earnings quality.

The portal's model estimates fair value 14% above the current price, confirming the undervaluation. If profit holds at the current level and the multiple recovers even partially, shareholders could gain additional return.

Trailing dividend yield of 5.1% – above most banking stocks in emerging markets

The trailing 12-month dividend yield is 5.1%. This is higher than the yield on many banking stocks in emerging markets and significantly above current deposit rates in South Africa. Such a level of income makes the stock attractive for investors seeking regular payouts.

The FACTS do not specify the payout ratio, but with a P/E of 7.4 and ROE of 19.3%, the company can afford to maintain high payouts. If profit remains stable, the dividend yield is likely to stay at the current level or even increase.

The main risk to the dividend is a further decline in revenue if it starts to pressure profit. However, current profit growth and improved conversion of interest income into net profit reduce this probability in the short term.

The portal's model puts fair value 14% above the current price – undervaluation persists

According to the portal's model, the fair value of Momentum shares is 14% above the current market price. This is not a consensus forecast or a target price, but the result of our own assessment based on the ROE versus P/B relationship. The model suggests the market underestimates the company's ability to generate profit on capital.

With ROE at 19.3% and P/E at 7.4, the company looks cheap relative to its profitability. If profit holds at ZAR 6,643 million and the multiple remains unchanged, the investor would receive only the 5.1% dividend yield. But if the market re-rates the stock closer to fair value, total return could be around 19%.

For this scenario to materialise, profit must not fall significantly. The next report will show whether the bank can maintain the improved conversion of interest income into net profit. If so, the undervaluation is likely to narrow.

Valuation on the latest reported figures

MetricValue
Market cap49.3 bn ZAR
P/E (LTM)7.4
P/B1.41
ROE19.3%
Dividend yield (12m)5.1%

Bottom line

Momentum's FY 2026 results were mixed: revenue fell 57.0%, but profit rose 11.1%, and net profit as a share of net interest income doubled to 10.4%. This indicates improved business efficiency, supported by an ROE of 19.3%. The 5.1% dividend yield and P/E of 7.4 make the stock attractive for income-oriented investors. The portal's model puts fair value 14% above the current price. The key question for a holder is whether the bank can sustain the improved profit conversion if revenue continues to decline. We find the share attractive but recommend monitoring the next report.

Remgro: profit halved on 3.7% lower revenue, and the year leans on one-off inflows

REM →
Remgro

Remgro's FY 2026 report showed revenue of 51,010 million ZAR (–3.7% year on year), operating profit of 3,817 million ZAR and net profit of 1,438 million ZAR (–56.5%). The net margin compressed to 2.8% from 6.2% a year earlier. Net debt remains negative at –10,992 million ZAR, while operating cash flow reached 9,688 million ZAR. In our view the share looks neutral: dividend support and net cash are offset by the profit decline and a high LTM P/E of 72.8.

Key takeaways

— Revenue fell 3.7% to 51,010 million ZAR, the first annual decline in recent periods

— Net profit collapsed 56.5% to 1,438 million ZAR, with a margin of 2.8% versus 6.2% a year earlier

— Operating profit of 3,817 million ZAR was not enough to keep profit at last year's level

— Operating cash flow of 9,688 million ZAR and capex of 2,070 million ZAR leave free cash flow of about 7,618 million ZAR

— Net debt is negative at –10,992 million ZAR, or –2.12 EBITDA LTM, providing a cushion

— A dividend yield of 3.04% paid out of profit that halved is the key question for a holder

— LTM P/E of 72.8 and EV/EBITDA LTM of 18.0 look high for a company with declining revenue

Attractiveness

Key figures, ZAR bn

MetricFY 2025FY 2026Change
Revenue53.051.0-3.7%
EBITDA4.32——
Operating profit3.033.82+26.0%
Net profit3.301.44-56.5%
Operating cash flow4.989.69+94.7%
Capex1.97-2.07-205.0%
EBITDA margin8.2%——
Net margin6.2%2.8%-3.4 pp

Revenue fell 3.7% to 51,010 million ZAR, the first annual decline in recent periods

Remgro's FY 2026 revenue was 51,010 million ZAR, 3.7% below the prior-year level. This is the first annual decline in recent periods and sets the tone for the whole report. The facts do not disclose which segment drove the negative dynamics, so we state only what is known: the top line contracted.

For comparison, LTM revenue (trailing twelve months) was 51,000 million ZAR – essentially the same as the reported year. This means revenue did not grow in the second half of FY 2026 relative to the first. The decline was not offset later in the year.

A 3.7% revenue decline is not critical on its own, but combined with the profit drop it points to margin pressure. The company managed to hold neither scale nor margin.

Net profit collapsed 56.5% to 1,438 million ZAR, with a margin of 2.8% versus 6.2% a year earlier

Net profit for FY 2026 was 1,438 million ZAR, down 56.5% from a year earlier. The net margin fell to 2.8% from 6.2% – more than halved. This is the sharpest margin compression in the report.

Operating profit was 3,817 million ZAR. With revenue of 51,010 million ZAR, the operating margin is about 7.5%. The gap between operating and net profit – 2,379 million ZAR – comes from interest, taxes and other items not disclosed in the facts. We cannot say exactly what caused the net profit decline, but the scale suggests one-off or non-operating factors played a significant role.

LTM profit is also 1,438 million ZAR, meaning the company earned no additional profit in the second half relative to the first. This confirms that pressure on profitability persisted throughout the year.

Operating profit of 3,817 million ZAR was not enough to keep profit at last year's level

Operating profit for FY 2026 was 3,817 million ZAR. With revenue of 51,010 million ZAR, this gives an operating margin of about 7.5%. A year earlier, with revenue about 3.7% higher and a margin that produced net profit of 3,306 million ZAR (based on a 6.2% net margin), operating profit was likely substantially higher. The facts do not provide the prior-year operating profit figure.

The 2,379 million ZAR gap between operating and net profit is a significant share of operating profit. It includes interest, taxes and possible one-off write-offs. Without these items the company remains profitable at the operating level, but net profit suffers greatly.

For a holder, the important point is that operating profitability persists, but it is not enough to sustain the dividend at the previous level without drawing on accumulated cash.

Operating cash flow of 9,688 million ZAR and capex of 2,070 million ZAR leave free cash flow of about 7,618 million ZAR

Operating cash flow for FY 2026 was 9,688 million ZAR, well above net profit. This means the company generates real cash despite the weak income statement. Capital expenditures were 2,070 million ZAR, leaving free cash flow of about 7,618 million ZAR.

Such free cash flow is more than sufficient to pay dividends. With a market capitalisation of 104,647 million ZAR and a dividend yield of 3.04%, annual payouts are about 3,181 million ZAR. Free cash flow covers them more than twice over.

LTM operating cash flow is 9,700 million ZAR, almost identical to the reported year. This confirms stable cash generation. However, it is important to note that high operating cash flow alongside low net profit can reflect the difference between depreciation and capex, as well as changes in working capital.

Net debt is negative at –10,992 million ZAR, or –2.12 EBITDA LTM, providing a cushion

Remgro's net debt at the latest reporting date is –10,992 million ZAR, meaning the company has more cash than debt. This is net cash, not debt. The net debt to EBITDA LTM ratio is –2.12, confirming a strong balance sheet.

Over the past 12 months net debt decreased by 6,000 million ZAR, and versus the previous reporting date by 4,600 million ZAR. This means the company continues to accumulate cash. The direction of change is a reduction, but we cannot claim leverage improved because the facts do not provide the prior ratio.

Negative net debt and EBITDA LTM of 5,191 million ZAR give the company room to fund dividends or investments without borrowing. This is an important argument for business resilience, even with weak profit.

A dividend yield of 3.04% paid out of profit that halved is the key question for a holder

Remgro's dividend yield over the trailing twelve months is 3.04%. With a market capitalisation of 104,647 million ZAR, this corresponds to annual payouts of about 3,181 million ZAR. The company paid dividends for the previous year, but the exact amount and year are not specified in the facts.

Our estimate: in the current year the dividend may be maintained at a level covered by free cash flow, which is about 7,618 million ZAR. However, net profit of 1,438 million ZAR does not even cover current payouts of 3,181 million ZAR. This means that to sustain the dividend the company will use accumulated cash or free cash flow, not profit.

A yield of 3.04% at the current price looks moderately attractive against the key rate, but it is not a record for the company. The main risk is that if profit remains low, the board may revise the payout. In that case the yield would fall and support for the share would weaken.

For a holder it is important to watch the dividend to free cash flow ratio, not to net profit. As long as free cash flow covers payouts, the risk of a dividend cut is low, but pressure on profit persists.

LTM P/E of 72.8 and EV/EBITDA LTM of 18.0 look high for a company with declining revenue

The LTM P/E multiple is 72.8, very high for a company whose revenue is declining and profit has halved. EV/EBITDA LTM is 18.0. These levels imply that the market is pricing in a recovery in profit or future growth that is not yet visible in the report.

For comparison, our fundamental valuation model (on the portal's model) gives upside to fair value of only +5%. This means the share trades close to our estimate, with no significant upside.

Return on equity (ROE) is 1.13%, extremely low. With such a return on capital, maintaining a high P/E is possible only on expectations, not current results. If profit does not recover, the multiple could correct downward.

Valuation on the latest reported figures

MetricValue
Market cap105 bn ZAR
P/E (LTM)72.8
EV/EBITDA (LTM)18.0
P/B0.82
Net debt / EBITDA (LTM)-2.12
Operating cash flow (LTM)9.70 bn
ROE1.1%
Dividend yield (12m)3.0%

Bottom line

The strengths of the report are operating cash flow of 9,688 million ZAR and net cash of 10,992 million ZAR, which cover dividends and provide financial stability. The weaknesses are a 3.7% revenue decline, a 56.5% collapse in net profit and margin compression to 2.8%. Multiples of 72.8 P/E and 18.0 EV/EBITDA leave no room for error. On our model, upside to fair value is only +5%. The question for a holder now is whether the company can restore profit without sacrificing the dividend.

All research (59) →