Kazatomprom: revenue up 8.7% but EBITDA down 10.2% — margin compressed 7.4 pp on higher taxes and sulphuric acid
On 21 August Kazatomprom released its operating and financial review for the six months ended 30 June 2026. Revenue for the first half rose 8.7% year on year, but EBITDA fell 10.2% and net profit declined 8.7%. The EBITDA margin compressed to 35.2% from 42.6% a year earlier, and the net margin to 33.5% from 39.9%. At a P/E of 10.8 and EV/EBITDA of 9.4, the share looks neutral: rising uranium prices are not translating into profit because costs and taxes are growing faster.
Key takeaways
— Revenue rose 8.7% on a 16% increase in the average realised uranium price in US dollars
— EBITDA fell 10.2% as MET doubled and sulphuric acid prices rose 38.7%
— Net profit declined 8.7% with tax accruals up 53%
— Dividend yield of 3.0% for the 2025 payout is below the key rate and historical levels
— Net debt / EBITDA LTM of 0.23 is low, but net profit is falling
— P/E of 10.8 and EV/EBITDA of 9.4 are neutral versus history, but profit is under pressure
Attractiveness
Key figures, KZT bn
| Metric | H1 2025 | H1 2026 | Change |
|---|---|---|---|
| Revenue | 660 | 718 | +8.7% |
| EBITDA | 281 | 253 | -10.2% |
| Operating profit | 254 | 253 | -0.4% |
| Net profit | 263 | 240 | -8.7% |
| Operating cash flow | 710 | 7 100 | +900.0% |
| EBITDA margin | 42.6% | 35.2% | -7.4 pp |
| Net margin | 39.9% | 33.5% | -6.4 pp |
Revenue rose 8.7% on a 16% increase in the average realised uranium price in US dollars
Revenue for the first half of 2026 was KZT 1,860.7 bn, up 8.7% year on year. The main driver was a higher average realised uranium price: in US dollars it rose 16% to USD 67.88 per pound, in tenge 10% to KZT 33,014 per pound. The average spot price rose even more — 24% in US dollars to USD 85.98 per pound — but the company's contract portfolio includes fixed prices and price ceilings, so realisations lag the spot market.
Physical sales volumes are not disclosed in the available part of the report, but revenue growth with a faster price increase suggests physical volumes may have declined. This is consistent with the 'value over volume' strategy the company has followed since 2025. The currency factor also weighed: the average tenge exchange rate strengthened 5% to KZT 486.34 per US dollar, partially offsetting the dollar price gain.
For an investor, the key point is that revenue is growing slower than spot prices. If spot remains above USD 80 per pound and contract ceilings are revised, the realised price could catch up with the market with a time lag. For now, the company sells uranium at prices 21% below the current spot.
EBITDA fell 10.2% as MET doubled and sulphuric acid prices rose 38.7%
EBITDA for the first half of 2026 fell 10.2% year on year, and the EBITDA margin compressed to 35.2% from 42.6% a year earlier. The main blow came from the mineral extraction tax (MET): from 1 January 2026 a differentiated rate was introduced, and the average MET rate rose to 12.4% from a flat 9% a year earlier. Accrued MET doubled to KZT 119.5 bn.
The second factor was the rising cost of sulphuric acid, a key reagent for in-situ recovery. The weighted average price rose 38.7% to KZT 97,312 per tonne. Sulphuric acid accounts for about 15.3% of production costs, and its appreciation directly pressures the cost base. The company expects the deficit to ease in the medium term, but the commissioning of its own TQZ plant has been delayed by 6–12 months — to Q3 2027 or Q1 2028.
Total tax accruals rose 53% to KZT 323.3 bn. Besides MET, corporate income tax increased 42% on higher revenue, and other taxes rose 30%, partly due to the VAT rate increase from 12% to 16%. Margin pressure will persist until the uranium price catches up with cost inflation.
Net profit declined 8.7% with tax accruals up 53%
Net profit for the first half of 2026 declined 8.7% year on year, and the net margin fell to 33.5% from 39.9%. Besides operational pressure, the result was affected by a net foreign exchange loss of KZT 19.4 bn versus KZT 12.7 bn a year earlier. The tenge's appreciation against the dollar reduces tenge-denominated revenue, although most debt is dollar-denominated, creating a natural hedge.
Profit for the trailing twelve months was KZT 783.9 bn. Return on equity (ROE) is 26.6%, which remains high. However, profit dynamics are negative: the company cannot pass on higher taxes and costs to the selling price due to the contract structure.
For an investor, the key question is whether the company can restore its margin. If the uranium price remains high and contract prices are revised upward, profit could return to growth. But for now the trend is unfavourable.
Dividend yield of 3.0% for the 2025 payout is below the key rate and historical levels
The dividend yield for the trailing twelve months is 3.0%. The company pays dividends based on a policy linked to net income. A payout for 2025 was made, but its size is not disclosed in the available part of the report. At the current price, the 3.0% yield is below the key rate and looks modest for a company with high profitability.
Our estimate for the 2026 dividend is based on the current profit trend. If net profit for the year falls by 8.7%, as in the first half, and the payout ratio remains at the level of previous years, the dividend could come under pressure. However, low leverage (0.23 to EBITDA LTM) and strong operating cash flow (KZT 809.8 bn for LTM) support the payout.
A 3.0% yield is not attractive for an income-oriented investor, especially against the high key rate in Kazakhstan. A reversal in profit dynamics is needed for dividend growth, which is not yet visible.
Net debt / EBITDA LTM of 0.23 is low, but net profit is falling
Net debt at the latest reporting date was KZT 207.5 bn, and the net debt to EBITDA LTM ratio was 0.23. This is a low level that gives the company a margin of safety. However, the change in net debt from the previous reporting date is minus RUB 235.5 bn, and over 12 months plus RUB 555.9 bn. These figures are in rubles, which may reflect a conversion or disclosure feature.
Operating cash flow for the trailing twelve months was KZT 809.8 bn, significantly exceeding net debt. This allows the company to fund capital expenditures and dividends without increasing debt. Capital expenditures in the first half of 2026 are not disclosed in the available part of the report, but the company continues to invest in expansion, including the Zhalpak plant.
Low leverage is a strength for the credit profile, but profitability matters more for the shareholder. Debt is not a problem now, but falling EBITDA could eventually increase the ratio if profit continues to decline.
P/E of 10.8 and EV/EBITDA of 9.4 are neutral versus history, but profit is under pressure
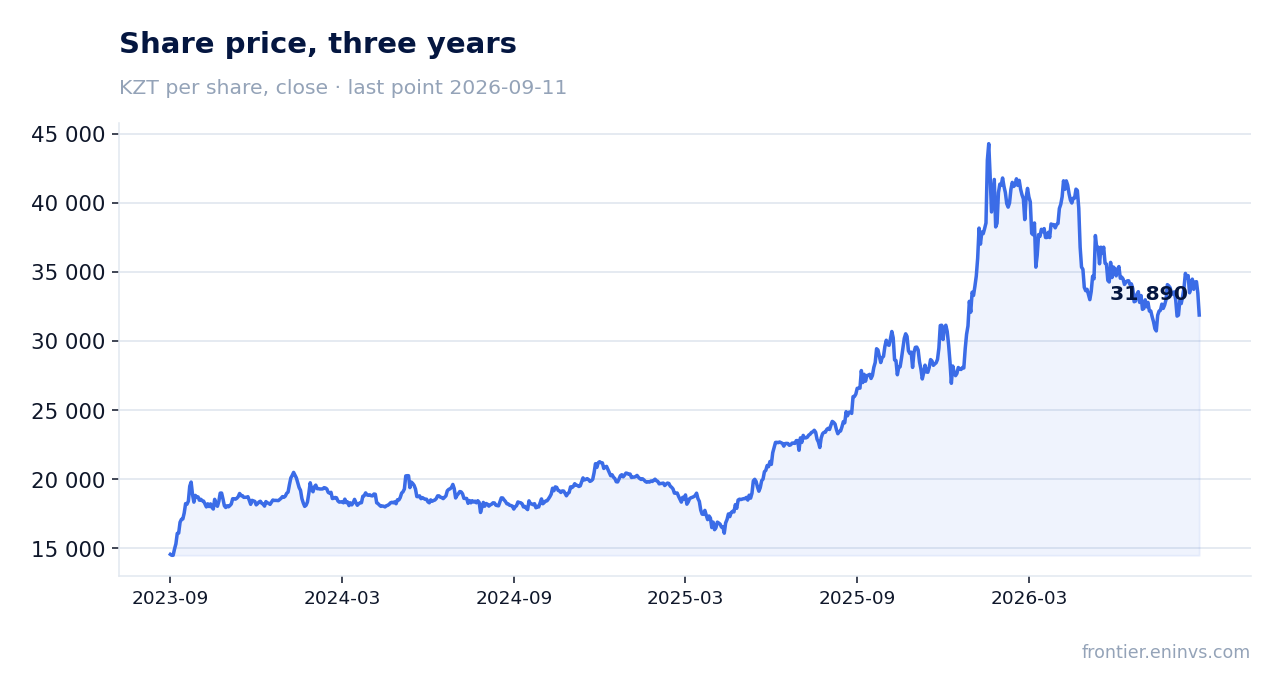
The shares trade at a P/E of 10.8 and EV/EBITDA of 9.4 on an LTM basis. Market capitalisation is KZT 8,465.7 bn. We do not have three-year history in the facts to compare, so we cannot say whether current multiples are above or below their own averages. However, the absolute levels look moderate for a company with an ROE of 26.6%.
According to the portal's model, which re-prices EBITDA at current commodity prices at the target EV/EBITDA, the upside to fair value is minus 2%. This means the market already prices in current uranium prices and the current profit level. Growth in market value requires either higher uranium prices or a margin recovery.
Given falling profit and dividend uncertainty, the valuation looks fair but offers no clear advantage. Upside is limited unless the company can reverse the negative margin trend.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 8 466 bn KZT |
| P/E (LTM) | 10.8 |
| EV/EBITDA (LTM) | 9.4 |
| P/B | 2.61 |
| Net debt / EBITDA (LTM) | 0.23 |
| Operating cash flow (LTM) | 810 bn |
| ROE | 26.6% |
| Dividend yield (12m) | 3.0% |
Bottom line
The report's strengths are revenue growth of 8.7% and low leverage of 0.23 to EBITDA LTM. However, EBITDA fell 10.2%, net profit declined 8.7%, and the margin compressed by 7.4 pp due to doubled MET and higher sulphuric acid costs. A dividend yield of 3.0% does not compensate for the risks. The valuation at P/E 10.8 and EV/EBITDA 9.4 is neutral, with the portal model showing minus 2% upside. An improvement requires higher realised uranium prices or a lower tax burden.
Open the company's financial profile KZAP →
See also: market overview · valuation map · stock screeners