Ambev: double-digit revenue growth, but cash goes to taxes and dividends
On August 25, Ambev reported Q2 2026 results. Revenue grew 10.1% YoY, EBITDA 14.5%, net profit 36.7%. The shares look attractive: multiples are below historical averages, and the portal's model implies 12% upside.
Key takeaways
— Q2 revenue grew 10.1% YoY to USD 3,967.8 million
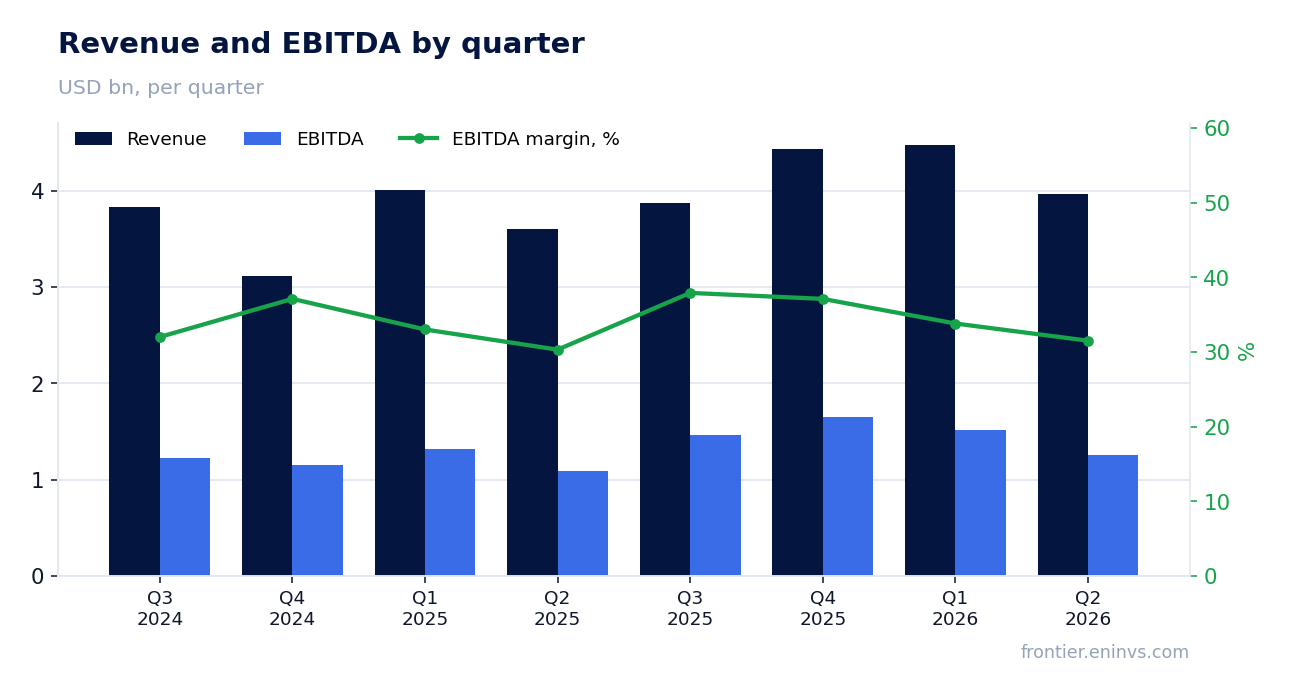
— EBITDA margin expanded 1.2 pp to 31.5% on operating leverage
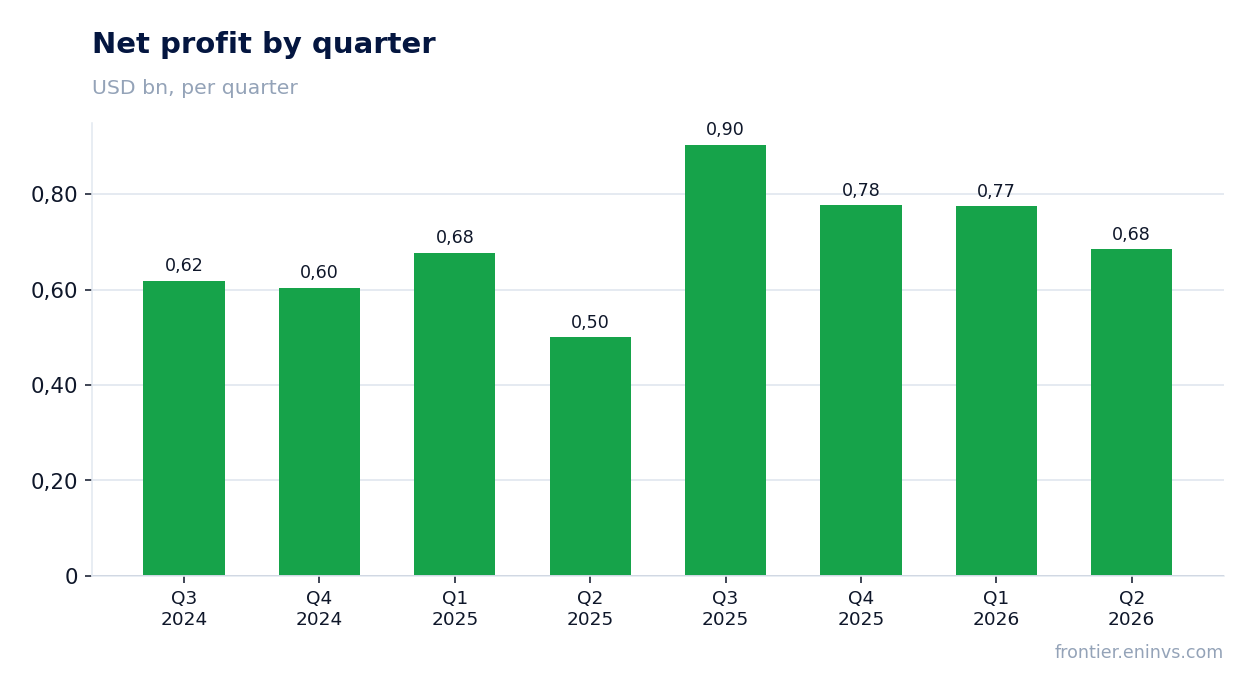
— Net profit rose 36.7% YoY to USD 684.2 million, helped by a lower effective tax rate
— Quarterly free cash flow of USD 754.5 million covers dividends
— Trailing dividend yield of 0.3% is below the key rate
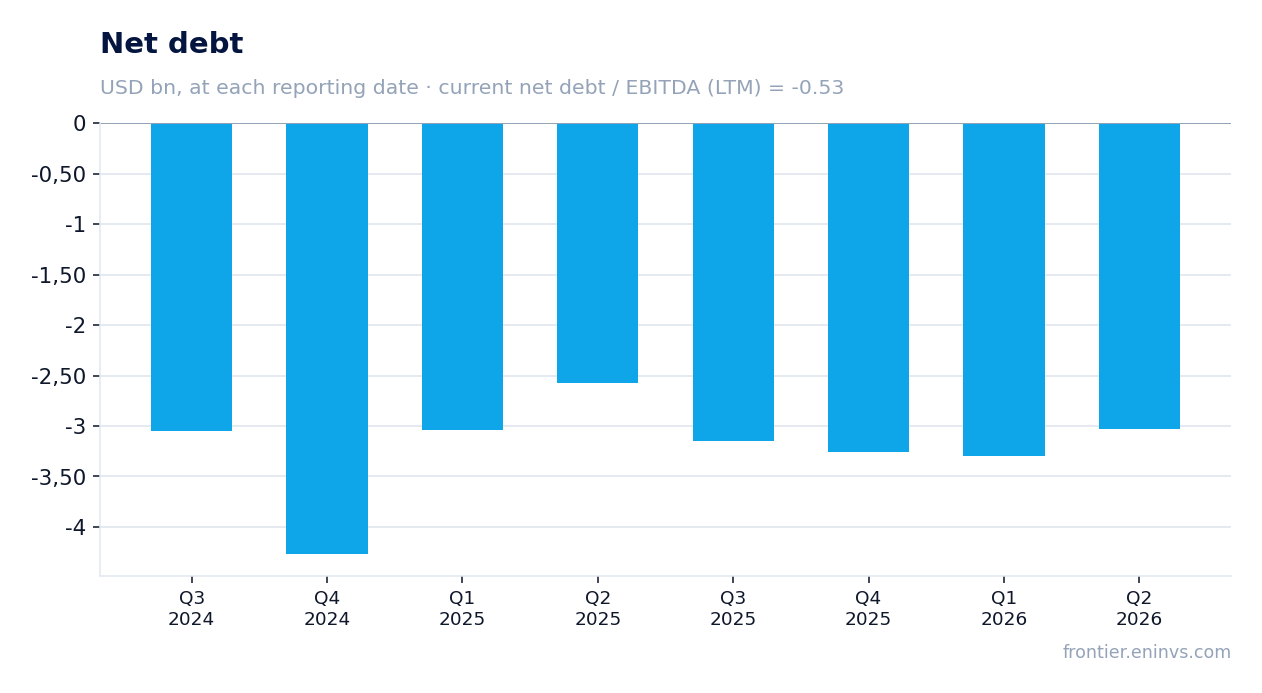
— Net debt is negative at minus USD 3,032.1 million; net debt/EBITDA LTM is minus 0.53
— P/E LTM of 14.9 and EV/EBITDA LTM of 7.5 are below their own historical averages
Attractiveness
Key figures, USD bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 3.60 | 3.97 | +10.1% |
| EBITDA | 1.09 | 1.25 | +14.5% |
| Operating profit | 0.79 | 0.95 | +20.6% |
| Net profit | 0.50 | 0.68 | +36.7% |
| Operating cash flow | 0.55 | 0.93 | +69.6% |
| Capex | 0.20 | 0.17 | -11.2% |
| EBITDA margin | 30.3% | 31.5% | +1.2 pp |
| Net margin | 13.9% | 17.2% | +3.3 pp |
Q2 revenue grew 10.1% YoY to USD 3,967.8 million
In Q2 2026, Ambev's revenue reached USD 3,967.8 million, up 10.1% YoY. This continues the acceleration: Q1 growth was 11.8%, and Q4 2025 saw 42.6% growth.
Growth was driven by all key markets, especially Brazil, where beer volumes recovered after a period of stagnation. The company also benefited from improved pricing and a favorable currency environment.
EBITDA margin expanded 1.2 pp to 31.5% on operating leverage
Q2 EBITDA grew 14.5% YoY to USD 1,251.7 million, with margin at 31.5% versus 30.3% a year earlier. Margin expansion came from operating leverage: revenue grew faster than fixed costs.
The company also contained raw material and logistics costs, preserving profitability despite inflation.
Net profit rose 36.7% YoY to USD 684.2 million, helped by a lower effective tax rate
Quarterly net profit was USD 684.2 million, up 36.7% YoY. Profit growth outpaced EBITDA significantly, due to a lower effective tax rate and the absence of one-off write-offs that occurred last year.
Net margin expanded to 17.2% from 13.9% a year earlier. This indicates improved earnings quality, though part of the effect may be one-off.
Quarterly free cash flow of USD 754.5 million covers dividends
Q2 operating cash flow was USD 927.8 million, capex USD 173.3 million, resulting in free cash flow of USD 754.5 million.
This is sufficient to cover dividends: over the last 12 months, the company paid about USD 140 million in dividends (based on a 0.3% yield and market cap of USD 46,930.6 million). Cash generation is stable, supporting payouts.
Trailing dividend yield of 0.3% is below the key rate
Over the last 12 months, Ambev paid dividends yielding 0.3% of the current price. This is well below risk-free yields, making the stock unattractive for income-focused investors.
However, the company historically pays out a significant portion of earnings, and payouts could increase if profits stay at current levels. The decision depends on the board and funding needs.
Net debt is negative at minus USD 3,032.1 million; net debt/EBITDA LTM is minus 0.53
At the end of Q2, net debt was minus USD 3,032.1 million, meaning the company holds a net cash position. Net debt/EBITDA LTM stood at minus 0.53.
During the quarter, the net cash position declined by USD 0.3 billion, but over the year it increased by USD 0.5 billion. The company retains financial flexibility for investments and shareholder returns.
P/E LTM of 14.9 and EV/EBITDA LTM of 7.5 are below their own historical averages
Current P/E LTM is 14.9, EV/EBITDA LTM is 7.5. These multiples are below their three-year averages, suggesting undervaluation relative to its own history.
According to the portal's model, the stock has +12% upside. Key risks to valuation include slowing revenue or margin growth and higher tax burden.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 46.9 bn USD |
| P/E (LTM) | 14.9 |
| EV/EBITDA (LTM) | 7.5 |
| P/B | 2.89 |
| Net debt / EBITDA (LTM) | -0.53 |
| Operating cash flow (LTM) | 4.50 bn |
| ROE | 15.4% |
| Dividend yield (12m) | 0.3% |
Bottom line
In Q2, Ambev delivered solid growth: revenue and EBITDA rose at double-digit rates, margins expanded, and net profit grew 36.7% thanks to a tax effect. The company generates stable free cash flow and has negative net debt, providing a strong financial cushion. However, the dividend yield is extremely low, limiting appeal for income investors. Still, valuation is below historical averages, and the portal's model implies 12% upside, making the shares attractive.
Open the company's financial profile ABEV →
See also: market overview · valuation map · stock screeners