Itau Unibanco: Q2 2026 EBITDA up 106.8%, but net interest income is the main driver
On August 25, Itau Unibanco reported Q2 2026 results. Net interest income rose 6.9% YoY to $19,706.8 million, while EBITDA surged 106.8% to $5,392.0 million. At the current price, the share looks attractive: ROE of 19.3%, dividend yield of 7.0%, and the portal's model implies 7% upside.
Key takeaways
— Net interest income in Q2 2026 rose 6.9% YoY to $19,706.8 million
— EBITDA in Q2 2026 jumped 106.8% YoY to $5,392.0 million
— Operating profit in Q2 2026 reached $2,810.9 million, up 62.3% from a year earlier
— Dividend yield over the trailing twelve months is 7.0% at the current price
— ROE over the trailing twelve months is 19.3%, supporting the share valuation
— Capital expenditure in Q2 2026 was $333.8 million, below the average of the previous four quarters
— The portal's model implies 7% upside from the current price
Attractiveness
Key figures, USD bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| EBITDA | 2.61 | 5.39 | +106.8% |
| Operating profit | 1.73 | 2.81 | +62.3% |
| Capex | 0.32 | 0.33 | +4.3% |
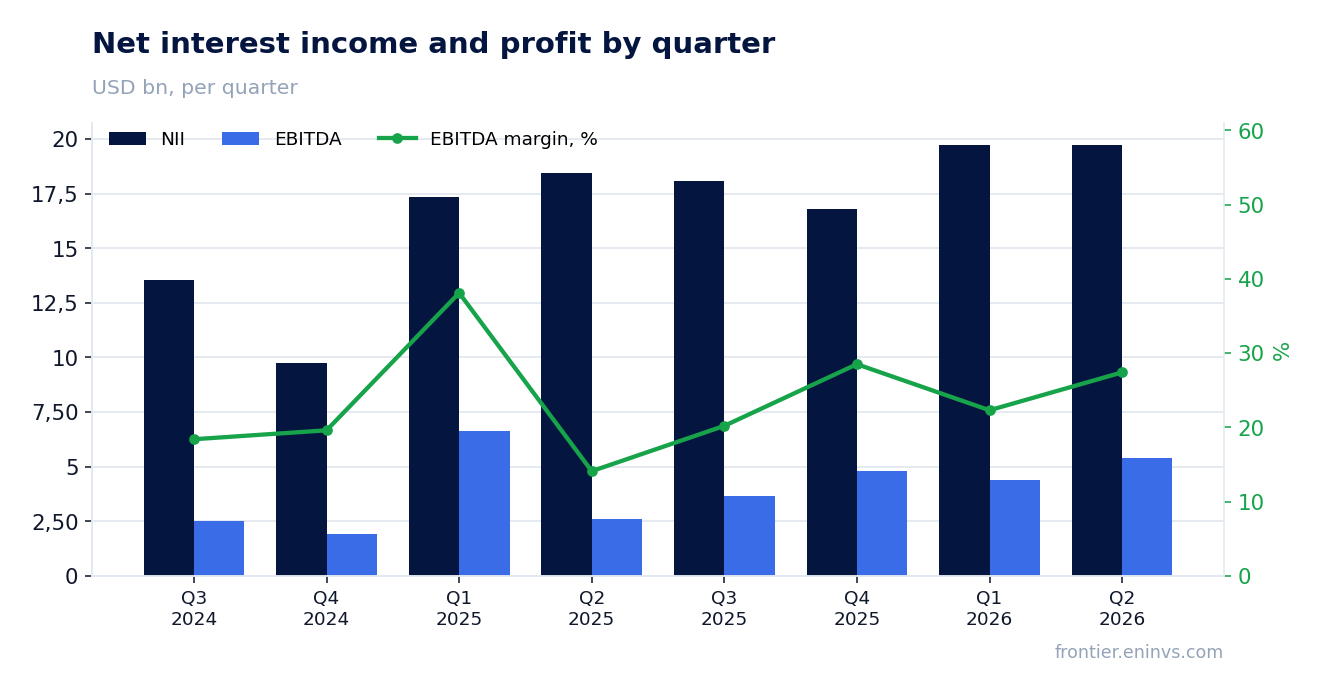
Net interest income in Q2 2026 rose 6.9% YoY to $19,706.8 million
In Q2 2026, Itau Unibanco's net interest income reached $19,706.8 million, up 6.9% from the same quarter a year earlier. Growth slowed from 13.8% in Q1 2026 but remained positive.
Over the trailing twelve months, net interest income reached $70,700.0 million. This is the base on which the bank's entire profit is built: interest margin remains the main source of income.
EBITDA in Q2 2026 jumped 106.8% YoY to $5,392.0 million
EBITDA for Q2 2026 rose 106.8% YoY to $5,392.0 million. This is a sharp acceleration compared with previous quarters: growth was more modest in Q1 2026, and EBITDA in Q2 2025 was $2,607.0 million.
The jump in EBITDA amid moderate growth in net interest income suggests operating expenses grew slower than revenues or that there were one-off factors. The company does not disclose details in the report, so the exact reason cannot be identified.
Operating profit in Q2 2026 reached $2,810.9 million, up 62.3% from a year earlier
Operating profit in Q2 2026 was $2,810.9 million versus $1,732.3 million in Q2 2025. The 62.3% increase is the strongest in the last four quarters.
Operating profit is growing faster than revenue, indicating improved operating efficiency. However, part of the growth may be due to one-off items not disclosed in the report.
Dividend yield over the trailing twelve months is 7.0% at the current price
Over the trailing twelve months, Itau Unibanco paid dividends that, at the current market capitalization of $91,630.4 million, yield 7.0%. This is above the average yield for the Brazilian market and makes the share attractive for income-oriented investors.
The size of future payouts will depend on profit and the bank's policy. With ROE of 19.3%, the bank generates sufficient profit to sustain dividends, but if the economic situation deteriorates, payouts could be reduced.
ROE over the trailing twelve months is 19.3%, supporting the share valuation
Return on equity over the trailing twelve months was 19.3%. This is a high figure for the banking sector, confirming the bank's ability to use capital efficiently.
High ROE combined with a dividend yield of 7.0% gives a total shareholder return of over 26% per annum, well above the cost of capital.
Capital expenditure in Q2 2026 was $333.8 million, below the average of the previous four quarters
Capital expenditure in Q2 2026 was $333.8 million. For comparison, in Q1 2026 it was $842.7 million, and the average over the previous four quarters was about $457 million.
The low capex in the reported quarter means the bank is spending less on development, which could support free cash flow and dividends. However, if this is a one-off reduction, capex may return to higher levels in subsequent quarters.
The portal's model implies 7% upside from the current price
Our model, based on annual earnings relative to market capitalization, i.e., ROE versus P/B, values the share at 7% above the current price. This is moderate upside, which combined with a dividend yield of 7.0% gives an expected total return of about 14%.
The valuation is sensitive to ROE dynamics: if return on equity remains at 19.3%, the share will trade at a slight discount to fair value. A decline in ROE or a worsening macroeconomic situation in Brazil could offset this potential.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 91.6 bn USD |
| P/B | 0.21 |
| ROE | 19.3% |
| Dividend yield (12m) | 7.0% |
Bottom line
The Q2 2026 report showed strong growth in EBITDA and operating profit, but with moderate growth in net interest income. The bank maintains high return on equity (ROE of 19.3%) and offers a dividend yield of 7.0%, making the share attractive for long-term investors. The portal's model implies 7% upside, which combined with dividends gives an expected return of about 14%. The key question for a holder is whether the bank can sustain revenue growth and ROE at current levels, or whether the slowdown in interest income becomes a trend.
Open the company's financial profile ITUB →
See also: market overview · valuation map · stock screeners