Magazine Luiza: revenue up 7%, but Q2 loss widened again
On 30 July 2026, Magazine Luiza reported results for the second quarter of 2026. Revenue rose 7.0% year on year to USD 1,752.4 million, EBITDA added 7.9% to USD 133.0 million, but the net loss widened to USD 14.3 million from USD 4.4 million a year earlier. Leverage remains moderate: net debt to EBITDA for the trailing twelve months stands at 0.95. At the current price the share looks rather attractive: the portal's model implies 37% upside to fair value, and the EV/EBITDA multiple of 2.46 is below its three-year average.
Key takeaways
— Q2 revenue grew 7.0% year on year but slowed from 9.8% in Q1
— EBITDA added 7.9%, with the margin nearly flat at 7.6% versus 7.5% a year earlier
— The net loss widened to USD 14.3 million, marking the second consecutive quarter of negative earnings
— Operating cash flow for the quarter reached USD 967.9 million, well above the year-earlier level
— Leverage remains low: net debt to EBITDA for the trailing twelve months stands at 0.95
— The trailing twelve-month dividend yield is 1.46%, below the key rate
— The EV/EBITDA multiple of 2.46 is below its three-year average, and the portal's model implies 37% upside
Attractiveness
Key figures, USD bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 1.64 | 1.75 | +7.0% |
| EBITDA | 0.12 | 0.13 | +7.9% |
| Operating profit | 0.07 | 0.07 | +2.3% |
| Net profit | -0.00 | -0.01 | — |
| Operating cash flow | 0.72 | 0.97 | +34.0% |
| Capex | 0.04 | 0.03 | -17.5% |
| EBITDA margin | 7.5% | 7.6% | +0.1 pp |
| Net margin | -0.3% | -0.8% | -0.5 pp |
Q2 revenue grew 7.0% year on year but slowed from 9.8% in Q1
Magazine Luiza's revenue in Q2 2026 reached USD 1,752.4 million, up 7.0% year on year. For comparison, Q1 growth was 9.8%, indicating a slowdown. The main contribution likely came from retail sales and the online segment, though the facts do not provide a breakdown.
The slowdown may reflect a high base effect from last year, when Q2 2025 revenue grew 2.0%. In contrast, Q1 2026 growth was higher due to a weaker Q1 2025 base. This is normal volatility, and one quarter does not set a trend.
Nevertheless, the company continues to expand, and the current revenue level exceeds that of previous quarters. The next report will show whether the slowdown persists or is a one-off.
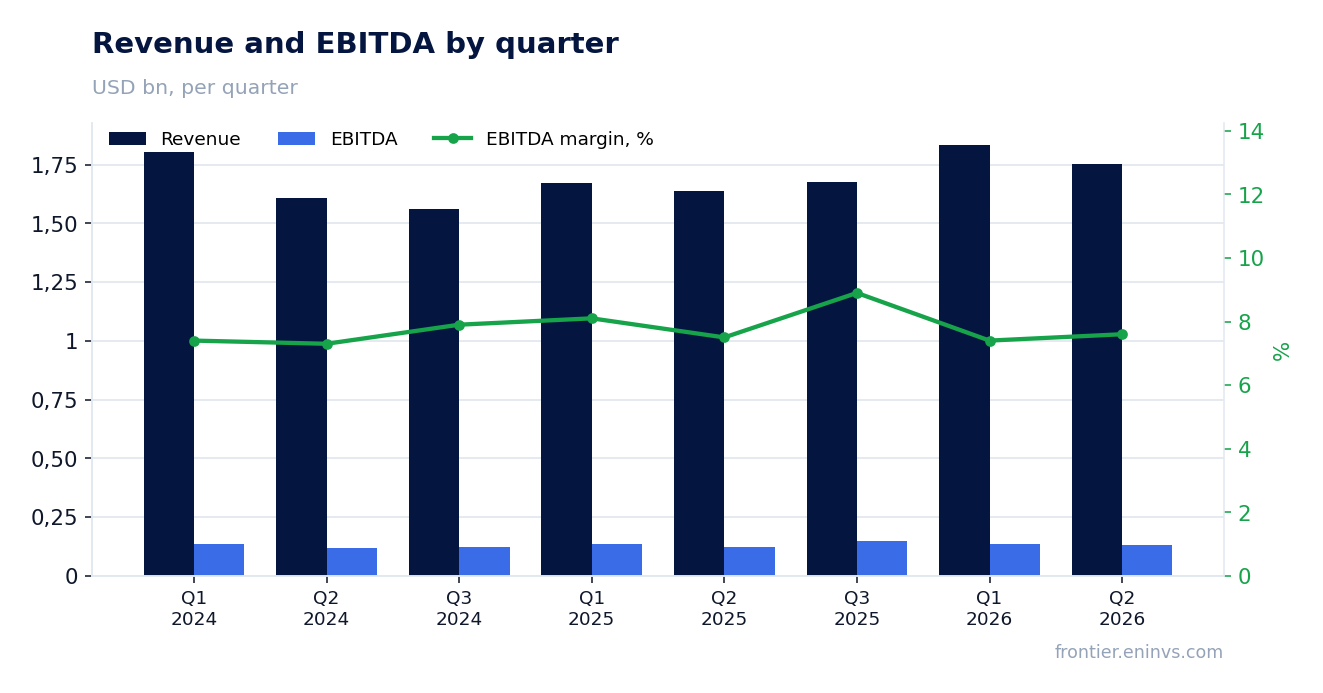
EBITDA added 7.9%, with the margin nearly flat at 7.6% versus 7.5% a year earlier
EBITDA in Q2 2026 was USD 133.0 million, up 7.9% year on year. The EBITDA margin was essentially unchanged at 7.6% versus 7.5% in Q2 2025, indicating stable operating efficiency.
Operating profit reached USD 67.7 million, also above the year-earlier level. However, the growth in EBITDA and operating profit did not translate into net profit due to financial expenses and possibly other factors not disclosed in the facts.
Maintaining the margin at the previous level amid revenue growth is a positive signal, but to improve profitability the company needs either further revenue growth or cost reduction below the current level.
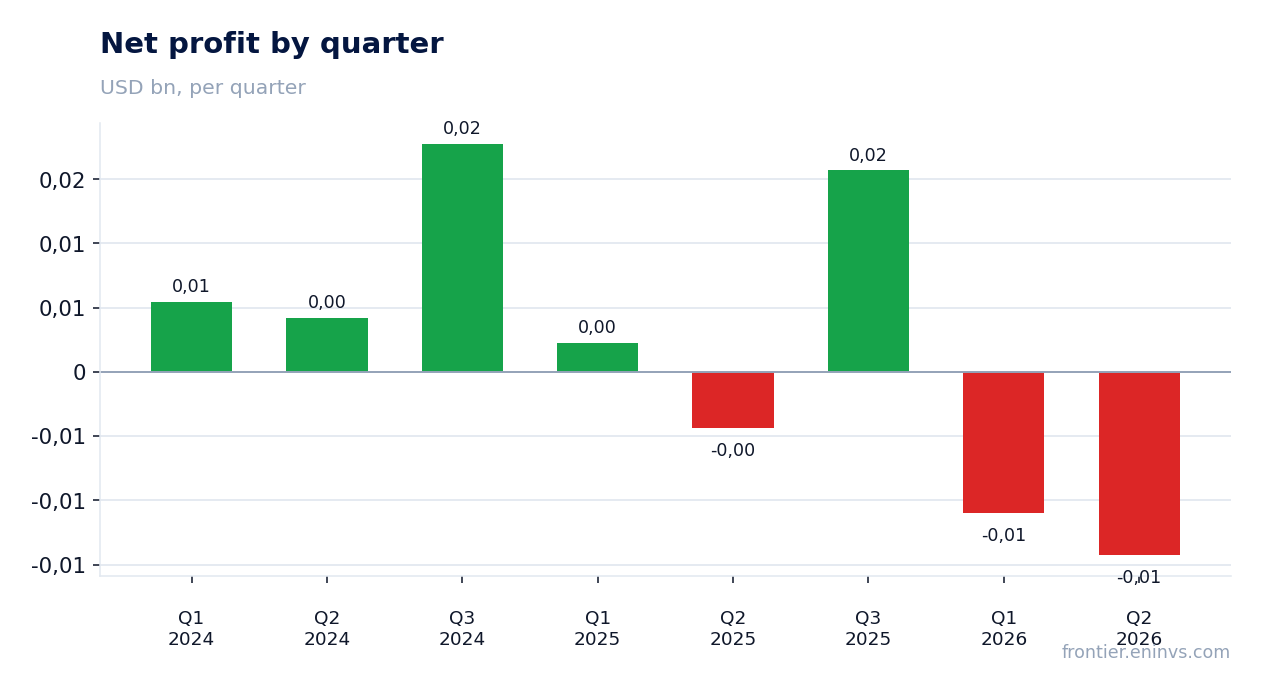
The net loss widened to USD 14.3 million, marking the second consecutive quarter of negative earnings
Magazine Luiza's net loss in Q2 2026 was USD 14.3 million, compared with a loss of USD 4.4 million a year earlier. This is the second consecutive quarter with a negative bottom line: in Q1 2026 the loss was USD 11.0 million.
The net margin deteriorated to -0.8% from -0.3% a year earlier. The reason is faster growth of expenses below operating profit, likely financial and tax expenses. Details are not provided in the facts.
The loss is still small relative to revenue, but its accumulation could limit the company's ability to pay dividends and invest. Over the trailing twelve months, net profit remains positive at USD 37.4 million, suggesting that the Q2 loss is not chronic.
Operating cash flow for the quarter reached USD 967.9 million, well above the year-earlier level
Operating cash flow in Q2 2026 reached USD 967.9 million, significantly above the Q2 2025 figure of USD 722.5 million. This inflow allows the company to fund investments and service debt.
Capital expenditures for the quarter were USD 30.5 million, down from USD 37.0 million a year earlier. Lower capex combined with higher operating cash flow boosts free cash flow, which can be directed to dividends or debt reduction.
However, operating cash flow can be volatile due to changes in working capital. In Q1 2026 it was USD 899.2 million, also above the year-earlier level. Consistently high cash flow is a positive factor for credit quality.
Leverage remains low: net debt to EBITDA for the trailing twelve months stands at 0.95
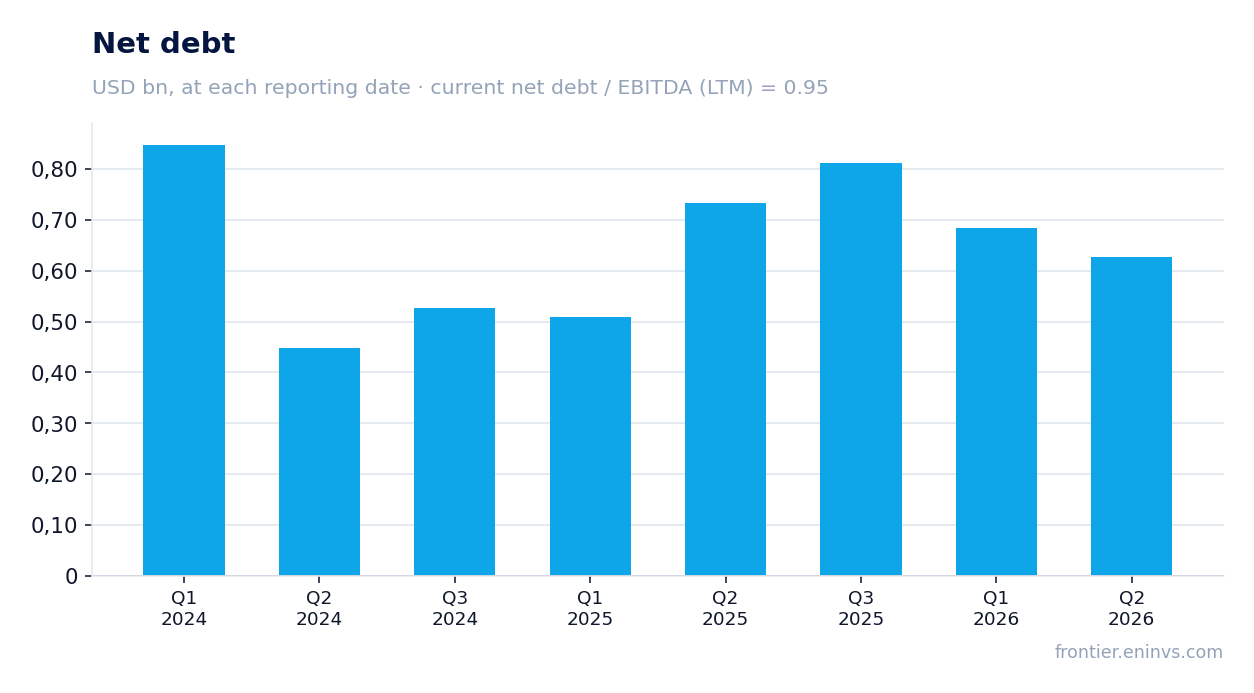
Net debt at the latest reporting date was USD 531.2 million, and the net debt to EBITDA ratio for the trailing twelve months was 0.95. This is a moderate level that does not pose significant risks to financial stability.
During the quarter, net debt decreased by RUB 0.1 billion, and over the trailing twelve months also by RUB 0.1 billion. The reduction in debt alongside EBITDA growth supports credit metrics.
Interest expenses are not disclosed, but with such leverage they are likely not excessive. Low debt gives the company freedom for investments and shareholder payouts.
The trailing twelve-month dividend yield is 1.46%, below the key rate
The trailing twelve-month dividend yield is 1.46%. This is a low level, especially compared to fixed-income instruments. The company likely directs most of its profit to business development.
With net profit of USD 37.4 million over the trailing twelve months and a market capitalisation of USD 837.6 million, dividend payments amount to about USD 12.2 million. This is a moderate share of profit, allowing funds to be retained for investment.
Dividends could grow in the future if net profit increases. However, the current yield is unlikely to attract income-oriented investors. They may find other securities more appealing.
The EV/EBITDA multiple of 2.46 is below its three-year average, and the portal's model implies 37% upside
The current EV/EBITDA multiple is 2.46, below its three-year average. This may indicate that the share is undervalued relative to its own history. The trailing P/E is 22.4, which also does not look stretched.
The portal's model estimates 37% upside to fair value. This is our own estimate, based on EBITDA growth and a target multiple. It is not a market consensus or a target price.
The combination of low EV/EBITDA, moderate leverage and positive operating cash flow makes the share attractive for investors willing to accept the risk of a continuing net loss.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 0.84 bn USD |
| P/E (LTM) | 22.4 |
| EV/EBITDA (LTM) | 2.5 |
| P/B | 0.41 |
| Net debt / EBITDA (LTM) | 0.95 |
| Operating cash flow (LTM) | 2.90 bn |
| ROE | -2.6% |
| Dividend yield (12m) | 1.5% |
Bottom line
Bottom line: Magazine Luiza delivered revenue and EBITDA growth while maintaining its margin, but the net loss widened. Operating cash flow remains strong, and leverage is low. The share looks rather attractive: the EV/EBITDA multiple is below its historical average, and the portal's model implies 37% upside. However, a return to net profit in the coming quarters is needed to confirm the trend.
Open the company's financial profile MGLU →
See also: market overview · valuation map · stock screeners