Rumo: profit up 71%, but 3.18x LTM EBITDA leverage leaves little room to manoeuvre
Rumo has reported its results for the second quarter of 2026. Revenue rose 16.6% year on year to USD 775.9 million, EBITDA increased 22.4% to USD 413.3 million, and net profit jumped 71.2% to USD 102.4 million. The EBITDA margin improved to 53.3% from 50.7% a year earlier, while the net margin rose to 13.2% from 9.0%. Leverage remains high at 3.18x LTM EBITDA. At the current price, the stock trades at 22.3x LTM earnings and 8.9x LTM EBITDA, while the portal's model implies 20% upside to fair value. Given the strong profit dynamics, but high debt load and limited revenue growth, the stock looks rather attractive.
Key takeaways
— Revenue rose 16.6% year on year to USD 775.9 million, but growth slowed from 23.9% in Q1 2026
— EBITDA increased 22.4% year on year, with the margin rising to 53.3% from 50.7% a year earlier
— Net profit jumped 71.2% year on year to USD 102.4 million, and the net margin reached 13.2% versus 9.0% a year earlier
— Operating cash flow for the quarter was USD 429.9 million, but capital expenditures of USD 314.5 million consumed most of it
— Leverage remains high: net debt of USD 3,437.2 million, or 3.18x LTM EBITDA
— Dividend yield over the last 12 months is 0.74%, below the yield on many debt instruments
— Valuation: 22.3x LTM P/E and 8.9x LTM EV/EBITDA, while the portal's model implies 20% upside to fair value
Attractiveness
Key figures, USD bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 0.67 | 0.78 | +16.6% |
| EBITDA | 0.34 | 0.41 | +22.4% |
| Operating profit | 0.24 | 0.31 | +31.1% |
| Net profit | 0.06 | 0.10 | +71.2% |
| Operating cash flow | 0.39 | 0.43 | +10.4% |
| Capex | 0.25 | 0.31 | +25.7% |
| EBITDA margin | 50.7% | 53.3% | +2.6 pp |
| Net margin | 9.0% | 13.2% | +4.2 pp |
Revenue rose 16.6% year on year to USD 775.9 million, but growth slowed from 23.9% in Q1 2026
In the second quarter of 2026, Rumo's revenue reached USD 775.9 million, up 16.6% year on year. This marks a significant acceleration from 4.5% growth in Q2 2025, but a slowdown from 23.9% in Q1 2026. Quarterly revenue was a record for recent periods, surpassing USD 709.6 million in Q3 2025.
The growth was likely driven by higher transportation volumes and improved tariffs, although segment details are not available in the provided data. Notably, revenue is growing slower than EBITDA and net profit, indicating faster margin expansion.
Over the last 12 months, revenue amounted to USD 2,800.0 million. This is below the sum of the last four quarters, reflecting seasonal fluctuations and changes in cargo mix. Nevertheless, the company demonstrates the ability to grow revenue even amid volatility in the rail freight market.
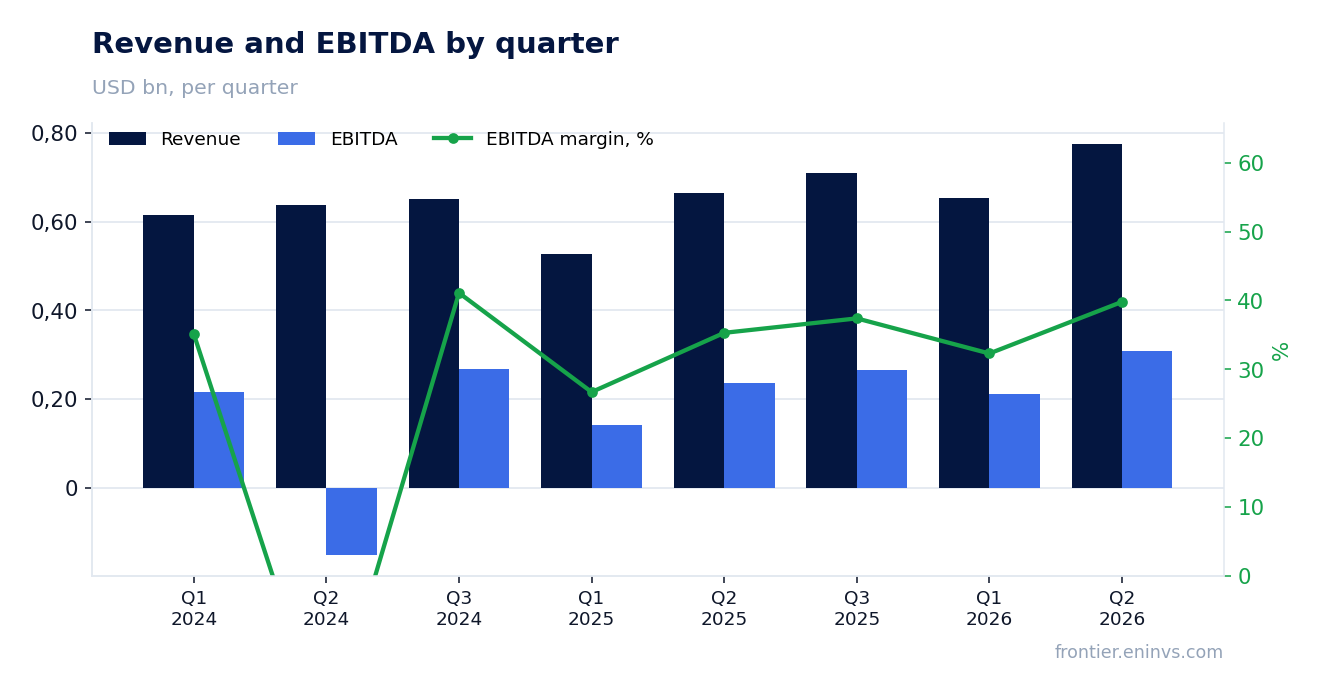
EBITDA increased 22.4% year on year, with the margin rising to 53.3% from 50.7% a year earlier
EBITDA in Q2 2026 rose 22.4% year on year to USD 413.3 million. The EBITDA margin reached 53.3%, up 2.6 percentage points from 50.7% a year earlier. This is the highest margin level in at least five quarters.
The margin improvement came on the back of revenue growth and likely lower unit operating costs. However, a breakdown of expenses is not provided, so it is impossible to say exactly which line contributed most. Importantly, EBITDA is growing faster than revenue, indicating positive operating leverage.
Over the last 12 months, EBITDA amounted to USD 924.1 million. This is below the sum of the last four quarters, explained by weaker results in earlier periods. The current quarterly figure is a record for the period under review, confirming improved operational efficiency.
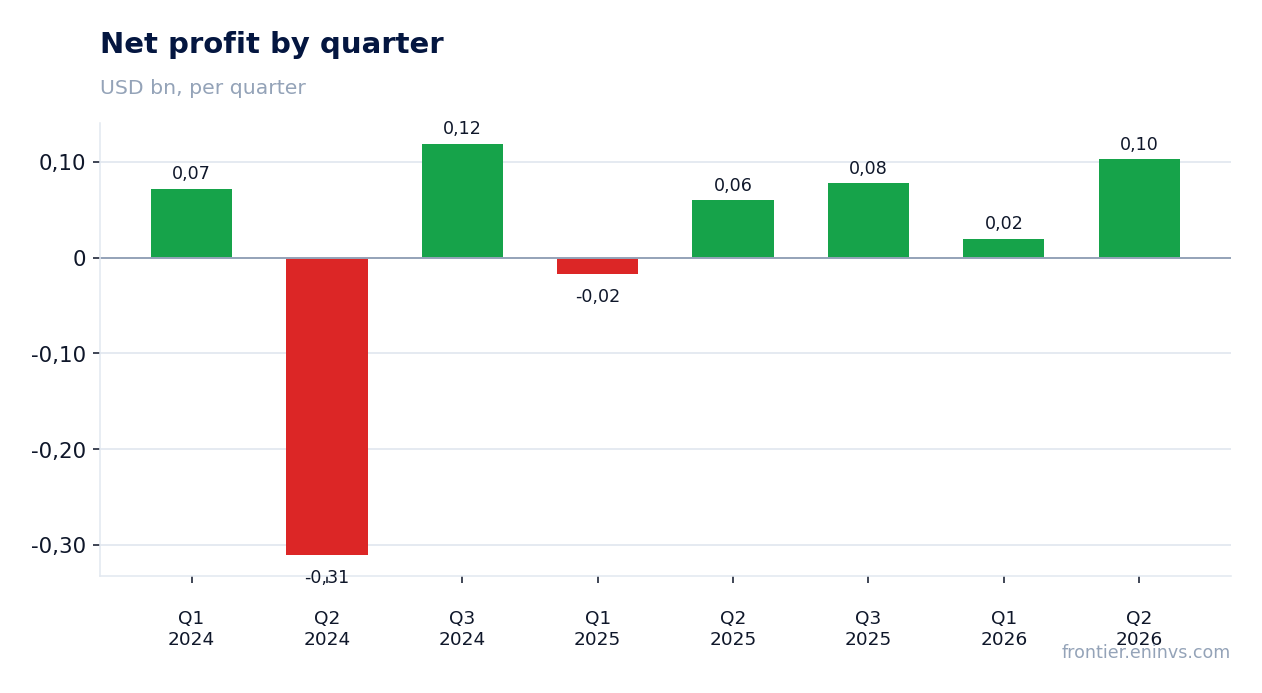
Net profit jumped 71.2% year on year to USD 102.4 million, and the net margin reached 13.2% versus 9.0% a year earlier
Net profit in Q2 2026 was USD 102.4 million, up 71.2% from USD 59.8 million a year earlier. The net margin rose to 13.2% from 9.0% a year earlier. This is a significant improvement, partly driven by higher operating profit and possibly by financial leverage.
Operating profit in the reporting period was USD 308.5 million, up 31.1% from USD 235.3 million a year earlier. Operating profit growth outpaces revenue growth, confirming improved profitability at the operating level. However, net profit is also affected by interest expenses and taxes, which are not detailed.
Over the last 12 months, net profit amounted to USD 237.3 million. This is below the sum of the last four quarters, due to a loss in Q2 2024. The current quarterly result is one of the best in recent periods, indicating a recovery in profitability.
Operating cash flow for the quarter was USD 429.9 million, but capital expenditures of USD 314.5 million consumed most of it
Operating cash flow in Q2 2026 was USD 429.9 million, up 10.4% from USD 389.4 million a year earlier. However, capital expenditures rose to USD 314.5 million from USD 250.1 million a year earlier. As a result, free cash flow (operating cash flow minus capex) was USD 115.4 million, significantly lower than USD 139.3 million a year earlier.
The 25.7% year-on-year increase in capex reflects ongoing investments in infrastructure and rolling stock. This is necessary to maintain and expand operations, but it limits the ability to pay dividends and reduce debt. Over the last 12 months, operating cash flow amounted to USD 1,300.0 million, below the sum of the last four quarters.
Free cash flow remains positive, but it is insufficient to significantly reduce debt. The company must balance growth investments with debt servicing, which could constrain dividend payments in the future.
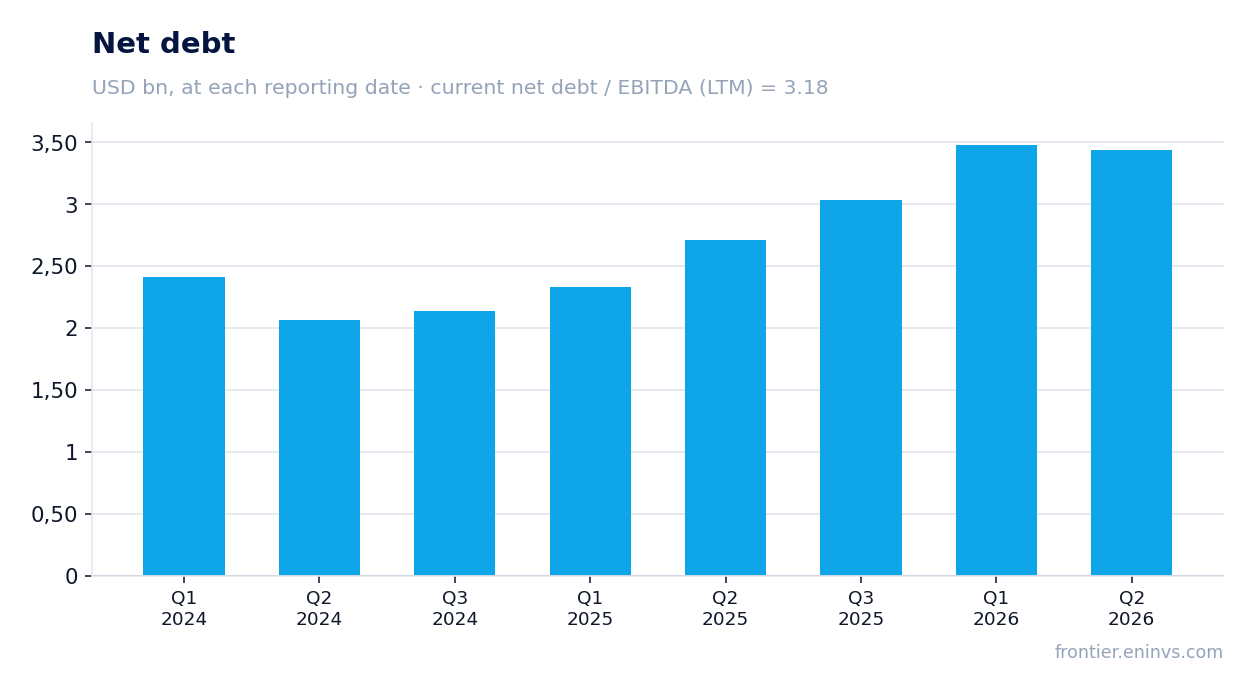
Leverage remains high: net debt of USD 3,437.2 million, or 3.18x LTM EBITDA
Net debt at the end of Q2 2026 was USD 3,437.2 million, up by RUB 0.7 billion over 12 months. The net debt to LTM EBITDA ratio stands at 3.18x. This is a high level that limits the company's financial flexibility.
For comparison, at the end of Q1 2026 net debt was USD 3,481.1 million, meaning it slightly decreased over the quarter. However, on a yearly basis, debt has increased. Interest expenses are not detailed, but with such a load, they can significantly impact net profit.
High leverage requires stable operating cash flow to service debt. The company generates sufficient operating cash flow, but a significant portion goes to capital expenditures, limiting the ability to reduce debt. This is a key risk for shareholders.
Dividend yield over the last 12 months is 0.74%, below the yield on many debt instruments
The dividend yield over the last 12 months is 0.74%. This is a low level that does not compensate for the risks associated with high leverage and profit volatility. For comparison, yields on risk-free instruments in Russia can be higher, making the company's dividend history less attractive for income-oriented investors.
The company does not disclose its dividend policy in the provided data, but the low yield may be a consequence of high debt load and the need to allocate funds to capital expenditures. In the future, if free cash flow grows, dividends may increase, but for now this is not a primary factor of investment appeal.
It is worth noting that the dividend yield is calculated based on the current share price and payments over the last 12 months. If profit continues to grow and leverage decreases, dividend payments may be revised upwards.
Valuation: 22.3x LTM P/E and 8.9x LTM EV/EBITDA, while the portal's model implies 20% upside to fair value
Currently, Rumo's shares trade at 22.3x LTM P/E and 8.9x LTM EV/EBITDA. Market capitalisation is USD 5,290.3 million. While historical comparison data is not available, the current multiples appear moderate for a company with growing profits and high profitability.
The portal's model estimates 20% upside to fair value. This is based on projected EBITDA growth and a target multiple. If the company can maintain current profit growth rates and gradually reduce leverage, the valuation could be revised upwards.
However, high leverage and limited free cash flow may constrain value growth. Investors should monitor EBITDA and debt dynamics in upcoming reports to assess the sustainability of the current trend.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 5.29 bn USD |
| P/E (LTM) | 22.3 |
| EV/EBITDA (LTM) | 8.9 |
| P/B | 2.06 |
| Net debt / EBITDA (LTM) | 3.18 |
| Operating cash flow (LTM) | 1.30 bn |
| ROE | 14.4% |
| Dividend yield (12m) | 0.7% |
Bottom line
Bottom line: Rumo delivered strong results in Q2 2026 – revenue up 16.6%, EBITDA up 22.4%, net profit up 71.2%. Profitability improved, and operating cash flow remains positive. However, high leverage (3.18x LTM EBITDA) and low dividend yield (0.74%) limit the appeal. Valuation at 22.3x P/E and 8.9x EV/EBITDA appears fair, while the portal's model implies 20% upside. Given the strong profit dynamics but high debt-related risks, the stock looks rather attractive.
Open the company's financial profile RAIL →
See also: market overview · valuation map · stock screeners