Localiza: revenue up 36.7% but quarterly profit and cash flow diverge
On 25 August Localiza released its second-quarter 2026 results. Revenue rose 36.7% year on year to USD 2,427.4 million, EBITDA added 25.2% to USD 457.7 million, and net profit came in at USD 197.5 million against a loss of USD 30.2 million a year earlier. Operating cash flow for the quarter was negative, at minus USD 348.9 million. In our view the share looks attractive: an EV/EBITDA of 8.46, earnings per share of 11.43 and a dividend yield of 5.85% leave room, and the portal's model puts the upside to fair value at +24%.
Key takeaways
— Revenue in Q2 2026 grew 36.7% year on year to USD 2,427.4 million – the second consecutive quarter above 35% growth
— EBITDA added 25.2% but its margin fell to 30.5% from 33.3% a year earlier – growth is costing more
— Net profit in Q2 2026 was USD 197.5 million against a loss of USD 30.2 million a year earlier, while over the last twelve months it stands at USD 662.9 million
— Operating cash flow for the quarter was negative at minus USD 348.9 million, even though over the last twelve months it is USD 392.0 million
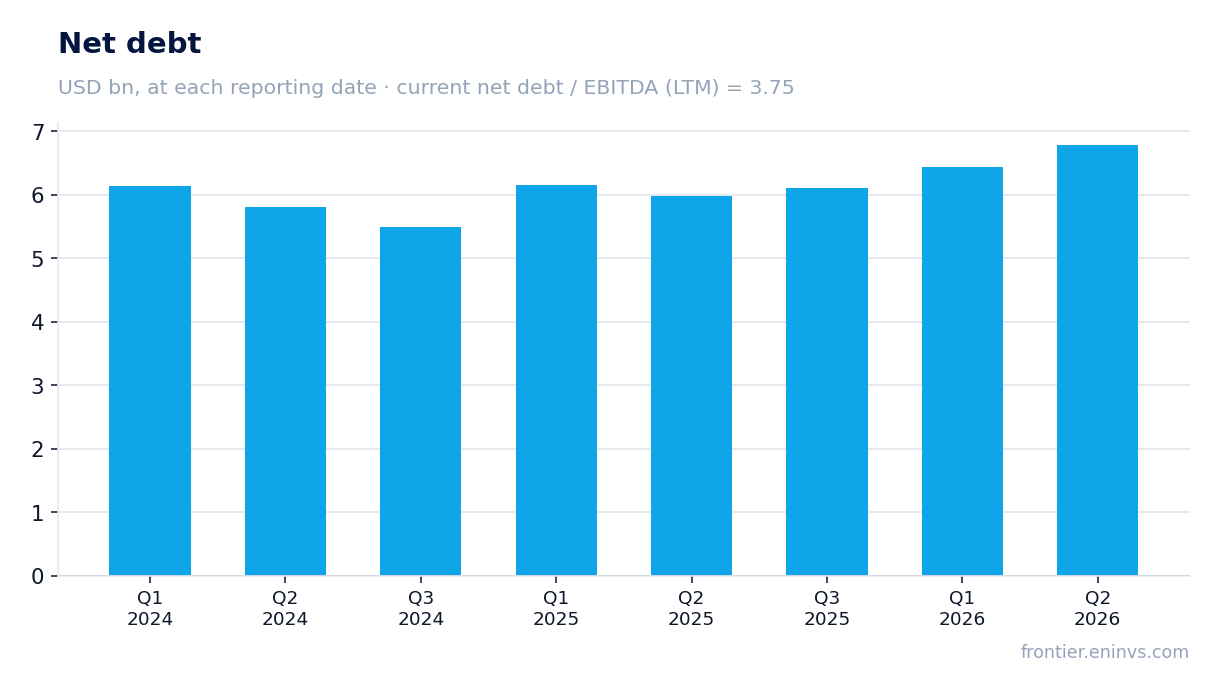
— Net debt rose to USD 6,791.3 million and its ratio to LTM EBITDA is 3.75 – a level, not a direction
— The trailing twelve-month dividend yield is 5.85%, above many instruments' current yields, but the payout depends on profit and investment
— On the portal's model the upside to fair value is +24%, which together with an EV/EBITDA of 8.46 supports the share's attractiveness
Attractiveness
Key figures, USD bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 1.78 | 2.43 | +36.7% |
| EBITDA | 0.59 | 0.74 | +25.2% |
| Operating profit | 0.36 | 0.46 | +26.3% |
| Net profit | -0.03 | 0.20 | в прибыль |
| Operating cash flow | 0.29 | -0.35 | -219.2% |
| Capex | 0.02 | 0.05 | +196.1% |
| EBITDA margin | 33.3% | 30.5% | -2.8 pp |
| Net margin | -1.7% | 8.1% | +9.8 pp |
Revenue in Q2 2026 grew 36.7% year on year to USD 2,427.4 million – the second consecutive quarter above 35% growth
Localiza's revenue in Q2 2026 was USD 2,427.4 million, up 36.7% year on year. This continues an acceleration: growth was 35.7% in Q1 2026 and 18.7% in Q4 2025. The company has been gaining speed for two consecutive quarters, and the current pace is more than double the average growth in 2024–2025.
Such revenue growth is the key fact of the report. It means the business is scaling faster than in previous periods, creating a base for future profit. But how this growth converts into margin and cash is what matters – see below.
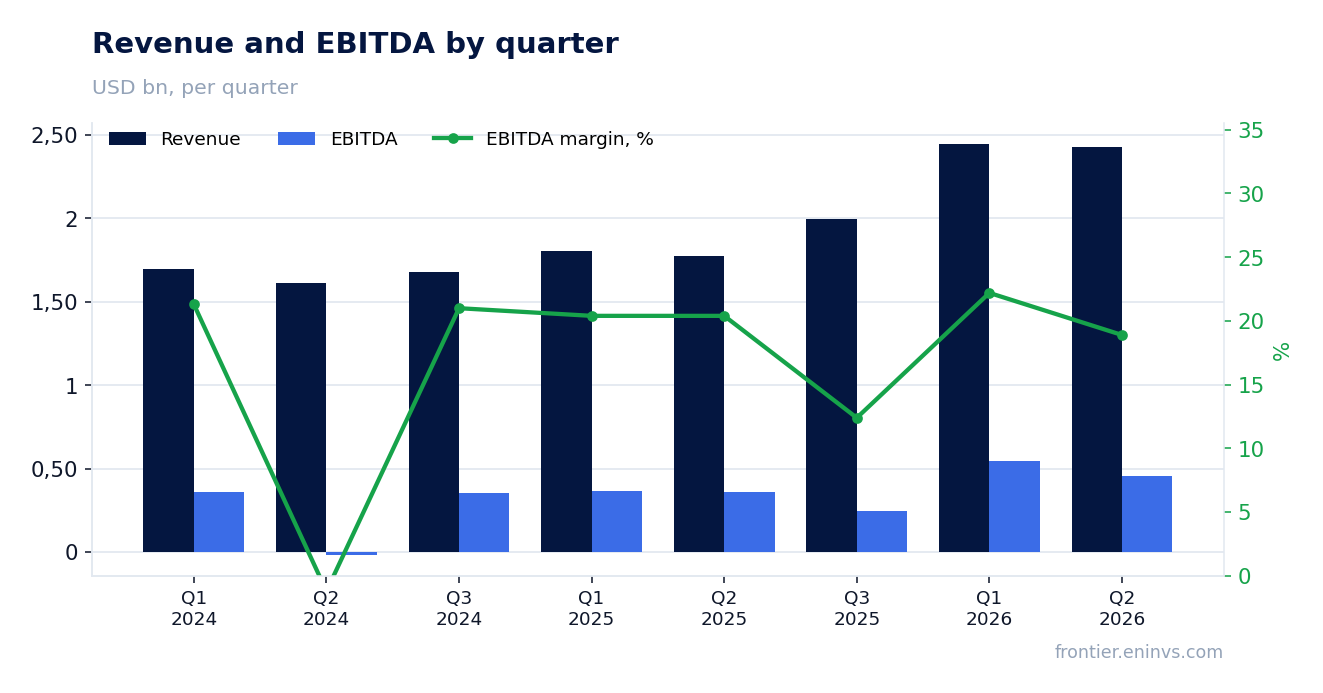
EBITDA added 25.2% but its margin fell to 30.5% from 33.3% a year earlier – growth is costing more
EBITDA in Q2 2026 was USD 457.7 million, up 25.2% year on year. However, the EBITDA margin fell to 30.5% from 33.3% in Q2 2025. This means costs are growing faster than revenue, and each dollar of sales brings less operating profit than a year ago.
The 2.8 percentage point margin decline is notable. It could be due to higher personnel, logistics or marketing costs, but the provided facts do not break down the cost lines. We note the fact: revenue growth of 36.7% is not matched by proportional EBITDA growth, which weighs on the bottom line.
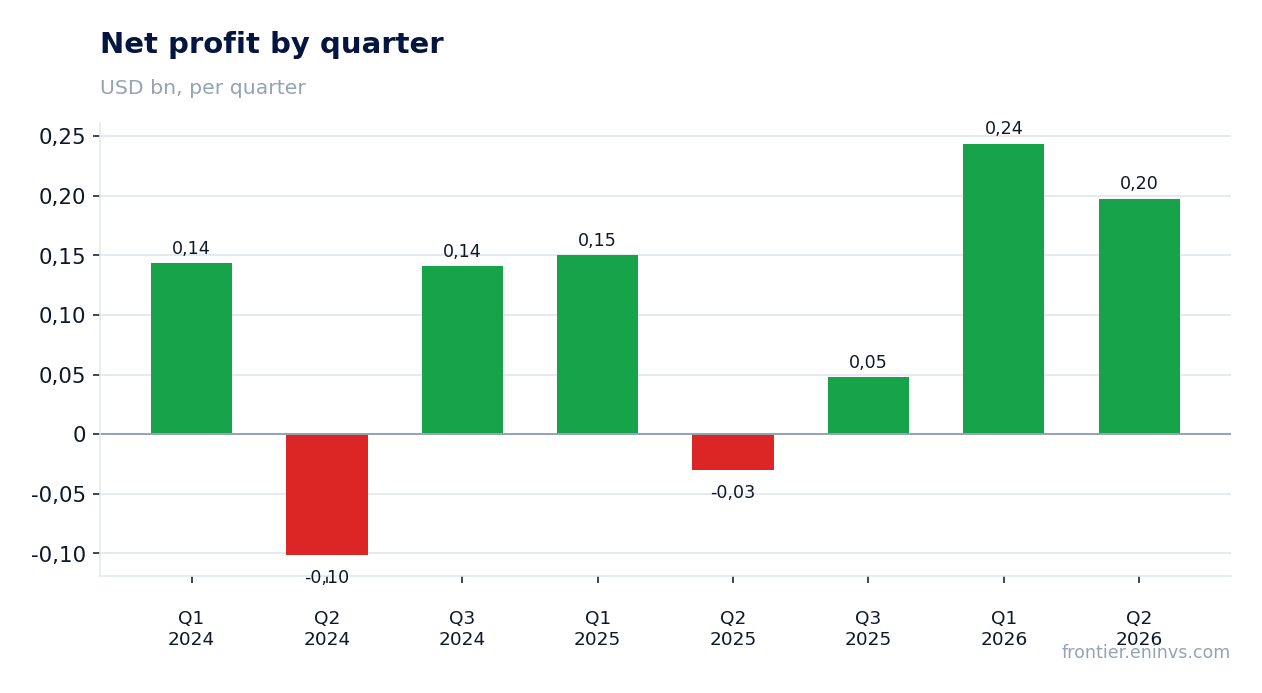
Net profit in Q2 2026 was USD 197.5 million against a loss of USD 30.2 million a year earlier, while over the last twelve months it stands at USD 662.9 million
Localiza's net profit in Q2 2026 was USD 197.5 million against a loss of USD 30.2 million in Q2 2025. The net margin turned positive at 8.1% versus minus 1.7% a year earlier. This is a swing from loss to profit, which is positive, but quarterly profit is lower than in Q1 2026 (USD 243.5 million) despite higher revenue.
Over the last twelve months net profit is USD 662.9 million. This is a trailing figure, not tied to a single quarter, and reflects the accumulated result. Importantly, the current quarterly result supports this level, but the gap between revenue and profit points to cost pressure and possibly one-off factors not detailed in the facts.
Operating cash flow for the quarter was negative at minus USD 348.9 million, even though over the last twelve months it is USD 392.0 million
Operating cash flow in Q2 2026 was negative at minus USD 348.9 million. This contrasts sharply with positive flow in previous quarters: USD 439.3 million in Q1 2026 and USD 292.7 million in Q2 2025. Negative flow means operations consumed cash rather than generated it.
Over the last twelve months operating cash flow remains positive at USD 392.0 million. However, the quarterly outflow is significant and could be tied to working capital growth or seasonal factors. Meanwhile, capital expenditure in Q2 rose to USD 45.3 million from USD 15.3 million a year earlier, adding pressure on free cash flow. Whether this outflow is sustainable remains an open question.
Net debt rose to USD 6,791.3 million and its ratio to LTM EBITDA is 3.75 – a level, not a direction
Localiza's net debt at the end of Q2 2026 was USD 6,791.3 million, up USD 0.4 billion from the previous reporting date and USD 0.8 billion over 12 months. The ratio of net debt to LTM EBITDA is 3.75. This is a level of leverage, and the facts do not provide a prior value for this ratio, so we cannot say whether it rose or fell.
A level of 3.75 is moderate for a capital-intensive business, but it requires stable EBITDA. Meanwhile, quarterly operating cash flow is negative, which could complicate debt servicing without new borrowing. However, over the last twelve months EBITDA is USD 1,608.8 million, covering debt about 4.2 times in absolute terms, providing a cushion.
The trailing twelve-month dividend yield is 5.85%, above many instruments' current yields, but the payout depends on profit and investment
Localiza's trailing twelve-month dividend yield is 5.85%. This is a notable level that may attract income-oriented investors. However, the facts do not provide the specific amount of the last dividend or the year for which it was paid, so we cannot assess its sustainability or compare it with the payout history.
Our estimate for the current year's dividend relies on profit and payout policy, but the facts do not include a payout ratio. If the company maintains the current yield, it will remain competitive versus risk-free rates. However, negative quarterly operating cash flow and rising capital expenditure could force the company to revise the payout downward if the outflow persists.
On the portal's model the upside to fair value is +24%, which together with an EV/EBITDA of 8.46 supports the share's attractiveness
According to the portal's model, Localiza's fair value implies an upside of +24% to the current price. This estimate is based on EBITDA growth multiplied by a target multiple and compared with market capitalisation. The model is not a market consensus or a target price; it is our own calculation.
The current LTM EV/EBITDA is 8.46 and P/E is 11.43. The facts do not provide a three-year average for these multiples, so we cannot say whether the current level is above or below its history. However, the absolute values look moderate for a company with growing revenue and profit. At the same time, negative cash flow and margin decline could limit re-rating.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 7.58 bn USD |
| P/E (LTM) | 11.4 |
| EV/EBITDA (LTM) | 8.5 |
| P/B | 1.62 |
| Net debt / EBITDA (LTM) | 3.75 |
| Operating cash flow (LTM) | 0.39 bn |
| ROE | 14.9% |
| Dividend yield (12m) | 5.9% |
Bottom line
Bottom line: Localiza delivered strong revenue growth of 36.7% and a swing from loss to profit of USD 197.5 million, confirming demand for its services. However, this growth came with an EBITDA margin decline to 30.5% and negative operating cash flow of minus USD 348.9 million, pointing to cost pressure and possible one-off factors. Net debt rose to USD 6,791.3 million, and its ratio to EBITDA is 3.75 – a moderate level but one that requires stable cash generation. The dividend yield of 5.85% and the +24% upside on the portal's model support the share's attractiveness, but the key question for a holder is whether the company can restore positive cash flow and sustain its margin. Verdict: the share looks attractive at the current price, with a caveat about cash flow deterioration.
Open the company's financial profile RENT →
See also: market overview · valuation map · stock screeners