Amerigo Resources: revenue up 61.1%, but cash flow lagged profit
Amerigo Resources reported second-quarter 2026 results. Revenue rose 61.1% year on year to $120.305 million, EBITDA – by 115.6% to $35.139 million, and net profit – by 142.4% to $18.287 million. The EBITDA margin improved to 29.2% from 21.8%, and the net margin to 15.2% from 10.1%. Operating cash flow came in at $23.034 million, well behind net profit. At the current price, the stock looks neutral: profit and margin growth are impressive, but the EV/EBITDA multiple of 9.43x is above the three-year average of 3.76x, and the 8.7% dividend yield already reflects high payouts.
Key takeaways
— Revenue rose 61.1% year on year to $120.305 million, an acceleration from 58.4% in the first quarter of 2026
— EBITDA jumped 115.6% to $35.139 million, with the EBITDA margin reaching 29.2% versus 21.8% a year earlier
— Net profit increased 142.4% to $18.287 million, but operating cash flow was only $23.034 million
— The trailing 12-month dividend yield is 8.7%, above the key rate, but payouts depend on profit
— EV/EBITDA at 9.43x is above the three-year average of 3.76x, limiting upside potential
— According to the portal's model, the stock is valued 7% below fair value, offering no clear advantage
Attractiveness
Key figures, USD bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 0.07 | 0.12 | +61.1% |
| EBITDA | 0.02 | 0.04 | +115.6% |
| Operating profit | 0.01 | 0.03 | +176.8% |
| Net profit | 0.01 | 0.02 | +142.4% |
| Operating cash flow | 0.01 | 0.02 | +263.1% |
| EBITDA margin | 21.8% | 29.2% | +7.4 pp |
| Net margin | 10.1% | 15.2% | +5.1 pp |
Revenue rose 61.1% year on year to $120.305 million, an acceleration from 58.4% in the first quarter of 2026
In the second quarter of 2026, Amerigo Resources' revenue reached $120.305 million, up 61.1% year on year. This is an acceleration from 58.4% growth in the first quarter of 2026. The company does not disclose details on volumes and prices, but such significant growth is likely linked to favourable conditions in the copper market.
The acceleration in revenue growth is a positive signal that may indicate an improving market situation. However, without production data, it is difficult to assess how sustainable this growth is. In the next report, attention should be paid to production volumes and average selling prices.
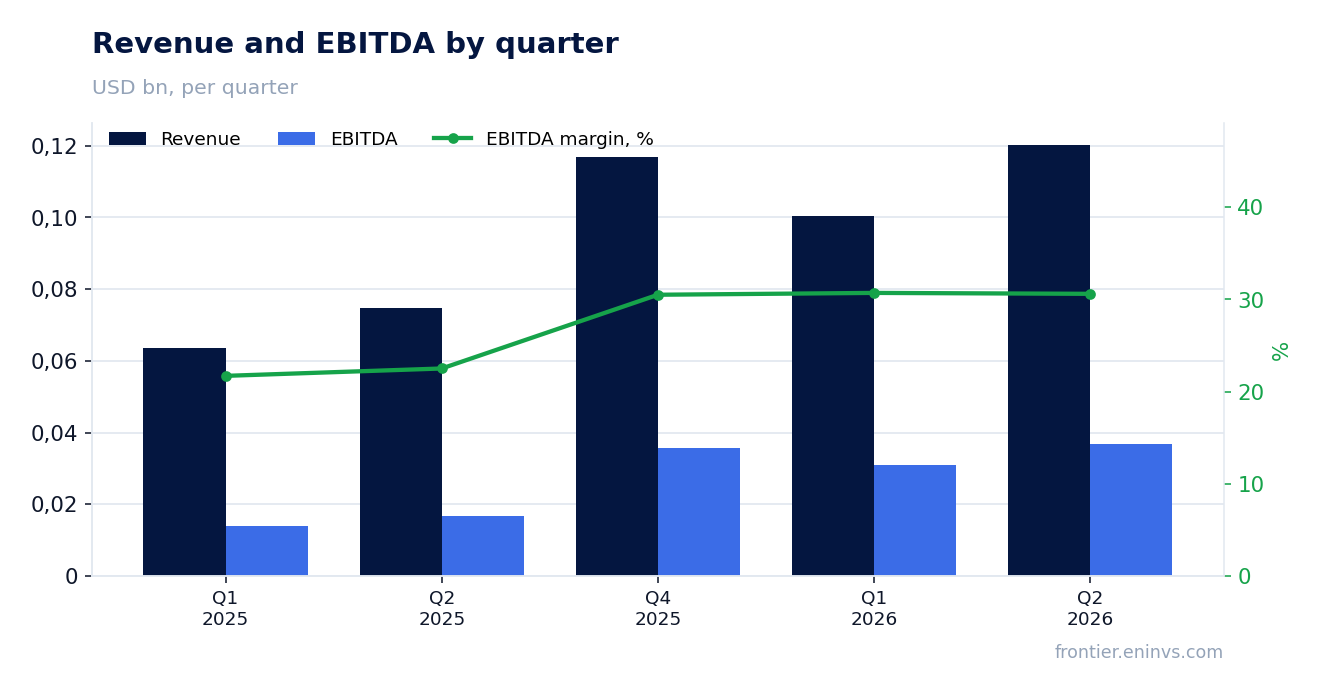
EBITDA jumped 115.6% to $35.139 million, with the EBITDA margin reaching 29.2% versus 21.8% a year earlier
EBITDA in the second quarter of 2026 increased 115.6% year on year to $35.139 million. The EBITDA margin rose to 29.2% from 21.8% a year earlier. Operating profit grew to $30.686 million from $11.085 million a year earlier.
The margin expansion of almost 7.4 percentage points indicates that revenue grew faster than costs. This could be due to both higher copper prices and cost control. The sustainability of this margin will depend on metal price dynamics and production expenses.
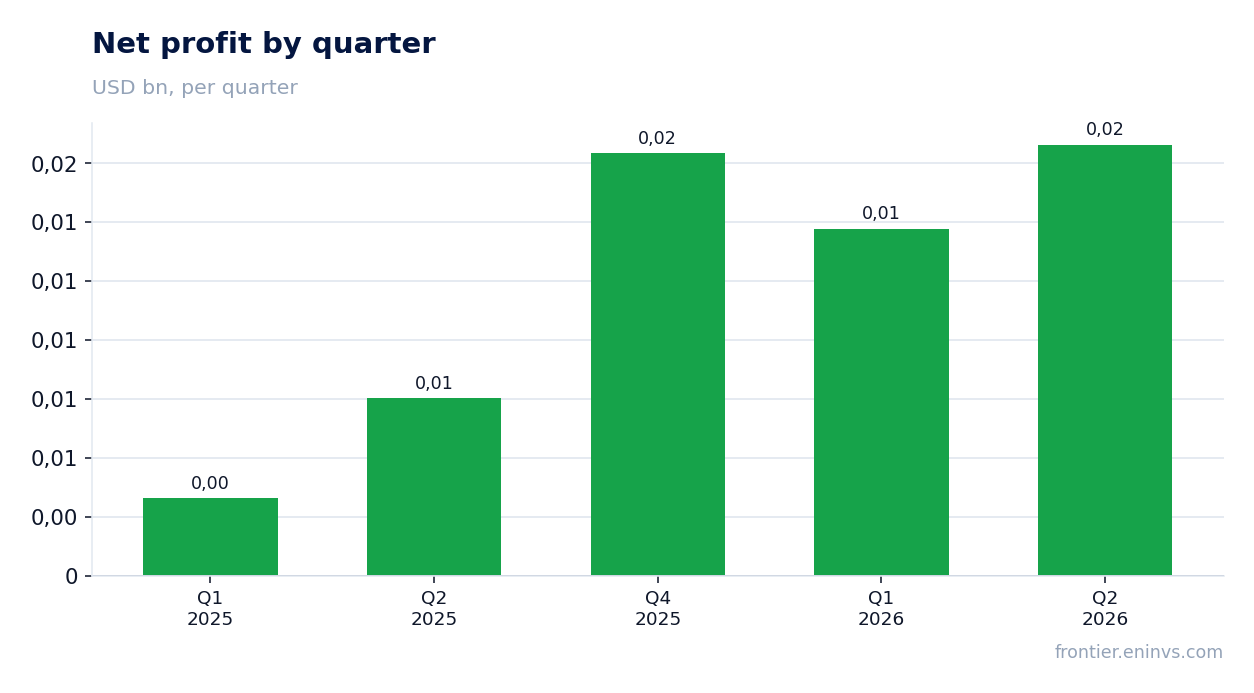
Net profit increased 142.4% to $18.287 million, but operating cash flow was only $23.034 million
Net profit in the second quarter of 2026 was $18.287 million, up 142.4% year on year. However, operating cash flow was $23.034 million, below net profit. This may be explained by an increase in working capital or other non-cash items.
The gap between profit and cash flow is concerning, as it may indicate problems converting profit into cash. At the same time, for the first half of 2026, operating cash flow was $63.156 million (the sum of the first and second quarters), which is higher than in the same period last year. This suggests the situation may be temporary.
The trailing 12-month dividend yield is 8.7%, above the key rate, but payouts depend on profit
Amerigo Resources' dividend yield over the last 12 months is 8.7%. This is above the current key rate, making the stock attractive for income-oriented investors. However, the company does not disclose the size of the latest dividend or the payout ratio.
Our estimate of the dividend for 2026 is based on current profit and an assumed payout ratio. If the company maintains its practice of distributing a significant portion of profit, the dividend could be substantial. However, a decline in copper prices or rising costs could reduce profit and, consequently, the dividend.
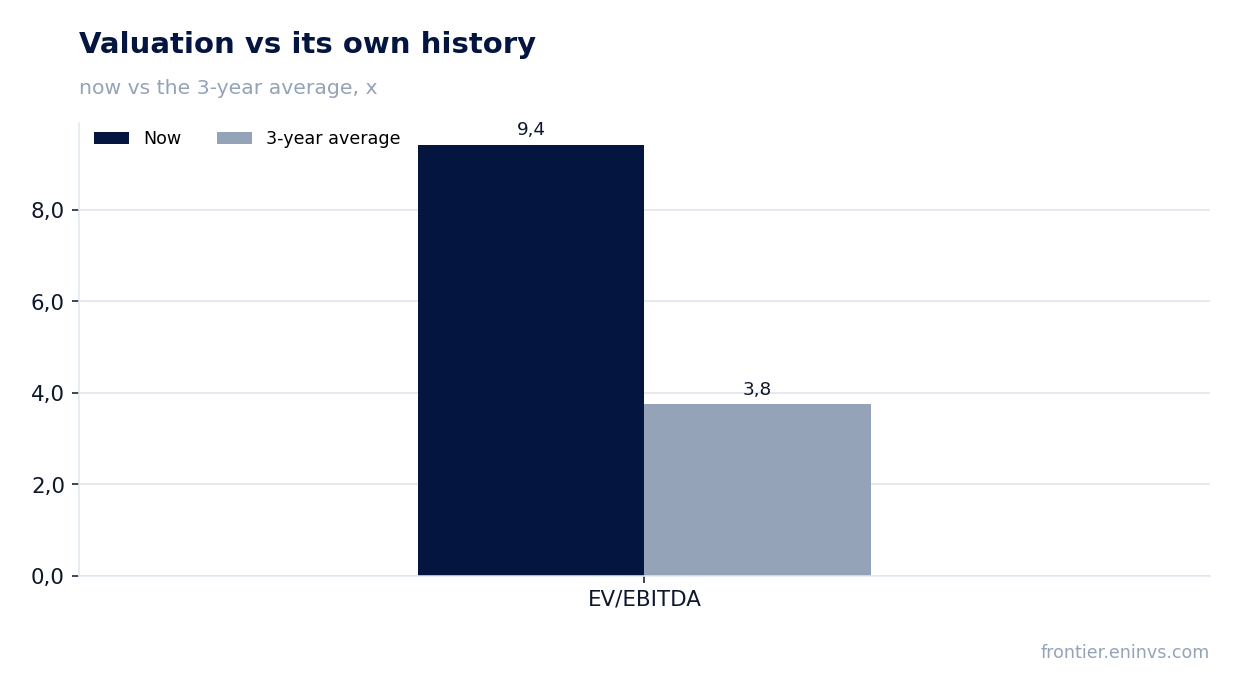
EV/EBITDA at 9.43x is above the three-year average of 3.76x, limiting upside potential
The current EV/EBITDA multiple is 9.43x, significantly above the three-year average of 3.76x. This indicates that the stock is valued more expensively than historically. At the same time, the P/E LTM is 21.54, and ROE reaches 62.9%.
Such a high multiple may be justified by profit growth expectations, but it limits the potential for further stock appreciation. For comparison, according to the portal's model, the fair value of the stock is 7% below the current market price, implying no significant upside.
According to the portal's model, the stock is valued 7% below fair value, offering no clear advantage
Our model, which re-prices EBITDA at current commodity prices and a target EV/EBITDA, shows that the fair value of the stock is 7% below the current market price. This means the market is already pricing in current high copper prices and profitability.
Thus, from our model's perspective, the stock is fairly valued or even slightly expensive. Further stock appreciation would require either a continued rise in copper prices or improved operational performance, which is not guaranteed.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 0.99 bn USD |
| P/E (LTM) | 21.5 |
| EV/EBITDA (LTM) | 9.4 |
| P/B | 8.64 |
| Operating cash flow (LTM) | 0.06 bn |
| ROE | 62.9% |
| Dividend yield (12m) | 8.7% |
| EV/EBITDA, 3-year average | 3.8 |
Bottom line
Amerigo Resources delivered strong second-quarter 2026 results: revenue rose 61.1%, EBITDA – by 115.6%, net profit – by 142.4%. However, operating cash flow lagged profit, and the EV/EBITDA multiple is above the three-year average. The 8.7% dividend yield is attractive but depends on profit. According to our model, the stock is valued 7% below fair value, offering no clear advantage. Overall, the stock looks neutral: profit and margin growth are impressive, but valuation and cash flow quality raise questions.
Open the company's financial profile ARG →
See also: market overview · valuation map · stock screeners