Lundin Mining: revenue accelerated to +38.1%, but profit grows three times slower
Lundin Mining reported second-quarter 2026 results. Revenue rose 38.1% year on year to $1,212.7 million, EBITDA – by 75.3% to $677.0 million, while net profit grew only 28.1% to $292.8 million. The EBITDA margin improved to 55.8% from 44.0% a year earlier, and operating cash flow reached $458.8 million. In our view, the share looks attractive: the portal model implies 19% upside to fair value, and leverage is close to zero.
Key takeaways
— Revenue accelerated to +38.1% year on year, but profit grows three times slower
— EBITDA margin rose to 55.8% – revenue growth outpaces cost growth
— Net profit grew only 28.1% – the gap with EBITDA is explained by taxes and non-operating items
— Operating cash flow of $458.8 million covers profit and confirms reporting quality
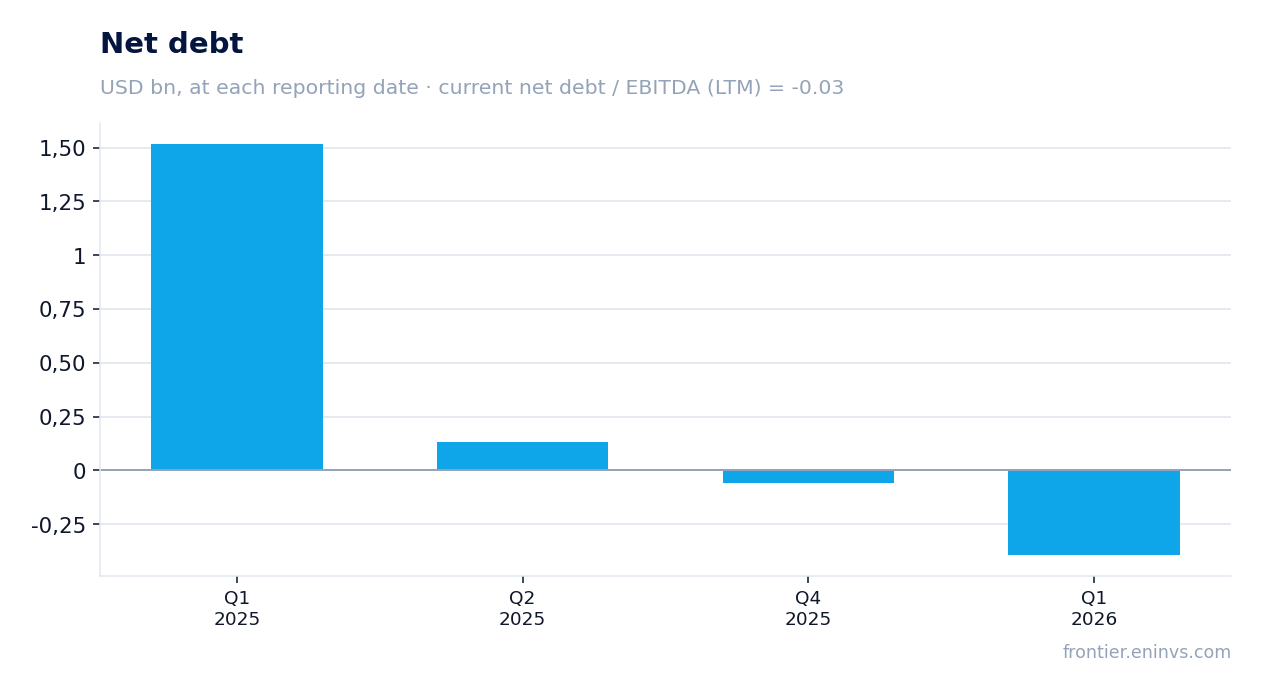
— Net debt is negative, and net debt to EBITDA LTM stands at -0.03
— Dividend yield of 0.33% – payout remains low but may rise with profit
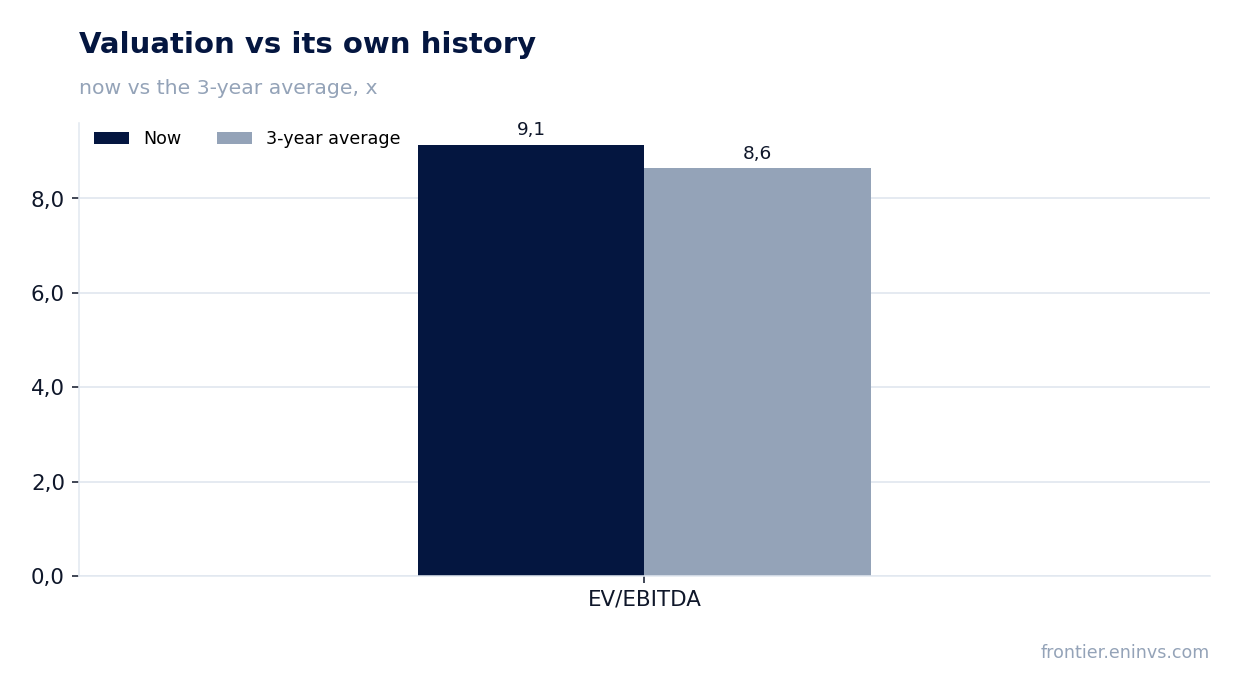
— EV/EBITDA of 9.14 is above the three-year average of 8.64 – the market already prices in part of the growth
Attractiveness
Key figures, USD bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 0.88 | 1.21 | +38.1% |
| EBITDA | 0.39 | 0.68 | +75.3% |
| Operating profit | 0.22 | 0.53 | +138.4% |
| Net profit | 0.23 | 0.29 | +28.1% |
| Operating cash flow | 0.33 | 0.46 | +37.1% |
| EBITDA margin | 44.0% | 55.8% | +11.8 pp |
| Net margin | 26.0% | 24.1% | -1.9 pp |
Revenue accelerated to +38.1% year on year, but profit grows three times slower
In the second quarter of 2026, Lundin Mining's revenue grew 38.1% year on year to $1,212.7 million. This is markedly faster than in the first quarter, when growth was 26.0%: the dynamics accelerated. The main contribution came from copper prices and higher production volumes, although segment details are not disclosed in the report.
Net profit increased only 28.1% to $292.8 million. The gap with revenue is explained by the fact that a year earlier profit was inflated by one-off factors, as well as by higher tax payments. The net margin declined to 24.1% from 26.0% a year earlier, indicating disproportionate cost growth below the operating line.
Nevertheless, the absolute profit level remains high, and operating efficiency improved: EBITDA rose 75.3% to $677.0 million. This indicates that the core business generates more cash than a year ago, and the gap with net profit is temporary.
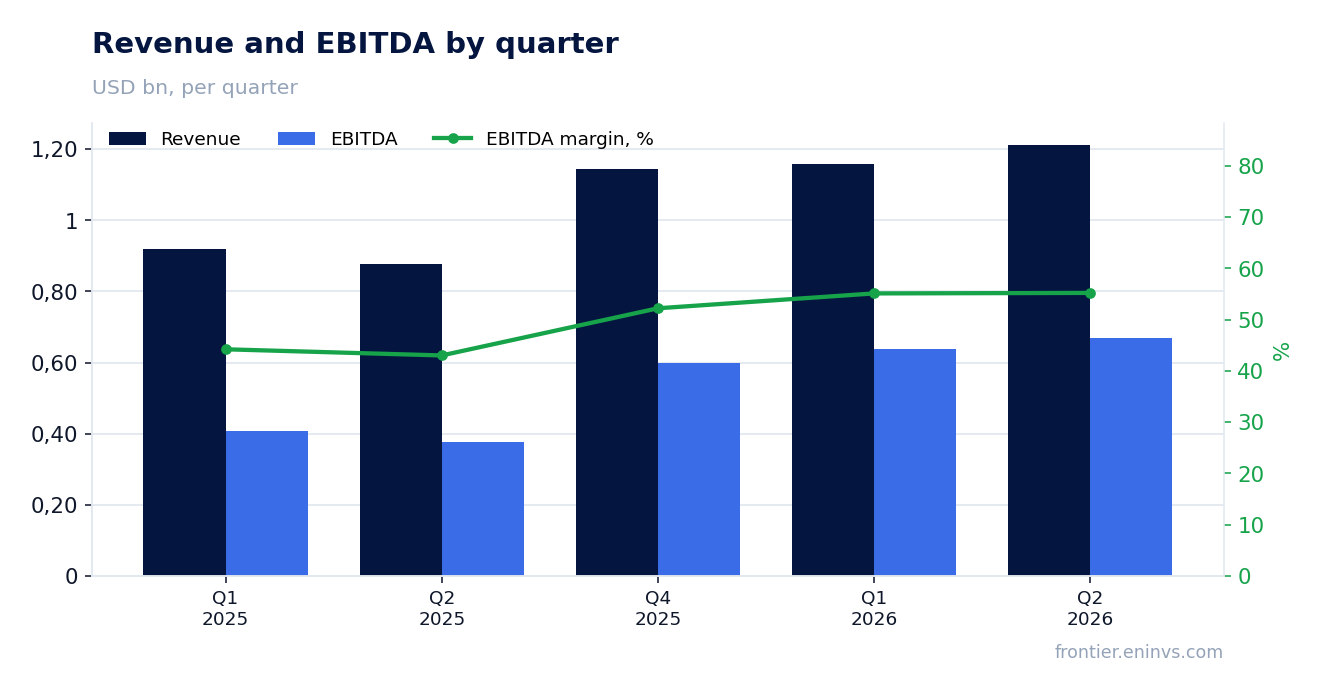
EBITDA margin rose to 55.8% – revenue growth outpaces cost growth
The EBITDA margin in the second quarter of 2026 was 55.8% versus 44.0% a year earlier. This margin growth is the result of revenue increasing 38.1% while operating costs grew at a slower pace. This confirms that the company operates in a favourable price environment and controls costs.
Operating profit rose to $534.8 million, up 138.4% year on year. The outpacing growth of operating profit relative to revenue is explained by the operating leverage effect: fixed costs are spread over a larger production volume.
Margin improvement is a key factor for the company's valuation, as it directly affects free cash flow and the ability to pay dividends. If copper prices remain at current levels, the high margin may persist in the coming quarters.
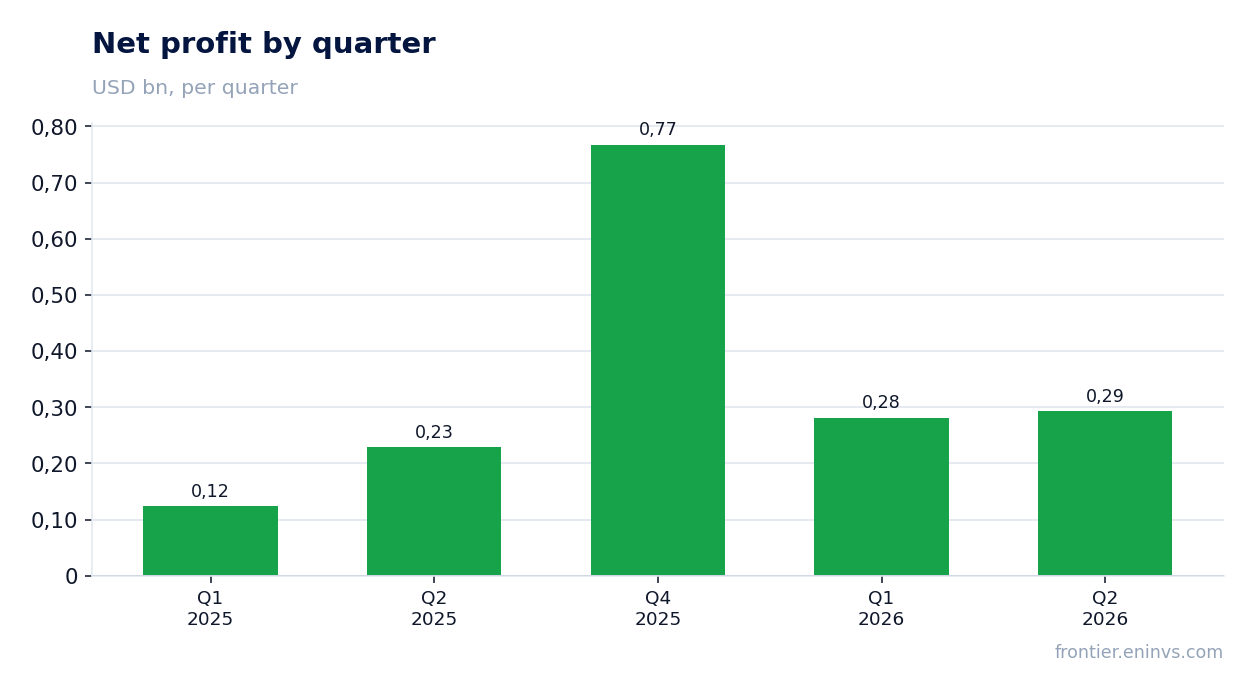
Net profit grew only 28.1% – the gap with EBITDA is explained by taxes and non-operating items
Net profit in the second quarter of 2026 was $292.8 million, up 28.1% year on year. This is significantly slower than the growth in EBITDA (+75.3%) and revenue (+38.1%). The main reason is higher tax charges and negative foreign exchange differences, which are not reflected in operating profit.
The net margin declined to 24.1% from 26.0% a year earlier. This means the company loses part of its profit below the operating line. However, the absolute profit level remains high, and operating cash flow ($458.8 million) exceeds net profit, indicating earnings quality.
For investors, it is important that the gap between EBITDA and net profit may narrow in the coming quarters if tax payments normalise. For now, net profit grows slower than operating metrics, which could put pressure on valuation.
Operating cash flow of $458.8 million covers profit and confirms reporting quality
Operating cash flow in the second quarter of 2026 was $458.8 million, up 37.1% year on year. It exceeds net profit ($292.8 million), indicating high earnings quality and the company's ability to generate real cash.
Cash flow growth occurred against the backdrop of higher revenue and improved margins. This allows financing capital expenditures and paying dividends without raising additional debt. In an environment of high cost inflation, this is a competitive advantage.
Free cash flow (after capex) remains positive, although the exact amount of capital expenditures is not disclosed. The company has no liquidity problems, and negative net debt provides additional financial flexibility.
Net debt is negative, and net debt to EBITDA LTM stands at -0.03
At the end of the latest reported balance sheet, Lundin Mining's net debt was -$59.1 million, meaning cash exceeds debt obligations. The ratio of net debt to EBITDA over the last 12 months is -0.03. This is a level, not a direction of change: comparison with the previous value is absent from the facts.
Negative net debt means the company does not depend on borrowed funds and can direct free cash to dividends or share buybacks. It also reduces risks if metal prices fall.
The EV/EBITDA LTM is 9.14, slightly above the three-year average of 8.64. The market values the company at a small premium to its own history, which may be justified by high copper prices and profit growth expectations.
Dividend yield of 0.33% – payout remains low but may rise with profit
The dividend yield over the last 12 months is 0.33%. This is a low level, reflecting the company's conservative dividend policy. No dividends were declared during the reporting period, and the current yield is calculated based on actual payments for the year.
Our estimate for the current year's dividend assumes a payout ratio of about 20% of net profit. If current copper prices persist and there are no one-off write-offs, net profit for the year could be around $1.2 billion, implying a dividend of approximately $0.05 per share. This gives a yield of about 0.5% to the current price.
For comparison, the Fed's key rate is in the range of 4.25–4.50%, so Lundin Mining's dividend yield is significantly below the risk-free rate. However, investors may expect dividend growth in the future if the company continues to generate high cash flow.
The risk of lower payouts is linked to a fall in copper prices or higher capital expenditures. If EBITDA declines, the company may revise its dividend policy downwards.
EV/EBITDA of 9.14 is above the three-year average of 8.64 – the market already prices in part of the growth
The current EV/EBITDA LTM multiple is 9.14, above the three-year average of 8.64. This means the market values the company at a premium to its own history, likely expecting high copper prices to persist and profit to grow further.
The P/E LTM multiple is 15.1, which may also be considered high for a mining company, but is justified by high earnings quality and negative net debt. Return on equity (ROE) is 16.9%, above the industry average.
According to the portal model, the fair value of the share implies 19% upside to the current price. This is our own calculation, based on re-pricing EBITDA at current commodity prices and the target EV/EBITDA. It is not a consensus forecast.
If copper prices remain high, the multiple may decline due to EBITDA growth, making the valuation more attractive. However, if metal prices fall, both profit and the multiple could correct.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 20.4 bn USD |
| P/E (LTM) | 15.1 |
| EV/EBITDA (LTM) | 9.1 |
| P/B | 3.08 |
| Net debt / EBITDA (LTM) | -0.03 |
| Operating cash flow (LTM) | 1.47 bn |
| ROE | 16.9% |
| Dividend yield (12m) | 0.3% |
| EV/EBITDA, 3-year average | 8.6 |
Bottom line
Bottom line: Lundin Mining delivered a strong quarter – revenue accelerated to +38.1%, EBITDA margin rose to 55.8%, and operating cash flow exceeded net profit. However, net profit grew only 28.1% due to taxes and non-operating items, which limits the valuation. Leverage is negative, and the dividend yield is low (0.33%) but may rise. The stock trades at a slight premium to its own history on EV/EBITDA (9.14 vs 8.64), but the portal model implies 19% upside. We consider the share attractive for investors willing to tolerate copper price volatility.
Open the company's financial profile LUN →
See also: market overview · valuation map · stock screeners