Tourmaline Oil: revenue accelerated to +4.2%, but EBITDA margin collapsed from 80.0% to 45.8%
Tourmaline Oil released its Q2 2026 results. Revenue rose 4.2% year-on-year to $1,077.6 million, accelerating from 2.5% in Q1. However, EBITDA fell 40.3% to $493.8 million and net profit dropped 64.4% to $132.6 million, with the EBITDA margin compressing from 80.0% to 45.8%. At the current price, the stock looks neutral: revenue acceleration does not offset the margin collapse, and the discount to its own history on EV/EBITDA is already small.
Key takeaways
— Revenue accelerated to +4.2% year-on-year, but this did not save profit
— EBITDA fell 40.3%, and the margin compressed from 80.0% to 45.8%
— Net profit collapsed 64.4% to $132.6 million
— Debt load at 0.4 EBITDA LTM – comfortable, but without dynamics
— Dividend yield of 3.7% on a payout that may shrink
— EV/EBITDA at 8.0 – slightly below its own three-year average of 8.2
— The portal's model implies 13% downside to fair value
Attractiveness
Key figures, USD bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 1.03 | 1.08 | +4.2% |
| EBITDA | 0.83 | 0.49 | -40.3% |
| Operating profit | 0.18 | 0.23 | +25.1% |
| Net profit | 0.37 | 0.13 | -64.4% |
| Operating cash flow | 0.54 | 0.46 | -14.1% |
| EBITDA margin | 80.0% | 45.8% | -34.2 pp |
| Net margin | 36.0% | 12.3% | -23.7 pp |
Revenue accelerated to +4.2% year-on-year, but this did not save profit
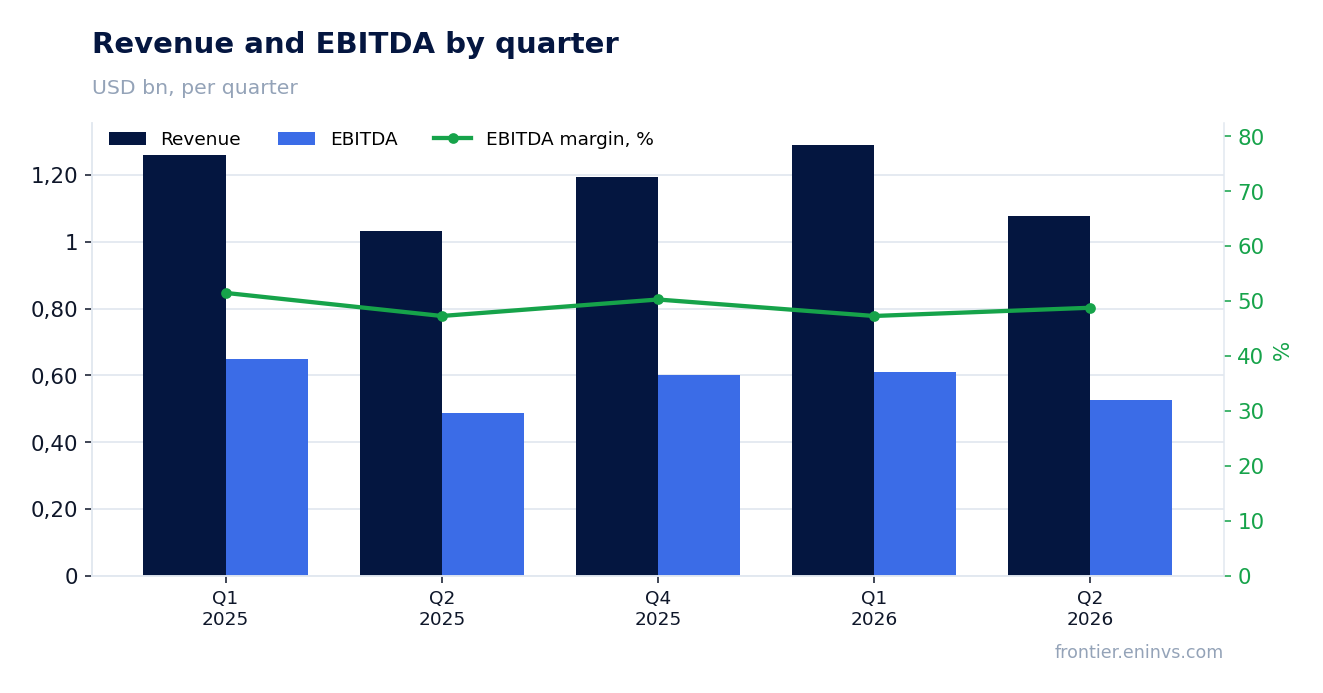
In Q2 2026, revenue amounted to $1,077.6 million, up 4.2% year-on-year. This is an acceleration from 2.5% growth in Q1 2026. However, compared to Q1 2026, revenue declined 16.5% from $1,291.1 million to $1,077.6 million, indicating weak sequential dynamics.
The year-on-year acceleration looks positive, but it did not translate into profit growth. EBITDA fell 40.3% year-on-year, and net profit dropped 64.4%. This means revenue growth was achieved through factors that did not improve profitability – possibly lower realised prices or higher costs.
EBITDA fell 40.3%, and the margin compressed from 80.0% to 45.8%
EBITDA in Q2 2026 was $493.8 million, down 40.3% from the same period last year. The EBITDA margin collapsed from 80.0% to 45.8%. This is the key event of the report: despite revenue growth, the company lost a significant portion of its operating efficiency.
Such a sharp margin decline may be due to a change in revenue structure or higher unit costs. The report does not disclose details, but the scale of the compression – more than 34 percentage points – points to severe pressure on realised prices or rising production costs.
Operating profit in Q2 was $231.2 million, also below last year's level. The decline in EBITDA and operating profit alongside revenue growth is a warning signal for investors.
Net profit collapsed 64.4% to $132.6 million
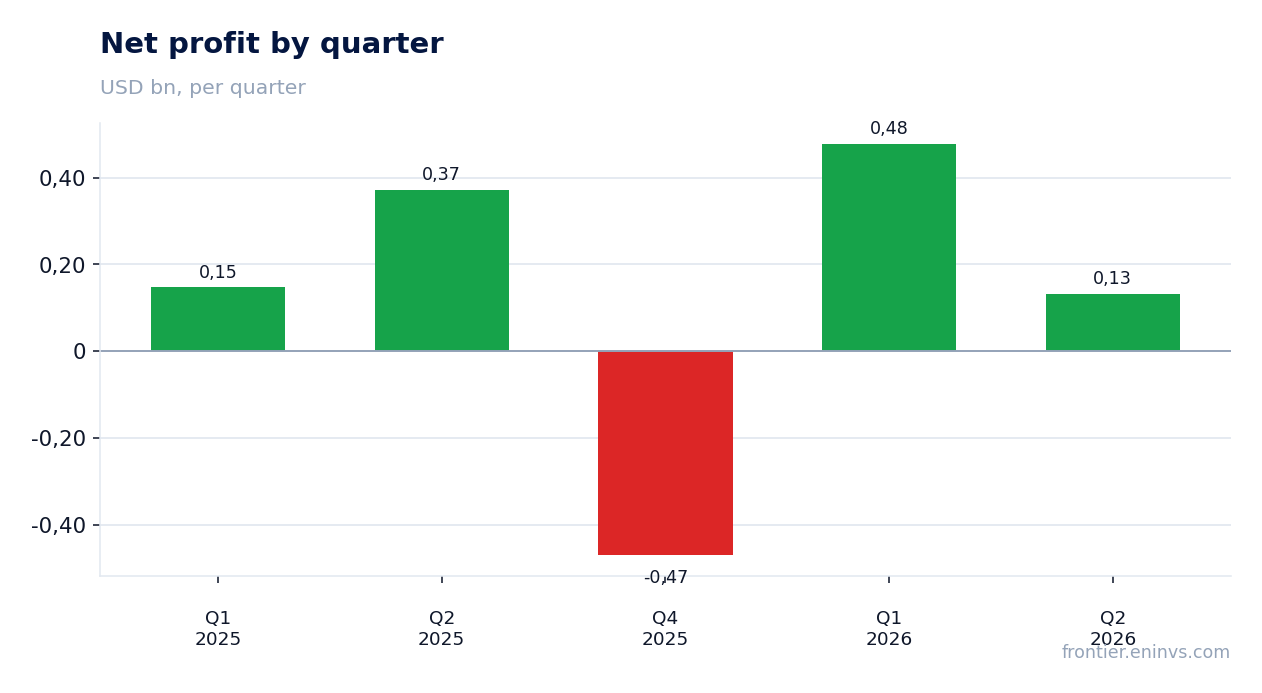
Net profit in Q2 2026 was $132.6 million, down 64.4% year-on-year. The net margin fell from 36.0% to 12.3%. This reflects both lower operating efficiency and possibly higher expenses below the operating line.
For comparison: in Q1 2026, net profit was $478.0 million, meaning it more than tripled sequentially in Q2. Such dynamics indicate that pressure on profit intensified in the second quarter.
Debt load at 0.4 EBITDA LTM – comfortable, but without dynamics
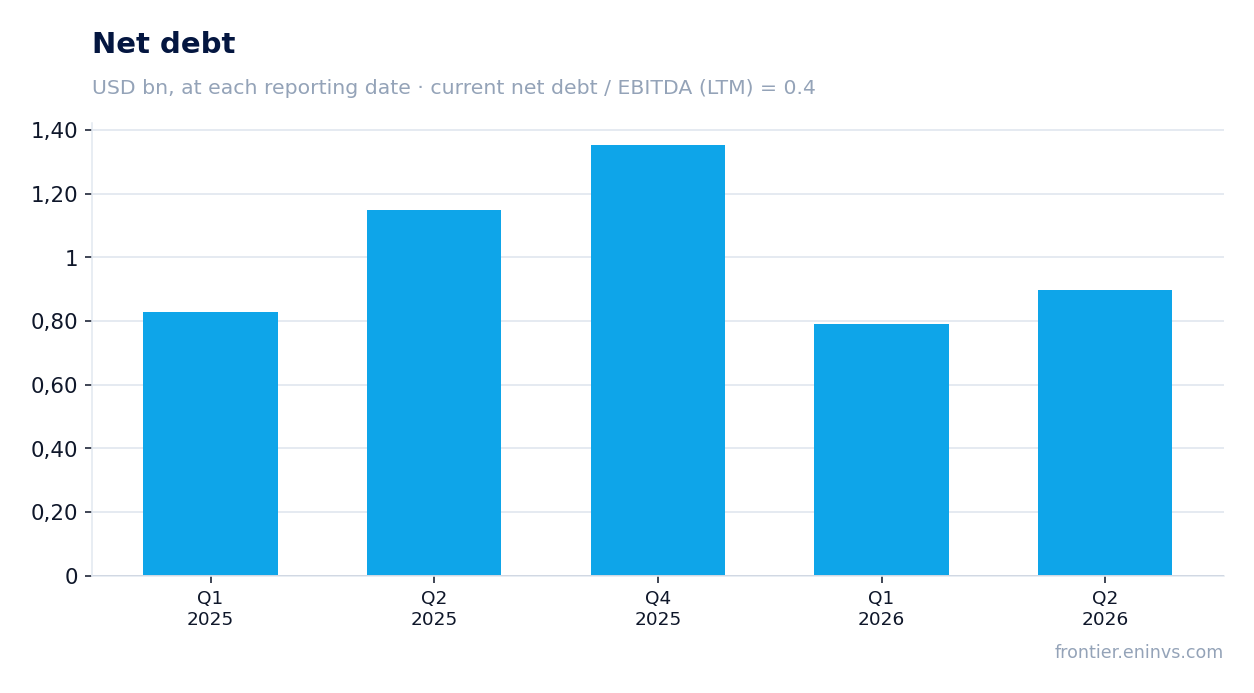
Net debt as of June 30, 2026, was $896.6 million. The net debt to EBITDA ratio for the trailing twelve months is 0.4. This is a low level that does not raise concerns. However, the facts do not provide the previous value of this ratio, so it cannot be stated that leverage decreased or increased.
Net debt changed from $791.0 million on March 31, 2026, to $896.6 million on June 30, 2026, an increase of $105.6 million. Over 12 months, net debt decreased from $1,148.3 million on June 30, 2025, to $896.6 million on June 30, 2026 – a decrease of $251.7 million. This is a positive fact, but it does not offset the weak operating results of the quarter.
Dividend yield of 3.7% on a payout that may shrink
The dividend yield over the last 12 months is 3.7%. This is a moderate level that may be attractive relative to the current key rate, but it is not exceptional. Payouts depend on profit, which fell sharply in the last quarter.
If margin pressure persists, the company may be forced to revise the dividend size. Our estimate for the current year suggests the payout could be lower than in previous periods if profitability does not recover. This is a key risk for the dividend story.
EV/EBITDA at 8.0 – slightly below its own three-year average of 8.2
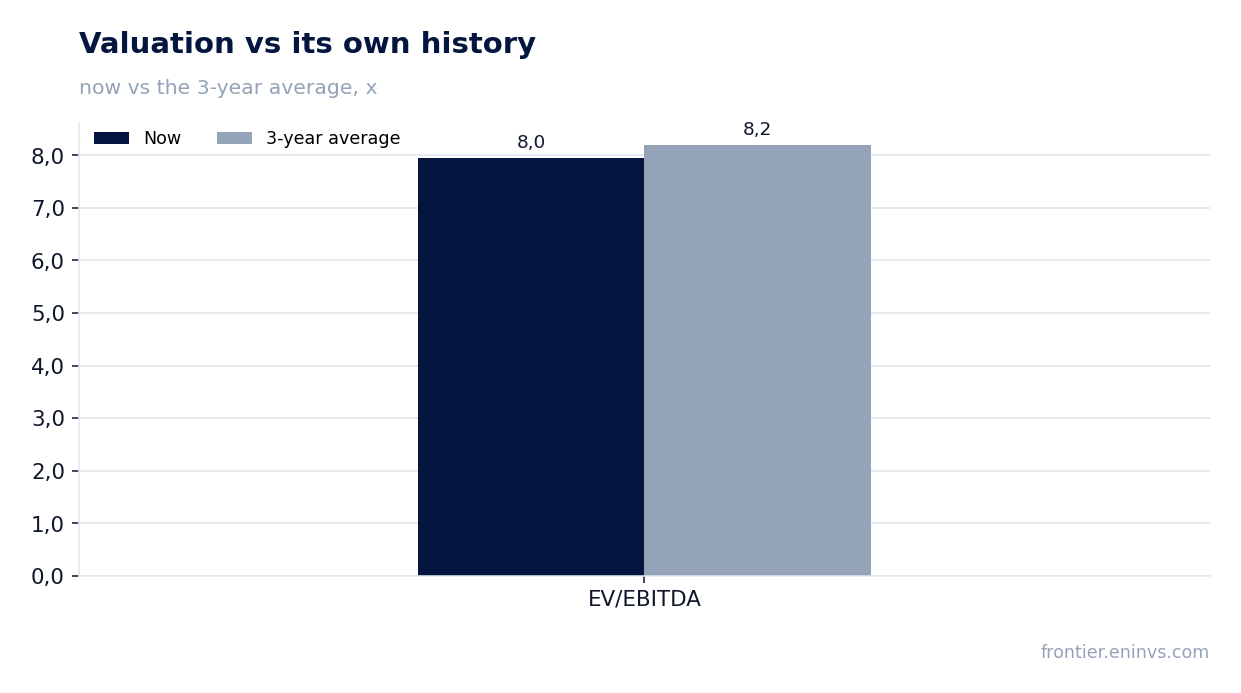
The current EV/EBITDA for the trailing twelve months is 8.0. This is slightly below its own three-year average of 8.2. Thus, the stock trades at a small discount to its history, but this discount is insignificant.
Given the sharp drop in EBITDA in the last quarter, the current multiple may be overstated if profit does not recover. The portal's model, which re-prices EBITDA at current commodity prices at the target EV/EBITDA, implies 13% downside to fair value. This means the stock may be overvalued relative to our estimates.
The portal's model implies 13% downside to fair value
According to the portal's model, the fair value of the share is 13% below the current market price. This is the result of re-pricing EBITDA at current commodity prices at the target EV/EBITDA. Such downside potential suggests the market may be overly optimistic about the company's future results.
It should be noted that the model is based on current commodity prices and a target multiple, and is not a market consensus. Nevertheless, it points to limited upside and possible downside risk.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 16.7 bn USD |
| EV/EBITDA (LTM) | 8.0 |
| P/B | 1.48 |
| Net debt / EBITDA (LTM) | 0.40 |
| Operating cash flow (LTM) | 2.35 bn |
| ROE | 4.7% |
| Dividend yield (12m) | 3.7% |
| EV/EBITDA, 3-year average | 8.2 |
Bottom line
Bottom line: Tourmaline Oil's revenue accelerated to +4.2% year-on-year, but this did not offset the EBITDA margin collapse from 80.0% to 45.8% and a 64.4% drop in net profit. Debt load remains low at 0.4 EBITDA LTM, but increased over the quarter. Dividend yield of 3.7% may shrink if profit pressure persists. The stock trades at a small discount to its own history on EV/EBITDA, but the portal's model implies 13% downside. Verdict – neutral: the current price broadly reflects the risks, but a turnaround in margin is needed for a better assessment.
Open the company's financial profile TOU →
See also: market overview · valuation map · stock screeners