Var Energi: revenue doubled, but EBITDA margin fell to 89.1%
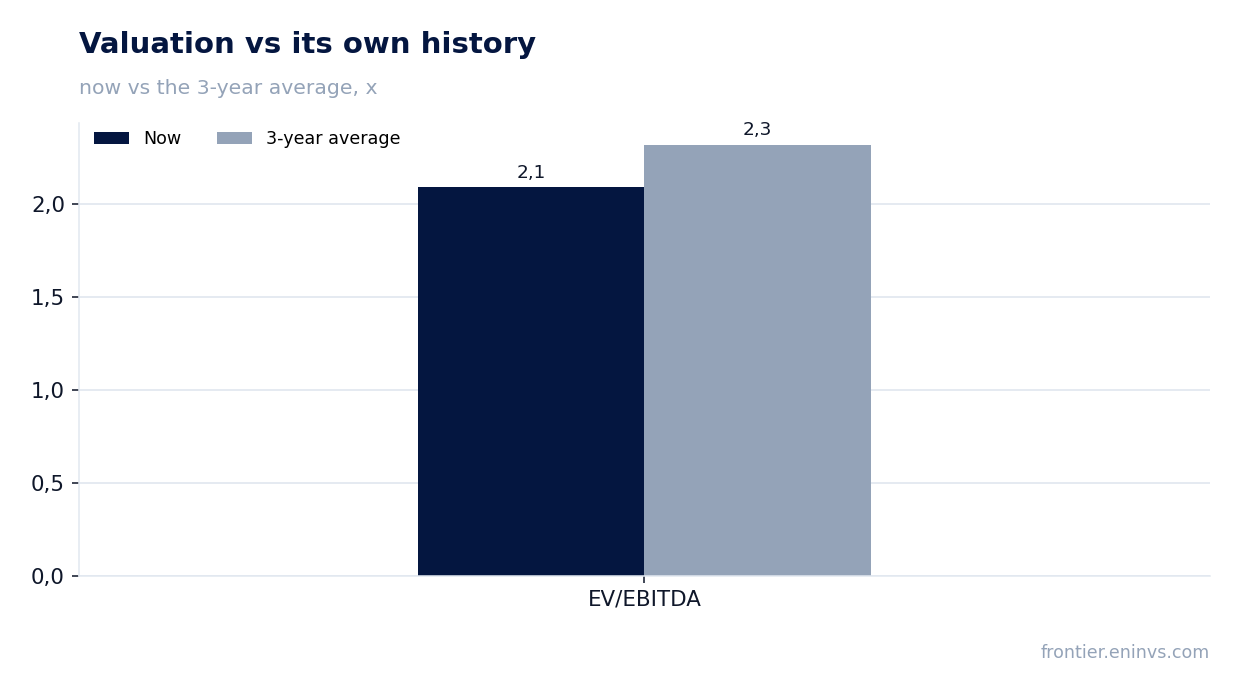
Var Energi reported Q2 2026 results. Revenue doubled year-on-year to $3,704.8 million, EBITDA rose 81.4% to $3,301.7 million, and net profit jumped 287.1% to $838.9 million. Growth accelerated: revenue grew 45.0% in Q1 and 102.7% in Q2. Despite the EBITDA margin falling to 89.1% from 99.6% a year earlier, the shares look attractive: EV/EBITDA of 2.09 is below the three-year average of 2.32, the dividend yield is 9.6%, and the portal model implies 94% upside.
Key takeaways
— Revenue doubled year-on-year, accelerating from 45.0% growth in Q1 to 102.7% in Q2
— EBITDA rose 81.4%, but the margin fell to 89.1% from 99.6% a year earlier
— Net profit surged 287.1% to $838.9 million, with a net margin of 22.6%
— Leverage is comfortable: net debt/EBITDA LTM stands at 0.38
— Dividend yield of 9.6% and payout are attractive amid falling debt
— EV/EBITDA of 2.09 is below the three-year average of 2.32, suggesting undervaluation
— The portal model estimates 94% upside for the shares
Attractiveness
Key figures, USD bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 1.83 | 3.70 | +102.7% |
| EBITDA | 1.82 | 3.30 | +81.4% |
| Operating profit | 0.72 | 2.20 | +206.9% |
| Net profit | 0.22 | 0.84 | +287.1% |
| Operating cash flow | 0.77 | 2.08 | +171.1% |
| EBITDA margin | 99.6% | 89.1% | -10.5 pp |
| Net margin | 11.9% | 22.6% | +10.7 pp |
Revenue doubled year-on-year, accelerating from 45.0% growth in Q1 to 102.7% in Q2
In Q2 2026, Var Energi's revenue reached $3,704.8 million, up 102.7% year-on-year. This marks a significant acceleration from 45.0% growth in Q1. The jump was likely driven by higher hydrocarbon prices and increased production volumes, although the exact drivers are not disclosed in the report.
The acceleration in revenue growth is a positive signal for investors, indicating improved market conditions and possibly successful operational performance. However, without segment details, it is difficult to assess the sustainability of this trend.
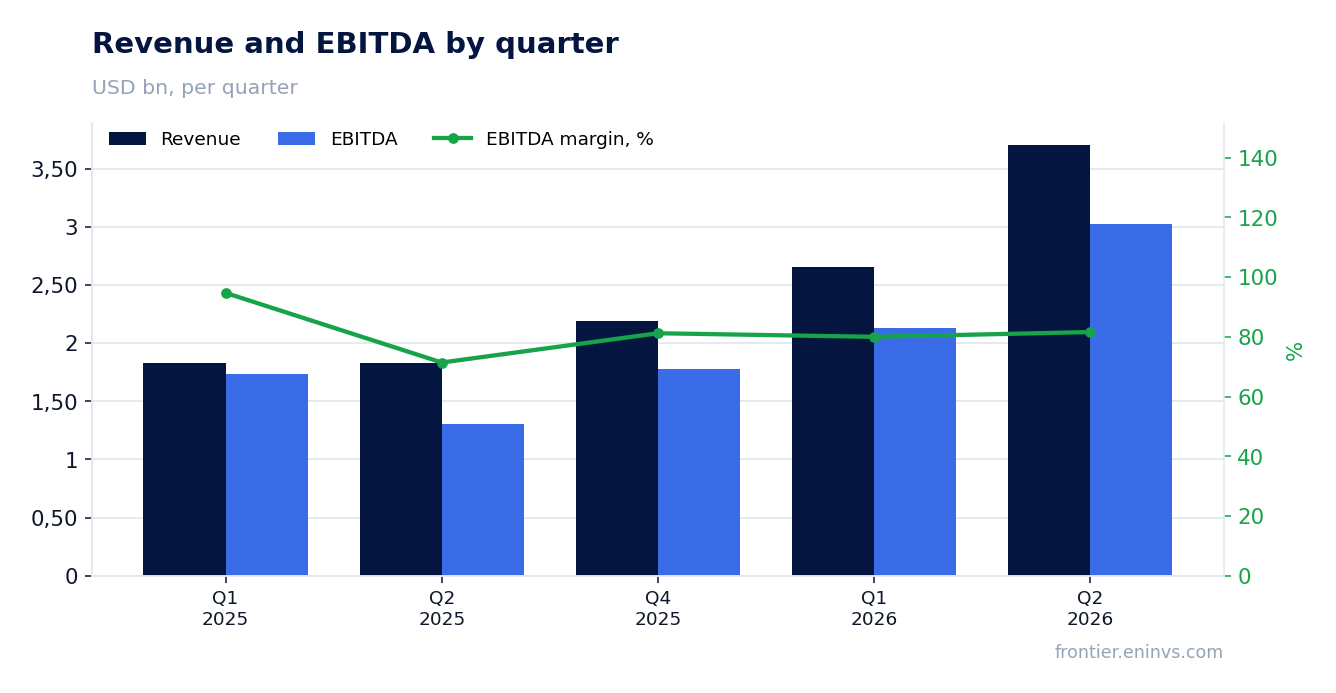
EBITDA rose 81.4%, but the margin fell to 89.1% from 99.6% a year earlier
EBITDA in Q2 2026 was $3,301.7 million, up 81.4% year-on-year. However, the EBITDA margin declined to 89.1% from 99.6% in Q2 2025. The margin contraction could be due to higher operating costs or a change in revenue mix.
Despite the margin decline, the absolute EBITDA level remains high, indicating strong operational efficiency. Future margin trends will depend on oil and gas prices and cost control.
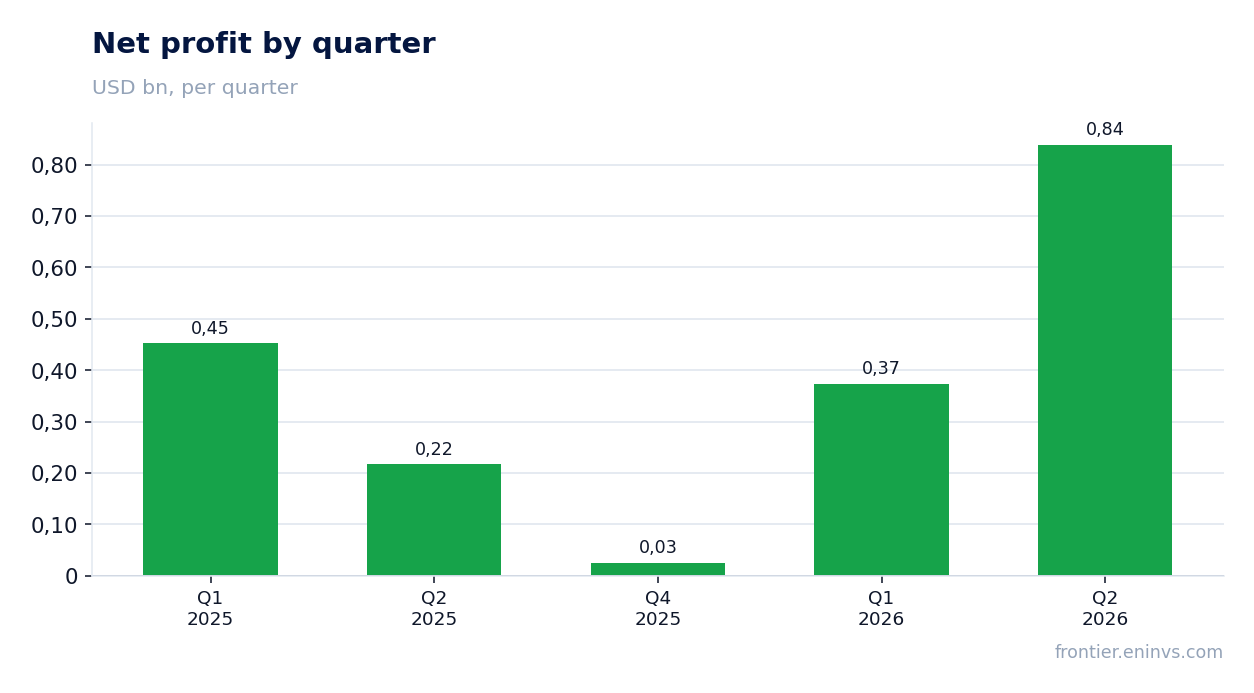
Net profit surged 287.1% to $838.9 million, with a net margin of 22.6%
Net profit in Q2 2026 reached $838.9 million, up 287.1% year-on-year. The net margin improved to 22.6% from 11.9% a year earlier. This profit surge is explained by both higher revenue and possibly lower financial expenses or tax burden.
Such significant net profit growth positively impacts EPS and dividend capacity. However, the sustainability of this growth will depend on continued favorable price conditions.
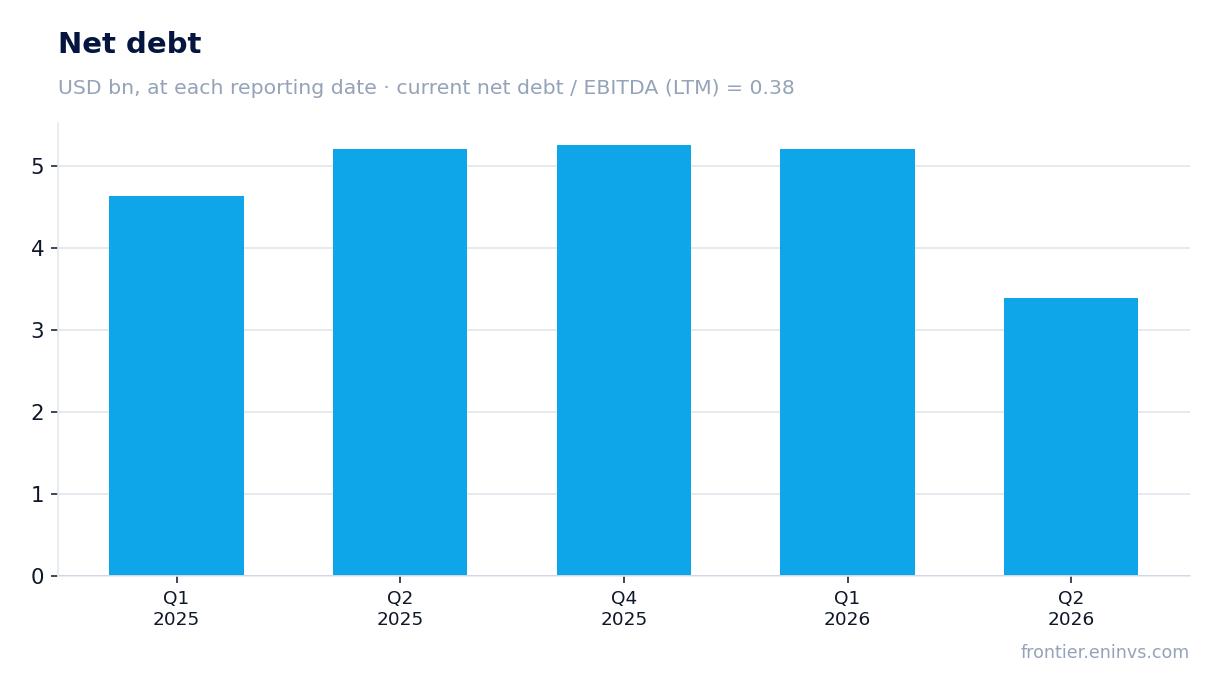
Leverage is comfortable: net debt/EBITDA LTM stands at 0.38
Net debt as of June 30, 2026, was $3,387.6 million, down from $5,201.7 million on March 31, 2026, and from $5,208.7 million on June 30, 2025. The reduction over the quarter and year was $1.8 billion. The net debt/EBITDA LTM ratio is 0.38, a low level indicating high financial stability.
The debt reduction and low leverage ratio give the company flexibility in case of market deterioration and allow it to maintain high dividend payments.
Dividend yield of 9.6% and payout are attractive amid falling debt
The dividend yield over the last 12 months is 9.6%. The company pays dividends, and the current yield significantly exceeds that of many peers and the key rate. The reduction in debt provides a basis for maintaining or increasing payments.
The expected dividend for the current year, by our estimate, may be at or above last year's level, given profit growth. However, the payout size depends on profit and potential one-offs. The risk of a dividend cut is linked to falling oil and gas prices.
EV/EBITDA of 2.09 is below the three-year average of 2.32, suggesting undervaluation
The current EV/EBITDA multiple is 2.09, below the three-year average of 2.32. This indicates that the shares are trading at a discount to their historical valuation. For comparison, the P/E LTM is 9.0.
Such a low multiple may be due to the cyclical nature of the industry and investor concerns about the sustainability of high energy prices. Nevertheless, given strong financial results and low leverage, the current valuation appears attractive.
The portal model estimates 94% upside for the shares
According to the portal model, which re-prices EBITDA at current commodity prices and a target EV/EBITDA, the fair value of Var Energi shares implies 94% upside from the current market capitalization. This is our own estimate, not a consensus forecast.
Such significant upside is explained by the low current multiple and strong operating performance. However, the model is sensitive to commodity price assumptions and may not account for market volatility risks.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 13.2 bn USD |
| P/E (LTM) | 9.0 |
| EV/EBITDA (LTM) | 2.1 |
| P/B | 23.60 |
| Net debt / EBITDA (LTM) | 0.38 |
| Operating cash flow (LTM) | 5.92 bn |
| ROE | 18.0% |
| Dividend yield (12m) | 9.6% |
| EV/EBITDA, 3-year average | 2.3 |
Bottom line
Var Energi delivered impressive Q2 2026 results: revenue doubled, net profit surged 287.1%. The decline in EBITDA margin to 89.1% from 99.6% warrants monitoring, but absolute figures remain strong. Leverage decreased, with net debt/EBITDA LTM at 0.38. A dividend yield of 9.6% and 94% upside per the portal model make the shares attractive for investors, despite potential risks.
Open the company's financial profile VAR →
See also: market overview · valuation map · stock screeners