Whitecap Resources: profit nearly tripled, but revenue growth is slower than a quarter ago
On 25 August Whitecap Resources reported results for the second quarter of 2026. Revenue rose 85.5% year on year to USD 1,940.86 million, EBITDA – by 107.6% to USD 1,271.47 million, and net profit – by 184.8% to USD 639.76 million. The EBITDA margin improved to 65.5% from 58.5%, and the net margin to 33.0% from 21.5%. Net debt fell from USD 2.0 billion on 31 March to USD 1.4 billion on 30 June. The stock trades below its own three-year average EV/EBITDA, and the portal's model implies 69% upside to fair value, making the share attractive at the current price.
Key takeaways
— Revenue rose 85.5%, but that is slower than the 114.9% a quarter earlier
— EBITDA added 107.6%, and its margin rose to 65.5% from 58.5%
— Net profit grew 184.8%, with the margin reaching 33.0%
— Net debt fell from USD 2.0 billion on 31 March to USD 1.4 billion on 30 June
— Operating cash flow for the quarter was USD 1,100.94 million
— Dividend yield of 4.16% on a payout that could grow with profit
— EV/EBITDA of 5.97 is below the three-year average of 6.21, and the portal's model implies 69% upside
Attractiveness
Key figures, USD bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 1.05 | 1.94 | +85.5% |
| EBITDA | 0.61 | 1.27 | +107.6% |
| Operating profit | 0.21 | 0.81 | +286.4% |
| Net profit | 0.22 | 0.64 | +184.8% |
| Operating cash flow | 0.48 | 1.10 | +127.7% |
| EBITDA margin | 58.5% | 65.5% | +7.0 pp |
| Net margin | 21.5% | 33.0% | +11.5 pp |
Revenue rose 85.5%, but that is slower than the 114.9% a quarter earlier
In the second quarter of 2026, Whitecap Resources' revenue reached USD 1,940.86 million, up 85.5% year on year. Growth remains very high, but it decelerated from the first quarter, when revenue added 114.9%. The slowdown is explained by a higher year-on-year comparison base and by exceptionally favourable hydrocarbon prices in the first quarter.
A sequential comparison with the first quarter of 2026, when revenue was USD 1,513.08 million, shows growth of 28.2% over three months. This indicates that the company is not only benefiting from a low base last year but also increasing revenue quarter on quarter. The main contribution to growth likely came from both higher production volumes and favourable prices, although the exact drivers are not disclosed in the report.
For an investor, it is important that even with a slowdown in annual growth, revenue remains at a historically high level. The company demonstrates the ability to generate significant income even with somewhat slower growth. The next quarter will show whether the deceleration is a sustainable trend or a one-off base effect.
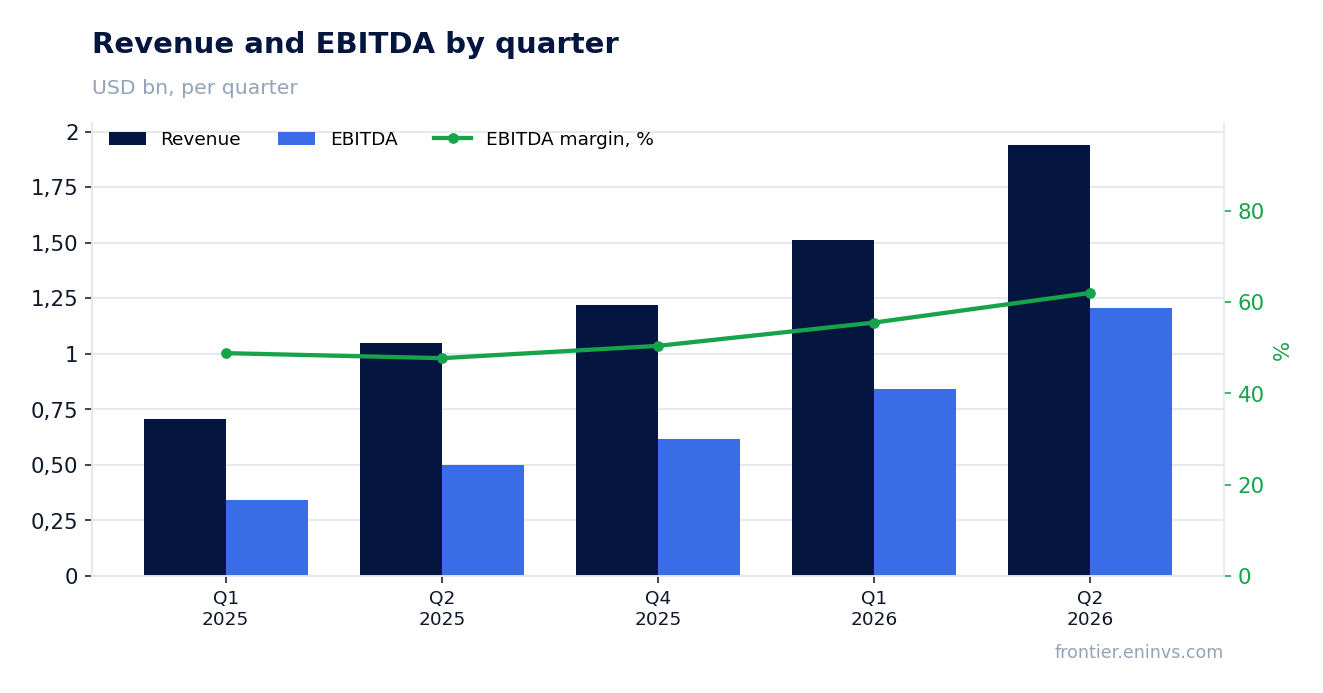
EBITDA added 107.6%, and its margin rose to 65.5% from 58.5%
EBITDA in the second quarter of 2026 grew 107.6% year on year to USD 1,271.47 million. This is significantly faster than revenue growth, which led to an expansion in the EBITDA margin to 65.5% from 58.5% a year earlier. Such a margin level indicates high operational efficiency and favourable pricing.
The margin increase could be due to lower unit costs or a shift in the sales mix towards more profitable products. However, a breakdown by cost items is not available in the provided data, so the exact cause cannot be identified. Nevertheless, the fact remains: the company extracts more profit from each dollar of revenue.
The sustainability of such a high margin is questionable, as commodity companies depend on resource prices. If prices decline, the margin could shrink. But at present, this is one of the strongest indicators in the report.
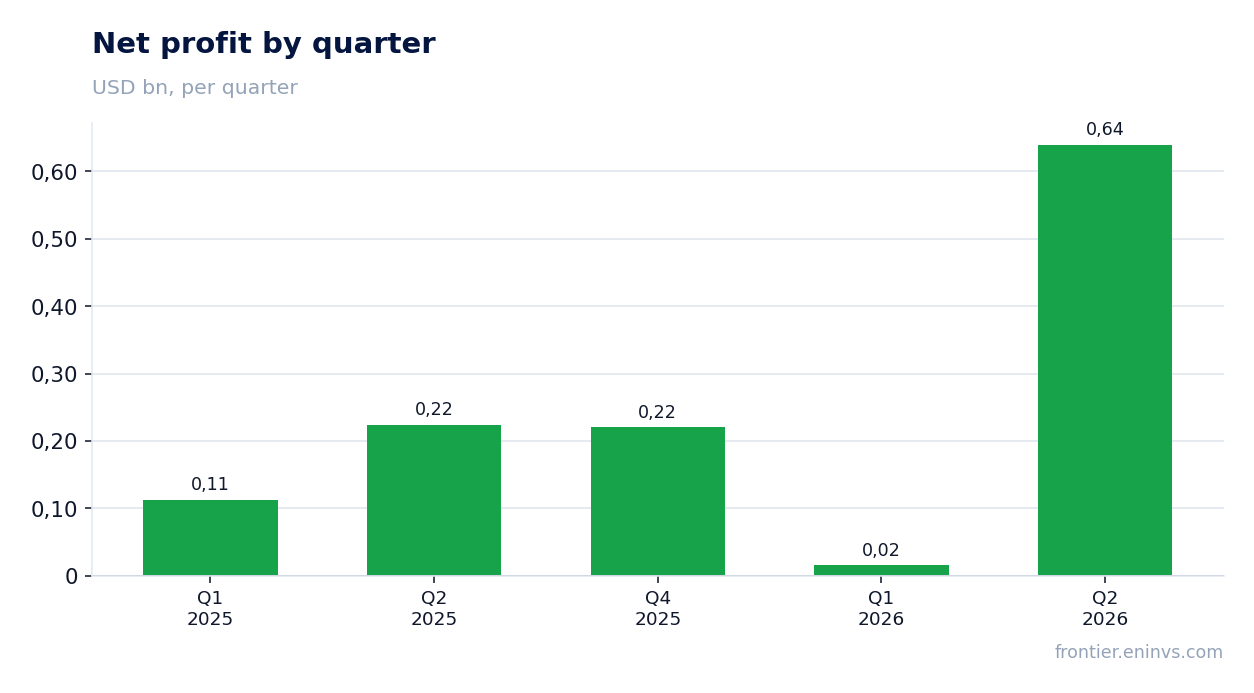
Net profit grew 184.8%, with the margin reaching 33.0%
Net profit in the second quarter of 2026 was USD 639.76 million, up 184.8% year on year. This outpaces EBITDA growth, indicating a reduction in relative debt burden or tax payments. The net margin rose to 33.0% from 21.5% a year earlier.
Such a significant profit increase could be partly due to one-off factors, such as asset sales or liability revaluation, but there is no confirmation of this in the provided data. Without additional information from the report, we cannot claim that all profit growth is organic. Nevertheless, the profit level is impressive.
It is important to note that net profit over the last twelve months was USD 1,119.1 million, giving a P/E of 13.47. This does not look overheated for a company with such dynamics, especially if the profit is sustainable.
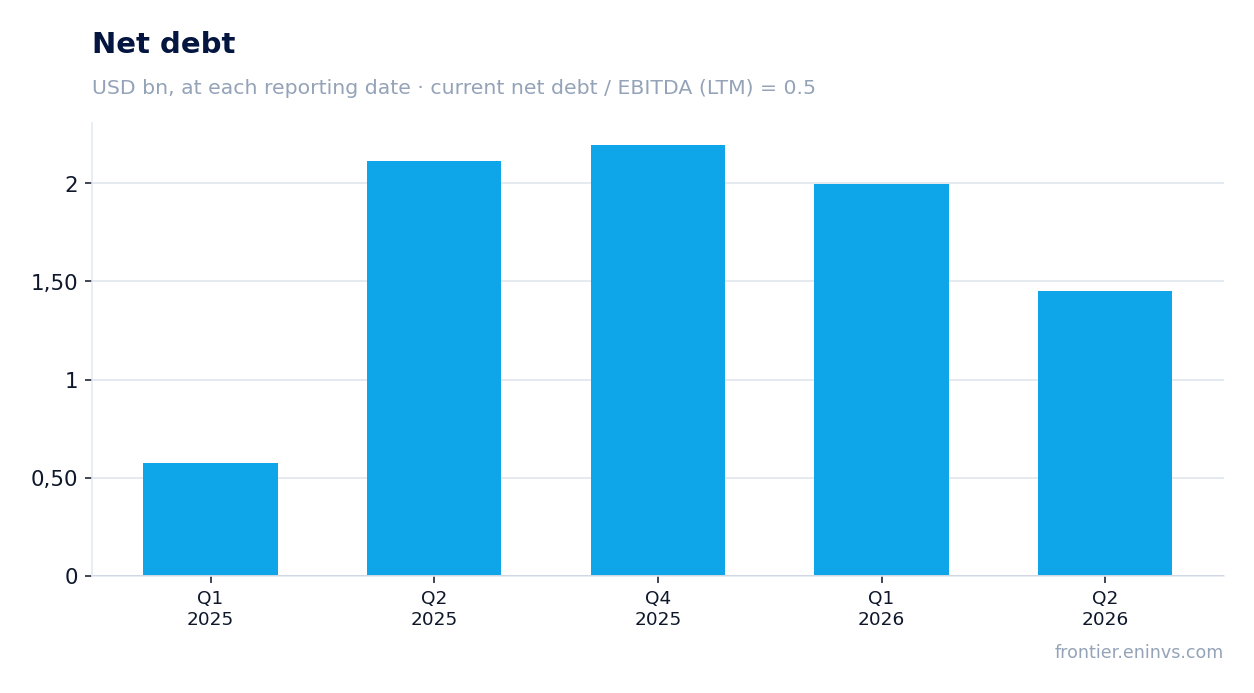
Net debt fell from USD 2.0 billion on 31 March to USD 1.4 billion on 30 June
Whitecap Resources' net debt as of 30 June 2026 was USD 1,449.21 million, down 0.5 billion from 31 March, when it stood at 2.0 billion. Over the year, debt decreased by 0.7 billion: from 2.1 billion on 30 June 2025 to 1.4 billion on 30 June 2026. The reduction in debt alongside profit growth is a positive signal.
The net debt to EBITDA ratio over the last twelve months is 0.5, which is a low level and indicates high debt sustainability. However, we do not have an earlier value for this ratio, so we cannot claim that it decreased. We merely state the current level.
The debt reduction could have been financed from operating cash flow, which was USD 1,100.94 million for the quarter. This allows the company to maintain financial flexibility and potentially increase dividends or investments.
Operating cash flow for the quarter was USD 1,100.94 million
Operating cash flow in the second quarter of 2026 reached USD 1,100.94 million, significantly exceeding net profit. This indicates high earnings quality and the company's ability to generate real cash. Over the last twelve months, operating cash flow was USD 2,537.7 million.
Such strong cash flow allows the company to fund capital expenditures, pay dividends, and reduce debt. The report does not disclose details on capital expenditures, and their absence in the provided data prevents us from assessing how much remains after investments. Nevertheless, even without this information, it is clear that the company is in a strong position.
For an investor, it is important that cash flow is sustainable and covers business needs. This reduces risks and creates a basis for future payouts.
Dividend yield of 4.16% on a payout that could grow with profit
Whitecap Resources pays dividends, and the yield over the last twelve months is 4.16%. This is a moderate level that may appeal to income-oriented investors. The company does not disclose the exact amount of the latest dividend and the period for which it was paid, but the fact of payment is confirmed.
Our estimate for the current year's dividend is based on trailing twelve-month profit of USD 1,119.1 million and the payout ratio the company has historically maintained. If profit remains at the current level, the dividend could be increased. However, this depends on the board's decision and may be adjusted based on capital expenditures and debt policy.
A yield of 4.16% looks adequate against current interest rates but is not exceptionally high. If the company increases payouts, the yield could rise, supporting the valuation.
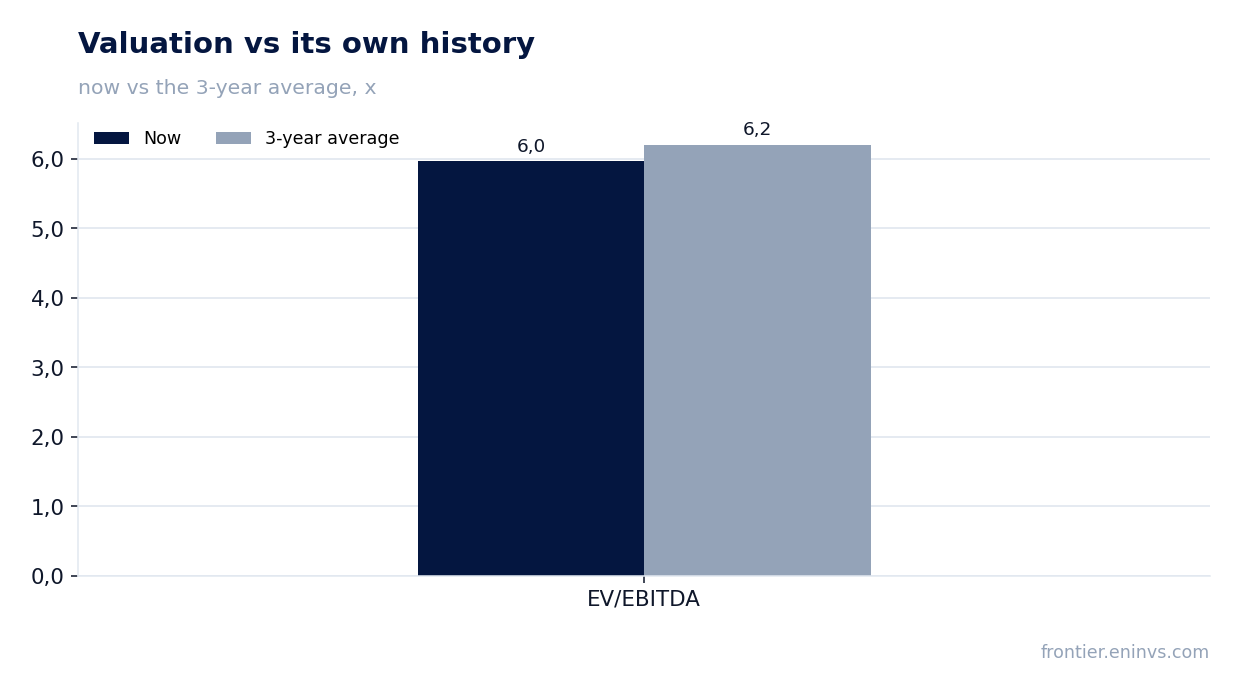
EV/EBITDA of 5.97 is below the three-year average of 6.21, and the portal's model implies 69% upside
Based on the trailing twelve-month EV/EBITDA multiple, Whitecap Resources trades at 5.97, below its own three-year average of 6.21. This indicates that the stock is valued cheaper than usual relative to its history. The trailing P/E is 13.47, which also does not look inflated.
Our model, based on current commodity prices and a target EV/EBITDA, implies 69% upside to fair value. This is the portal's own estimate, not a market consensus. It suggests that under current conditions, the stock may be undervalued.
Return on equity (ROE) is 32.3%, confirming business efficiency. The combination of a low valuation, high profitability, and growth potential makes the stock attractive for investors willing to accept commodity sector risks.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 15.1 bn USD |
| P/E (LTM) | 13.5 |
| EV/EBITDA (LTM) | 6.0 |
| P/B | 1.88 |
| Net debt / EBITDA (LTM) | 0.50 |
| Operating cash flow (LTM) | 2.54 bn |
| ROE | 32.3% |
| Dividend yield (12m) | 4.2% |
| EV/EBITDA, 3-year average | 6.2 |
Bottom line
Whitecap Resources delivered a strong quarter: revenue rose 85.5%, EBITDA – 107.6%, net profit – 184.8%, and the margin reached 65.5%. Debt fell to USD 1.4 billion, and operating cash flow was USD 1,100.94 million. However, revenue growth decelerated from the first quarter, and part of the profit may be one-off. The stock trades below its three-year average EV/EBITDA, and the portal's model implies 69% upside. At the current price, the share looks attractive, but the key question is the sustainability of commodity prices and the company's ability to maintain high margins.
Open the company's financial profile WCP →
See also: market overview · valuation map · stock screeners