AltynGold: profit more than doubled, and the gold price plus a fully loaded plant did almost all of it
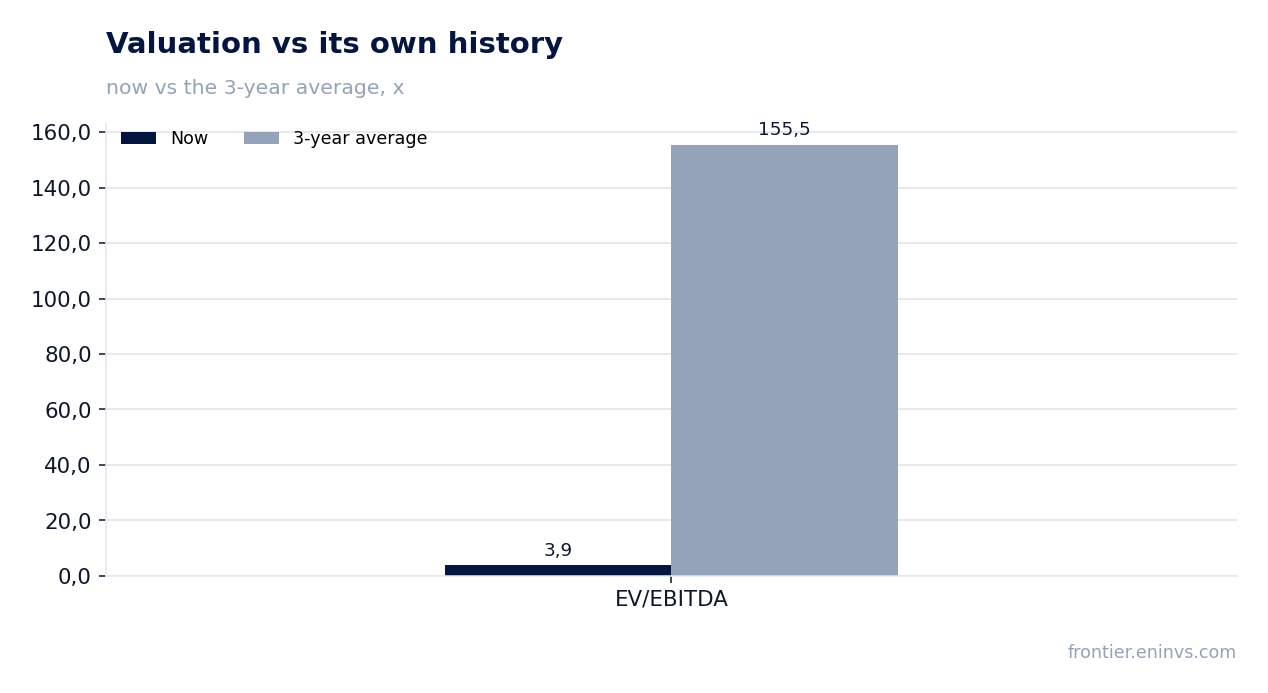
On 28 April AltynGold plc published its FY 2025 report. Revenue rose 81.7% to USD 175.4m, EBITDA by 97.2% to USD 101.4m and net profit by 134.7% to USD 62.0m. The EBITDA margin climbed to 57.8% from 53.3% a year earlier, while net debt fell to USD 18.5m, or 0.18 times LTM EBITDA. On the portal's model the share is 26% below fair value, and at an EV/EBITDA of 3.87 against its own three-year average of 155.5 the stock looks attractive.
Key takeaways
— Revenue rose 81.7% to USD 175.4m, and the gold price plus a fully loaded plant did almost all of it
— The EBITDA margin climbed to 57.8% from 53.3% because revenue grew faster than costs
— Net profit added 134.7% to USD 62.0m, and USD 2m of that was a one-off VAT write-off
— Operating cash flow came in at USD 55.7m while capital expenditure fell to USD 15.6m
— Net debt fell to USD 18.5m, or 0.18 times LTM EBITDA
— EV/EBITDA of 3.87 against its own three-year average of 155.5 puts the stock below its history
— On the portal's model the share is 26% below fair value
Attractiveness
Key figures, USD bn
| Metric | FY 2024 | FY 2025 | Change |
|---|---|---|---|
| Revenue | 0.10 | 0.18 | +81.7% |
| EBITDA | 0.05 | 0.10 | +97.2% |
| Operating profit | 0.04 | 0.09 | +101.1% |
| Net profit | 0.03 | 0.06 | +134.7% |
| Operating cash flow | 0.03 | 0.06 | +89.8% |
| EBITDA margin | 53.3% | 57.8% | +4.5 pp |
| Net margin | 27.4% | 35.4% | +8.0 pp |
Revenue rose 81.7% to USD 175.4m, and the gold price plus a fully loaded plant did almost all of it
FY 2025 revenue came in at USD 175.4m against USD 96.5m a year earlier. The company sold 50,442 ounces of gold versus 38,708 ounces, up 30%, while the average realised price rose to USD 3,474 per ounce from USD 2,441, up 42%. Both drivers worked at the same time, which is why the revenue increase was so large.
The Sekisovskoye plant ran a full year at its 1Mtpa capacity for the first time. Processing rose to 967kt from 594kt, and ore mined to 926kt from 750kt. Gold poured reached 53,852 ounces against 37,279 ounces, above the company's own 50,000-ounce target.
The processed gold grade fell to 2.05 g/t from 2.29 g/t, and recovery to 85.07% from 85.42%. The production increase came entirely from higher throughput, not from better ore. That matters for next year: holding output will require either more tonnage or richer ore from deeper levels.
The EBITDA margin climbed to 57.8% from 53.3% because revenue grew faster than costs
FY 2025 EBITDA reached USD 101.4m against USD 50.9m a year earlier, up 97.2%. The EBITDA margin rose to 57.8% from 53.3%. Revenue grew 81.7% while cost of sales went from USD 47m to USD 79m, up 68%. Operating leverage worked: fixed costs were spread over a larger volume.
Within cost of sales, subcontractor costs rose fastest, by USD 15.5m, which the company attributes to higher ore mined, labour rates and inflationary consumables. The mineral extraction tax added USD 6.8m on a 24% increase in ore extracted and a 42% rise in the gold price. Depreciation and amortisation rose USD 7.2m after new plant and machinery.
All-in sustaining costs rose to USD 1,562 per ounce from USD 1,318. The company attributes this to the transition to steady-state operations, processing optimisation and capital investment. With gold around USD 4,800 per ounce the margin remains very wide, but cost inflation is the main question for next year.
Net profit added 134.7% to USD 62.0m, and USD 2m of that was a one-off VAT write-off
FY 2025 net profit came in at USD 62.0m against USD 26.4m a year earlier. The net margin rose to 35.4% from 27.4%. Gross profit nearly doubled, to USD 96m from USD 49m. Tax payments totalled USD 17.5m, an effective rate of 19% after using tax losses.
Administrative costs rose to USD 9.7m from USD 6.6m. Of that increase, USD 2m was an irrecoverable VAT write-off and USD 0.8m was final payments for testing and implementing the third production line. Without those two items profit would have been about USD 2.8m lower, so one-offs explain a noticeable part of the increase.
Earnings per share and a 46.7% ROE reflect both the high margin and the reduced debt. But the quality of that profit is best checked against cash flow: that shows how much of the USD 62m actually reached the bank account.
Operating cash flow came in at USD 55.7m while capital expenditure fell to USD 15.6m
FY 2025 operating cash flow came in at USD 55.7m against USD 29.4m a year earlier. It almost matches the USD 62m net profit, which points to good earnings quality: the money did not get stuck in receivables or inventory. Year-end cash rose to USD 22.7m from USD 10.4m.
Capital expenditure fell to USD 15.6m from USD 21.9m because the plant upgrade is largely complete. For 2026–2028 the company has budgeted USD 95m of capex, of which USD 51m falls in 2026. That is more than it spent in 2025, and most of it goes to underground development, infrastructure and mining equipment.
Debt service and repayment cost USD 34.1m against USD 20.4m a year earlier. New financing raised USD 15m, mainly from refinancing a USD 10m bond at a lower coupon. Free cash flow after capex and debt remains positive, but debt service absorbs most of it.
Net debt fell to USD 18.5m, or 0.18 times LTM EBITDA
Net debt at end-2025 stood at USD 18.5m against USD 49.7m a year earlier. Total debt fell to USD 41.2m from USD 60.1m, while cash rose to USD 22.7m. Net debt to LTM EBITDA is 0.18. That is a low level for a mining company and gives a cushion if gold prices fall.
The company repaid bank debt in line with budget and expects to clear it fully by 2027. Bonds mature in 2027 and 2028. Refinancing the USD 10m bond at a lower coupon reduces interest costs.
Falling debt alongside rising EBITDA means credit quality has improved. But the current ratio cannot be compared with last year's because the earlier value is not in the facts. We can only state that the current level – 0.18 – is low.
EV/EBITDA of 3.87 against its own three-year average of 155.5 puts the stock below its history
LTM EV/EBITDA is 3.87. The three-year average of this multiple is 155.5. The gap is enormous and reflects the fact that in earlier years EBITDA was close to zero or negative, pushing the multiple towards infinity. Now, with EBITDA at USD 101.4m, the valuation rests on sustainable earnings for the first time.
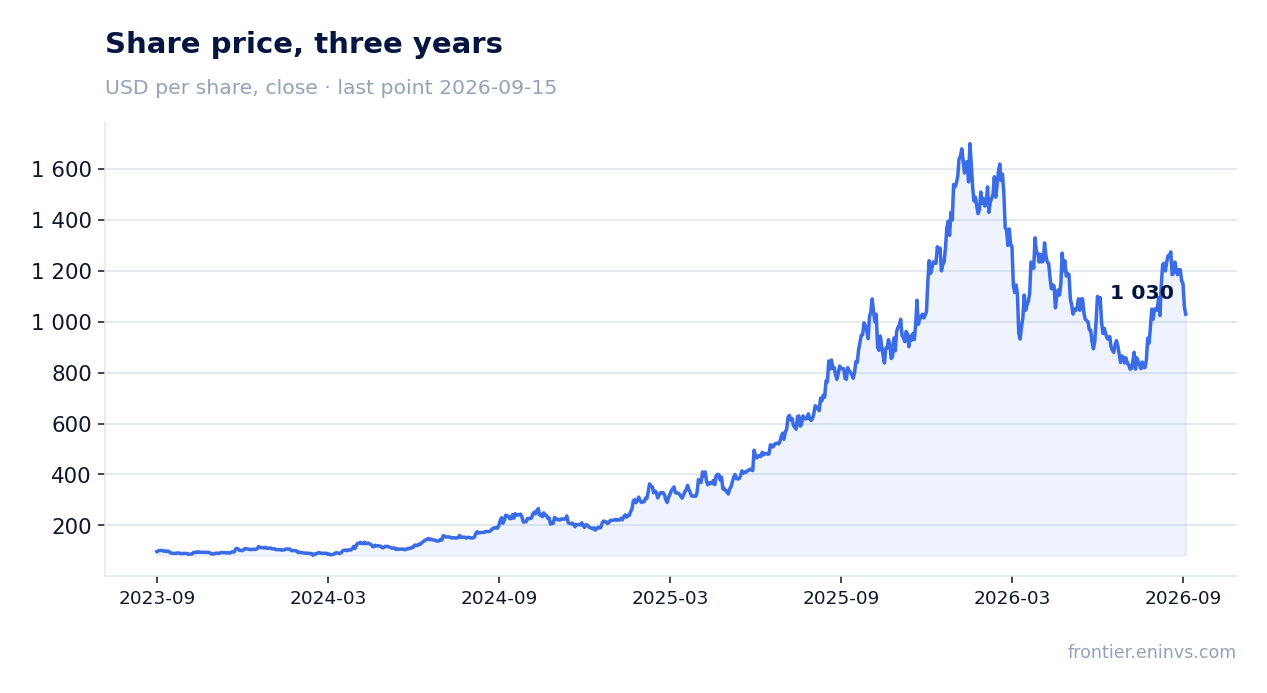
LTM P/E is 6.04. With a market capitalisation of USD 374.4m and net debt of USD 18.5m, enterprise value is about USD 393m. That is less than four times annual EBITDA. For a gold producer with growing output and low debt, that multiple looks modest.
On the portal's model, which reprices EBITDA at current commodity prices and a target EV/EBITDA, the upside to fair value is +26%. That is our own estimate, not a market consensus. It rests on gold around USD 4,800 per ounce, which is 39% above the 2025 average realised price.
On the portal's model the share is 26% below fair value
Our model reprices EBITDA at current gold prices and applies a target EV/EBITDA to the market capitalisation. With gold around USD 4,800 per ounce, the upside to fair value is +26%. That is not a share price forecast but an estimate of how far the current quote lags fundamental value in the present environment.
The share is held in live model strategies on the portal, including KZ Fundamental potential (AI). Membership follows each strategy's own screen and is not an argument for the valuation – it is simply a fact.
The key risk to this estimate is the gold price. If it returns to the 2025 average realised price of USD 3,474 per ounce, EBITDA and fair value would be lower. But even at that price the EV/EBITDA multiple stays below 5, and debt is low.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 0.37 bn USD |
| P/E (LTM) | 6.0 |
| EV/EBITDA (LTM) | 3.9 |
| P/B | 2.49 |
| Net debt / EBITDA (LTM) | 0.18 |
| Operating cash flow (LTM) | 0.06 bn |
| ROE | 46.7% |
| EV/EBITDA, 3-year average | 155.5 |
Bottom line
FY 2025 was a breakthrough year for AltynGold: revenue rose 81.7%, EBITDA 97.2% and net profit 134.7%. The EBITDA margin climbed to 57.8%, while net debt fell to USD 18.5m, or 0.18 times EBITDA. Part of the profit increase was one-off – USD 2m of VAT write-off and USD 0.8m of payments for the third line – but operating cash flow of USD 55.7m confirms the money was earned, not just booked. At an EV/EBITDA of 3.87 against its own three-year average of 155.5 and with 26% upside on the portal's model, the share looks attractive. The key question for a holder is whether the company can hold the margin as AISC rises to USD 1,562 per ounce, and what the next report shows on output and costs.
Open the company's financial profile ALTYNGOLD →
See also: market overview · valuation map · stock screeners