ASBN: H1 2026 profit fell 35.4% even as net interest income rose 45.2%
The H1 2026 report shows a divergence: net interest income grew 45.2% year on year to KZT 208,308 million, while net profit fell 35.4% to KZT 64,583 million. Profit was only 31.0% of net interest income, down from 69.7% a year earlier. Over the last twelve months, profit stands at KZT 116,437 million, and the stock trades at a P/E of 9.8 with a dividend yield of 7.8%. Verdict – neutral: strong net interest income growth and a high dividend yield are offset by a sharp profit decline and the absence of an explanation for it in the report.
Key takeaways
— Net interest income in H1 2026 grew 45.2% to KZT 208,308 million, but that did not save profit
— Net profit in H1 2026 fell 35.4% to KZT 64,583 million, just 31.0% of net interest income
— Operating profit in H1 2026 was KZT 78,533 million, indicating significant expenses below the operating line
— Over the last twelve months, net profit is KZT 116,437 million, and the market values it at a P/E of 9.8
— The trailing twelve-month dividend yield is 7.8%, above the current yield of many instruments
— According to the portal's model, the stock has an upside to fair value of +8%
Attractiveness
Key figures, KZT bn
| Metric | H1 2025 | H1 2026 | Change |
|---|---|---|---|
| Net interest income | 143 | 208 | +45.2% |
| Operating profit | 109 | 78.5 | -27.8% |
| Net profit | 100 | 64.6 | -35.4% |
| Net margin | 69.7% | 31.0% | -38.7 pp |
Net interest income in H1 2026 grew 45.2% to KZT 208,308 million, but that did not save profit
Net interest income for H1 2026 was KZT 208,308 million, up 45.2% from the same period last year. This is strong growth, indicating an expansion of the interest business. However, the bottom line did not follow.
The main reason for this divergence could be an increase in non-interest expenses or provisions for credit losses. The report does not disclose these details, so we can only state the fact: interest income grew, but profit fell.
Net profit in H1 2026 fell 35.4% to KZT 64,583 million, just 31.0% of net interest income
Net profit for H1 2026 was KZT 64,583 million, down 35.4% year on year. This is a sharp decline that contrasts with the growth in net interest income. Profit as a share of net interest income fell to 31.0% from 69.7% a year earlier.
This decline in profit margin could be due to one-off write-offs or higher operating expenses. Without additional information from the report, it is difficult to pinpoint the exact cause, but the fact remains: profitability has deteriorated significantly.
Operating profit in H1 2026 was KZT 78,533 million, indicating significant expenses below the operating line
Operating profit for H1 2026 was KZT 78,533 million. This is an intermediate figure between net interest income and net profit. The difference between operating and net profit is KZT 13,950 million, which may include taxes and other expenses.
Such a significant gap between operating and net profit indicates that a substantial portion of income goes to taxes or other mandatory payments. This reduces the overall efficiency of the business.
Over the last twelve months, net profit is KZT 116,437 million, and the market values it at a P/E of 9.8
Over the last twelve months, net profit was KZT 116,437 million. This is noticeably higher than in H1 2026 alone, suggesting that profit in the second half of 2025 was substantially higher. The current P/E is 9.8.
It is impossible to compare this multiple with a three-year average, as the FACTS do not provide historical data. However, a P/E below 10 is generally considered low for the banking sector, which may indicate undervaluation.
The trailing twelve-month dividend yield is 7.8%, above the current yield of many instruments
The trailing twelve-month dividend yield is 7.8%. This is a high figure that may attract income-oriented investors. For comparison, the key rate in Kazakhstan has recently been below this level, making dividends attractive.
However, dividend sustainability depends on profit. If the profit decline in H1 2026 proves not to be one-off, dividend payments could be reduced. This is a key risk for shareholders.
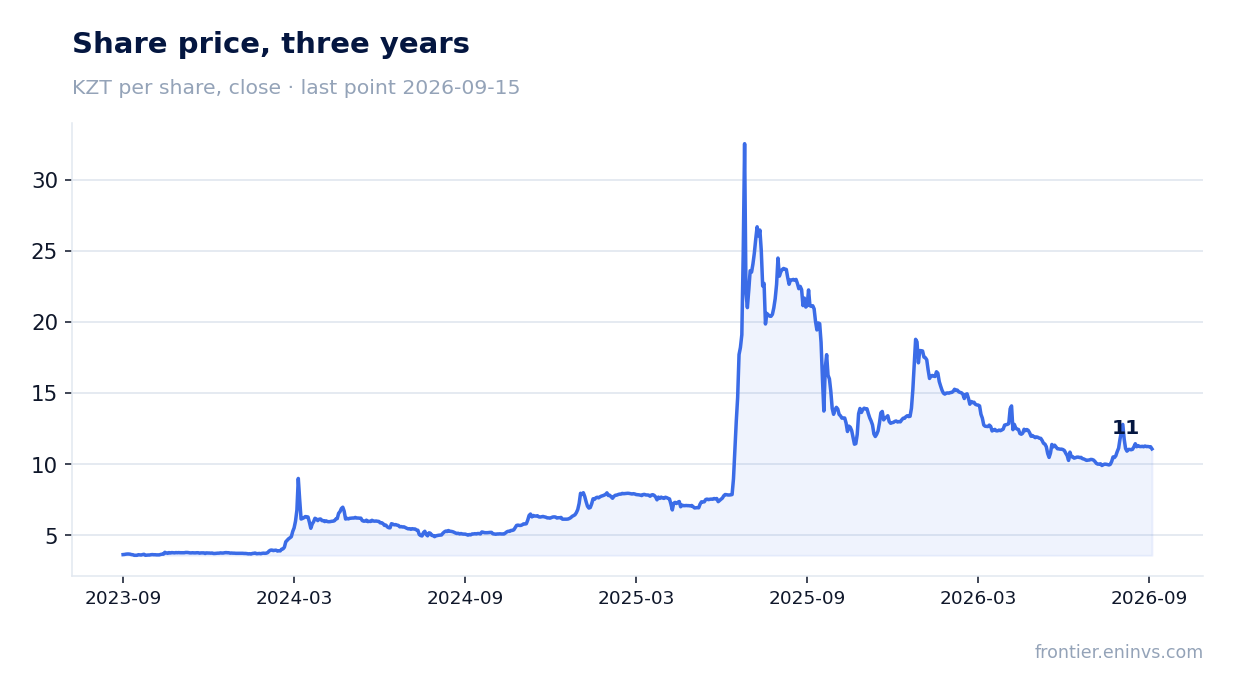
According to the portal's model, the stock has an upside to fair value of +8%
According to the portal's model, which compares return on equity with the price-to-book ratio, the fair value of the stock is 8% above the current market price. This is a moderate upside.
The model takes into account current earnings and book value but does not account for potential changes in dividend policy or asset quality. Therefore, this estimate should be treated as a guide, not a guaranteed outcome.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 1 142 bn KZT |
| P/E (LTM) | 9.8 |
| P/B | 2.66 |
| ROE | 15.2% |
| Dividend yield (12m) | 7.8% |
Bottom line
Bottom line: ASBN showed strong growth in net interest income in H1 2026, but net profit fell sharply. Trailing twelve-month profit remains solid, and the 7.8% dividend yield and P/E of 9.8 look attractive. However, without understanding the causes of the profit decline and the sustainability of dividends, the stock cannot be considered unequivocally attractive. Verdict – neutral: the current valuation is fair, but risks require attention.
Open the company's financial profile ASBN →
See also: market overview · valuation map · stock screeners