América Móvil: profit up a quarter, but almost all EBITDA growth was eaten by a one-off gain and a weak peso
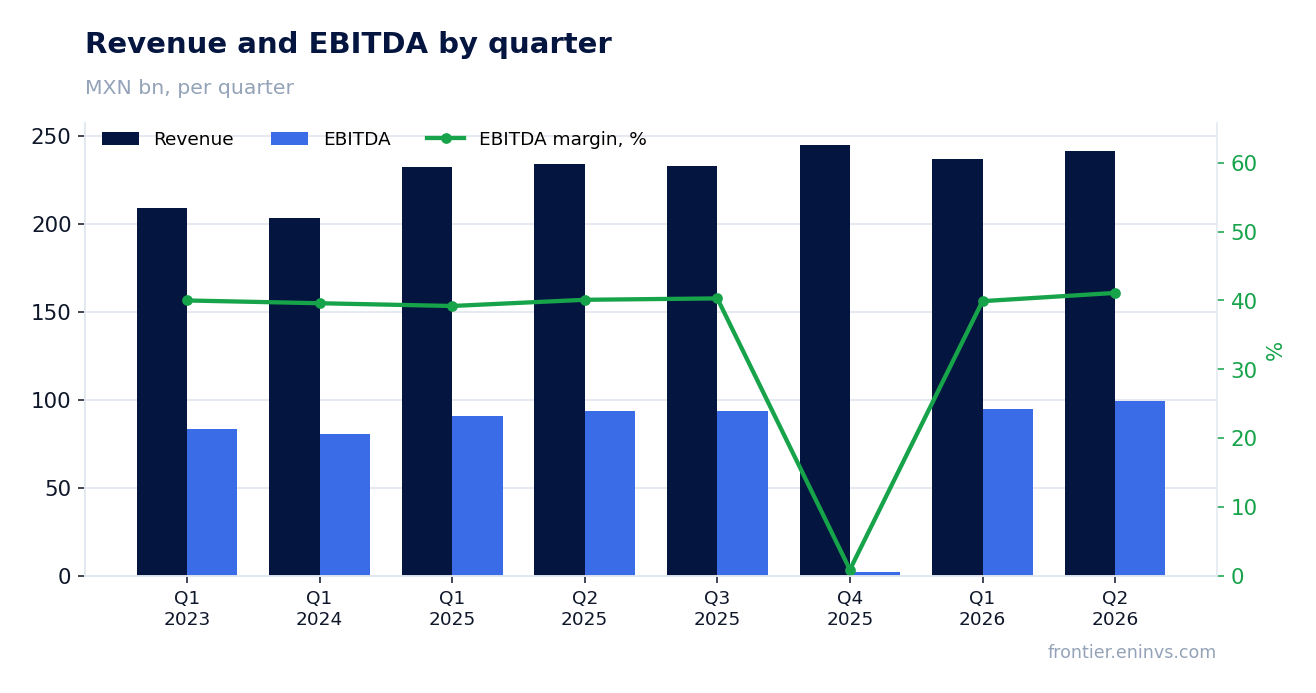
On 21 April América Móvil released its first-quarter 2026 results. Revenue rose 2.1% year on year to 236.8 bn pesos, EBITDA – 3.8% to 94.5 bn, net profit – 25.1% to 23.4 bn. Without the one-off gain from a Chilean TV-rights dispute and without the peso's appreciation the growth would have been more modest, while the EV/EBITDA multiple of 4.4 sits below its own three-year average of 4.77 – the share looks rather attractive than neutral.
Key takeaways
— Revenue added only 2.1% in pesos but 6.1% at constant currency – the peso ate almost all the growth
— A one-off gain from the Chilean TV-rights dispute brought 43 bn Chilean pesos and inflated EBITDA
— EBITDA margin fell to 40.4% from 42.1% a year earlier, despite operating profit growth
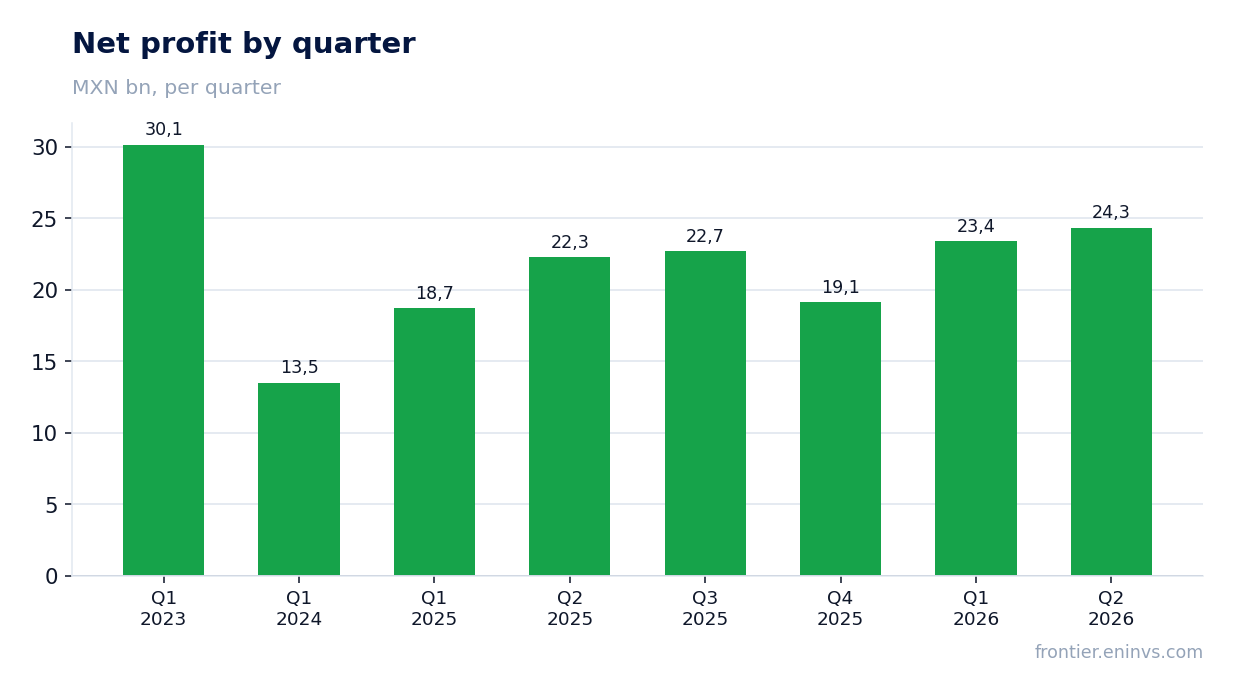
— Net profit rose 25.1% on lower financial expenses, not on operating performance
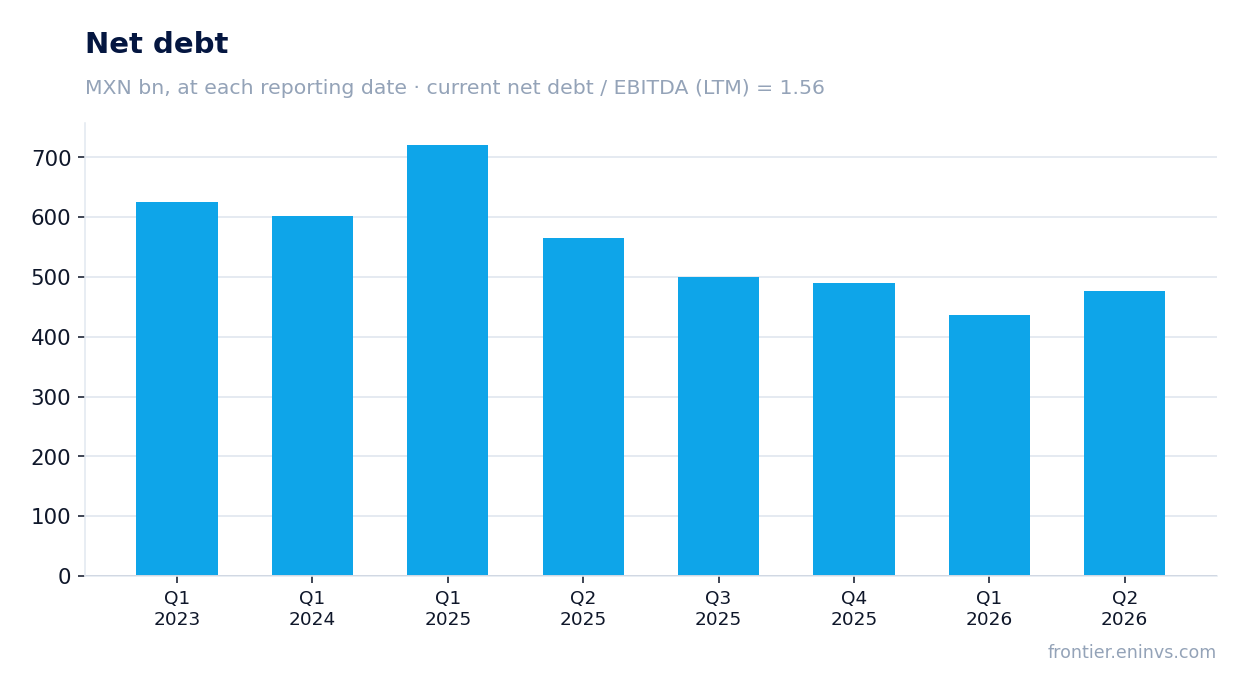
— Leverage at 1.56x EBITDA LTM is moderate, but debt rose 39.9 bn pesos in the quarter
— Dividend of 0.54 pesos per share at a 2.66% yield is modest, but the company is spending on buybacks
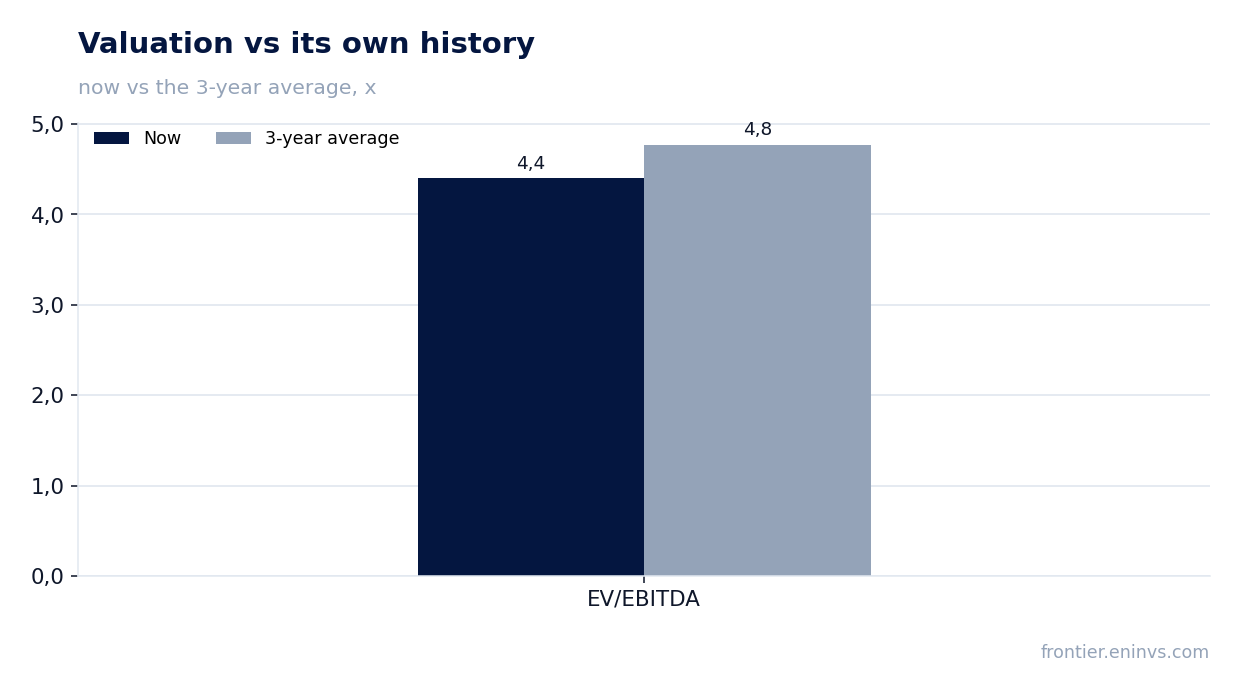
— EV/EBITDA of 4.4 is below its own three-year average of 4.77 – valuation is not stretched
Attractiveness
Key figures, MXN bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 234 | 241 | +3.1% |
| EBITDA | 98.4 | 97.3 | -1.1% |
| Operating profit | 48.8 | 55.1 | +12.9% |
| Net profit | 22.3 | 24.3 | +9.2% |
| EBITDA margin | 42.1% | 40.4% | -1.7 pp |
| Net margin | 9.5% | 10.1% | +0.6 pp |
Revenue added only 2.1% in pesos but 6.1% at constant currency – the peso ate almost all the growth
First-quarter 2026 revenue came in at 236.8 bn pesos, up 2.1% year on year. The company's report states that at constant exchange rates growth was 6.1%, with service revenue up 4.6%. The gap is explained by the appreciation of the Mexican peso: it gained 16.3% against the US dollar year on year, 4.6% against the euro, and 4.5% against the Brazilian real.
The mobile segment was the main contributor: service revenue there rose 6.4%, including prepaid up 5.0% and postpaid up 7.3%. In Mexico mobile service revenue added 5.7% – the best in two years; in Brazil 7.8%; in Colombia 10.2%, the strongest in a decade. Fixed-line service revenue grew more slowly, at 1.7%.
The weak peso-denominated growth should not mislead: operating metrics in local currencies look stronger. In Mexico revenue rose 5.1%, in Brazil 6.8% in reais, in Colombia 5.9% in Colombian pesos. But for reporting in Mexican pesos these gains are almost entirely offset by currency movements.
A one-off gain from the Chilean TV-rights dispute brought 43 bn Chilean pesos and inflated EBITDA
The report explicitly states that first-quarter revenue includes proceeds from a favourable ruling in a Chilean TV-rights dispute amounting to 43 bn Chilean pesos. This one-off gain boosted consolidated EBITDA: excluding it, the company calculates constant-currency EBITDA growth would have been 7.0% rather than 8.0%.
This one-off factor explains why Southern Cone EBITDA jumped 94.0% in Chilean pesos and the block's margin leapt to 29.9% from 19.2%. Excluding the Chilean gain, Southern Cone EBITDA would have risen 23.2%, with the margin at 21.3%. For the whole company the effect is smaller but present: without it, EBITDA would have grown roughly 3.0% in pesos instead of 3.8%.
The one-off nature of the gain means this contribution will disappear next quarter. Investors should assess the company's sustainable EBITDA generation, not the reported first-quarter figure.
EBITDA margin fell to 40.4% from 42.1% a year earlier, despite operating profit growth
The EBITDA margin in the first quarter of 2026 was 40.4% against 42.1% a year earlier. A margin decline with revenue up 2.1% means costs grew faster than income. The report notes that cost of service fell 1.2%, but cost of equipment rose 6.3% and selling, general and administrative expenses added 0.3%.
Operating profit nevertheless rose 12.7% to 50.5 bn pesos, with its margin up to 21.3% from 19.3%. The gap between EBITDA and EBIT dynamics is explained by a 4.9% decline in depreciation – the company likely completed part of its investment programmes from previous years.
The net margin, by contrast, improved to 10.1% from 9.5%. This came not from operating efficiency but from a 9.9% reduction in financial expenses and a positive effect from exchange-rate differences: in the first quarter of 2026 the company recorded a foreign-exchange gain of 5.0 bn pesos versus a loss of 1.2 bn a year earlier.
Net profit rose 25.1% on lower financial expenses, not on operating performance
Net profit for the first quarter of 2026 was 23.4 bn pesos, up 25.1% year on year. However, this growth was driven mainly not by operations but by a 9.9% reduction in comprehensive financing costs – to 12.1 bn pesos. Interest expenses fell 6.7% thanks to lower rates and debt refinancing.
An additional contribution came from a positive exchange-rate effect: a gain of 5.0 bn pesos from the revaluation of foreign-currency liabilities versus a loss of 1.2 bn a year earlier. Without this factor, net profit growth would have been considerably more modest.
Operating profit rose 12.7% to 50.5 bn pesos, which is decent in itself, but net profit growth is almost twice as fast. This means the quality of profit this quarter is lower than it appears: the sustainable component is operating profit, while financial factors can swing either way.
Leverage at 1.56x EBITDA LTM is moderate, but debt rose 39.9 bn pesos in the quarter
Net debt at the end of the first quarter of 2026 stood at 661.6 bn pesos, equivalent to 1.56x EBITDA for the trailing twelve months. The company's report states that net debt excluding leases was 437.0 bn pesos, equivalent to 1.41x EBITDAaL. The difference is explained by the inclusion of lease liabilities of around 218 bn pesos.
Net debt rose 39.9 bn pesos in the quarter but fell 87.8 bn pesos over the last twelve months. The company allocated 1.0 bn pesos of free cash flow to debt reduction and spent 21.6 bn on capital expenditure, 1.4 bn on share buybacks and 1.5 bn on labour obligations.
A leverage level of 1.56x EBITDA LTM is not a concern for a telecommunications company. Interest expenses are covered by operating profit with a large margin, and falling rates in Mexico and the US create conditions for further reductions in debt servicing costs.
Dividend of 0.54 pesos per share at a 2.66% yield is modest, but the company is spending on buybacks
The board proposed that the annual shareholders' meeting approve a dividend of 0.54 pesos per share, payable in two equal instalments. At the current price the trailing twelve-month yield is 2.66%. This is a modest level, especially given that Mexican rates remain high.
The company also proposed allocating an additional 10 bn pesos to the share-buyback fund for April 2026 to April 2027. In the first quarter 1.4 bn pesos was already spent on buybacks. Buybacks reduce the number of shares outstanding – from 60.9 bn a year earlier to 60.2 bn – supporting earnings per share.
The company's dividend policy remains conservative: payouts represent only a portion of free cash flow, which in the first quarter was just 3.3 bn pesos. The bulk of funds goes to capital expenditure and debt reduction. For an income-oriented investor this is not the most attractive option, but for long-term value creation it is a reasonable balance.
EV/EBITDA of 4.4 is below its own three-year average of 4.77 – valuation is not stretched
The trailing twelve-month EV/EBITDA multiple is 4.40, below its own three-year average of 4.77. This means the market values the company more cheaply than it did on average over the past three years. The trailing P/E is 13.4 and return on equity is 22.3%.
According to the portal's model, the fair value of the share based on EBITDA growth and the target multiple implies +14% upside to the current price. This is our own estimate, not a market consensus or a target price. It assumes the company maintains its current EBITDA growth rate and the multiple stays at its current level.
The share trades at a discount to its own history, which may reflect the slowdown in peso-denominated revenue growth and the one-off nature of part of the profit. If the company can accelerate revenue growth in local currencies or if the peso stops appreciating, the discount could narrow.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 1 202 bn MXN |
| P/E (LTM) | 13.4 |
| EV/EBITDA (LTM) | 4.4 |
| P/B | 2.81 |
| Net debt / EBITDA (LTM) | 1.56 |
| Operating cash flow (LTM) | 272 bn |
| ROE | 22.3% |
| Dividend yield (12m) | 2.7% |
| EV/EBITDA, 3-year average | 4.8 |
Bottom line
The first quarter of 2026 showed that América Móvil remains a resilient telecommunications business with growing operating profit and low leverage. However, reported revenue rose only 2.1% due to the peso's appreciation, and almost all of the EBITDA and net profit growth came from the one-off Chilean dispute gain and lower financial expenses. The EV/EBITDA multiple of 4.4 is below its own three-year average, and the portal's model implies +14% upside, making the share rather attractive. The key question for a holder is whether the company can accelerate revenue growth in local currencies and sustain its margin without one-off factors.
Open the company's financial profile AMX →
See also: market overview · valuation map · stock screeners