Grupo México: profit up 78.5%, but almost all of it comes from metal prices, not volumes
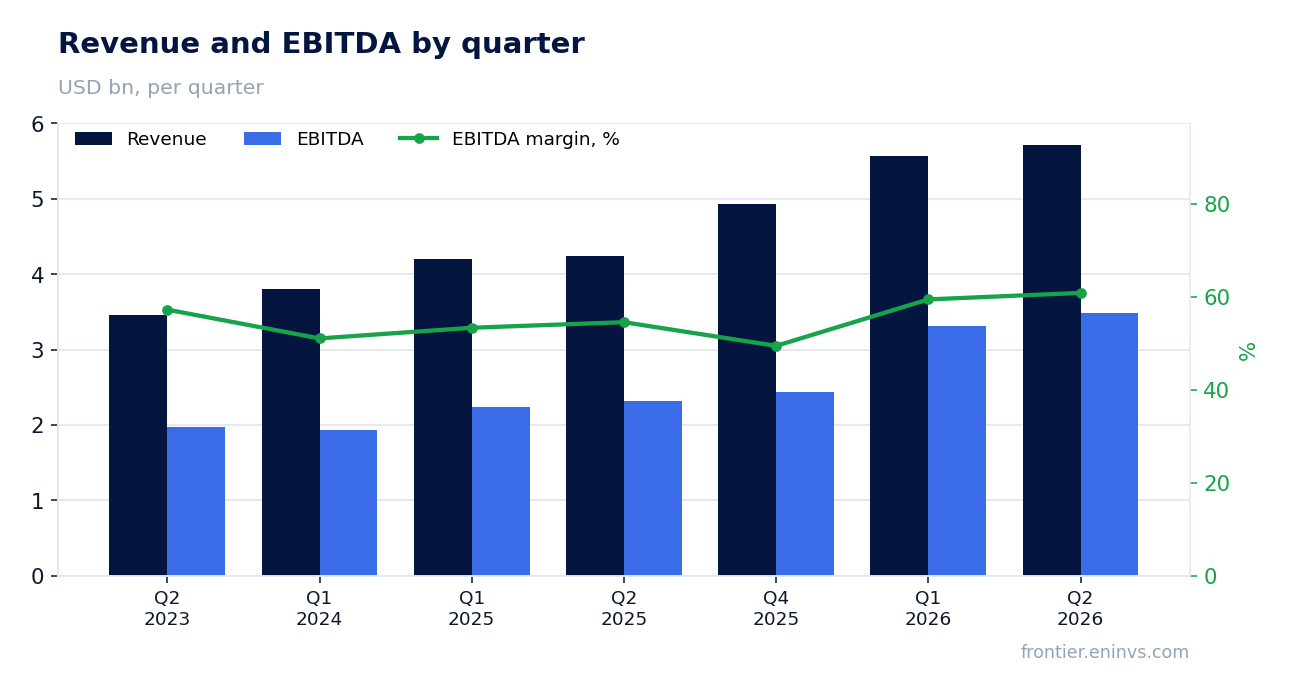
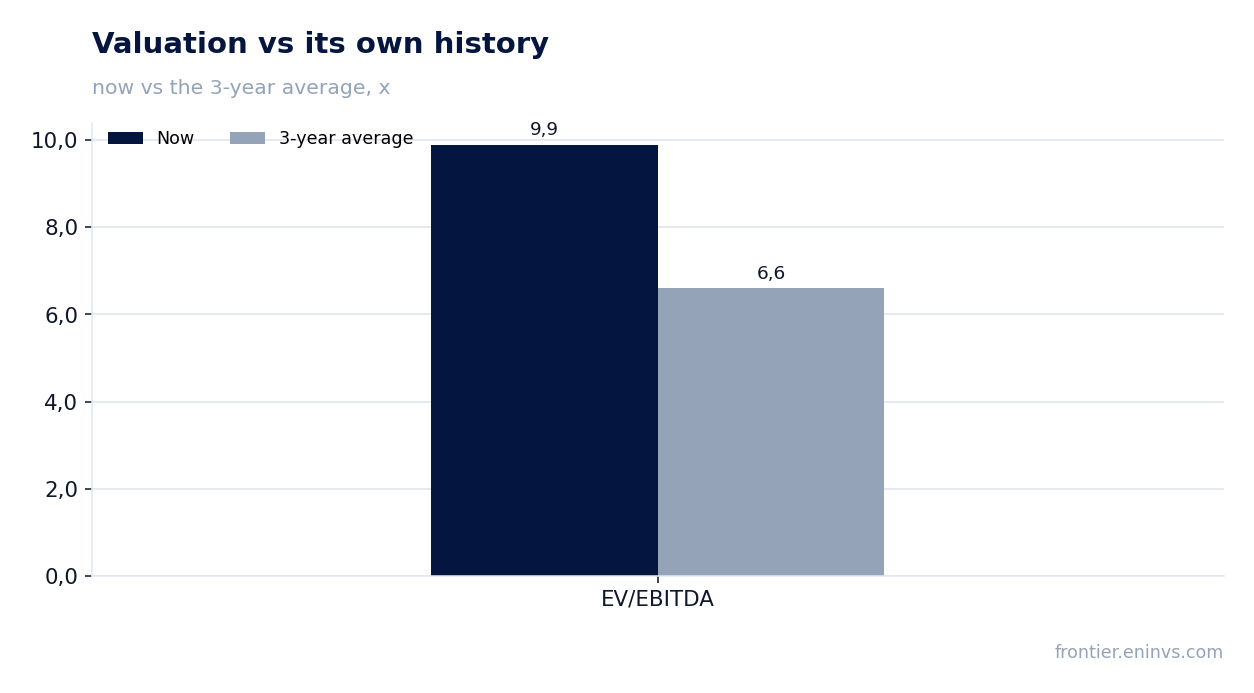
On April 28, Grupo México released its first-quarter 2026 results. Revenue reached a record $5.57 billion (+32.7% year on year), EBITDA – $3.31 billion (+49.6%), net profit – $1.64 billion (+62.4%). The EBITDA margin rose to 59.5% from 52.8%, and the net margin to 29.4% from 24.0%. The stock trades at EV/EBITDA of 9.9 against its own three-year average of 6.6, and on the portal's model the share is 21% below its current price, so despite the strong report the valuation looks neutral.
Key takeaways
— Revenue rose 32.7% to a record $5.57 billion, and almost all of the gain came from metal prices, not volumes
— EBITDA added 49.6%, but the margin rose only 6.7 pp – most of the gain was eaten by costs
— Net profit rose 62.4%, but 78.5% of the annual growth is a low-base effect from last year
— Leverage remains minimal: net debt of $0.95 billion against LTM EBITDA of $9.91 billion
— Dividend yield of 2.55% on a payout of MXN 1.65 per share – below Mexican peers
— Valuation at EV/EBITDA of 9.9 against a three-year average of 6.6 – the stock trades above its own history
— The portal's model values the share 21% below its current price, leaving no room for upside
Attractiveness
Key figures, USD bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 4.24 | 5.72 | +35.0% |
| EBITDA | 2.48 | 3.69 | +48.9% |
| Operating profit | 1.99 | 3.12 | +56.6% |
| Net profit | 1.23 | 2.20 | +78.5% |
| Operating cash flow | 1.27 | 3.65 | +188.0% |
| EBITDA margin | 58.5% | 64.5% | +6.0 pp |
| Net margin | 29.1% | 38.5% | +9.4 pp |
Revenue rose 32.7% to a record $5.57 billion, and almost all of the gain came from metal prices, not volumes
Consolidated revenue in the first quarter of 2026 was $5.57 billion, up 32.7% year on year. The mining division contributed $4.61 billion (+37.7%), transportation – $896 million (+15.6%), infrastructure – $158 million (–9.5%).
The main driver is metal prices. The average copper price rose 26.9% year on year, silver – 157.9%, molybdenum – 25.3%, zinc – 14.0%. At the same time, copper production fell 2.8% to 258,138 tonnes due to lower ore grades at Peruvian operations. So revenue grew not from higher shipments but from price conditions.
The transportation division showed volume growth: carloads increased 4.4%, tonne-kilometres – 8.9%. However, its contribution to total revenue is only 16%, so even double-digit growth here could not offset the impact of metal prices.
The infrastructure division cut revenue by 9.5% due to the suspension of two drilling rigs in February 2025 and lower gas prices. This is the only segment with negative dynamics, but its share of revenue is less than 3%.
EBITDA added 49.6%, but the margin rose only 6.7 pp – most of the gain was eaten by costs
EBITDA in the first quarter of 2026 was $3.31 billion, up 49.6% year on year. The EBITDA margin rose to 59.5% from 52.8% a year earlier. The 6.7 pp margin gain looks modest against 32.7% revenue growth – meaning a significant part of the additional revenue went to cover higher costs.
Cost of sales rose 15.3% to $2.14 billion, below the revenue growth rate. This is explained by the fact that metal price growth was not accompanied by a proportional increase in extraction costs. However, administrative expenses increased 16.5%, and exploration expenses – 30.1%.
The mining division showed EBITDA of $2.87 billion (+59.2%) with a margin of 62.3% against 53.9% a year earlier. The transportation division – $376 million (+11.7%) with a margin of 42.0% against 43.4%. Infrastructure – $83 million (+4.1%) with a margin of 52.4% against 45.5%.
The margin decline in the transportation division is due to faster cost growth (+18.5%) compared to revenue (+15.6%). In the mining division, on the contrary, cost of sales rose only 13.8%, which provided the main margin gain.
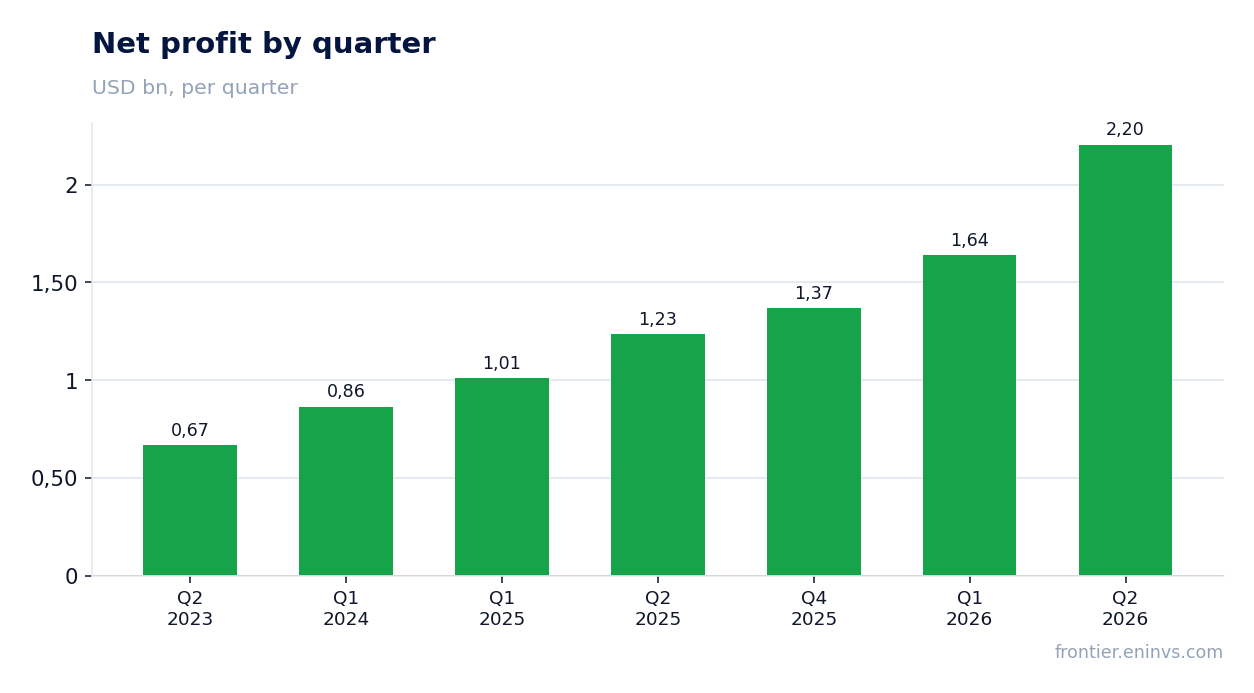
Net profit rose 62.4%, but 78.5% of the annual growth is a low-base effect from last year
Net profit in the first quarter of 2026 was $1.64 billion, up 62.4% year on year. However, year-on-year net profit growth was 78.5% – higher than EBITDA growth, indicating the impact of non-operating factors.
The main contribution to profit growth came from financial items: interest expense rose 14.9% to $170 million, but interest income remained virtually flat at $105 million. The balance of other income and expenses improved by $28.4 million, related to exchange rate differences and tax effects.
The effective tax rate declined: taxes rose 62.5% to $972 million, but their share of pre-tax profit was 34.6% against 33.8% a year earlier. This means that net profit growth was largely driven not by operational efficiency but by a lower tax burden and the low-base effect from last year.
The share of non-controlling interests in net profit rose 39.4% to $235 million, reflecting improved results at subsidiaries, particularly Southern Copper.
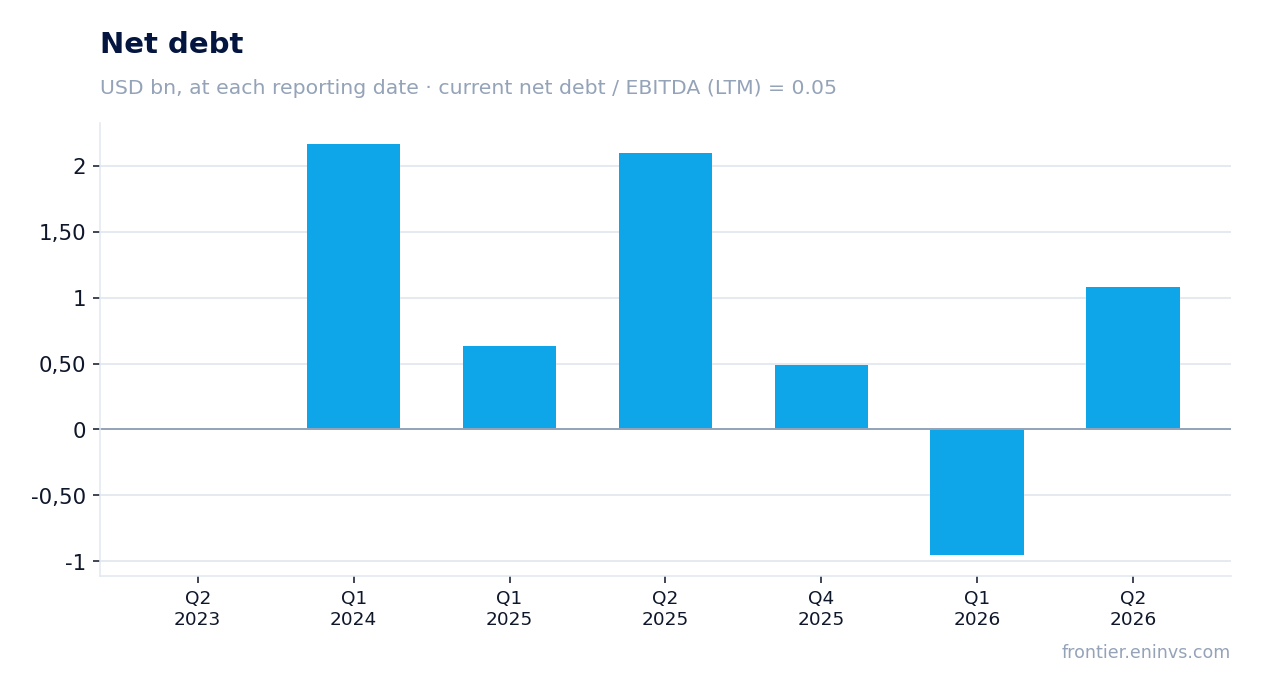
Leverage remains minimal: net debt of $0.95 billion against LTM EBITDA of $9.91 billion
Net debt at the end of the first quarter of 2026 was $0.95 billion, corresponding to a net debt to LTM EBITDA ratio of 0.05. This is an extremely low figure, reflecting the company's ability to generate significant cash flow with low debt burden.
Operating cash flow in the first quarter of 2026 was $1.65 billion, up 89.7% year on year. This allowed the company to finance capital expenditures of $524 million and pay dividends of $826 million, while maintaining a positive cash balance.
The debt structure is balanced: 78% of liabilities are denominated in US dollars, 22% in Mexican pesos. 83% of debt has a fixed rate, reducing interest rate risk. Total debt is $9.94 billion, with the short-term portion at only $443 million.
The company has a comfortable debt maturity profile and significant liquidity buffer: cash and equivalents at the end of the quarter were $10.89 billion. This provides a margin of safety even if market conditions deteriorate.
Dividend yield of 2.55% on a payout of MXN 1.65 per share – below Mexican peers
On April 24, 2026, the board of directors of Grupo México declared a cash dividend of MXN 1.65 per share, to be paid in a single installment on June 1, 2026. This corresponds to an annualized dividend yield of about 3.3% at the current price, although the trailing 12-month yield is 2.55%.
Based on our estimates from current profit and dividend policy, the company could allocate about 40% of net profit for 2026 to dividends. If current metal prices and production volumes persist, net profit for the year could be around $6.5 billion, implying dividend payments of approximately $2.6 billion.
However, a dividend yield of 2.55% looks modest against Mexico's key rate, which remains at 7.5%. This means investors receive a risk premium for holding the shares of about 5 percentage points, which may be insufficient for conservative investors.
The main risks to the dividend are related to a possible decline in copper and silver prices, as well as increased capital expenditures on development projects such as Tia Maria and Los Chancas. If the company decides to accelerate investments, dividend payments could be cut.
Valuation at EV/EBITDA of 9.9 against a three-year average of 6.6 – the stock trades above its own history
Grupo México's current valuation at EV/EBITDA LTM is 9.9, significantly above its three-year average of 6.6. This means the market values the company more expensively than on average over the past three years, which may be due to expectations of higher copper and silver prices.
The P/E LTM ratio is 19.4, also above historical levels. At the same time, ROE reaches 37.9%, reflecting high capital efficiency. However, the high return on equity is partly explained by the low share of equity in the financing structure.
According to the portal's model, which re-prices EBITDA at current commodity prices at the target EV/EBITDA, the fair value of the share is 21% below the current market price. This means that even with high metal prices, the stock looks overvalued.
For comparison: a dividend yield of 2.55% and EV/EBITDA of 9.9 create a combination that leaves no significant room for upside. If copper and silver prices remain at current levels, multiples may stay elevated, but further stock growth requires either higher production volumes or lower capital expenditures.
The portal's model values the share 21% below its current price, leaving no room for upside
According to the portal's model, which re-prices EBITDA at current commodity prices at the target EV/EBITDA, the fair value of Grupo México's share is 21% below the current market price. This is a key argument for a neutral rating: even with record metal prices, the stock trades above its fair value.
The model takes into account current prices for copper, silver, molybdenum and zinc, as well as current production levels. If metal prices remain at current levels, LTM EBITDA could be around $9.9 billion, which at a target multiple of 6.6 gives a fair value significantly below the current price.
It is important to note that the model does not account for possible production growth after the launch of the Tia Maria and Los Chancas projects, scheduled for 2027 and 2031 respectively. However, these projects require significant capital expenditures and carry delay risks.
Thus, the current valuation leaves no room for upside unless metal prices continue to rise or the company increases production faster than expected. This makes the stock vulnerable to a correction in commodity prices.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 97.5 bn USD |
| P/E (LTM) | 19.4 |
| EV/EBITDA (LTM) | 9.9 |
| P/B | 4.19 |
| Net debt / EBITDA (LTM) | 0.05 |
| Operating cash flow (LTM) | 6.00 bn |
| ROE | 37.9% |
| Dividend yield (12m) | 2.6% |
| EV/EBITDA, 3-year average | 6.6 |
Bottom line
The first-quarter 2026 report showed record revenue and profit, but almost all growth was driven by metal prices rather than production volumes. The EBITDA margin rose to 59.5%, but rising costs and lower copper production limit the sustainability of this improvement. Leverage is minimal, and operating cash flow covers capital expenditures and dividends. The key question for a holder is whether the company can justify its current valuation, which is already above its three-year average, if commodity prices stop rising.
Open the company's financial profile GMEXICO →
See also: market overview · valuation map · stock screeners