Coca-Cola FEMSA: profit up 16.9%, but debt jumped 36.1 bn rubles in the quarter
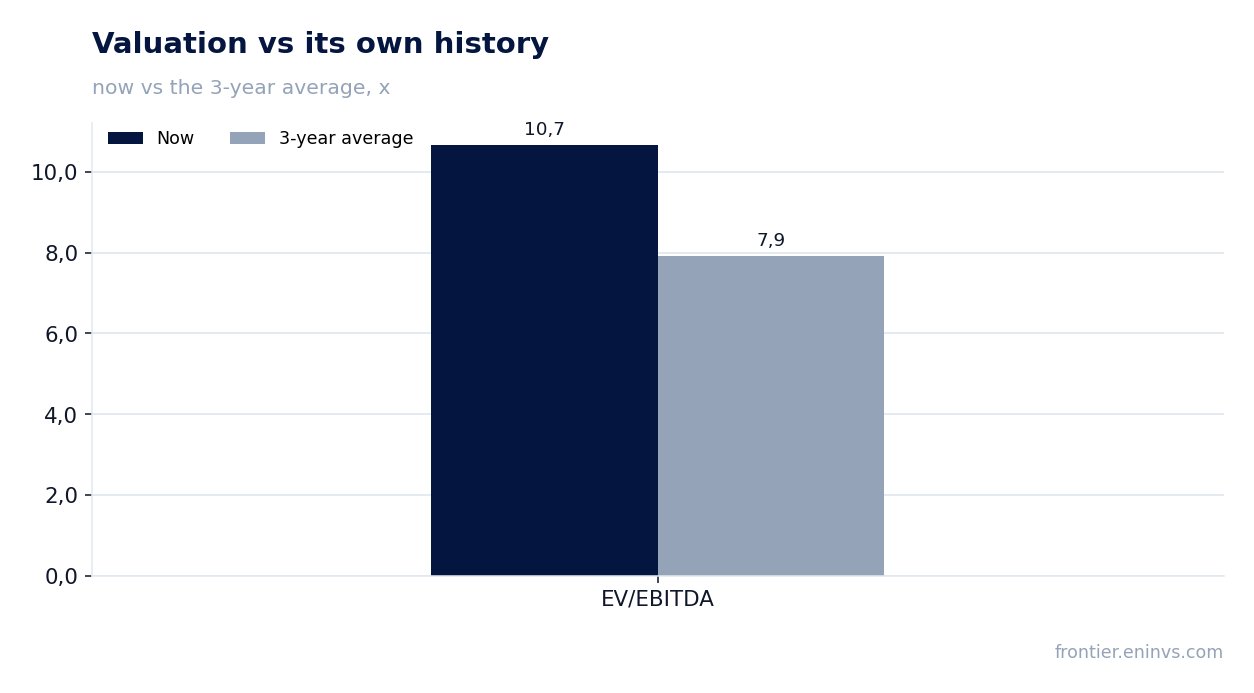
On April 29, Coca-Cola FEMSA reported first-quarter 2026 results. Revenue rose 4.7% year on year to 76,318 mn pesos, EBITDA – 8.3% to 10,527 mn pesos, net profit – 16.9% to 6,211 mn pesos. Profit growth against a lower operating margin looks contradictory, and debt increased by 36.1 bn rubles in the quarter. With EV/EBITDA at 10.7 versus its own three-year average of 7.9, the share looks rather unattractive despite a 3.9% dividend yield.
Key takeaways
— Revenue grew 4.7% year on year, but in Mexico and Central America it fell 1.4%
— EBITDA rose 8.3%, although operating profit declined 2.3% due to higher expenses
— Net profit increased 16.9% despite a lower operating margin – one-off items helped
— Debt increased by 36.1 bn rubles in the quarter, with net debt/EBITDA at 1.04
— Dividend yield of 3.9% with a payout of 7.74 pesos per unit for 2025
— EV/EBITDA at 10.7 versus its own three-year average of 7.9 – valuation above historical
— On the portal's model, upside to fair value is zero
Attractiveness
Key figures, MXN bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 72.9 | 76.3 | +4.7% |
| EBITDA | 10.6 | 11.5 | +8.3% |
| Operating profit | 9.65 | 10.5 | +9.0% |
| Net profit | 5.31 | 6.21 | +16.9% |
| EBITDA margin | 14.6% | 15.1% | +0.5 pp |
| Net margin | 7.3% | 8.1% | +0.8 pp |
Revenue grew 4.7% year on year, but in Mexico and Central America it fell 1.4%
Revenue in the first quarter of 2026 amounted to 76,318 mn pesos, up 4.7% year on year. Growth was driven by South America and revenue management initiatives, while the Mexican market contracted. In Mexico and Central America, revenue fell 1.4% to 39,117 mn pesos due to a 1.6% decline in sales volume and unfavourable currency translation.
In South America, revenue rose 4.3% to 31,809 mn pesos, supported by a 4.8% volume increase and higher prices. Excluding currency effects, South American revenue grew 12.3%. In Mexico, currency-neutral revenue rose 1.4%, indicating weak consumer demand and the impact of the excise tax increase.
Total sales volume increased 1.2% to 998.4 mn unit cases. Growth in Brazil, Colombia, Argentina and Guatemala offset the decline in Mexico. The average price per unit case fell 0.5% to 68.64 pesos, highlighting the difficulty of passing on costs.
EBITDA rose 8.3%, although operating profit declined 2.3% due to higher expenses
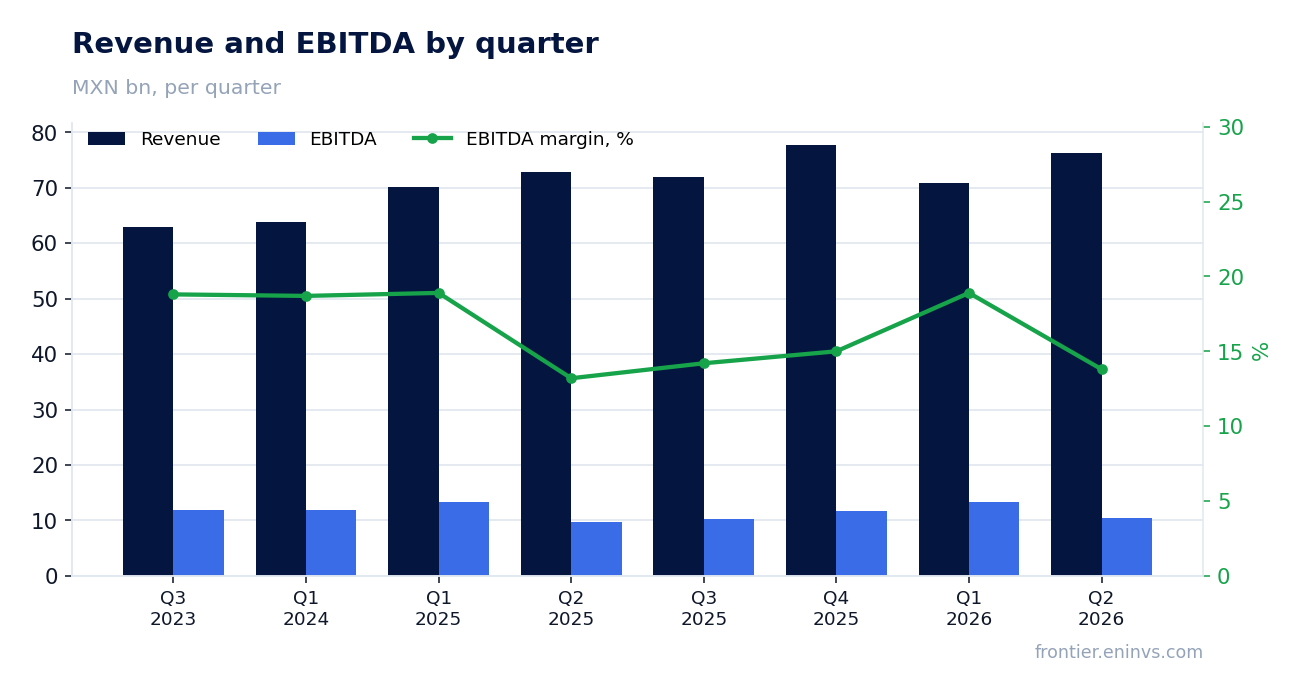
EBITDA in the first quarter of 2026 rose 8.3% year on year to 10,527 mn pesos. However, operating profit declined 2.3% to 9,032 mn pesos, and the operating margin contracted by 50 basis points to 12.7%. The discrepancy is explained by higher depreciation and other non-cash charges, which are added to EBITDA but not to operating profit.
The main pressure on operating profit came from restructuring and SAP4Hana implementation costs, as well as higher marketing expenses and depreciation. In Mexico and Central America, operating profit fell 17.4% to 4,461 mn pesos due to lower volume and unfavourable mix. In South America, operating profit rose 18.8% to 4,571 mn pesos, supported by operating leverage and cost control.
Gross margin expanded by 150 basis points to 46.9%, driven by lower sugar and PET costs and the appreciation of operating currencies against the US dollar. This partially offset higher fixed costs such as labour and depreciation.
Net profit increased 16.9% despite a lower operating margin – one-off items helped
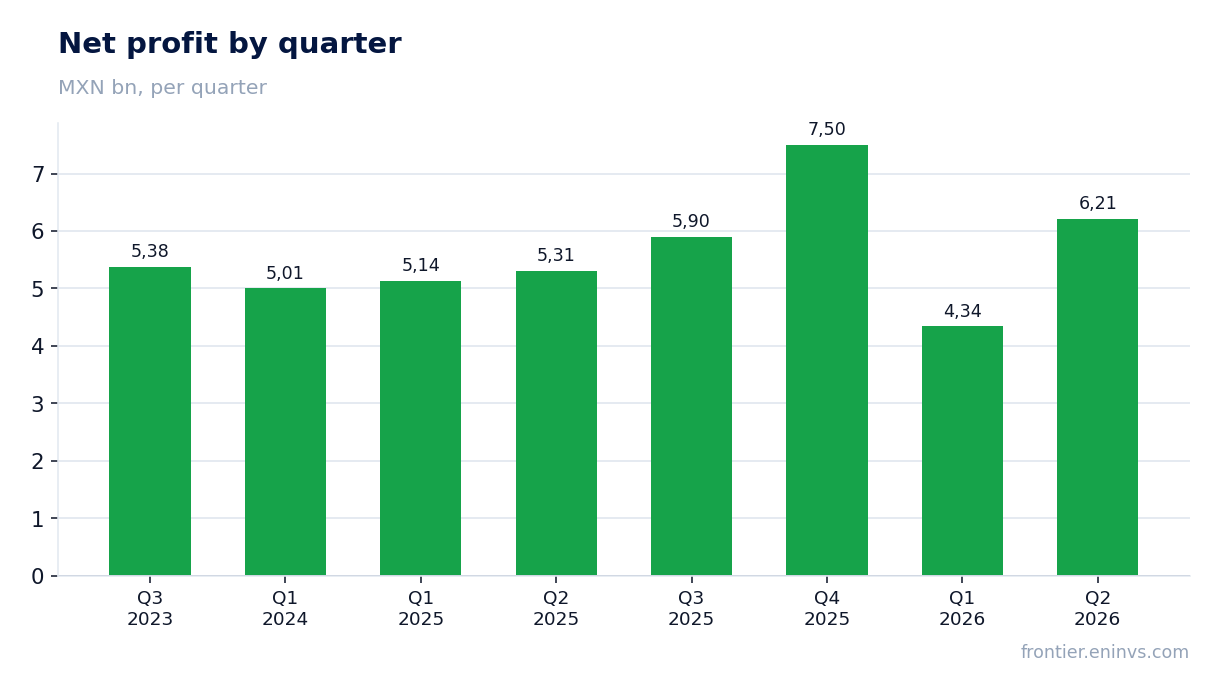
Net profit in the first quarter of 2026 rose 16.9% year on year to 6,211 mn pesos. This occurred despite a 2.3% decline in operating profit. Support came from a lower effective tax rate and one-off items, notably the recognition of a 95 mn peso income from insurance claims related to Hurricane John in Mexico.
Net margin increased to 8.1% from 7.3% a year earlier. However, profit growth was not accompanied by improved operating efficiency: the operating margin contracted. This means the quality of profit in the reporting period was lower than the net profit dynamics suggest.
The comprehensive financing result was an expense of 1,752 mn pesos versus an expense of 1,126 mn pesos a year earlier. The increase was driven by a loss on financial instruments of 167 mn pesos versus a gain of 135 mn pesos a year earlier, as well as higher interest expenses from new bond issuances.
Debt increased by 36.1 bn rubles in the quarter, with net debt/EBITDA at 1.04
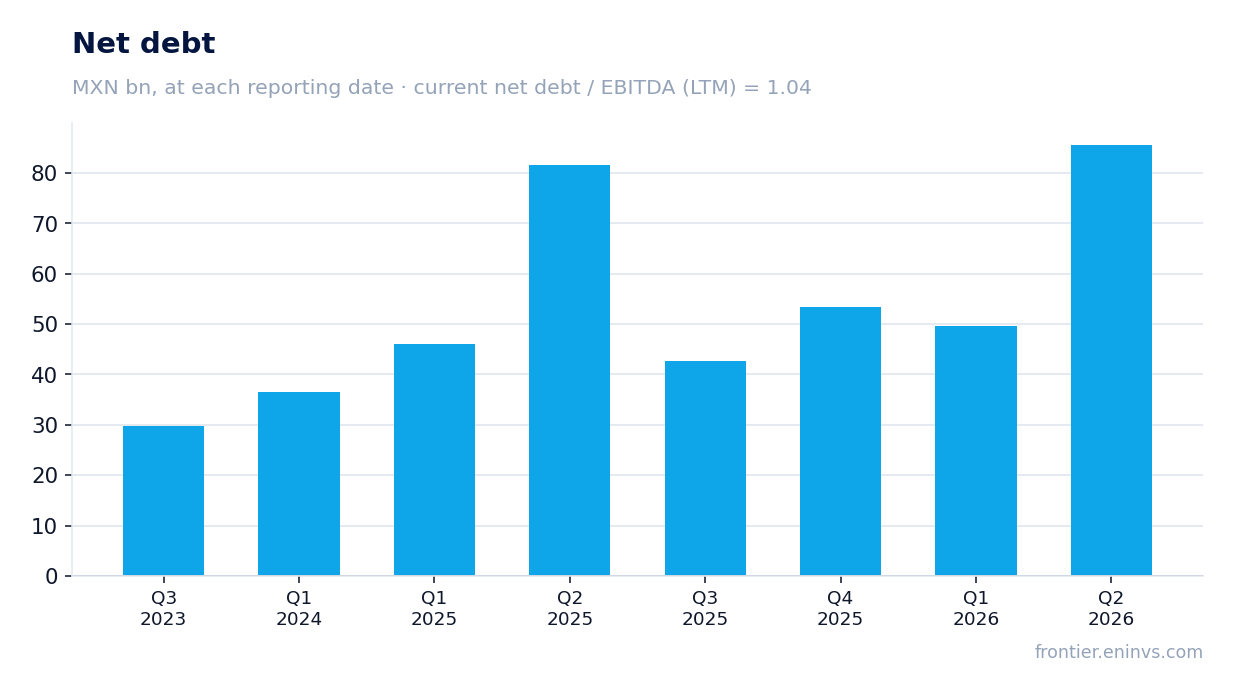
Net debt at the end of the first quarter of 2026 was 43,321 mn pesos. It increased by 36.1 bn rubles in the quarter and by 4.1 bn rubles over 12 months. The net debt to EBITDA ratio for the trailing twelve months is 1.04. This is a moderate level, but the quarterly debt increase is significant.
Total debt rose due to new bond issuances in US dollars and Mexican pesos, which also led to higher interest expenses. Interest expense increased 11.1% to 2,087 mn pesos, and net interest expense rose 22.1% to 1,572 mn pesos. This is due to higher debt and lower interest income from a reduced cash position.
Operating cash flow for the trailing twelve months was 42,400 mn pesos. This is sufficient to cover capital expenditures, but the debt increase raises questions about financial discipline. The company is actively investing, which may justify the debt increase, but so far it has not led to improved operating profit.
Dividend yield of 3.9% with a payout of 7.74 pesos per unit for 2025
For 2025, the company pays a dividend of 7.74 pesos per unit (0.9675 pesos per share), in four equal installments of 1.935 pesos per unit. The first payment was made on April 21, 2026, totalling 4,065.1 mn pesos. The current trailing twelve-month dividend yield is 3.9%.
Our estimate for the 2026 dividend is around 8.0–8.5 pesos per unit, implying a yield of 4.0–4.3% at the current price. This depends on maintaining the payout ratio and the absence of large one-off write-offs. However, rising debt and capital expenditures could limit the ability to increase payouts.
The 3.9% dividend yield exceeds the yield on many Mexican government bonds but is not exceptionally high. For a company with rising debt and volatile operating margins, such a yield looks adequate but not attractive.
EV/EBITDA at 10.7 versus its own three-year average of 7.9 – valuation above historical
The current trailing twelve-month EV/EBITDA multiple is 10.7. This is above its own three-year average of 7.9. Thus, the share trades above its historical valuation. The trailing P/E is 16.8, which may also be above historical levels, but we lack data for comparison.
The multiple expansion occurred against a backdrop of declining operating profit and rising debt. This means the market values the company higher despite deteriorating operating performance. The market may expect margin recovery and profit growth in the future, but current results do not confirm this trend.
On the portal's model, the upside to fair value is 0%. This means the current price fully reflects fair value according to our model. Given the high multiple and lack of upside, the share looks unattractive for new investments.
On the portal's model, upside to fair value is zero
Our fundamental valuation model, based on EBITDA growth and a target multiple, shows that the upside to fair value is 0%. This means the current market price fully corresponds to our fair value estimate.
The model takes into account current operating results and expected growth. At the current EBITDA level and multiple, further price growth is possible only with improved operating performance or reduced risks. However, in the first quarter of 2026, operating profit declined and debt increased, which does not create prerequisites for growth.
Thus, according to our model, the share is fairly valued, and there is no upside potential. This confirms our verdict that the share is unattractive at the current level.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 403 bn MXN |
| P/E (LTM) | 16.8 |
| EV/EBITDA (LTM) | 10.7 |
| P/B | 2.81 |
| Net debt / EBITDA (LTM) | 1.04 |
| Operating cash flow (LTM) | 42.4 bn |
| ROE | 17.2% |
| Dividend yield (12m) | 3.9% |
| EV/EBITDA, 3-year average | 7.9 |
Bottom line
Bottom line: in the first quarter of 2026, Coca-Cola FEMSA showed revenue growth of 4.7% and net profit growth of 16.9%, but operating profit declined 2.3% and debt increased by 36.1 bn rubles. Profit growth was supported by one-off items and a lower tax rate, not by improved operating efficiency. The EV/EBITDA multiple of 10.7 exceeds its own three-year average of 7.9, and the portal model's upside is zero. The 3.9% dividend yield looks adequate but does not compensate for the risks. The share is assessed as unattractive at the current level.
Open the company's financial profile KOF →
See also: market overview · valuation map · stock screeners