MX_LAB: Q2 2026 revenue fell 6% and EBITDA nearly a third, yet net profit held flat
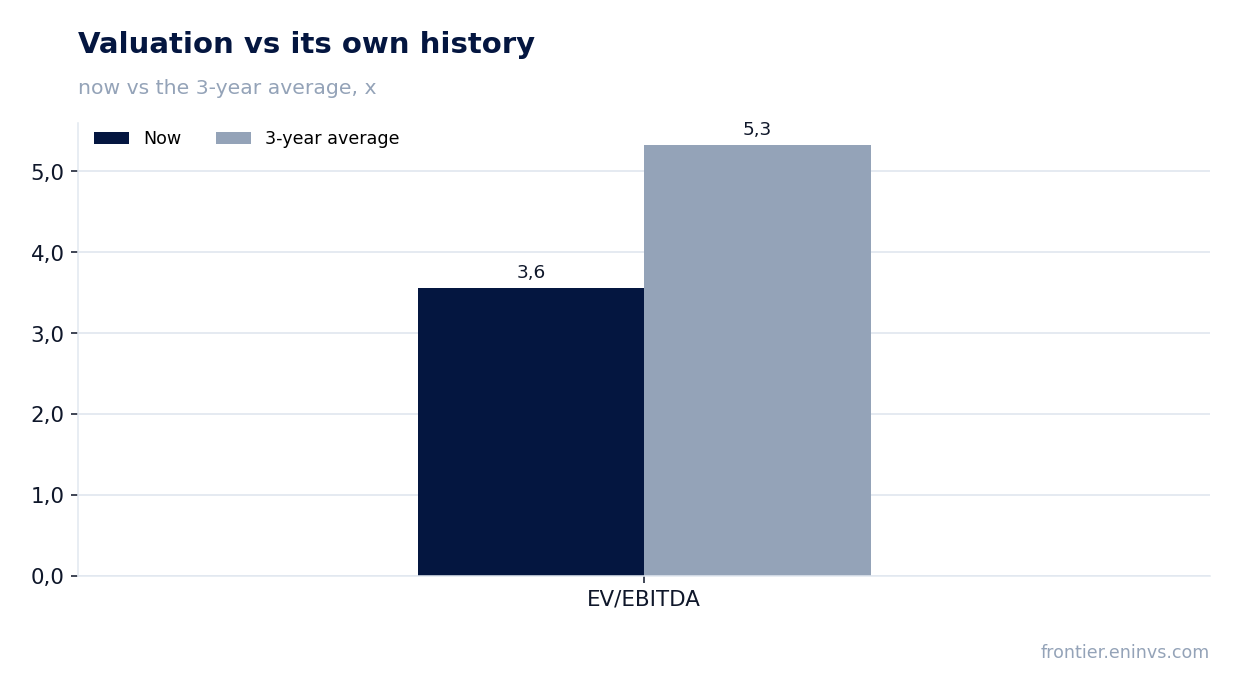
On 22 April MX_LAB released its first-quarter 2026 results. Revenue for the reported period was MXN 4,190.6 million, down 4.9% year on year, EBITDA was MXN 956.4 million at a 22.8% margin, and net profit was MXN 494.6 million. In the second quarter of 2026 revenue fell 6.0% year on year, EBITDA dropped 28.6%, while net profit rose 5.5%. With an EV/EBITDA of 3.56 against its own three-year average of 5.33 and a dividend yield of 6.5%, the share looks rather attractive, but weak Mexican consumption and margin pressure require confirmation of a turnaround.
Key takeaways
— Q1 2026 revenue fell 4.9%, with Mexico accounting for almost the entire decline
— EBITDA dropped 8.7% as operating expenses rose against falling sales
— Net profit held up thanks to lower financial expenses, not operations
— Debt load at 1.31x for the quarter remains comfortable, but net debt increased
— Trailing-twelve-month free cash flow fell 31.6% on higher working capital
— Dividend yield of 6.5% on a MXN 0.20 per share payout looks sustainable
— EV/EBITDA of 3.56 versus a three-year average of 5.33 points to undervaluation
Attractiveness
Key figures, MXN bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 4.68 | 4.40 | -6.0% |
| EBITDA | 1.12 | 0.80 | -28.6% |
| Operating profit | 1.03 | 0.87 | -15.3% |
| Net profit | 0.35 | 0.37 | +5.5% |
| Operating cash flow | 0.51 | 0.38 | -24.8% |
| EBITDA margin | 24.0% | 18.2% | -5.8 pp |
| Net margin | 7.6% | 8.5% | +0.9 pp |
Q1 2026 revenue fell 4.9%, with Mexico accounting for almost the entire decline
Revenue for the first quarter of 2026 was MXN 4,190.6 million, down 4.9% from a year earlier. Like-for-like sales declined 3.9% in constant currency. Mexico contributed MXN 1,877.8 million, losing 8.6% year on year, which the company attributes to continued retailer destocking amid weak consumption and a tough comparison base.
Latin American sales rose 2.9% in pesos and 5.3% like-for-like, supported by Central America and the Andean region. Argentina grew 72% in local currency but only 15.2% in Mexican pesos due to the Argentine peso devaluation. The US fell 22.0% in pesos and 9.7% in local currency on disruptions in Hispanic retail and a mild cold season.
By product, isotonic beverages fell 20.3%, OTC dropped 4.7%, while infant nutrition rose 35.6% and personal care added 1.5%. Weakness in key categories outweighed growth in niche segments.
EBITDA dropped 8.7% as operating expenses rose against falling sales
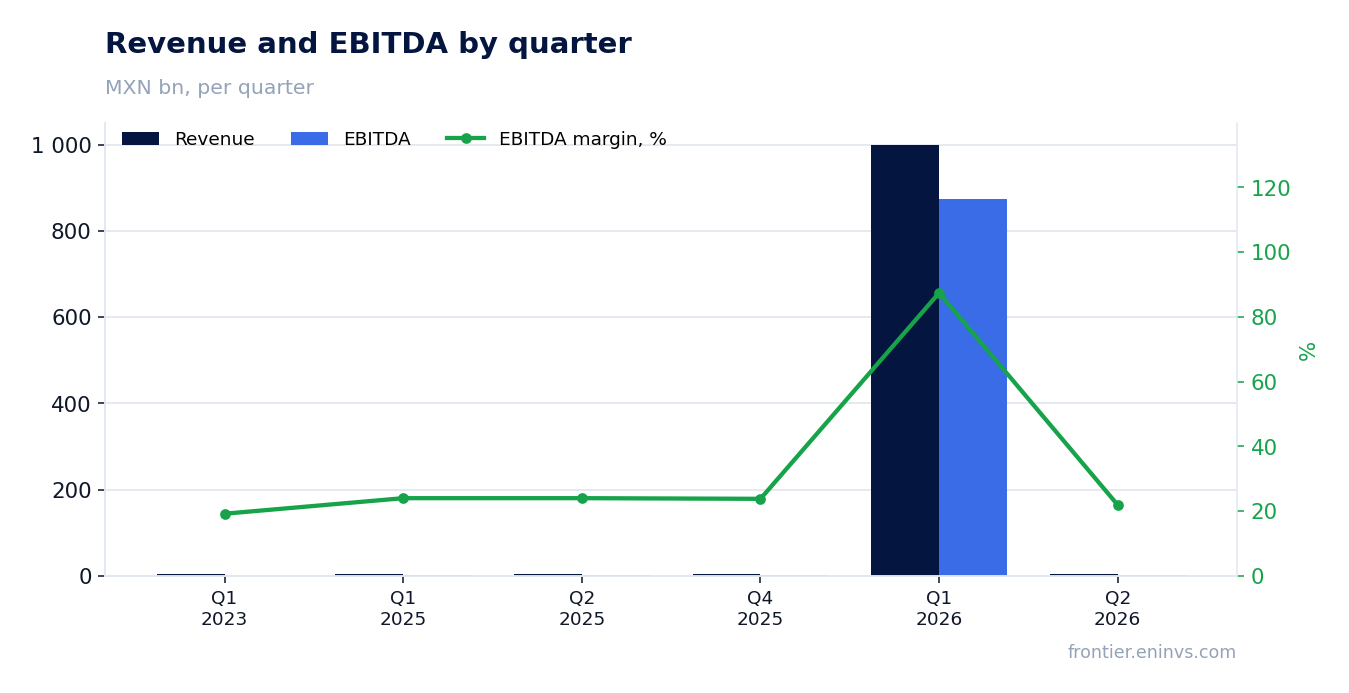
EBITDA for Q1 2026 was MXN 956.4 million, down 8.7% year on year. The EBITDA margin contracted 96 basis points to 22.8%. The company attributes this to operating deleverage and higher operating expenses to support sales growth in the second half of 2026.
Gross margin expanded 61 basis points to 63.4% thanks to productivity initiatives. However, a 1.0% increase in selling, general and administrative expenses against a 4.9% revenue decline offset this improvement. In Mexico, EBITDA margin fell 119 basis points to 23.1%; in the US, it dropped 377 basis points to 13.1%.
In Q2 2026, EBITDA was MXN 963.4 million, down 28.6% year on year, with the margin falling to 18.2% from 24.0%. This points to intensifying pressure on profitability in the second quarter.
Net profit held up thanks to lower financial expenses, not operations
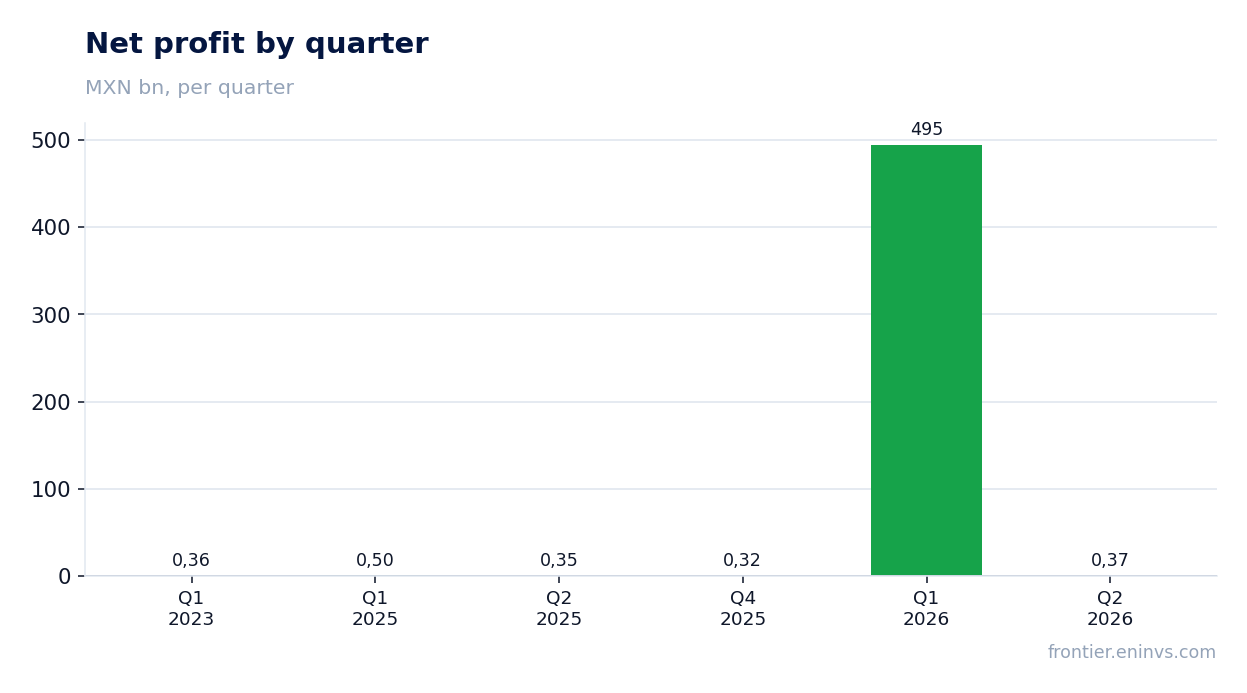
Net profit for Q1 2026 was MXN 494.6 million, down just 0.8% year on year. The net margin expanded 49 basis points to 11.8%. Support came from a 19.2% drop in interest expense to MXN 177.8 million and a 26.6% rise in interest income to MXN 35.8 million.
However, operating profit fell 9.0% to MXN 874.4 million, and the inflationary loss from the monetary position in the hyperinflationary subsidiary more than doubled to MXN 108.1 million. Without the decline in financial expenses, net profit would have shown weaker dynamics.
In Q2 2026, net profit rose 5.5% year on year to MXN 374.5 million, with the margin improving to 8.5% from 7.6%. This improvement is also driven by financial items rather than operating efficiency.
Debt load at 1.31x for the quarter remains comfortable, but net debt increased
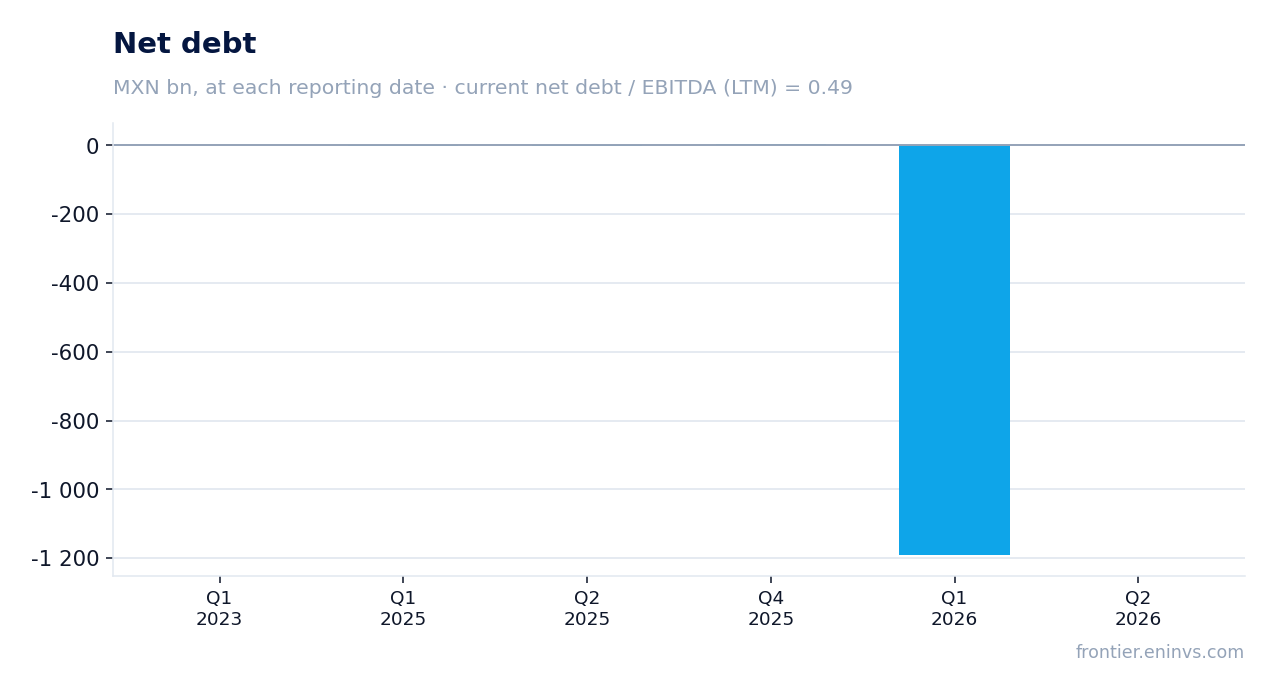
The net debt to EBITDA ratio at the end of Q1 2026 was 1.31x, which the company considers comfortable. The debt service coverage ratio reached 5.32x. However, net debt increased by RUB 1,194.0 million compared to the previous reporting date and by RUB 4.7 million over 12 months.
Total debt rose: short-term debt and current portion of long-term debt increased 12.5% to MXN 3,329.1 million, long-term debt securities jumped 54.6% to MXN 3,389.0 million. Cash and equivalents rose 30.2% to MXN 2,809.0 million, but this was not enough to reduce net debt.
The debt increase is partly tied to financing working capital and investments. At the current EBITDA level, debt servicing is not a concern, but further debt growth without profit recovery could limit financial flexibility.
Trailing-twelve-month free cash flow fell 31.6% on higher working capital
Trailing-twelve-month free cash flow fell 31.6% to MXN 1,964.5 million. The main reasons are lower operating profit and higher working capital requirements. Operating cash flow in Q1 2026 was negative at minus MXN 229.2 million versus minus MXN 151.0 million a year earlier.
Working capital increased: receivable days rose by 6 to 109 days, payable days fell by 5 to 99 days. This pushed the cash conversion cycle up by 3 days to 119 days. The company attributes the rise in receivables to a more competitive retail environment and the drop in payables to a strategic hedge against raw material cost increases.
Capital expenditure in Q1 2026 was MXN 115.3 million, of which MXN 93.0 million went to the manufacturing plant and distribution center. If weak operating cash flow persists, the company may need additional financing.
Dividend yield of 6.5% on a MXN 0.20 per share payout looks sustainable
On 31 March 2026, the company paid a quarterly dividend of MXN 0.20 per share, totaling MXN 200 million. This is the fifteenth payment, and the company intends to continue quarterly dividends. The current trailing-twelve-month dividend yield is 6.5%.
Our estimate for the annual dividend assumes the quarterly payout remains at MXN 0.20, giving MXN 0.80 per share per year. At the current price, this corresponds to a yield of about 6.5%. The payout is covered by net profit: over the last 12 months, net profit was MXN 1,633.5 million, while annual dividend payments are about MXN 800 million, less than half of profit.
However, dividend sustainability depends on the company's ability to generate free cash flow. The 31.6% decline in FCF over 12 months and negative operating cash flow in Q1 2026 could pressure payouts if the situation does not improve. If weak operating results persist, the company may revise the dividend.
EV/EBITDA of 3.56 versus a three-year average of 5.33 points to undervaluation
The current trailing-twelve-month EV/EBITDA multiple is 3.56, well below its own three-year average of 5.33. This indicates the market values the company cheaper than its average over the past three years. The trailing P/E is 7.37.
According to the portal's model, the fair value of the share implies a 41% downside from the current market capitalization. This is our own estimate, not a market consensus. Market capitalization is MXN 12,036.1 million.
Return on equity over the last 12 months was 13.1%. At current multiples and a 6.5% dividend yield, the share looks attractive, but confirmation of the valuation requires a recovery in revenue and margin. If operating performance continues to deteriorate, the current discount may prove justified.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 12.0 bn MXN |
| P/E (LTM) | 7.4 |
| EV/EBITDA (LTM) | 3.6 |
| P/B | 1.08 |
| Net debt / EBITDA (LTM) | 0.49 |
| Operating cash flow (LTM) | 2.10 bn |
| ROE | 13.1% |
| Dividend yield (12m) | 6.5% |
| EV/EBITDA, 3-year average | 5.3 |
Bottom line
The strong point of the report is the ability to hold net profit: in Q1 2026 it was almost unchanged, and in Q2 it rose 5.5% thanks to lower financial expenses. However, the operating picture is weaker: revenue is falling, EBITDA in Q2 dropped 28.6%, and the margin fell to 18.2%. Debt load at 1.31x is comfortable, but net debt is rising, and trailing-twelve-month free cash flow fell 31.6%. A dividend yield of 6.5% and an EV/EBITDA of 3.56 versus a three-year average of 5.33 make the share attractive for income-oriented investors, but sustainable growth requires stabilisation of revenue and margin.
Open the company's financial profile LAB →
See also: market overview · valuation map · stock screeners