MX_OMA: Q2 profit up nearly a tenth, but the growth rests on cost cuts, not on revenue
On 25 August MX_OMA released its Q2 2026 results. Revenue rose 2.6% year on year to MXN 4,466.5 mn, EBITDA – by 6.2%, net profit – by 9.8%. The EBITDA margin improved to 59.9% from 57.9%, and the net margin to 32.8% from 30.7%. Yet revenue is growing at only 2.6% – a modest pace – and the main contribution to profit comes not from business expansion but from lower relative costs. Leverage remains below one EBITDA, and the dividend yield exceeds 5.8%. In our view, the share looks attractive for a dividend-oriented investor, but limited revenue growth and no clear acceleration driver prevent it from being called unambiguously undervalued.
Key takeaways
— Revenue grew just 2.6% year on year, and that is the main constraint on the story
— EBITDA margin rose to 59.9% – profit is growing faster than revenue on the back of costs
— Net profit added 9.8% year on year, with no visible one-offs
— Leverage at 0.99 EBITDA LTM is comfortable, but absolute debt rose by MXN 1.8 bn in the quarter
— Free cash flow remains under pressure from capital expenditure
— Dividend yield of 5.8% is above the key rate, and that is the key argument for the share
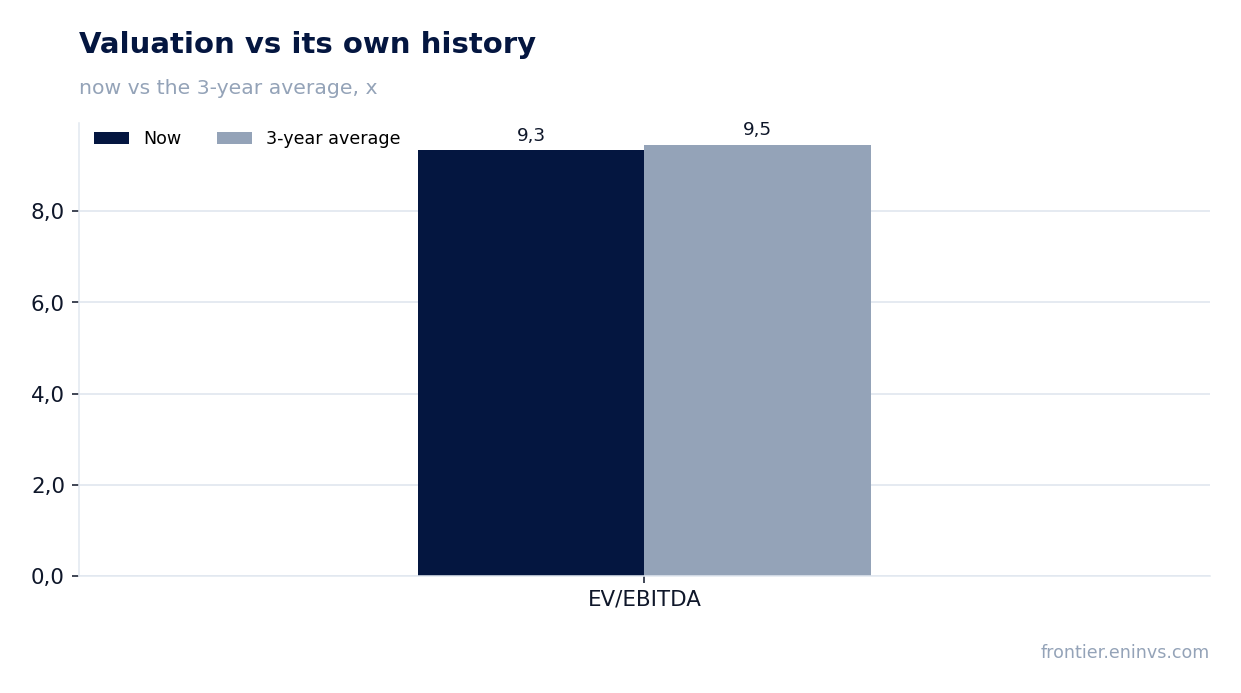
— EV/EBITDA of 9.3x is slightly below its own three-year average of 9.5x, but offers no cushion
Attractiveness
Key figures, MXN bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 4.35 | 4.47 | +2.6% |
| EBITDA | 2.52 | 2.68 | +6.2% |
| Operating profit | 2.30 | 2.39 | +4.1% |
| Net profit | 1.34 | 1.47 | +9.8% |
| Operating cash flow | 1.82 | 1.76 | -3.3% |
| EBITDA margin | 57.9% | 59.9% | +2.0 pp |
| Net margin | 30.7% | 32.8% | +2.1 pp |
Revenue grew just 2.6% year on year, and that is the main constraint on the story
Revenue in Q2 2026 came in at MXN 4,466.5 mn, up 2.6% from MXN 4,353.2 mn a year earlier. This is a modest pace that lags noticeably behind profit dynamics. The bulk of revenue, given the scale of the business, comes from the core segment, but the facts do not provide a breakdown by business line.
Over the trailing twelve months revenue reached MXN 16,300.0 mn. That is roughly 3.6 times the quarterly figure, indicating a stable base. However, annual growth of 2.6% is a pace that does not create an operating leverage effect. Acceleration would require either tariff increases or volume growth, but the facts contain no indication that either occurred.
Weak revenue growth is the main risk to the story. If it stays at 2–3%, then even with margin expansion profit will grow only moderately. The investor should watch whether the next report shows revenue acceleration, or at least signs of it.
EBITDA margin rose to 59.9% – profit is growing faster than revenue on the back of costs
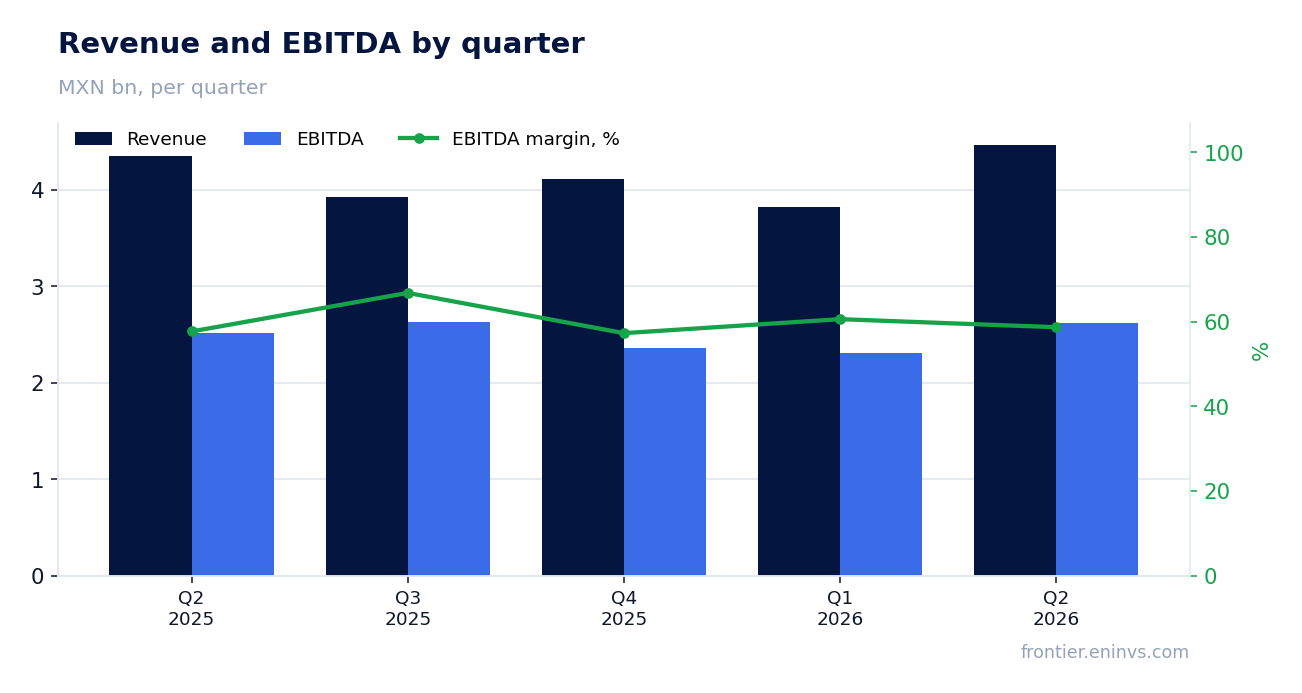
EBITDA in Q2 2026 was MXN 2,623.1 mn, up 6.2% from MXN 2,513.5 mn a year earlier. The EBITDA margin rose to 59.9% from 57.9% a year earlier. This means the company not only maintained but improved cost control: with revenue up 2.6%, EBITDA grew 6.2%.
The outperformance of EBITDA is explained by costs growing slower than revenue. The facts do not provide a breakdown by line item, but the very fact of a 2 percentage point margin improvement suggests the company either cut variable costs or benefited from fixed-cost leverage. This is an important positive signal, but it cannot offset weak revenue growth indefinitely.
A margin of 59.9% is a very high level that is hard to improve further. If revenue stays flat, further EBITDA growth is possible only through cost cuts, and that reserve is limited. Therefore, profit sustainability will depend on the company's ability to resume revenue growth.
Net profit added 9.8% year on year, with no visible one-offs
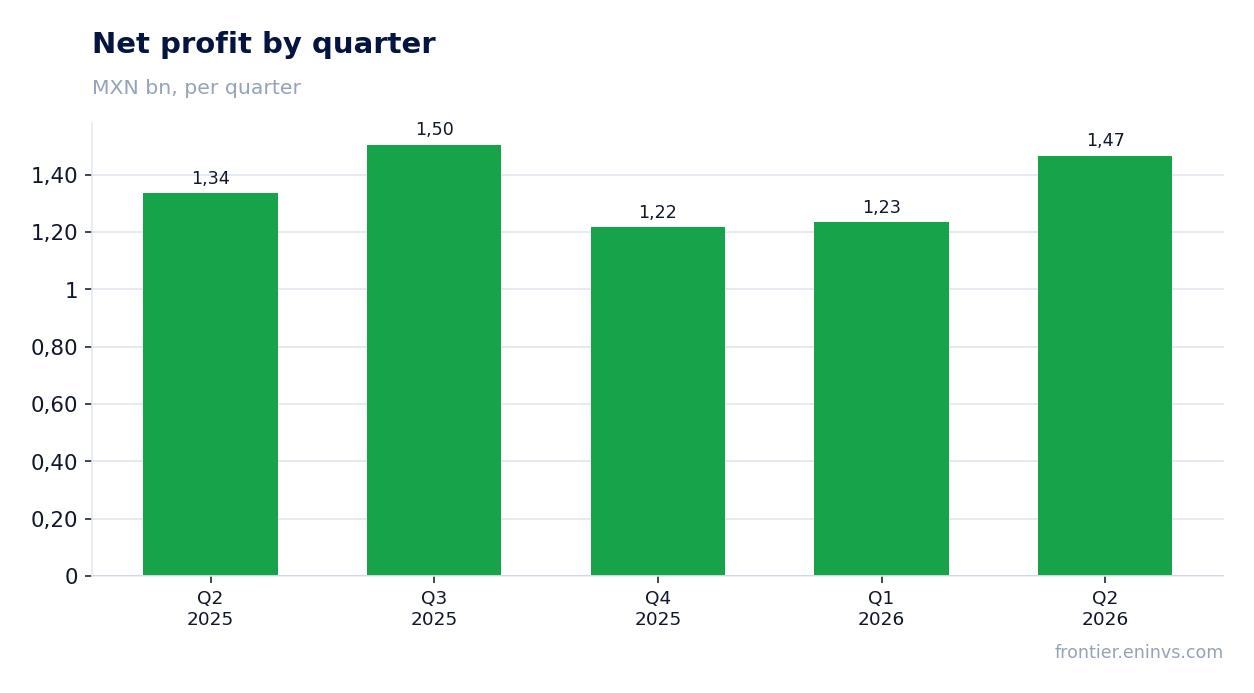
Net profit in Q2 2026 was MXN 1,466.5 mn, up 9.8% from MXN 1,335.5 mn a year earlier. Profit growth outpaces EBITDA growth, which may be explained by lower interest expenses or tax burden. The facts contain no data on one-off items, so profit appears organic.
The net margin rose to 32.8% from 30.7% a year earlier. This also confirms that margin improvement is occurring at all levels. However, it is worth remembering that profit growth of 9.8% with revenue growth of 2.6% is the result of faster cost reduction, not business expansion.
Over the trailing twelve months net profit reached MXN 5,421.2 mn. That is roughly 3.7 times the quarterly figure, indicating stability. If the company can maintain the current margin level, annual profit may remain at this level or grow slightly.
Leverage at 0.99 EBITDA LTM is comfortable, but absolute debt rose by MXN 1.8 bn in the quarter
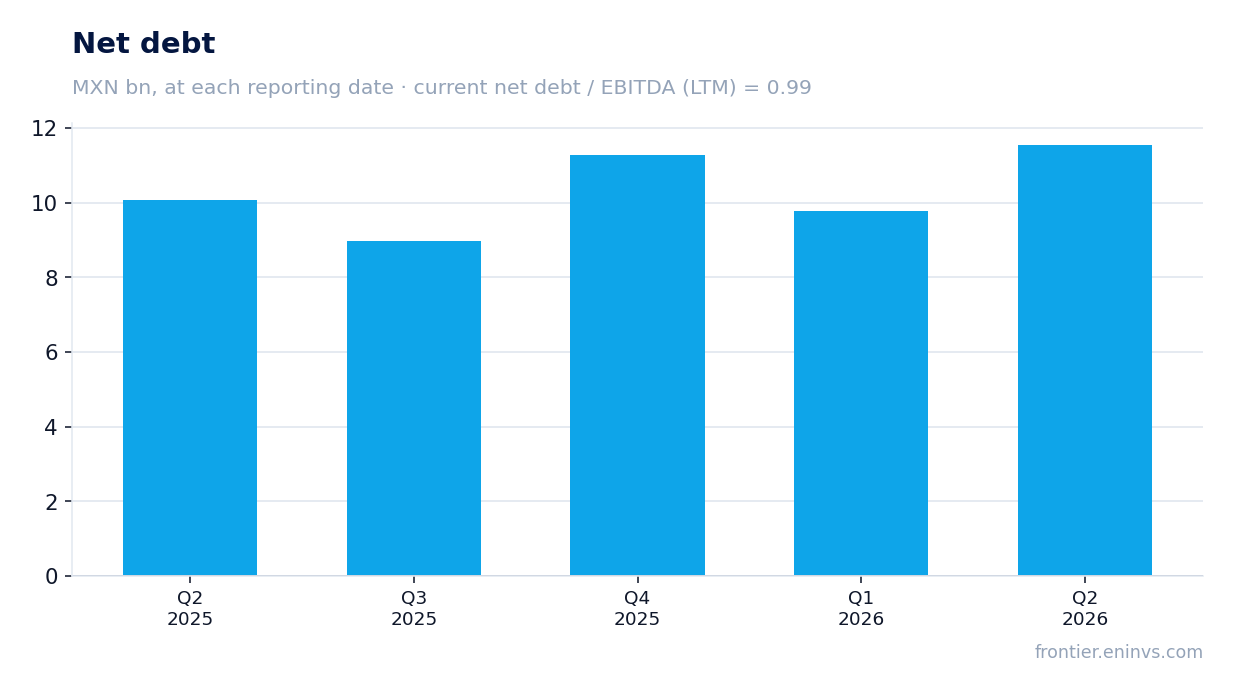
Net debt at the latest reporting date was MXN 9,638.2 mn. The ratio of net debt to EBITDA over the trailing twelve months is 0.99. This is a comfortable level that does not create risks to financial stability. However, compared with the previous reporting date, net debt rose by MXN 1.8 bn, and over twelve months – by MXN 1.5 bn.
The rise in absolute debt with stable leverage is explained by EBITDA growth, which over the trailing twelve months reached MXN 9,714.5 mn. The company can service its debt without strain. Interest expenses are likely moderate, but the facts do not disclose them.
It is important to note that leverage below one EBITDA is a strength. However, if revenue does not accelerate and debt continues to grow, the ratio could start to rise. For now, the debt level is not a problem.
Free cash flow remains under pressure from capital expenditure
Operating cash flow in Q2 2026 was MXN 1,758.9 mn, slightly below MXN 1,819.0 mn a year earlier. Capital expenditure in Q1 2026 was MXN 841.6 mn, while Q2 data are absent. Assuming capital expenditure remains at a comparable level, free cash flow could be close to MXN 900–1,000 mn.
Over the trailing twelve months operating cash flow reached MXN 7,400.0 mn. This is a solid base, but capital expenditure likely consumes a significant portion. The facts do not provide Q2 capital expenditure, so free cash flow cannot be precisely estimated.
Nevertheless, the ability to generate operating cash flow remains key for dividend payments. If capital expenditure stays at the Q1 level, the company can fund dividends from free cash flow, but the cushion may be small.
Dividend yield of 5.8% is above the key rate, and that is the key argument for the share
The dividend yield over the trailing twelve months is 5.8%. This is above the current key rate, making the share attractive for income-oriented investors. The company appears to pay dividends regularly, but the facts do not provide the exact size of the latest payment or the payout ratio.
Our estimate of the future dividend is based on current profit. Over the trailing twelve months net profit was MXN 5,421.2 mn. If the company maintains a payout ratio that provides a 5.8% yield, the annual dividend could be around MXN 4,700 mn. However, this is our estimate, and it depends on profit and dividend policy.
The risk of a dividend cut is linked to a possible decline in profit or an increase in capital expenditure. If free cash flow proves insufficient, the company may reduce payments. Nevertheless, the current yield looks sustainable given low leverage.
EV/EBITDA of 9.3x is slightly below its own three-year average of 9.5x, but offers no cushion
EV/EBITDA over the trailing twelve months is 9.3x. This is slightly below its own three-year average of 9.5x. Thus, the share trades a bit cheaper than its average over the past three years, but the difference is insignificant. P/E LTM is 14.9x.
On the portal's model, the fair value of the share based on EBITDA growth and the target multiple implies an upside of 9%. This is our own estimate, not a market consensus. It points to moderate upside, mainly supported by the dividend yield.
Given low leverage and high profitability, the current valuation looks fair. However, a significant upward revision would require accelerating revenue growth, which is not yet present. Therefore, the margin of safety is limited.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 81.0 bn MXN |
| P/E (LTM) | 14.9 |
| EV/EBITDA (LTM) | 9.3 |
| P/B | 6.87 |
| Net debt / EBITDA (LTM) | 0.99 |
| Operating cash flow (LTM) | 7.40 bn |
| ROE | 54.3% |
| Dividend yield (12m) | 5.8% |
| EV/EBITDA, 3-year average | 9.5 |
Bottom line
MX_OMA reported Q2 2026 results with revenue up 2.6%, EBITDA up 6.2%, and net profit up 9.8%. The strengths are high profitability and low leverage of 0.99 EBITDA LTM. The weakness is slow revenue growth, which does not create operating leverage. The dividend yield of 5.8% is above the key rate, making the share attractive for income-oriented investors. However, EV/EBITDA of 9.3x is only slightly below its own three-year average, and the upside on the portal's model is 9%. Overall, the share looks rather attractive, but without a significant margin of safety.
Open the company's financial profile OMA →
See also: market overview · valuation map · stock screeners