Aboitiz Equity Ventures: H1 profit up 63%, but Q2 revenue collapsed 99.7% — two scales collide in the filings
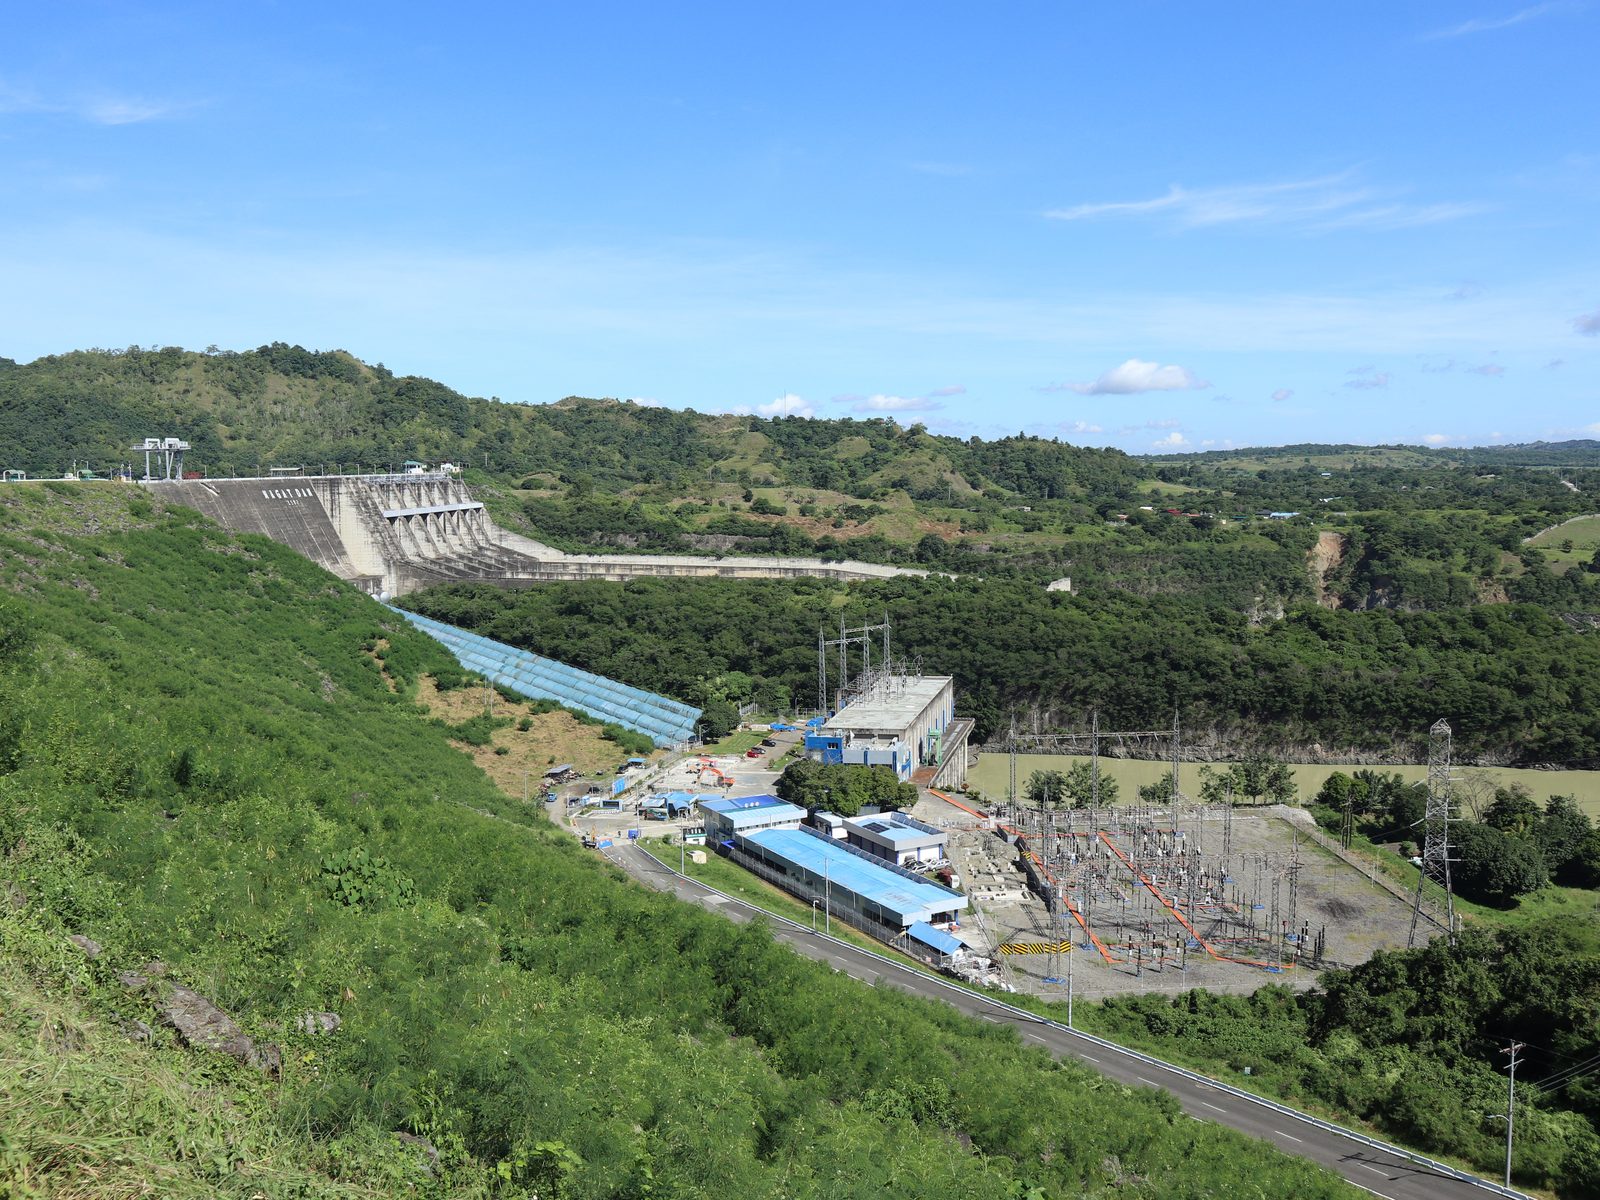
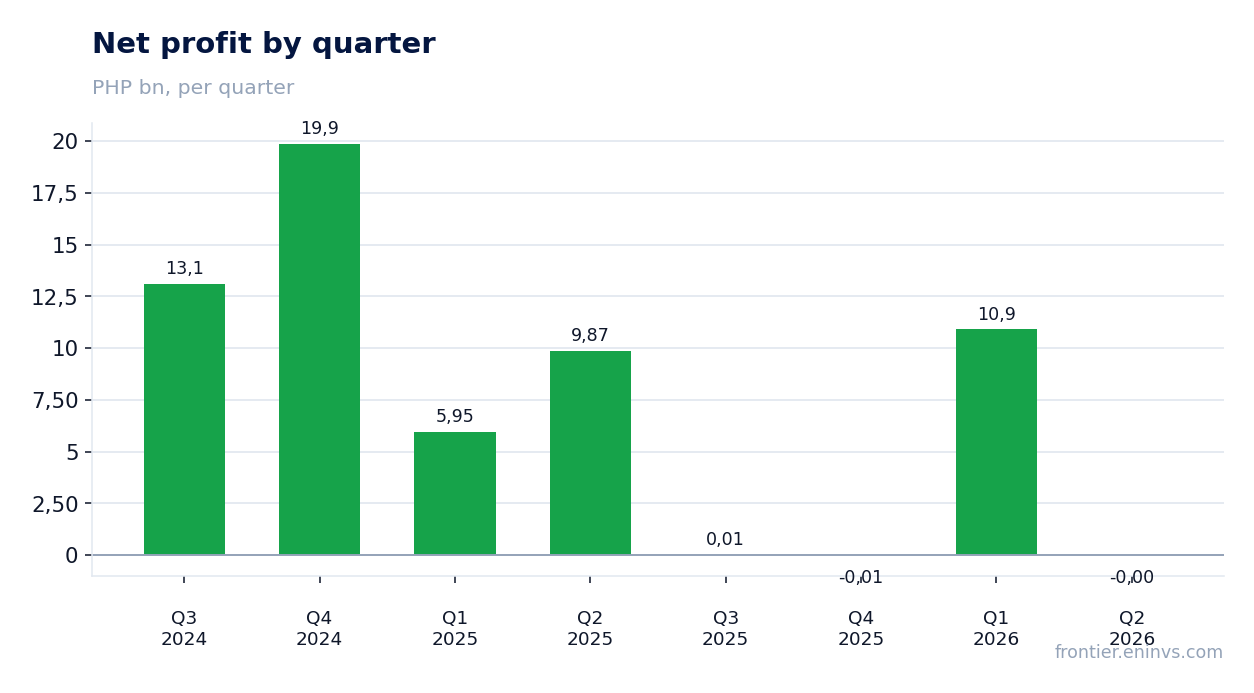
On 13 August Aboitiz Equity Ventures released its first-half 2026 report. Net income attributable to shareholders rose 63% to PHP 13.6 bn, half-year EBITDA added 31% to PHP 52.4 bn, and revenue increased 32% to PHP 186.7 bn. Yet for the second quarter alone revenue was just PHP 186.7 mn against PHP 73.8 bn a year earlier — a 99.7% drop — and net profit slipped to a loss of PHP 1.9 mn. The gap stems from a one-off consolidation in the Q2 2025 base while the current quarter reflects a different perimeter. The shares trade at P/E 10.8 and EV/EBITDA 2.85 with a 4.19% dividend yield, and the portal model puts upside to fair value at +34% — on that valuation and a strong half-year the stock looks attractive, though quarterly volatility warrants caution.
Key takeaways
— Half-year profit rose 63% on power and banking, not one-off items
— Quarterly revenue fell 99.7% on a base effect: Q2 2025 was the first to include a major consolidation
— EBITDA margin held at 28% for the half-year despite higher fuel and purchased-power costs
— Leverage at 1.88x EBITDA LTM remains moderate, with net debt down RUB 379 bn over 12 months
— The 4.19% dividend yield on PHP 8.5 bn paid in the half-year is steady but not a record for the stock
— At 2.85x EV/EBITDA and 10.8x P/E LTM there is room for re-rating if quarterly revenue normalises
— The portal model puts upside to fair value at +34%, supporting the case for attractiveness at current levels
Attractiveness
Key figures, PHP bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 73.4 | 0.19 | -99.7% |
| EBITDA | 13.5 | 0.01 | -99.9% |
| Operating profit | 9.25 | 0.01 | -99.9% |
| Net profit | 9.87 | -0.00 | -100.0% |
| Operating cash flow | 5.41 | 2.47 | -54.3% |
| Capex | 5.49 | — | — |
| EBITDA margin | 18.5% | 4.6% | -13.9 pp |
| Net margin | 13.5% | -1.0% | -14.5 pp |
Half-year profit rose 63% on power and banking, not one-off items
Net income attributable to Aboitiz Equity Ventures shareholders for the first half of 2026 reached PHP 13.6 bn, up 63% year-on-year. Two segments drove the growth: power contributed PHP 10.0 bn (up 44%) and banking PHP 3.4 bn (more than doubled). Together they added over PHP 13 bn before intra-group eliminations.
The power division benefited from higher energy market prices, new solar capacity (221 MW Olongapo, 47 MW Armenia, 93 MW San Manuel), and a full half-year contribution from CBK HEPP, which was turned over in February 2026. The banking segment, represented by UnionBank, more than doubled its contribution on higher net interest income and lower funding costs.
The food and agribusiness segment added PHP 4.0 bn (up 10%), while infrastructure and real estate remained loss-making. Infrastructure narrowed its loss to PHP 278 mn from PHP 525 mn a year earlier, while the real estate loss widened to PHP 37 mn from PHP 4 mn. These losses did not offset the overall growth but show that not all divisions are performing equally well.
Quarterly revenue fell 99.7% on a base effect: Q2 2025 was the first to include a major consolidation
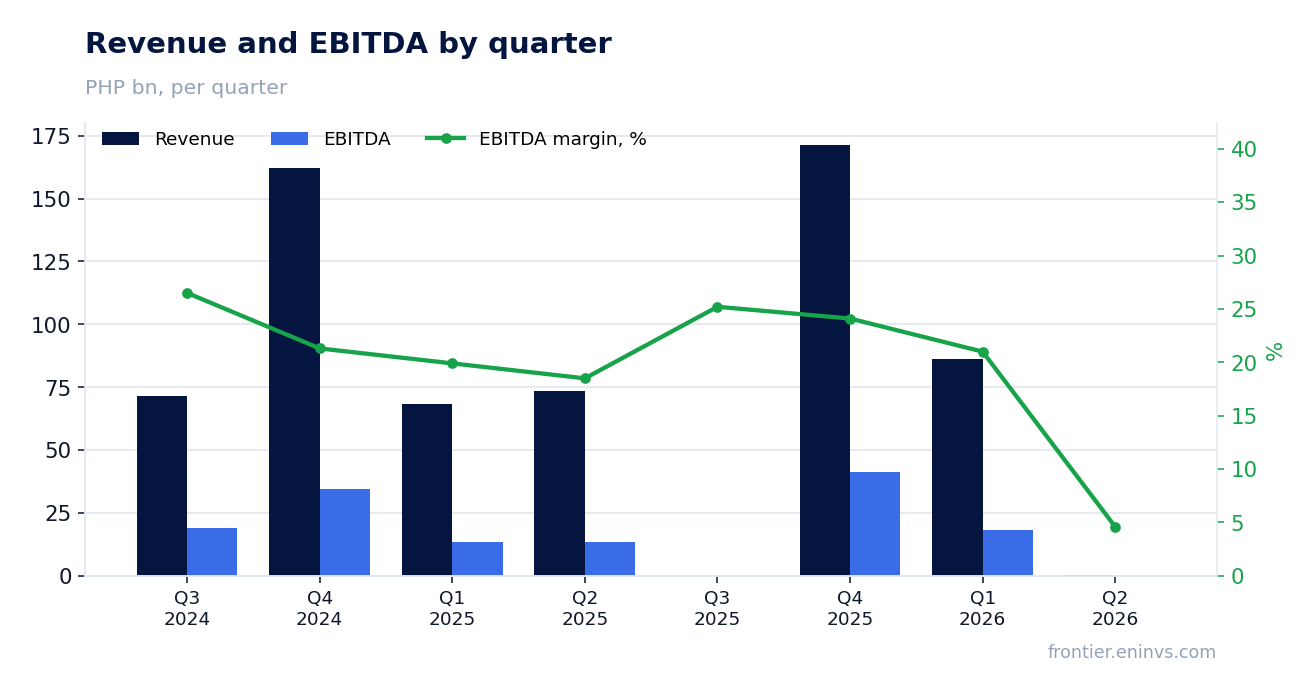
Second-quarter 2026 revenue was PHP 186.7 mn, compared with PHP 73.8 bn a year earlier. The 99.7% drop is not an operational collapse but a reporting-structure effect: in Q2 2025 the consolidated accounts first included a major acquisition — CGHI — which inflated the comparison base. The current quarter reflects a different perimeter, and a direct comparison with last year's level is misleading.
For the half-year, revenue rose 32% to PHP 186.7 bn, confirming that the cumulative result was not damaged. Power sales contributed PHP 119.8 bn (up 31%) and goods sales PHP 59.6 bn (up 34%). Real estate revenue fell 12% to PHP 1.7 bn due to the timing of revenue recognition at Economic Estates.
The quarterly dynamics look alarming only at first glance. Excluding the base effect, the half-year operating performance remains strong. The question is whether this scale will persist in coming quarters as the comparison base normalises.
EBITDA margin held at 28% for the half-year despite higher fuel and purchased-power costs
First-half 2026 EBITDA reached PHP 52.4 bn, up 31% year-on-year. The half-year EBITDA margin was around 28%, above last year's level. This was achieved despite higher costs: the cost of generated and purchased power rose 37% to PHP 76.1 bn, and cost of goods sold increased 39% to PHP 50.4 bn.
The cost increase was offset by higher tariffs and an improved sales mix in power. Half-year operating profit rose 46% to PHP 27.1 bn, outpacing revenue growth. This indicates the company managed to pass on part of the costs to consumers and improve operational efficiency.
However, second-quarter 2026 EBITDA was only PHP 8.6 mn on revenue of PHP 186.7 mn, giving a margin of 4.6% versus 18.5% a year earlier. This is a consequence of the same base effect and perimeter change. The half-year margin remains representative for assessing business resilience.
Leverage at 1.88x EBITDA LTM remains moderate, with net debt down RUB 379 bn over 12 months
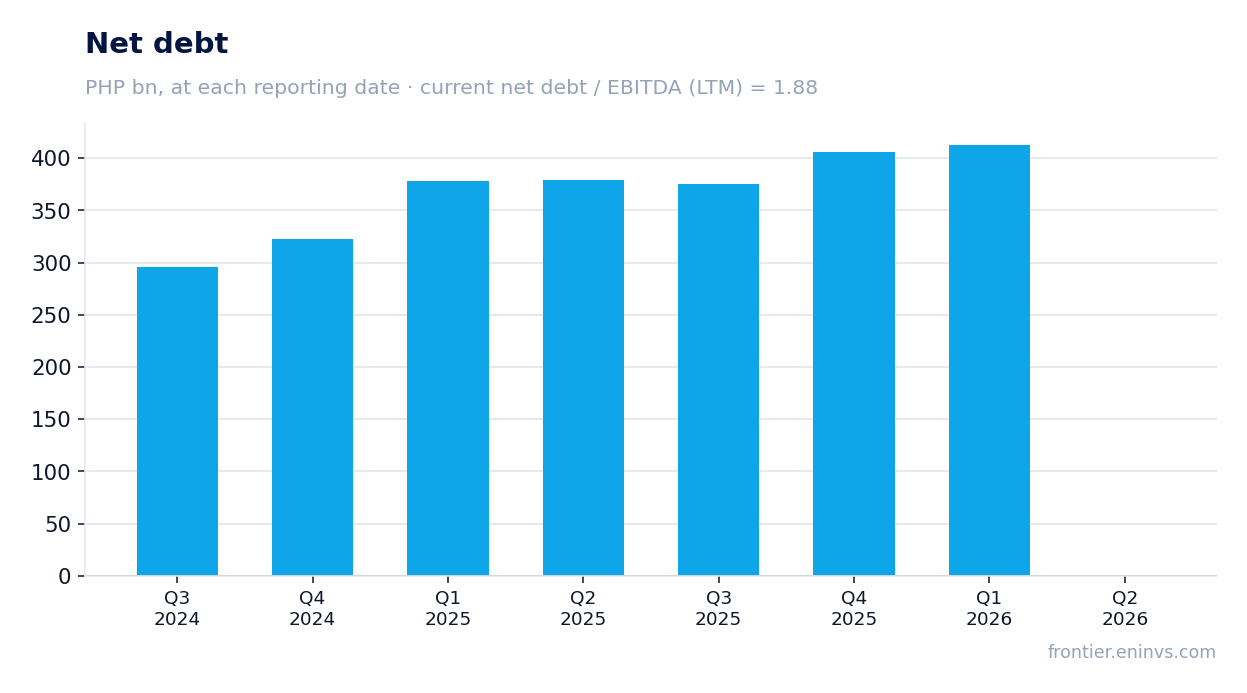
Net debt at the latest reporting date was PHP 405.5 bn, with a net debt to LTM EBITDA ratio of 1.88. This is a moderate level for a capital-intensive business. Over 12 months net debt fell by RUB 379.0 bn, driven by repayment of bridge loans taken for the CGHI acquisition and proceeds from investment returns.
Total debt as of 30 June 2026 was PHP 484.8 bn. Bank loans declined 11% to PHP 89.5 bn, reflecting repayment of short-term obligations. Long-term debt remained broadly flat at PHP 351.9 bn. Interest expense for the half-year rose 17% to PHP 13.2 bn due to AboitizPower bonds issued in Q3 2025 and a loan for the CBK HEPP acquisition.
The net debt to equity ratio fell to 0.9 from 1.0 at end-2025, according to the report. The decline came from both lower net debt and higher equity. The leverage level does not pose immediate risks, but interest expense is growing faster than revenue, which warrants attention.
The 4.19% dividend yield on PHP 8.5 bn paid in the half-year is steady but not a record for the stock
In the first half of 2026 AEV paid dividends of PHP 8.5 bn. The trailing 12-month dividend yield is 4.19%. This is a moderate level reflecting a stable dividend policy, but not a record for the stock.
Our estimate for the current year's dividend assumes a payout ratio of around 30% of net income. With half-year profit of PHP 13.6 bn and an expected annual result of about PHP 27–28 bn, the dividend could be around PHP 8–9 bn, implying a yield of about 4.2–4.3% on the current price. This assumption rests on earnings stability and the absence of large one-off write-offs.
The key risk to the dividend is further weakening of quarterly revenue if it proves to be a sustained trend rather than a base effect. The payout could also be affected by higher capital expenditure, which was significant in the first half, or by the need to allocate more funds to debt repayment. However, the current yield looks comfortable relative to the key rate and the payout history.
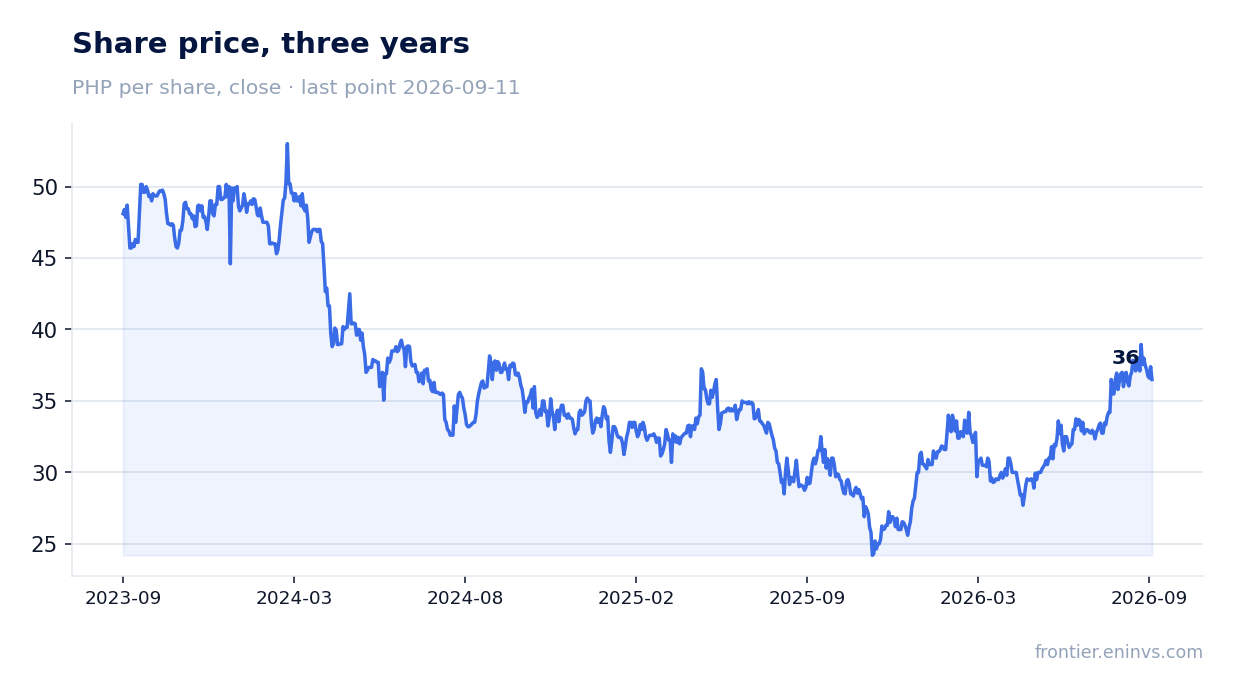
At 2.85x EV/EBITDA and 10.8x P/E LTM there is room for re-rating if quarterly revenue normalises
As of the reporting date, AEV's market capitalisation is PHP 208.2 bn. The EV/EBITDA LTM multiple is 2.85 and P/E LTM is 10.8. These are low levels, suggesting the market either doubts the sustainability of current earnings or prices in risks related to quarterly volatility.
For comparison with its own history: we do not have data on the three-year average multiple, so we cannot say whether the current level is above or below the company's typical range. However, the absolute values look modest for a diversified business with growing profit. Return on equity (ROE) is 10.9%, which also supports the valuation.
The portal model estimates upside to fair value at +34%. This is our own estimate based on EBITDA growth and a target multiple, not a market consensus. If the company can sustain the half-year dynamics and quarterly revenue normalises, a re-rating looks justified.
The portal model puts upside to fair value at +34%, supporting the case for attractiveness at current levels
Our fundamental valuation model, based on EBITDA growth and a target multiple, implies +34% upside to fair value from the current price. This is not a market consensus or a target price, but the output of our own model. It incorporates current profitability, debt structure, and dividend payments.
The stock is held in our live model strategies on the portal — PH FVC (quality). This is a fact, not an argument for the verdict: inclusion reflects passing the screen but does not replace analysis. Nevertheless, the combination of low multiples, sustained half-year growth, and a dividend yield above 4% creates preconditions for a positive re-rating.
The main question is whether operating dynamics will persist after the comparison base normalises. If quarterly revenue returns to levels comparable with last year, the current valuation looks undervalued. If the second-quarter weakness proves sustained, forecasts will need revision.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 208 bn PHP |
| P/E (LTM) | 10.8 |
| EV/EBITDA (LTM) | 2.8 |
| P/B | 0.52 |
| Net debt / EBITDA (LTM) | 1.88 |
| Operating cash flow (LTM) | 58.5 bn |
| ROE | 10.9% |
| Dividend yield (12m) | 4.2% |
Bottom line
Aboitiz Equity Ventures delivered strong first-half 2026 results with 63% profit growth and 31% EBITDA growth, driven by power and banking. However, quarterly reporting shows a 99.7% revenue drop, explained by a base effect rather than an operational collapse. Leverage remains moderate, the dividend yield is 4.19%, and multiples of 2.85x EV/EBITDA and 10.8x P/E look low. The portal model implies +34% upside to fair value, which together with sustained half-year growth makes the stock attractive for investors willing to accept quarterly volatility. Verdict: attractive.
Open the company's financial profile AEV →
See also: market overview · valuation map · stock screeners