Ayala Land: revenue falls for a fifth straight quarter, yet profit keeps the margin above 20%
On 31 March Ayala Land released its first-quarter 2026 report. Revenue for January–March fell 13.9% year on year to PHP 37.5 bn, net profit declined 20.2% to PHP 6.7 bn, and the net margin came in at 17.9% versus 19.3% a year earlier. Over the trailing twelve months the company earned PHP 40.9 bn of net profit on revenue of PHP 182.1 bn, and at a P/E of 5.4 the stock looks cheap, but weakening residential demand and rising debt prevent calling it attractive – the verdict is neutral.
Key takeaways
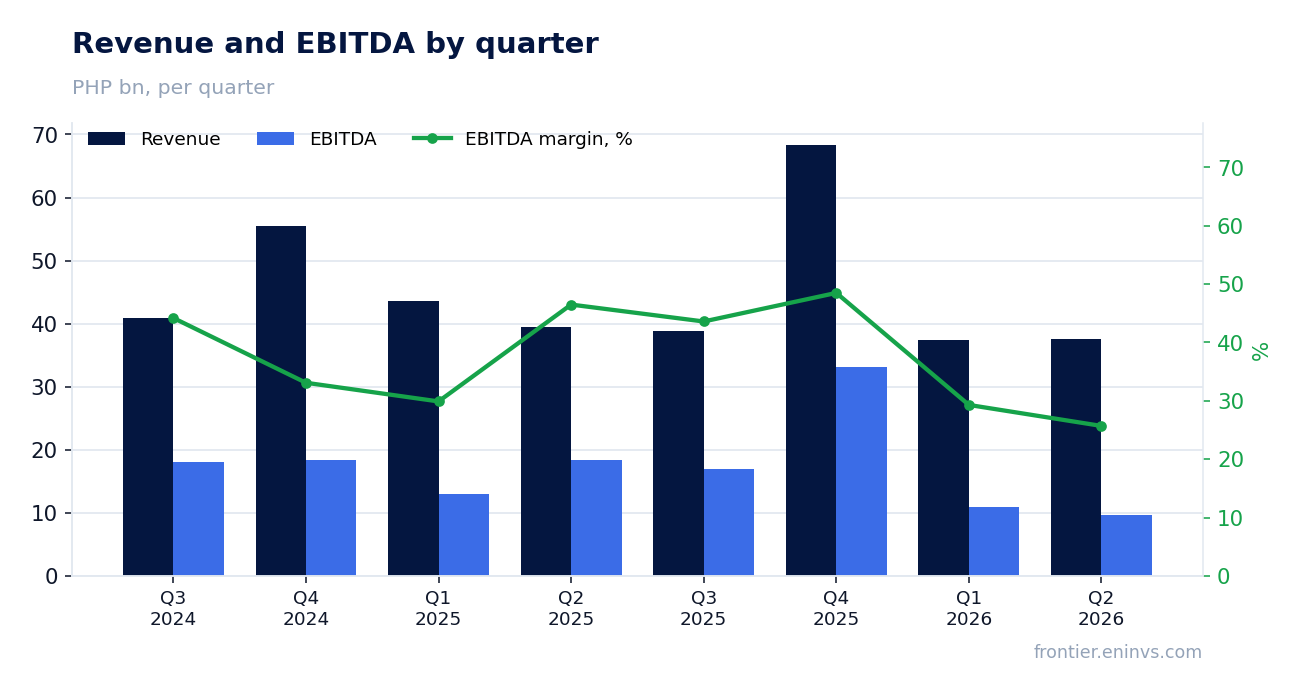
— Revenue has fallen for a fifth straight quarter, and the decline accelerated to 13.9%
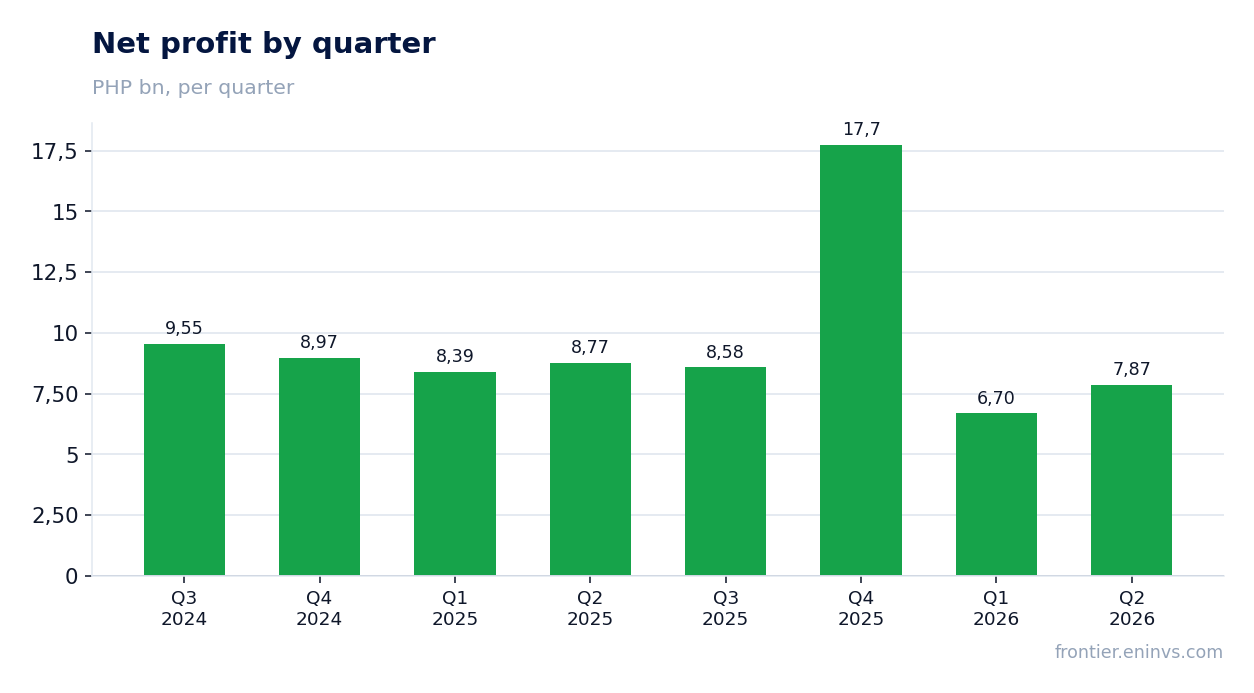
— Net profit fell 20.2%, but the margin stayed above 17%
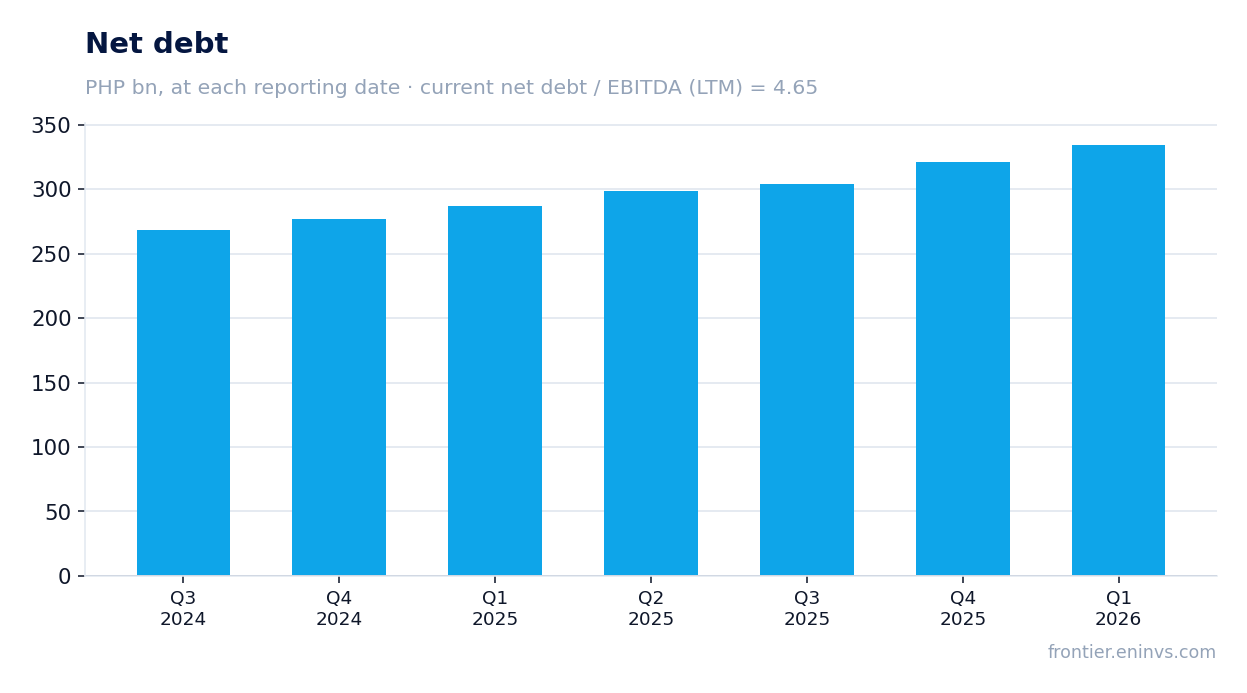
— Debt rose to PHP 320 bn, with a net debt/EBITDA ratio of 4.65
— Operating cash flow for the quarter was just PHP 1.8 bn against capex of PHP 9.6 bn
— Dividends for 2025 total PHP 1.40 per share, a yield of 4.3%
— P/E of 5.4 and EV/EBITDA of 7.9 look cheap, but the portal model shows only -3% upside
Attractiveness
Key figures, PHP bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 39.5 | 37.5 | -5.1% |
| EBITDA | 18.4 | — | — |
| Operating profit | 15.8 | 9.62 | -39.0% |
| Net profit | 8.77 | 7.87 | -10.3% |
| Operating cash flow | 4.46 | — | — |
| Capex | 0.56 | — | — |
| EBITDA margin | 46.5% | — | — |
| Net margin | 22.2% | 21.0% | -1.2 pp |
Revenue has fallen for a fifth straight quarter, and the decline accelerated to 13.9%
In the first quarter of 2026, Ayala Land's revenue amounted to PHP 37.5 bn, down 13.9% year on year. This is the fifth consecutive quarterly decline: in Q4 2025 the drop was 5.3%, in Q3 – 5.3%, in Q2 – 8.7%. The acceleration in Q4 2025 (23.2% growth) proved to be a one-off spike, and the negative trend resumed in early 2026.
The real estate segment was the main drag: its revenue fell to PHP 36.2 bn from PHP 42.6 bn a year earlier. The company does not provide segment details in this report, but the overall dynamics point to weak residential demand and a slowdown in mid-range project sales. Other income (interest and miscellaneous) rose to PHP 716 mn from PHP 390 mn, but its share is too small to offset the decline in the core business.
Net profit fell 20.2%, but the margin stayed above 17%
Net profit for January–March 2026 was PHP 6.7 bn, down 20.2% from the same period last year. The net margin declined to 17.9% from 19.3%, but remained at a level acceptable for a developer. The main reason for the profit decline is lower revenue, while administrative expenses rose to PHP 2.7 bn from PHP 2.4 bn and interest expenses increased to PHP 4.7 bn from PHP 4.1 bn.
It is worth noting that in the Q1 2026 report the company showed one-off items: other charges fell to PHP 641 mn from PHP 1.18 bn a year earlier, which partially supported profit. Without this reduction, the decline in net profit would have been deeper. Tax payments also decreased to PHP 1.5 bn from PHP 2.0 bn, reflecting a smaller taxable base.
Debt rose to PHP 320 bn, with a net debt/EBITDA ratio of 4.65
Ayala Land's net debt at the end of Q1 2026 reached PHP 320.2 bn, up PHP 13.4 bn over the quarter and PHP 47.4 bn over twelve months. The net debt/EBITDA ratio for the trailing twelve months stands at 4.65 – a level that constrains the company's financial flexibility. For comparison, trailing twelve-month EBITDA is PHP 68.9 bn, and debt covers almost five years of EBITDA.
Debt is rising against falling revenue and profit, putting pressure on credit quality. Interest expenses for the quarter rose to PHP 4.7 bn from PHP 4.1 bn a year earlier, and if the current trend persists, debt servicing will consume an increasing share of operating profit. The company does not disclose a repayment schedule, but the current portion of debt is PHP 18.4 bn and short-term borrowings are PHP 55.6 bn.
Operating cash flow for the quarter was just PHP 1.8 bn against capex of PHP 9.6 bn
Ayala Land's operating cash flow for Q1 2026 was PHP 1.8 bn, significantly lower than PHP 8.2 bn a year earlier. The main reason is growth in accounts receivable and inventories, linked to slowing sales. At the same time, capital expenditures for the quarter amounted to PHP 9.6 bn (including investments in real estate and fixed assets), resulting in negative free cash flow.
The company is financing the deficit through borrowings: PHP 63.7 bn of new loans were raised during the quarter, and PHP 45.0 bn was repaid. This explains the debt increase. Negative free cash flow is a warning sign, especially against falling revenue. If operating cash flow does not recover, the company will have to either cut capex or increase debt further.
Dividends for 2025 total PHP 1.40 per share, a yield of 4.3%
Ayala Land paid dividends for 2025 of PHP 1.40 per share (PHP 0.35 in Q1 2026 and PHP 1.05 in prior periods). At the current share price, the trailing twelve-month dividend yield is 4.3%. This is above the key rate but not a record level for the company.
For 2026, we expect dividends of PHP 1.40–1.50 per share, corresponding to a current yield of 4.3–4.6%. However, the payout could be cut if profit continues to fall and debt burden rises. The company has already increased debt to finance capex, and if negative free cash flow persists, dividends may be reduced. The main risk is a further decline in net profit, which directly affects the dividend base.
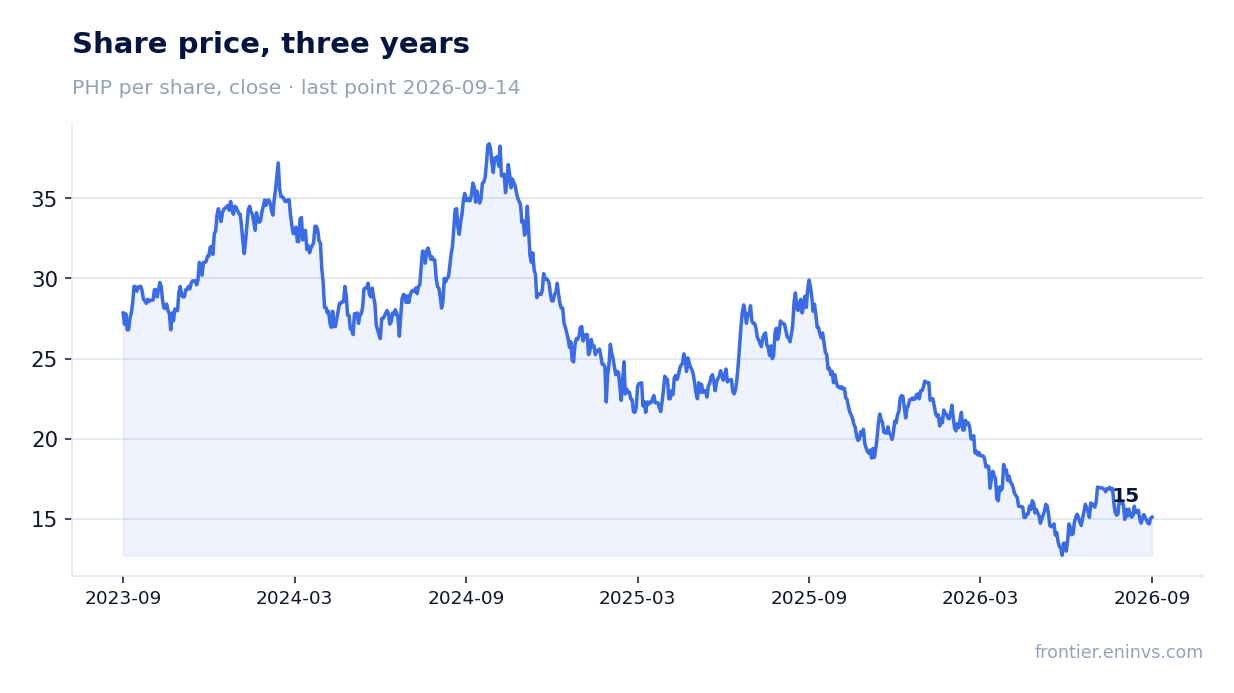
P/E of 5.4 and EV/EBITDA of 7.9 look cheap, but the portal model shows only -3% upside
By multiples, Ayala Land looks cheap: trailing twelve-month P/E is 5.4, EV/EBITDA is 7.9. However, our fundamental valuation model, based on EBITDA growth and a target multiple, shows that the fair value of the share is only 3% below the current market price. This means the market is already pricing in the company's current problems.
Comparison with the company's own history is difficult because the FACTS do not provide three-year average multiples. Nevertheless, the current P/E of 5.4 is lower than that of many Asian developers, but this is offset by high debt and falling revenue. The market appears to value the company based on current cash flows rather than future growth. A reversal in revenue dynamics and a reduction in debt burden are needed for a re-rating.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 221 bn PHP |
| P/E (LTM) | 5.4 |
| EV/EBITDA (LTM) | 7.9 |
| P/B | 0.57 |
| Net debt / EBITDA (LTM) | 4.65 |
| Operating cash flow (LTM) | 29.0 bn |
| ROE | 8.0% |
| Dividend yield (12m) | 4.3% |
Bottom line
Ayala Land reported Q1 2026 with a 13.9% decline in revenue and a 20.2% drop in profit. The company remains profitable, but debt is rising and operating cash flow fell to PHP 1.8 bn. A dividend yield of 4.3% and low multiples (P/E 5.4) make the stock interesting for income-oriented investors, but the portal model sees no upside. The verdict is neutral: the current price fairly reflects both the weakness of the business and its cheapness.
Open the company's financial profile ALI →
See also: market overview · valuation map · stock screeners