PH_BDO: net interest income jumped 15.6% but Q2 2026 profit stayed flat year on year
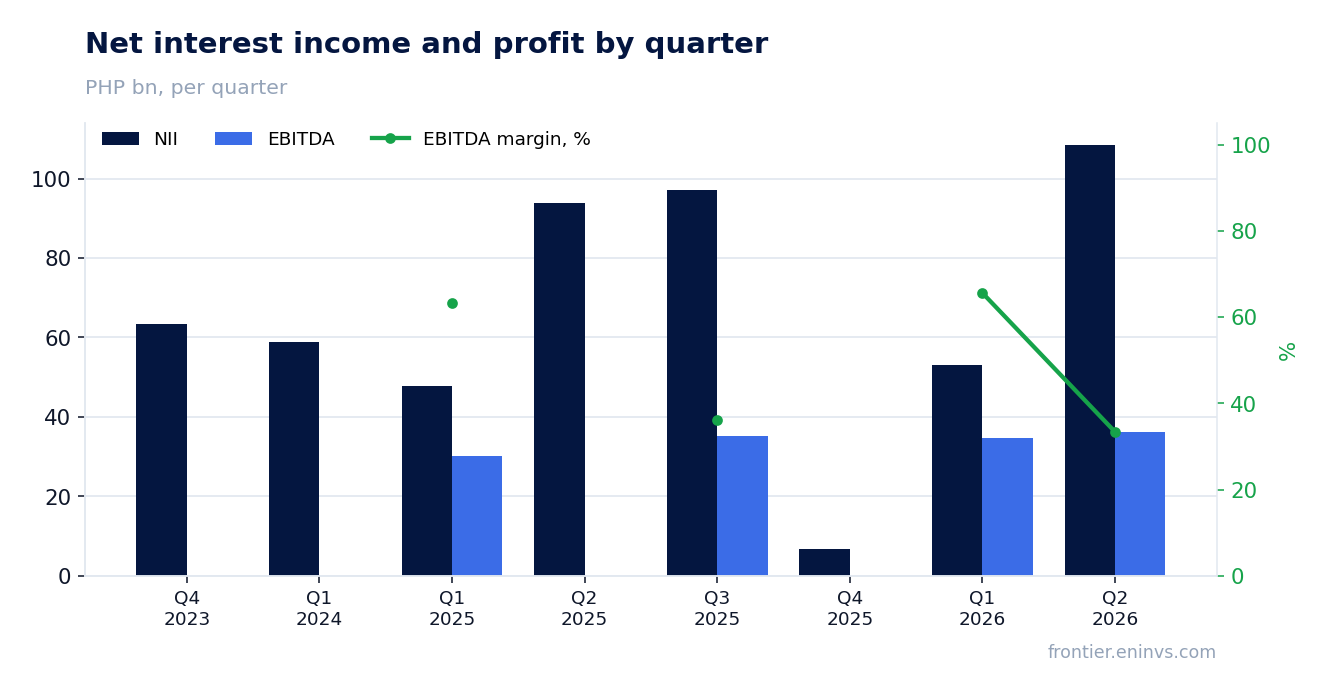
On 25 August PH_BDO released its Q2 2026 results. Net interest income rose 15.6% year on year to 108,511 mn pesos, EBITDA reached 36,252 mn, and net profit was 20,668 mn, down 1.5% from a year earlier. The EBITDA margin came in at 33.4%, while net profit was only 19.0% of net interest income. The share looks attractive: with a P/E LTM of 7.06 and ROE of 12.7%, the portal's model implies +13% upside to fair value, and a 3.82% dividend yield supports the valuation.
Key takeaways
— Net interest income rose 15.6% year on year to 108,511 mn pesos – the strongest quarterly result in the available history
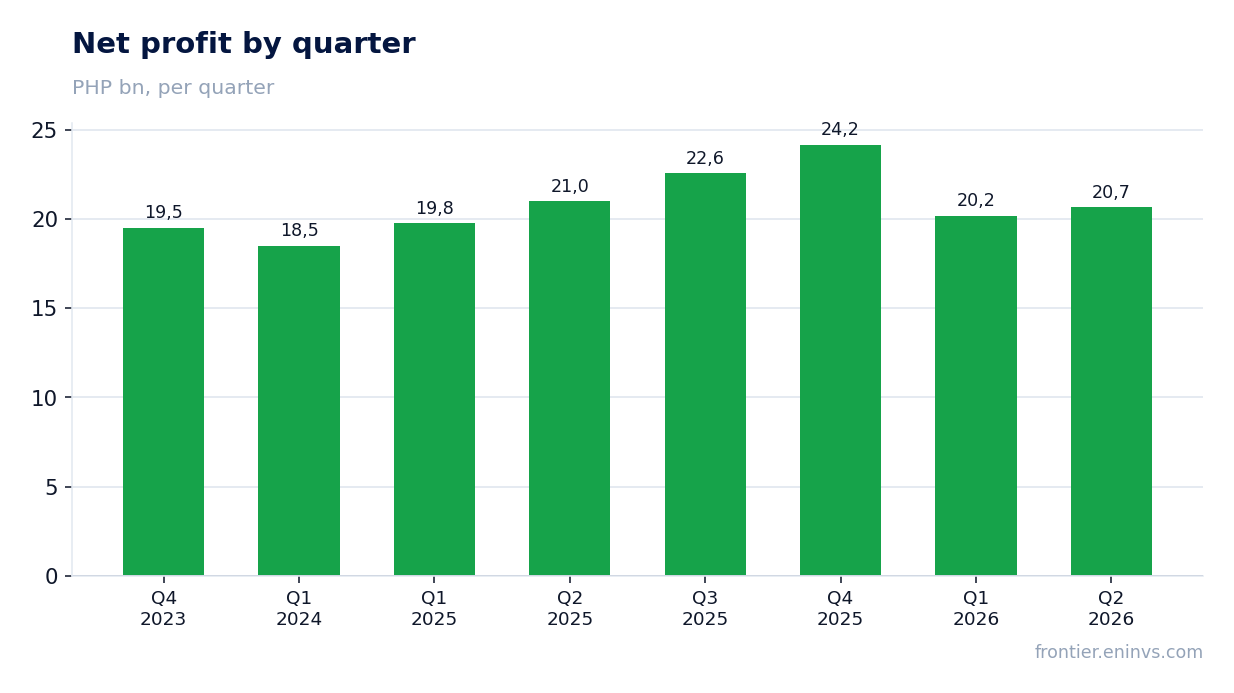
— Q2 2026 profit fell 1.5% year on year to 20,668 mn pesos despite higher interest income – costs absorbed part of the revenue
— The EBITDA margin was 33.4%, while net profit was only 19.0% of net interest income, pointing to a high cost and provisioning burden
— Leverage is not meaningful for a bank: deposits and borrowings are the business, not a leverage tool, and we do not assess net debt
— A dividend yield of 3.82%, with the payout ratio still to be clarified, provides support to the share price
— P/E LTM of 7.06 and ROE of 12.7% represent a moderate valuation, while the portal's model points to 13% upside to fair value
— Operating cash flow of 124,066 mn pesos reflects client balances and central-counterparty positions, not a result of operations
Attractiveness
Key figures, PHP bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Net interest income | — | 109 | — |
| EBITDA | — | 36.3 | — |
| Operating profit | 30.5 | 32.9 | +8.0% |
| Net profit | 21.0 | 20.7 | -1.5% |
| EBITDA margin | — | 33.4% | — |
| Net margin | — | 19.0% | — |
Net interest income rose 15.6% year on year to 108,511 mn pesos – the strongest quarterly result in the available history
In Q2 2026, PH_BDO's net interest income reached 108,511 mn pesos, up 15.6% from the same period last year. This is the highest quarterly figure in the available history: the previous peak was 97,187 mn pesos in Q3 2025. Growth accelerated from 11.0% year on year in Q1 2026.
The increase was driven by higher interest income, which could stem from either a larger volume of earning assets or higher rates. However, the breakdown by source is not disclosed in the report, so we limit ourselves to stating the fact: interest income has grown at a double-digit pace for two consecutive quarters.
For a bank, sustained growth in net interest income is a key indicator of the health of the core business. The acceleration from 11.0% in Q1 to 15.6% in Q2 2026 suggests the institution is gaining momentum, a positive signal for future profit.
Q2 2026 profit fell 1.5% year on year to 20,668 mn pesos despite higher interest income – costs absorbed part of the revenue
Net profit for Q2 2026 was 20,668 mn pesos, down 1.5% from a year earlier. This diverges from the 15.6% growth in net interest income. The reason is faster growth in expenses, likely including operating costs and provisions.
A decline in profit alongside rising revenue means the business's profitability is shrinking. If last year the company earned more per peso of net interest income, now the cost share has increased. This could be due to investments in growth, tighter provisioning, or one-off write-offs.
Nevertheless, the absolute profit level remains high: 20,668 mn pesos is the second-best result in the last five quarters, after 24,160 mn in Q4 2025. The company retains the ability to generate significant net profit even under margin pressure.
The EBITDA margin was 33.4%, while net profit was only 19.0% of net interest income, pointing to a high cost and provisioning burden
EBITDA in Q2 2026 was 36,252 mn pesos, with an EBITDA margin of 33.4%. This means about a third of net interest income remains after operating expenses, a moderate figure for the banking sector.
Net profit was only 19.0% of net interest income. The gap between EBITDA and net profit is explained by depreciation, taxes, and possibly provisions for credit losses. For a bank, this is a normal structure, but such a low conversion of income into profit indicates that a significant portion goes to cover risks and mandatory payments.
A comparison with previous quarters shows that the EBITDA margin in Q1 2026 was 34.8% (EBITDA of 34,773 mn on net interest income of 53,029 mn), so it declined slightly in Q2. This confirms that the pressure on profit is not only due to higher interest income but also to a relative increase in costs.
Leverage is not meaningful for a bank: deposits and borrowings are the business, not a leverage tool, and we do not assess net debt
For PH_BDO, as a bank, the net debt metric is meaningless: deposits and borrowings are the core of operations, not a sign of leverage. Therefore, we do not analyse net debt and do not draw conclusions about financial leverage.
Instead, one should focus on capital adequacy and asset quality, but these data are absent from the provided report. We can only note that the company continues to generate profit and pay dividends, which indirectly indicates a stable financial position.
Operating cash flow in Q2 2026 was 124,066 mn pesos, but for a bank this figure reflects client balances and central-counterparty positions, not a result of operations. We do not use it to assess performance.
A dividend yield of 3.82%, with the payout ratio still to be clarified, provides support to the share price
PH_BDO's dividend yield over the trailing 12 months is 3.82%. This is a moderate level that provides some support to the share price but is not the main factor of attractiveness.
The payout ratio and the absolute dividend for 2026 have not yet been disclosed. Our estimate, based on current profit and historical practice, assumes the company will maintain payments at a comparable level. However, this is only our estimate and depends on the final financial result and the board's decision.
With the key rate not provided in the data, a yield of 3.82% could be either above or below the risk-free rate. Without this comparison, we cannot make a definitive conclusion about the dividend's attractiveness, but we note that it remains stable.
P/E LTM of 7.06 and ROE of 12.7% represent a moderate valuation, while the portal's model points to 13% upside to fair value
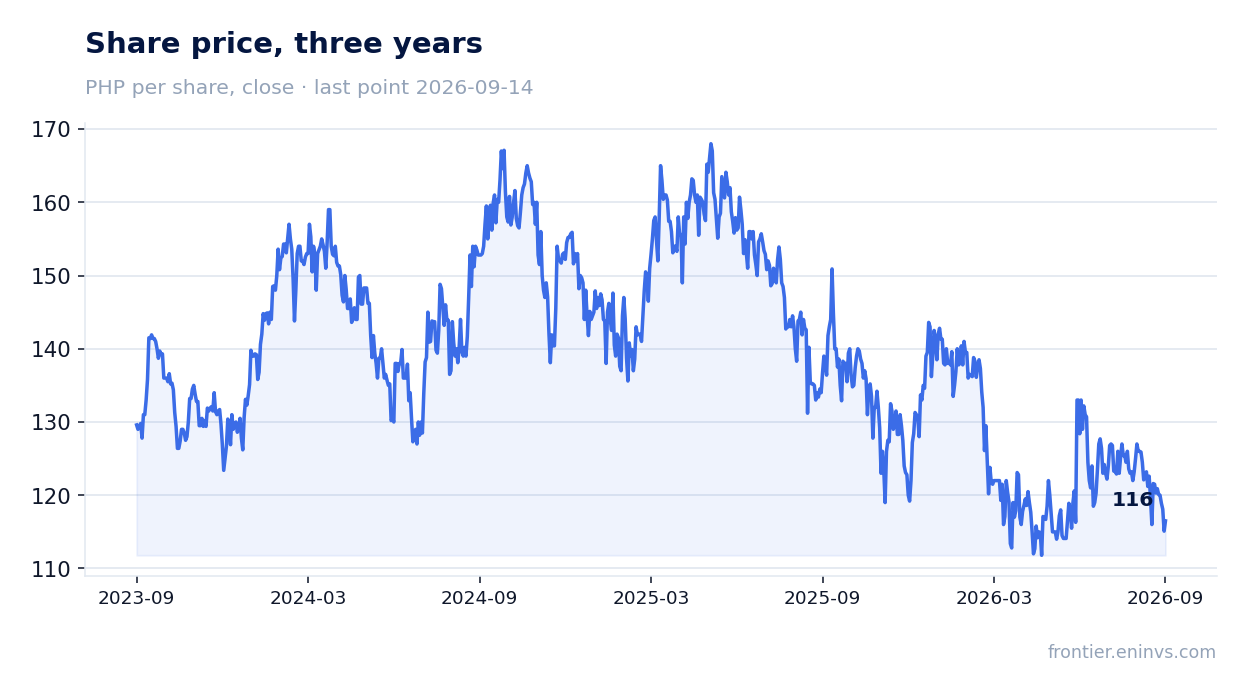
PH_BDO trades at a P/E LTM of 7.06 with a return on equity (ROE) of 12.7%. This is a moderate valuation: the market pays relatively little for earnings, which may reflect either banking sector risks or general undervaluation.
According to the portal's model, which compares ROE with P/B, the upside to fair value is estimated at +13%. This is our own model, not a consensus forecast or a target price. It assumes the current price does not fully reflect the company's ability to generate profit.
A comparison with the three-year history is absent from the provided data, so we cannot say whether the current multiple is above or below its average. Nevertheless, the combination of P/E 7.06 and ROE 12.7% looks balanced for a bank with growing net interest income.
Operating cash flow of 124,066 mn pesos reflects client balances and central-counterparty positions, not a result of operations
Operating cash flow in Q2 2026 was 124,066 mn pesos. For a bank, this metric is not an indicator of performance: it is shaped by client balances, loan issuance and repayment, and central-counterparty operations.
Therefore, we do not draw conclusions about earnings quality based on operating cash flow. Its positive value may indicate an inflow of client funds, which supports liquidity, but does not necessarily signal profit growth.
In a bank's report, the dynamics of net interest income and net profit are more important, which we have already reviewed. Operating cash flow remains outside our analysis, and we do not use it in valuation.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 618 bn PHP |
| P/E (LTM) | 7.1 |
| P/B | 0.96 |
| ROE | 12.7% |
| Dividend yield (12m) | 3.8% |
Bottom line
In Q2 2026, PH_BDO delivered strong 15.6% growth in net interest income to 108,511 mn pesos, a historical high. However, net profit fell 1.5% to 20,668 mn pesos due to faster growth in expenses and provisions. The EBITDA margin was 33.4%, while net profit was only 19.0% of net interest income, indicating moderate efficiency. Meanwhile, the share trades at a P/E LTM of 7.06 and ROE of 12.7%, and the portal's model implies 13% upside. A dividend yield of 3.82% supports the valuation. The key question for a holder is whether the company can sustain net interest income growth and improve cost control to return profit to growth.
Open the company's financial profile BDO →
See also: market overview · valuation map · stock screeners