DMCI Holdings: profit up 2.8x, but almost all of it came from coal and nickel while revenue fell 36%
On 12 August DMCI Holdings released its results for the second quarter of 2026. Quarterly revenue fell 36% year-on-year to PHP 19.0 bn, but net profit rose 176.4% to PHP 14.8 bn and EBITDA rose 118% to PHP 17.8 bn. The gap is explained by a one-off non-cash effect from the reassessment of SLPGC plant asset useful lives that flowed into EBITDA and profit, while revenue contracted on lower coal shipments. On multiples the stock looks cheap: P/E LTM 4.9, EV/EBITDA LTM 3.0, dividend yield 9.6%, and the portal's model puts upside to fair value at +12%. Verdict – rather attractive: the dividend and the low multiple outweigh the one-off nature of quarterly profit, but the sustainability of cash flow is not yet confirmed.
Key takeaways
— Q2 revenue fell 36% year-on-year to PHP 19.0 bn on collapsing coal shipments and lower nickel ore prices
— EBITDA rose 118% to PHP 17.8 bn, but almost the entire gain came from a one-off non-cash effect of reassessing SLPGC plant asset useful lives
— Net profit rose 176.4% to PHP 14.8 bn, with PHP 100 mn of non-recurring items, while coal and nickel segments drove the bulk
— Leverage is moderate: net debt PHP 37.8 bn, net debt / EBITDA LTM 0.76, but the direction of the ratio is not disclosed
— Dividend yield 9.6% on a PHP 0.30 per share payout for 2025, equal to 27% of 2025 core net income of PHP 14.9 bn
— Valuation is cheap versus its own history: P/E LTM 4.9 and EV/EBITDA LTM 3.0, while the portal's model implies +12% upside to fair value
— Free cash flow is in question: quarterly operating cash flow PHP 7.2 bn, but capex is not disclosed and dividend payments absorb a large share
Attractiveness
Key figures, PHP bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 29.7 | 19.0 | -36.0% |
| EBITDA | 8.15 | 17.8 | +118.0% |
| Operating profit | 5.25 | 17.8 | +238.2% |
| Net profit | 5.37 | 14.8 | +176.4% |
| Operating cash flow | 10.8 | 7.23 | -33.2% |
| Capex | 0.49 | — | — |
| EBITDA margin | 27.4% | 93.3% | +65.9 pp |
| Net margin | 18.1% | 78.0% | +59.9 pp |
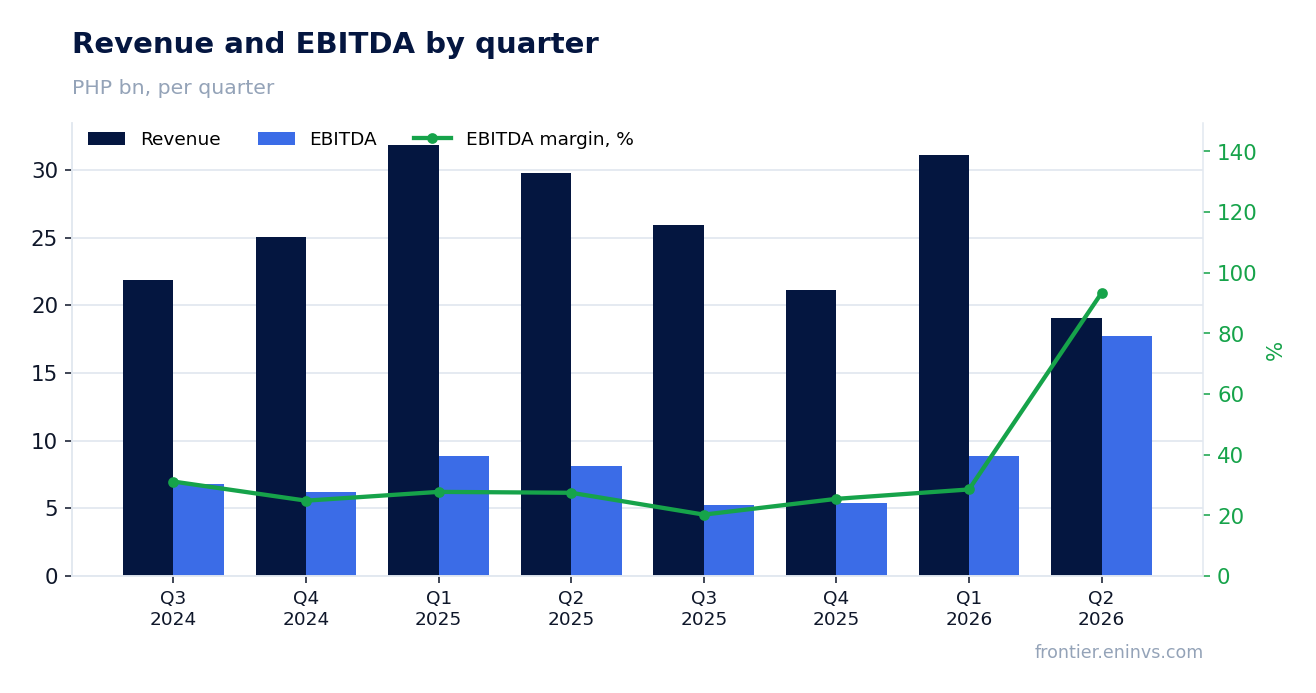
Q2 revenue fell 36% year-on-year to PHP 19.0 bn on collapsing coal shipments and lower nickel ore prices
Q2 2026 revenue came in at PHP 19.0 bn, down 36% from the same quarter last year. The decline is driven primarily by the coal segment: coal shipments fell 13% to 4.0 mn tonnes, while production collapsed 55% to 2.5 mn tonnes due to limited access to quality coal at the Acacia mine and a higher strip ratio. In nickel, shipments rose 2.4x to 1.26 mn tonnes, but the average selling price fell 10% to USD 35 per tonne, failing to offset the coal revenue decline.
Construction revenue also declined, partly offset by growth in real estate and cement. Nevertheless, the combined effect of the coal and nickel segments proved dominant. For context: in Q1 2026 revenue fell only 2.4% year-on-year, and in Q4 2025 it fell 15.6%. Thus Q2 saw a sharp deterioration in top-line dynamics.
EBITDA rose 118% to PHP 17.8 bn, but almost the entire gain came from a one-off non-cash effect of reassessing SLPGC plant asset useful lives
Q2 2026 EBITDA came in at PHP 17.8 bn, up 118% year-on-year. However, this growth is almost entirely explained by a one-off non-cash effect: the company reassessed the useful lives of SLPGC plant assets, which reduced depreciation and thus boosted EBITDA. The report notes a non-recurring gain of PHP 180 mn at the group level, but the effect on EBITDA is much larger as the reassessment affected depreciation in the power segment.
Without this effect, EBITDA would likely have declined, reflecting the revenue drop. The EBITDA margin in the reported quarter was 93.3% versus 27.4% a year earlier – such a jump cannot be sustainable and reflects the one-off nature of the factor. For comparison: in Q1 2026 the EBITDA margin was around 28.5%, close to the company's normal level.
Net profit rose 176.4% to PHP 14.8 bn, with PHP 100 mn of non-recurring items, while coal and nickel segments drove the bulk
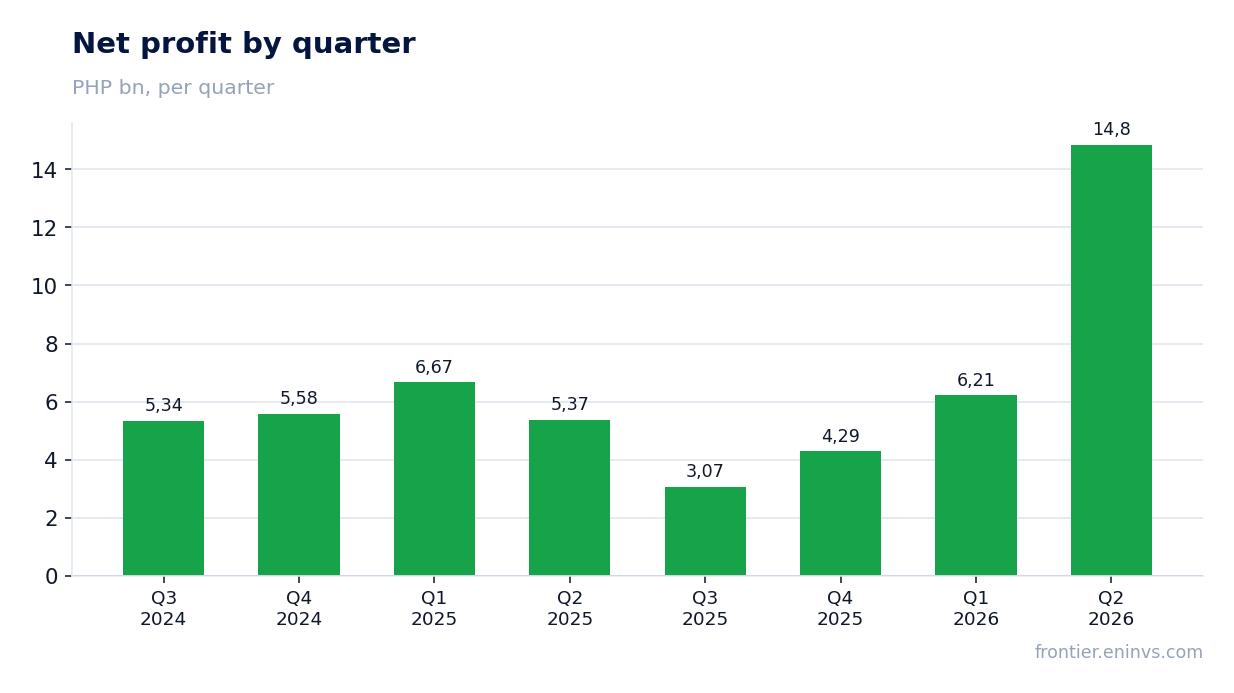
Q2 2026 net profit came in at PHP 14.8 bn, up 176.4% year-on-year. However, as with EBITDA, a significant portion of this growth is due to the one-off non-cash effect from the reassessment of SLPGC asset useful lives. In addition, the company recognised non-recurring items of PHP 100 mn, substantially less than the prior year when non-recurring items were only PHP 1 mn.
The main contribution to profit came from the coal and nickel segments. The coal segment, despite lower revenue, showed profit growth due to lower depreciation and tax effects. The nickel segment increased profit 3.8x to PHP 1.3 bn on record shipments. However, the net margin of 78% (versus 18.1% a year earlier) is clearly inflated by the one-off factor and does not reflect sustainable profitability.
Leverage is moderate: net debt PHP 37.8 bn, net debt / EBITDA LTM 0.76, but the direction of the ratio is not disclosed
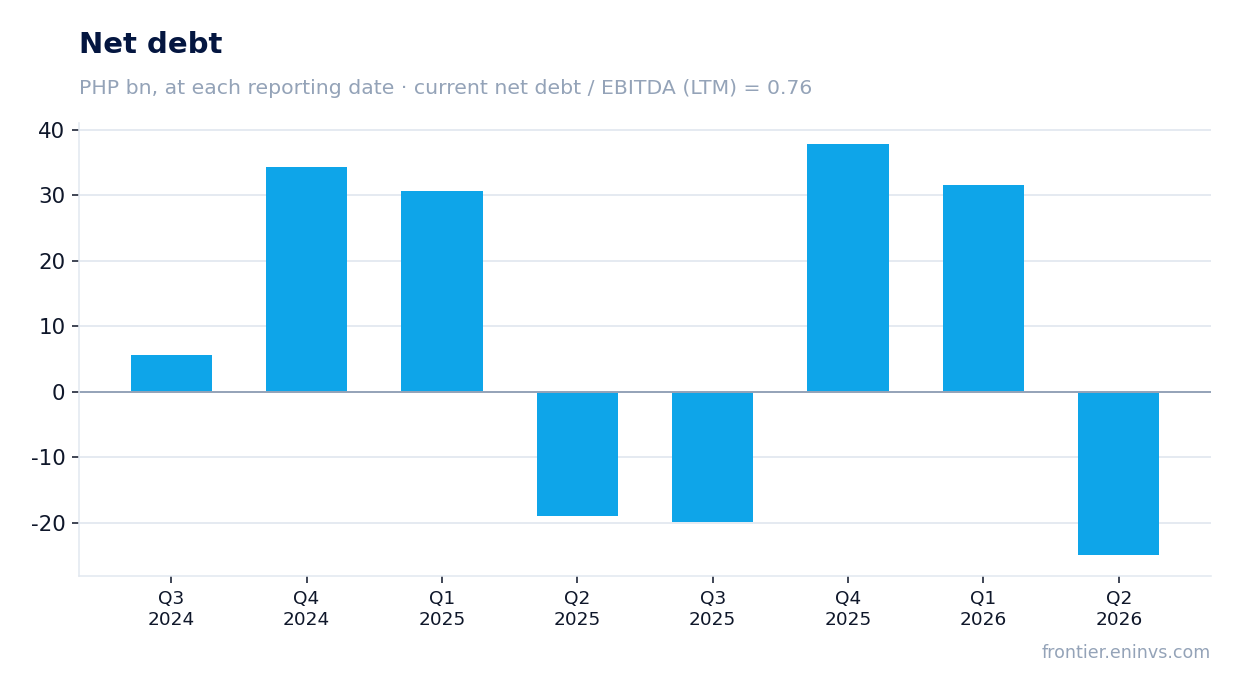
Net debt at the latest reporting date stood at PHP 37.8 bn, with a net debt / EBITDA LTM ratio of 0.76. This is a moderate level that raises no concerns. However, the previous value of this ratio is not provided in the facts, so it cannot be stated that leverage has fallen or risen – only the current level can be noted.
The change in net debt versus the previous reporting date was minus RUB 56.6 bn, and over 12 months minus RUB 6.1 bn. This is a reduction, but it may be driven by seasonal factors and one-off inflows. Operating cash flow for the quarter was PHP 7.2 bn, covering interest payments, but capex is not disclosed, complicating free cash flow assessment.
Dividend yield 9.6% on a PHP 0.30 per share payout for 2025, equal to 27% of 2025 core net income of PHP 14.9 bn
The trailing 12-month dividend yield is 9.6%. The latest payout was PHP 0.30 per share, declared on 7 May 2026 and paid on 5 June 2026. This represents 27% of 2025 core net income of PHP 14.9 bn, in line with the company's dividend policy of distributing at least 25% of the previous year's core earnings.
Our estimate for the 2026 dividend: assuming a payout ratio of 27% and core net income of around PHP 20 bn (based on current trends), the dividend per share could be around PHP 0.40, implying a yield of about 12% at the current price. However, this depends on the sustainability of profit, which is heavily influenced by one-off factors. The key risk is a decline in coal and nickel prices, as well as a possible increase in capital expenditures.
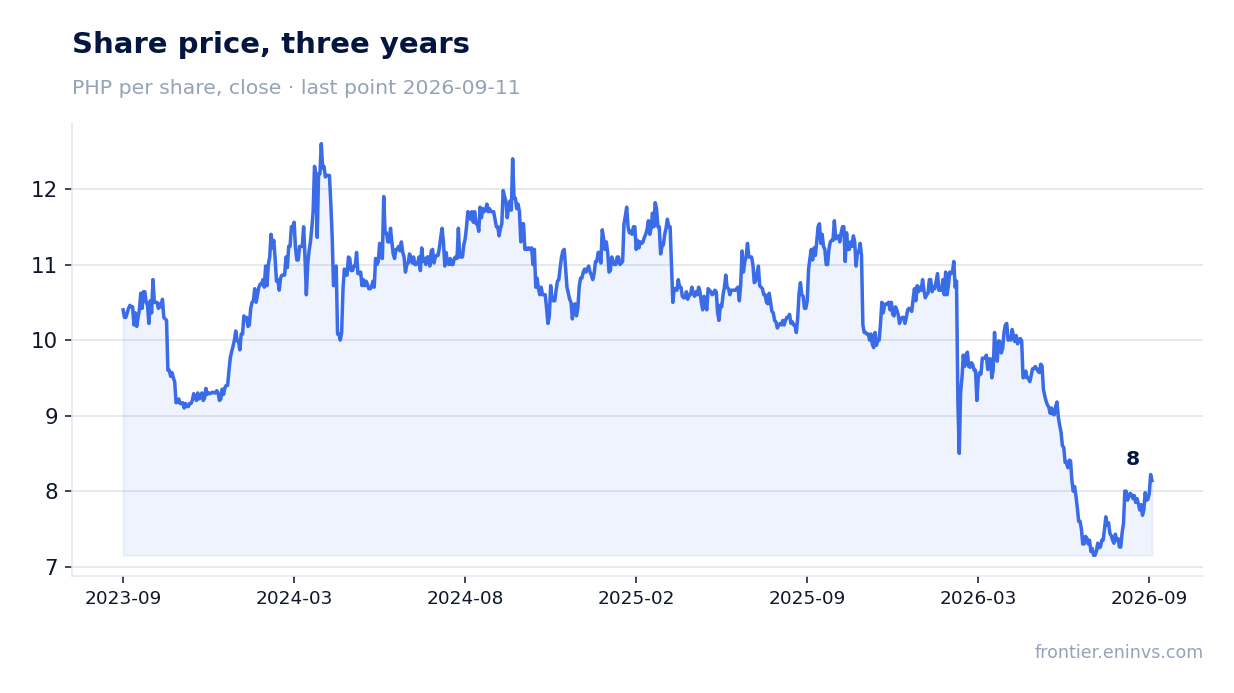
Valuation is cheap versus its own history: P/E LTM 4.9 and EV/EBITDA LTM 3.0, while the portal's model implies +12% upside to fair value
The trailing P/E is 4.9 and EV/EBITDA is 3.0. These are low values that may indicate undervaluation. However, we do not have data on the average values over the past three years for comparison, so it cannot be stated that the stock trades below its historical level – only that current multiples are low in absolute terms.
The portal's model estimates upside to fair value at +12%. This is our own model, not market consensus. Combined with a dividend yield of 9.6%, the total expected return could be attractive, but it depends on the sustainability of profit. If one-off factors do not repeat, profit may decline and multiples would rise.
Free cash flow is in question: quarterly operating cash flow PHP 7.2 bn, but capex is not disclosed and dividend payments absorb a large share
Operating cash flow for Q2 2026 was PHP 7.2 bn. This is less than net profit, explained by the non-cash nature of part of the profit. Capital expenditures for the quarter are not disclosed, so free cash flow cannot be assessed. In previous periods, capex was volatile: from PHP 0.5 bn in Q2 2025 to PHP 8.3 bn in Q4 2024.
Dividend payments for 2025 amounted to about PHP 4.0 bn, a significant outflow. At the same time, the company reduced net debt, which may indicate sufficient cash flow to cover investments and dividends. However, without quarterly capex data, the assessment of free cash flow sustainability remains incomplete.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 109 bn PHP |
| P/E (LTM) | 4.9 |
| EV/EBITDA (LTM) | 3.0 |
| P/B | 0.74 |
| Net debt / EBITDA (LTM) | 0.76 |
| Operating cash flow (LTM) | 25.2 bn |
| ROE | 16.4% |
| Dividend yield (12m) | 9.6% |
Bottom line
Bottom line: in Q2 2026 DMCI Holdings delivered impressive profit growth, but it was almost entirely due to a one-off non-cash effect from reassessing SLPGC asset useful lives. Revenue fell 36% on coal segment issues, and without the one-off factor the financial results would have looked much weaker. The company maintains low leverage (net debt/EBITDA 0.76) and a high dividend yield (9.6%), making the stock attractive for income-oriented investors. However, the sustainability of cash flow and the ability to maintain dividend payments at the current level are questionable. Verdict – rather attractive: the dividend and low multiples outweigh the risks, but confirmation of sustainability requires capex data and commodity price trends.
Open the company's financial profile DMC →
See also: market overview · valuation map · stock screeners