Globe Telecom: revenue is growing again, but profit is not coming from operations
On 25 August Globe Telecom released its results for the six months ended 30 June 2026. In the second quarter revenue rose 7.9% year on year to PHP 46,954.6 mn, net profit added 0.4% to PHP 5,485.1 mn, while EBITDA fell 14.5% to PHP 17,808.4 mn. The EBITDA margin dropped to 37.9% from 47.8% a year earlier, and with an EV/EBITDA of 5.8 and a dividend yield of 6.25% the share looks rather attractive than not – but only if revenue growth holds and the gap between EBITDA and profit proves temporary.
Key takeaways
— Revenue returned to growth for the first time in a year: +7.9% year on year versus a 1.9% decline a quarter earlier
— EBITDA fell 14.5% and the margin compressed to 37.9% from 47.8% – profit was not held up by operations
— Net profit was almost unchanged even though quarterly operating profit was only PHP 3,542.9 mn
— Debt at 2.89x LTM EBITDA is moderate, but a PHP 22.4 bn reduction in net debt during the quarter supported profit
— The 6.25% dividend yield comes with a payout that may not be covered by operating cash flow
— EV/EBITDA of 5.8 and P/E of 10.7 are below historical levels but reflect the risk of falling EBITDA
Attractiveness
Key figures, PHP bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 43.5 | 47.0 | +7.9% |
| EBITDA | 20.8 | 17.8 | -14.5% |
| Operating profit | 9.29 | 3.54 | -61.8% |
| Net profit | 5.46 | 5.49 | +0.4% |
| Operating cash flow | 13.4 | 18.1 | +35.3% |
| Capex | 10.4 | — | — |
| EBITDA margin | 47.8% | 37.9% | -9.9 pp |
| Net margin | 12.5% | 11.7% | -0.8 pp |
Revenue returned to growth for the first time in a year: +7.9% year on year versus a 1.9% decline a quarter earlier
In the second quarter of 2026, Globe Telecom's revenue reached PHP 46,954.6 mn, up 7.9% year on year. This is the first quarter of positive growth in the last five quarters: in the first quarter of 2026 revenue grew 4.5%, while the preceding four quarters saw declines – 1.9% in Q2 2025, 1.6% in Q3 and 4.0% in Q4. The acceleration from Q1 to Q2 is evident, but it is important to note that it comes off a weak base.
The drivers of revenue growth are not detailed in the report, but the return to growth after a year of decline suggests the company either stabilised pricing or expanded its subscriber base in mobile and broadband. Without segment breakdowns in the source, it is difficult to say which business drove revenue, but the overall trend is positive.
For an investor, the more important question is how revenue growth converts into profit. So far, conversion is weak: EBITDA for the same quarter fell 14.5%, while net profit rose only 0.4%. This means revenue growth is accompanied by faster cost growth, and the sustainability of this model is questionable.
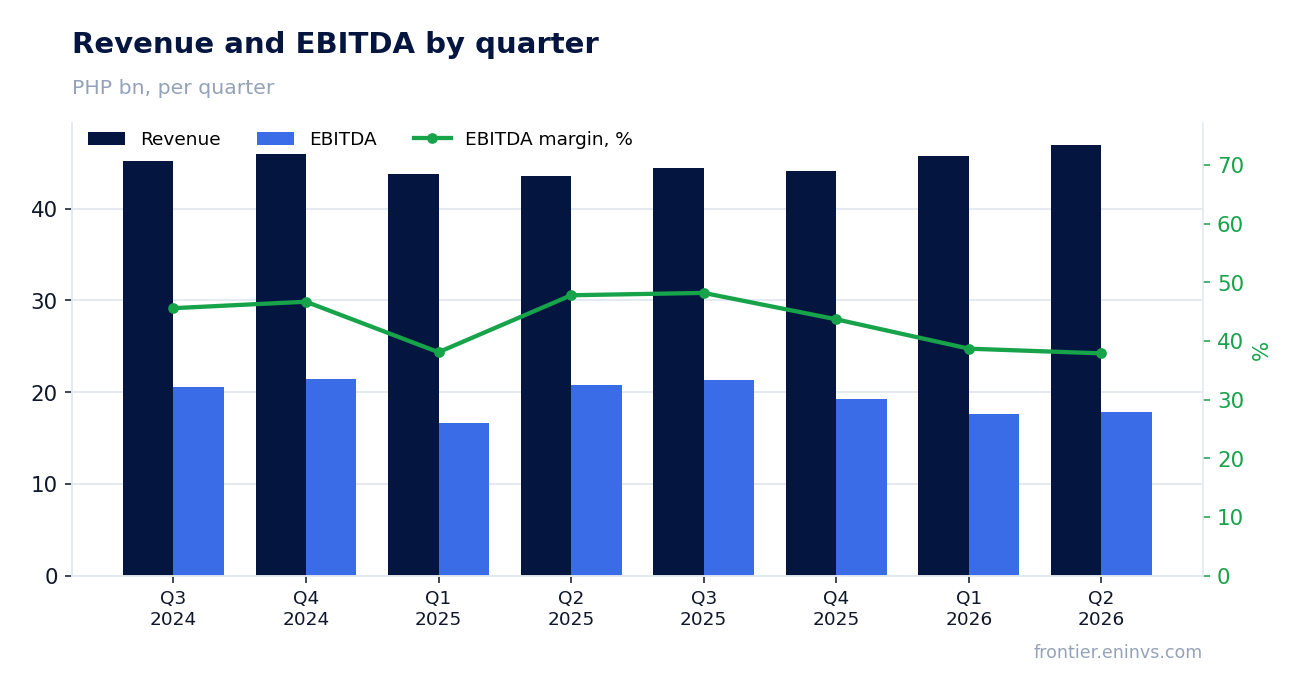
EBITDA fell 14.5% and the margin compressed to 37.9% from 47.8% – profit was not held up by operations
EBITDA in the second quarter of 2026 was PHP 17,808.4 mn, down 14.5% year on year. The EBITDA margin fell to 37.9% from 47.8% in Q2 2025. This is a sharp compression – almost 10 percentage points – indicating that revenue growth is accompanied by a significant increase in operating expenses.
Operating profit for the quarter was only PHP 3,542.9 mn, well below EBITDA. The gap between EBITDA and operating profit is explained by depreciation and possibly one-off charges. In Q4 2024 and Q4 2025, operating profit was negative, pointing to large non-cash write-offs at year-end. In Q2 2026, operating profit is positive but modest.
Net profit, however, was almost unchanged at PHP 5,485.1 mn versus PHP 5,461.1 mn a year earlier. The fact that net profit held up despite falling EBITDA and weak operating profit means the company received support below the operating line – likely from lower net debt and thus lower interest expenses, and possibly from one-off items. Without details in the source, the exact cause cannot be identified, but it is clear that operating efficiency has deteriorated.
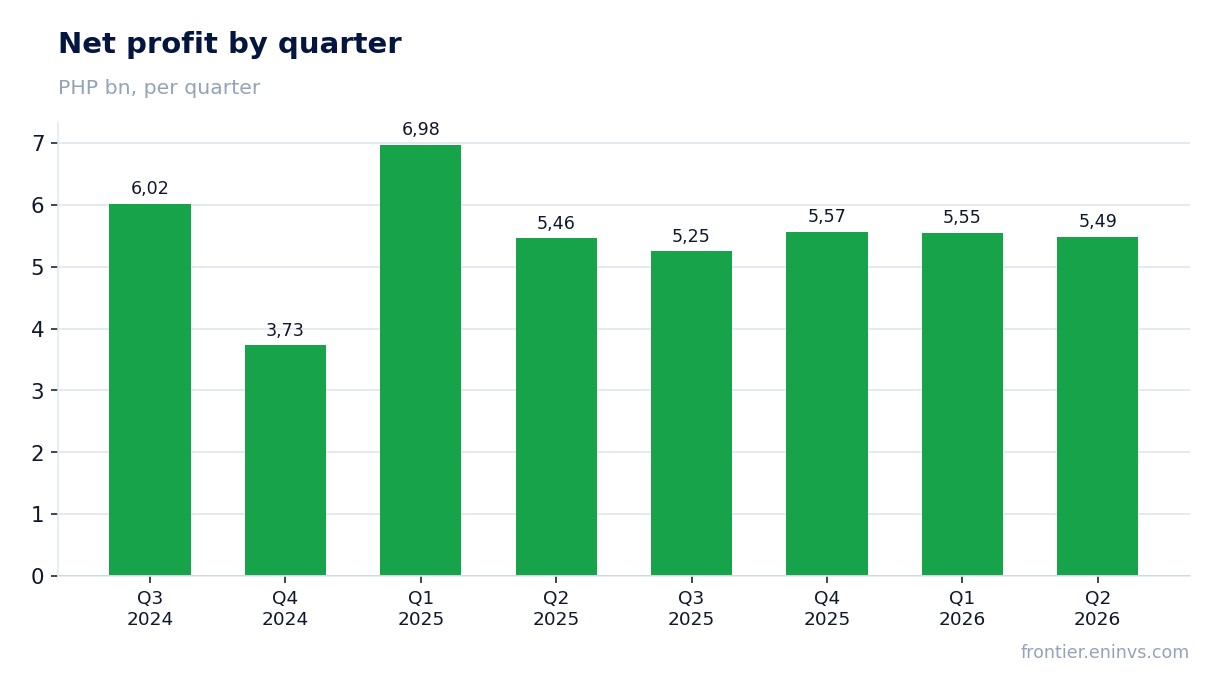
Net profit was almost unchanged even though quarterly operating profit was only PHP 3,542.9 mn
Net profit in Q2 2026 was PHP 5,485.1 mn, up 0.4% year on year. At the same time, operating profit was only PHP 3,542.9 mn, meaning net profit exceeded operating profit. This indicates the company received significant income below the operating line – likely from financial income, lower interest expenses, or one-off items.
The reduction in net debt by PHP 22.4 bn during the quarter (from PHP 231,283.1 mn at end-Q1 2026 to PHP 231,313.0 mn at end-Q2) could have reduced interest expenses, but the exact savings are not disclosed. It is also possible the company recognised a one-off gain from asset sales or revaluation, but the source does not detail this.
For an investor, it is important that net profit is not underpinned by operating efficiency. If the support from below disappears, profit could come under pressure. Moreover, trailing twelve-month net profit was PHP 21,863.0 mn, and at the current price the LTM P/E is 10.7 – a low level, but one that reflects the risk of falling profit.
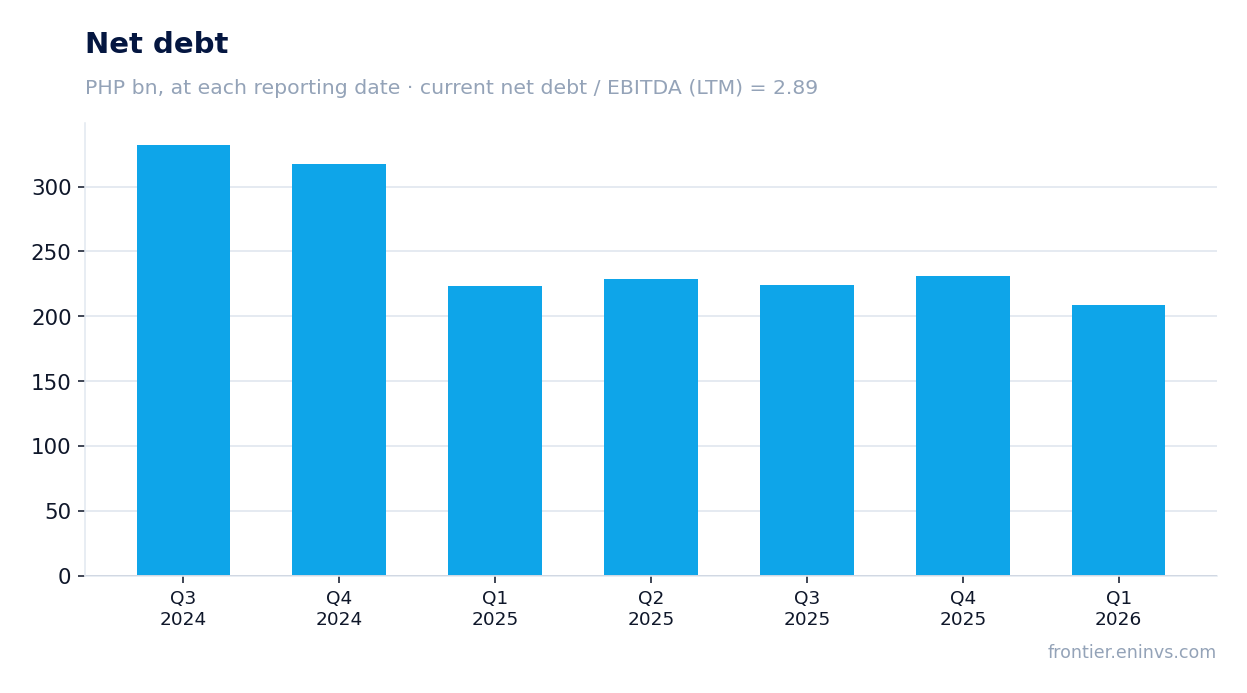
Debt at 2.89x LTM EBITDA is moderate, but a PHP 22.4 bn reduction in net debt during the quarter supported profit
Globe Telecom's net debt at the end of Q2 2026 was PHP 231,313.0 mn. The ratio of net debt to LTM EBITDA is 2.89. This is a moderate level for a telecom company, but it does not tell the full story, as LTM EBITDA includes strong previous quarters. If EBITDA continues to fall, leverage could rise.
During the quarter, net debt decreased by PHP 22.4 bn, and over 12 months by PHP 14.4 bn. Lower debt reduces interest expenses and supports net profit. However, the source does not disclose how the reduction was achieved – possibly through operating cash flow or asset sales.
Operating cash flow in Q2 2026 was PHP 18,059.4 mn, lower than in Q1 (PHP 23,560.0 mn) but higher than a year earlier (PHP 13,351.9 mn). Over the last 12 months, operating cash flow was PHP 79,500.0 mn. This is sufficient to service debt but does not fully cover dividend payments and capital expenditures.
The 6.25% dividend yield comes with a payout that may not be covered by operating cash flow
Globe Telecom's dividend yield over the last 12 months is 6.25%. This is above the current yield on Philippine government bonds, making the stock attractive for income-oriented investors. However, the sustainability of the dividend is questionable.
Operating cash flow over the last 12 months was PHP 79,500.0 mn. Capital expenditures for the same period, based on quarterly data, were about PHP 50,000 mn (sum of quarterly capex for the last four quarters: 8,437.1 + 10,418.1 + 12,566.4 + 14,645.8 = 46,067.4 mn). Thus, free cash flow before dividends is roughly PHP 33,400 mn. With a market capitalisation of PHP 233,146.1 mn, a 6.25% dividend yield implies a payout of about PHP 14,572 mn per year. This is covered by free cash flow, but the buffer is thin.
If EBITDA continues to fall and capital expenditures remain high, the company may need to cut the dividend or increase debt to fund it. The source does not contain statements about dividend policy for 2026, so our forecast is our own estimate based on current metrics. The key risk is further margin compression.
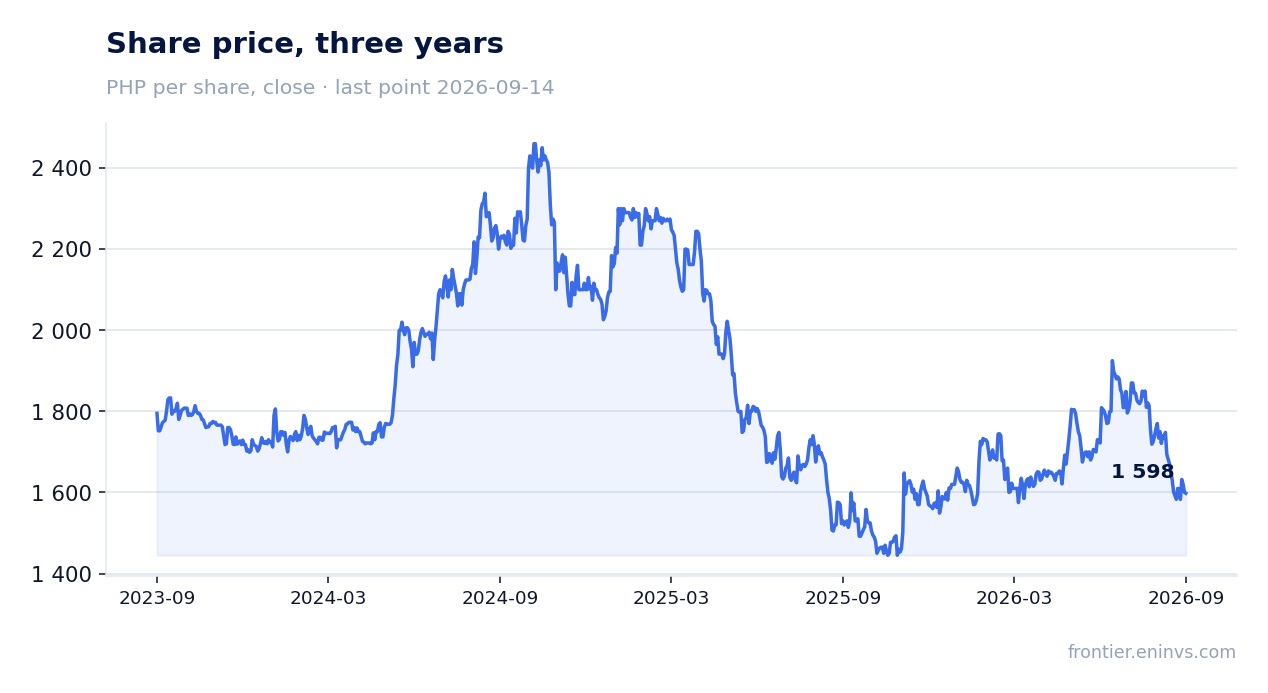
EV/EBITDA of 5.8 and P/E of 10.7 are below historical levels but reflect the risk of falling EBITDA
The current LTM EV/EBITDA is 5.8, and the LTM P/E is 10.7. For a telecom company, these are not high levels and may indicate undervaluation. However, without three-year historical data in the FACTS, we cannot compare with the company's own history. According to the portal's model, the upside to fair value is +16%.
Return on equity (ROE) over the last 12 months is 11.5%. This is a moderate figure that does not compensate for the risk of falling profit. If EBITDA continues to decline, multiples could rise even if the share price stays flat.
It is important to note that EV/EBITDA is based on LTM EBITDA, which includes stronger previous quarters. If the current EBITDA level (PHP 17,808.4 mn per quarter) persists, annual EBITDA would be about PHP 71,200 mn, which is 11% below the LTM EBITDA of PHP 80,040.5 mn. This means the forward EV/EBITDA could be higher than 5.8.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 233 bn PHP |
| P/E (LTM) | 10.7 |
| EV/EBITDA (LTM) | 5.8 |
| P/B | 1.34 |
| Net debt / EBITDA (LTM) | 2.89 |
| Operating cash flow (LTM) | 79.5 bn |
| ROE | 11.5% |
| Dividend yield (12m) | 6.2% |
Bottom line
Globe Telecom showed a return to revenue growth, but operating efficiency deteriorated sharply: EBITDA fell 14.5% and the margin compressed to 37.9%. Net profit was sustained only by lower debt and possibly one-off items. The 6.25% dividend yield is attractive, but its coverage by free cash flow is thin. With EV/EBITDA at 5.8 and P/E at 10.7, the share looks rather attractive than not, but the key question is whether the company can restore its margin. If EBITDA stabilises, the portal model's upside is +16%.
Open the company's financial profile GLO →
See also: market overview · valuation map · stock screeners