Megaworld: profit up 16.3% but revenue barely grows and Q2 EBITDA declined
On 4 May Megaworld Corporation released its Q1 2026 report. Revenue for the quarter rose 3.0% year on year to PHP 20.5bn, net profit increased 6.1% to PHP 6.18bn, and the net margin improved to 30.2% from 29.3%. However, in Q2, based on published quarterly data, revenue grew only 2.2% while EBITDA declined to PHP 8.11bn from PHP 8.49bn a year earlier. With a trailing P/E of 3.02 and a dividend yield of 5.38%, the stock looks rather attractive, but weak revenue growth and the absence of Q2 operating cash flow data call for caution.
Key takeaways
— Q1 2026 revenue grew 3.0% to PHP 20.5bn, but Q2 growth slowed to 2.2%
— Q1 net profit rose 6.1% to PHP 6.18bn, with the net margin improving to 30.2% from 29.3%
— Q2 EBITDA fell to PHP 8.11bn from PHP 8.49bn a year earlier, while operating profit remained at PHP 8.11bn
— Leverage stands at 2.33x LTM EBITDA, with net debt down PHP 6.8bn over 12 months
— A 5.38% dividend yield and a trailing P/E of 3.02 make the stock one of the cheapest in the sector, but dividend sustainability hinges on profit
— Q1 2026 operating cash flow was PHP 4.26bn, and PHP 11.4bn over the trailing twelve months
— The portal's model puts the upside to fair value at +20%
Attractiveness
Key figures, PHP bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 20.8 | 21.3 | +2.2% |
| EBITDA | 8.49 | — | — |
| Operating profit | 7.58 | 8.11 | +7.0% |
| Net profit | 5.60 | 6.51 | +16.3% |
| Operating cash flow | 4.12 | — | — |
| EBITDA margin | 40.8% | — | — |
| Net margin | 26.9% | 30.6% | +3.7 pp |
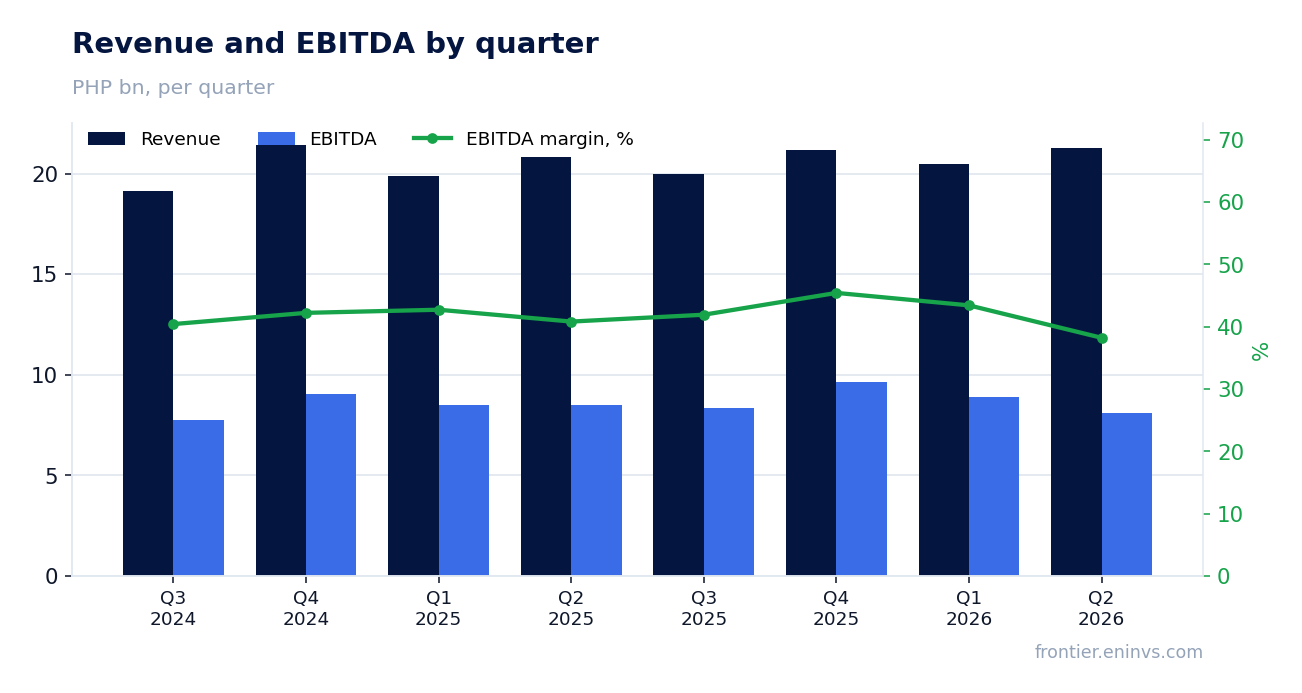
Q1 2026 revenue grew 3.0% to PHP 20.5bn, but Q2 growth slowed to 2.2%
In Q1 2026 Megaworld's revenue reached PHP 20.5bn, up 3.0% year on year. Real estate sales contributed PHP 13.3bn and rental income PHP 5.65bn. The growth was modest compared with the double-digit rates of previous years.
In Q2 2026 revenue grew only 2.2% year on year to PHP 21.3bn. This is the weakest quarterly increase in several quarters: Q1 2025 saw 6.4% growth, Q2 9.5%, Q3 4.3%, Q4 a 1.2% decline, and Q1 2026 3.0%.
The slowdown reflects a high base from last year and possibly more cautious housing demand. The company does not disclose Q2 segment details, so the exact cause cannot be identified. But the fact remains: revenue growth has nearly stalled.
Q1 net profit rose 6.1% to PHP 6.18bn, with the net margin improving to 30.2% from 29.3%
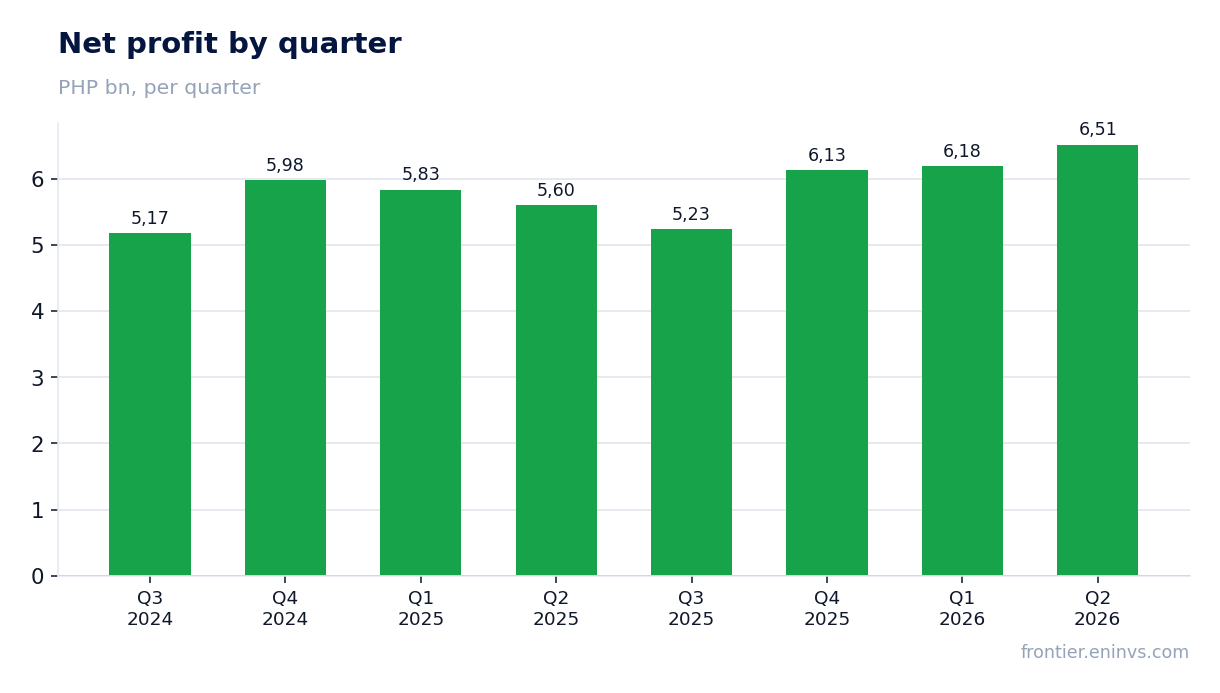
Q1 2026 net profit came in at PHP 6.18bn, up 6.1% from PHP 5.83bn a year earlier. The net margin improved to 30.2% from 29.3% in Q1 2025.
The margin improvement occurred despite a 10.6% increase in operating expenses and higher interest costs. It was supported by lower cost of real estate sales and higher other income. A reduction in the share of non-controlling interests also helped.
In Q2 2026 net profit rose 16.3% year on year, with the margin reaching 30.6% versus 26.9% a year earlier. This is a strong result, but it was achieved on weak revenue growth, indicating efficiency gains and possibly one-off factors.
Q2 EBITDA fell to PHP 8.11bn from PHP 8.49bn a year earlier, while operating profit remained at PHP 8.11bn
In Q2 2026 Megaworld's EBITDA amounted to PHP 8.11bn, down 4.4% from PHP 8.49bn a year earlier. This decline occurred despite a 2.2% revenue increase, pointing to margin pressure.
Operating profit in Q2 also stood at PHP 8.11bn, matching EBITDA. This may indicate that depreciation and other non-cash items were minimal or that the company changed its expense classification. In any case, operating efficiency declined.
Over the trailing twelve months EBITDA reached PHP 35.2bn. The year-on-year decline in the quarterly figure is a warning sign, especially since Q1 2026 EBITDA rose to PHP 8.87bn from PHP 8.49bn a year earlier.
Leverage stands at 2.33x LTM EBITDA, with net debt down PHP 6.8bn over 12 months
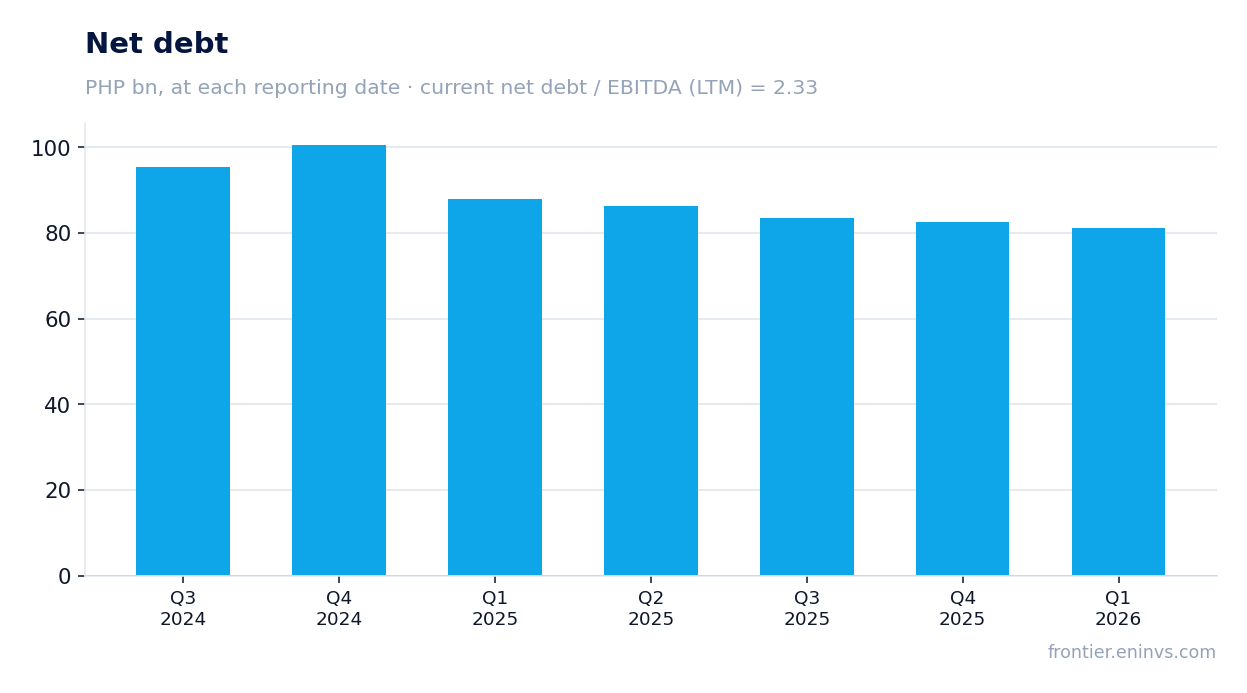
Megaworld's net debt at the latest reporting date stood at PHP 82.0bn. The net debt to trailing twelve-month EBITDA ratio is 2.33x. This is a moderate level for a developer, but it cannot be compared with earlier values as no prior ratio is available in the facts.
Over the past 12 months net debt decreased by PHP 6.8bn, and by PHP 1.6bn from the previous reporting date. The debt reduction is occurring alongside profit growth, strengthening the financial position.
Interest expenses in Q1 2026 rose to PHP 1.64bn from PHP 1.41bn a year earlier, reflecting higher borrowing costs. However, at the current debt and EBITDA levels the company can service its obligations.
A 5.38% dividend yield and a trailing P/E of 3.02 make the stock one of the cheapest in the sector, but dividend sustainability hinges on profit
Megaworld's trailing twelve-month dividend yield is 5.38%. This is above the yield on most Philippine bonds and the policy rate, making the stock attractive for income-oriented investors.
The trailing P/E is 3.02, which is very low. Historically, the company traded at higher multiples. EV/EBITDA LTM stands at 4.40. Such a valuation implies that the market is pricing in either a profit decline or risks related to the development cycle.
Dividend payments are funded from net profit, which over the trailing twelve months amounted to PHP 24.1bn. With a payout ratio of around 20%, the annual dividend is approximately PHP 4.8bn. A decline in profit or an increase in capital expenditures could lead to a dividend cut.
Q1 2026 operating cash flow was PHP 4.26bn, and PHP 11.4bn over the trailing twelve months
Operating cash flow in Q1 2026 was PHP 4.26bn, up 9.0% from PHP 3.91bn a year earlier. This is a positive signal, as cash flow is growing faster than revenue.
Over the trailing twelve months operating cash flow reached PHP 11.4bn. However, in Q4 2025 it was negative at minus PHP 7.02bn, due to seasonal factors and an increase in receivables. Overall, the ability to generate cash flow remains key to funding dividends and capital expenditures.
Q2 2026 operating cash flow data is not available, preventing an assessment of the dynamics in the second quarter. This creates uncertainty.
The portal's model puts the upside to fair value at +20%
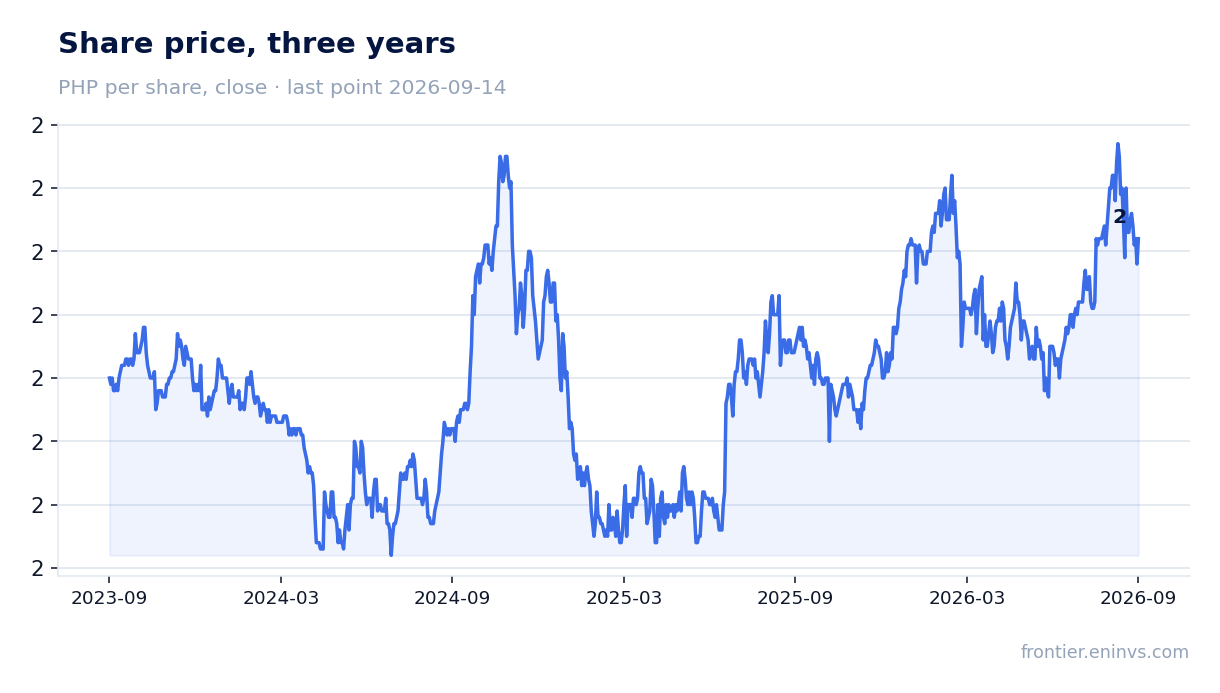
According to the portal's model, Megaworld's fair value implies +20% upside from the current price. The model incorporates EBITDA growth and a target multiple. This is our own estimate, not a market consensus.
The current market capitalisation is PHP 72.6bn. With EV/EBITDA LTM at 4.40 and P/E LTM at 3.02, the stock is trading below its historical levels. If the company can resume revenue growth and maintain its margin, the multiples could expand.
However, the model does not account for a possible decline in profit or a deterioration in market conditions. The 20% upside looks realistic but requires confirmation in the form of accelerating revenue and stable cash flow.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 72.6 bn PHP |
| P/E (LTM) | 3.0 |
| EV/EBITDA (LTM) | 4.4 |
| P/B | 0.24 |
| Net debt / EBITDA (LTM) | 2.33 |
| Operating cash flow (LTM) | 11.4 bn |
| ROE | 8.3% |
| Dividend yield (12m) | 5.4% |
Bottom line
Megaworld reported Q1 2026 with revenue up 3.0% and net profit up 6.1%, while in Q2 profit rose 16.3% with a 30.6% margin. However, Q2 revenue grew only 2.2% and EBITDA fell to PHP 8.11bn from PHP 8.49bn a year earlier. Leverage stands at 2.33x LTM EBITDA, with net debt down PHP 6.8bn over the year. A 5.38% dividend yield and a trailing P/E of 3.02 make the stock cheap, but dividend sustainability hinges on profit. The portal's model puts upside at +20%. Overall, the stock looks rather attractive, but confirmation requires sustainable revenue and cash flow growth.
Open the company's financial profile MEG →
See also: market overview · valuation map · stock screeners