Robinsons Land: profit up 15.5%, but the gap between accounting and cash returns widens
On 11 May Robinsons Land Corporation released its first-quarter 2026 results. Revenue rose 11.3% to PHP 12,281.5 million, net profit added 15.5% to reach PHP 4,400.1 million, and the net margin improved to 35.2% from 33.3% a year earlier. Over the trailing twelve months, however, the company earned PHP 18,392.2 million in net profit but generated only PHP 16,700.0 million in operating cash flow, while EBITDA stood at PHP 5,555.2 million – 3.3 times less than profit. The stock trades at a P/E of 4.44 and a dividend yield of 5.88%, but EV/EBITDA of 21.76 and the portal model's negative upside of -38% leave little room for appreciation. Verdict – neutral: the dividend and low P/E support the price, but the gap between profit and cash flow, along with high leverage at 7.05 net debt to EBITDA, limits attractiveness.
Key takeaways
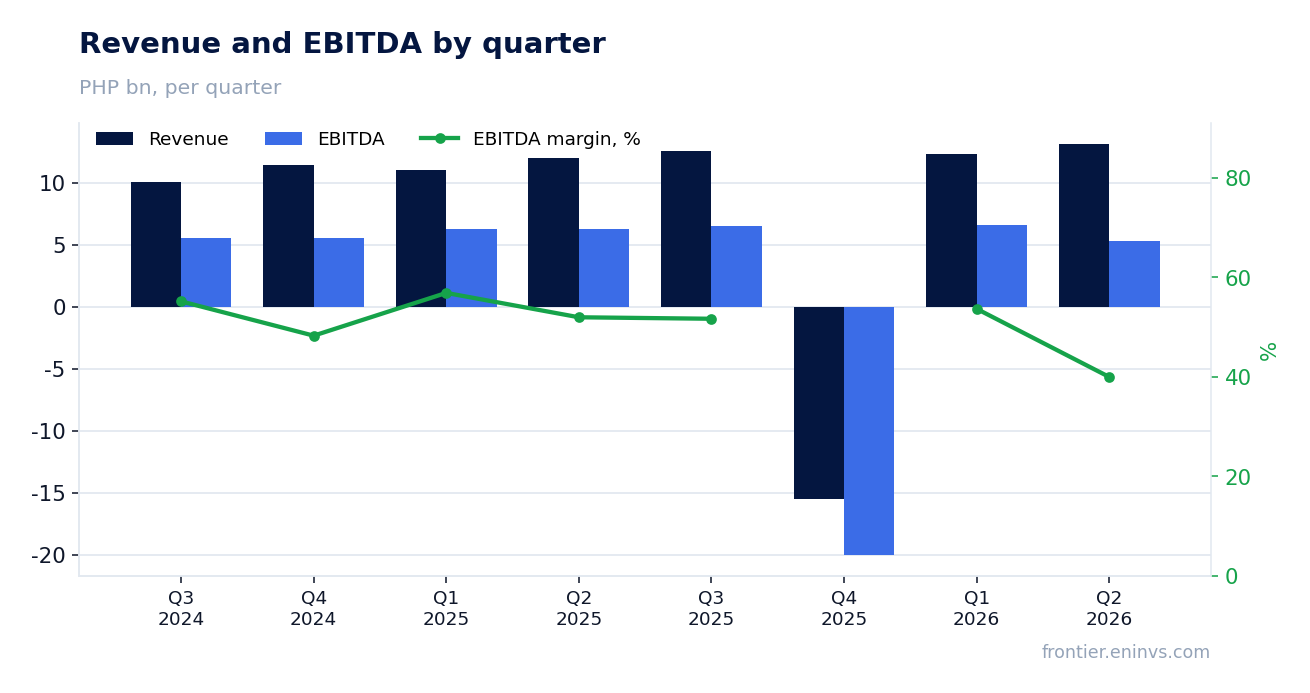
— Revenue rose 11.3% on residential real estate and hotels, but office and logistics leasing remain weak links
— Net margin improved to 35.2% due to lower interest expenses and higher other income
— Net profit over the last 12 months reached PHP 18,392.2 million, but EBITDA was only PHP 5,555.2 million, indicating low operating efficiency
— Operating cash flow for Q1 2026 reached PHP 7,219.1 million, yet over 12 months it lags behind profit
— Leverage remains high: net debt to LTM EBITDA is 7.05, and net debt increased by PHP 17.8 billion in the quarter
— Dividend yield of 5.88% with a payout ratio of about 26% of LTM profit supports interest in the stock
— The portal model's valuation implies a 38% downside to fair value, outweighing the low P/E of 4.44
Attractiveness
Key figures, PHP bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 12.0 | 13.1 | +9.5% |
| EBITDA | 6.24 | — | — |
| Operating profit | 4.73 | 5.26 | +11.3% |
| Net profit | 4.00 | 4.62 | +15.5% |
| Operating cash flow | 6.22 | — | — |
| EBITDA margin | 52.0% | — | — |
| Net margin | 33.3% | 35.2% | +1.9 pp |
Revenue rose 11.3% on residential real estate and hotels, but office and logistics leasing remain weak links
In Q1 2026, Robinsons Land's revenue grew 11.3% year-on-year to PHP 12,281.5 million. The main contributors were residential real estate sales, which jumped 40% to PHP 2,600.5 million, and the hotel segment, up 14% to PHP 1,721.1 million. Rental income rose only 5% to PHP 5,873.1 million, while other income fell 4% to PHP 1,846.2 million.
The office segment saw revenue rise 8% to PHP 2,168 million, but logistics (RLX) remains small at PHP 269 million. Robinsons Malls generated PHP 5,064 million, up 7% year-on-year, but its EBITDA grew only 3% to PHP 3,081 million, and EBIT rose 2% to PHP 2,172 million. This indicates that revenue growth in the segment does not translate proportionally into profit.
Thus, residential real estate remains the growth driver, but its share of revenue is 24% (PHP 2,898 million including equity share from joint ventures). The hotel segment accounts for 14% of revenue. The sustainability of such growth is questionable, as it relies on the realisation of previously sold projects rather than new sales.
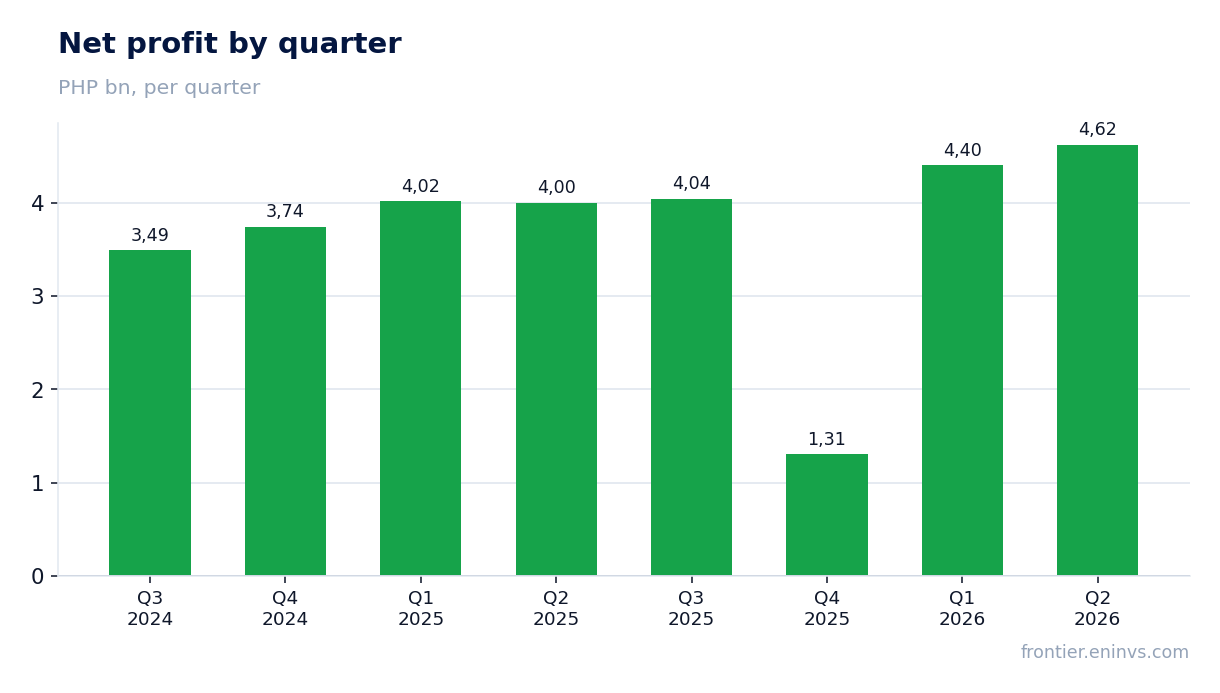
Net margin improved to 35.2% due to lower interest expenses and higher other income
The net profit margin in Q1 2026 was 35.2% versus 33.3% a year earlier. The margin increase occurred despite operating margin (EBIT to revenue) falling to 41% from 44% a year earlier. The reason was a 19% decline in interest expenses to PHP 429.0 million and a 100% increase in interest income to PHP 137.8 million.
In addition, the company recorded a foreign exchange gain of PHP 10.8 million versus a loss of PHP 0.8 million a year earlier. These factors increased pre-tax profit by 9% to PHP 4,745.3 million, while the tax burden remained low at PHP 345.2 million, or 7.3% of pre-tax profit.
However, the net margin improvement is not accompanied by better operating efficiency: gross margin declined as cost of sales rose 19% to PHP 5,801.3 million, outpacing revenue growth. The main contributors to cost growth were cost of real estate sales (+56%) and depreciation. This means the net margin improvement is financial rather than operational in nature.
Net profit over the last 12 months reached PHP 18,392.2 million, but EBITDA was only PHP 5,555.2 million, indicating low operating efficiency
Over the last twelve months, Robinsons Land earned PHP 18,392.2 million in net profit, but EBITDA was only PHP 5,555.2 million. The 3.3x gap is explained by the fact that net profit includes significant non-operating income, such as the gain from the sale of shares in subsidiary RCR, which in Q1 2026 brought PHP 6,917.4 million, recorded in equity rather than profit.
Operating profit (EBIT) in Q1 2026 was PHP 5,022.0 million, up 4% year-on-year. However, EBITDA for the same period fell to PHP 5,262.1 million from PHP 6,279.9 million in Q1 2025. This decline is due to higher depreciation and lease expenses.
Thus, the company generates significant net profit, but its operating cash generation remains weak. This poses a risk to dividend sustainability if non-operating income does not recur.
Operating cash flow for Q1 2026 reached PHP 7,219.1 million, yet over 12 months it lags behind profit
In Q1 2026, operating cash flow was PHP 7,219.1 million, up 40% from PHP 5,150.4 million a year earlier. The increase was driven by higher customer receipts and lower outflow on receivables. However, over the last twelve months, operating cash flow was PHP 16,700.0 million, which is 9.2% less than net profit for the same period (PHP 18,392.2 million).
The gap between profit and cash flow is partly explained by the fact that a significant portion of profit comes from non-operating items that do not generate cash. In addition, the company capitalises interest and has high depreciation charges, which reduce profit but do not affect cash flow.
Investing activities required PHP 2,089.3 million, mainly for capital expenditure on investment properties (PHP 1,933.8 million) and equipment (PHP 581.7 million). This means free cash flow after investments was about PHP 5,129.8 million, still below net profit.
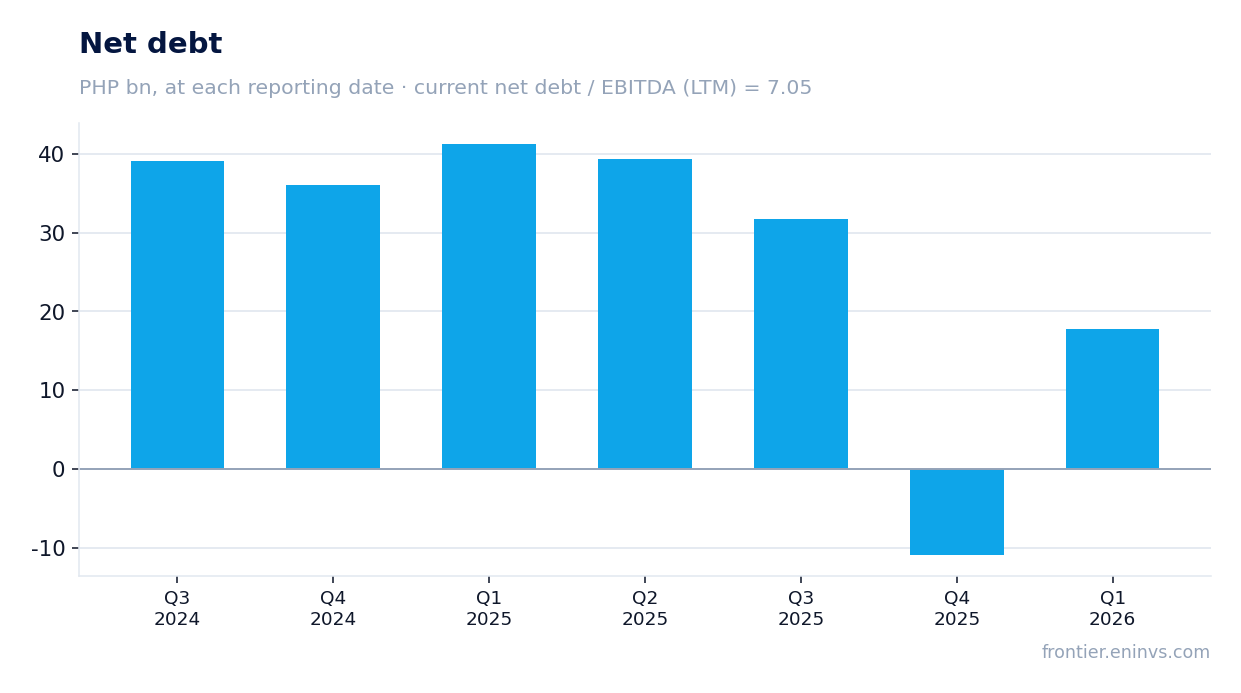
Leverage remains high: net debt to LTM EBITDA is 7.05, and net debt increased by PHP 17.8 billion in the quarter
Net debt at the end of Q1 2026 was PHP 39,175.8 million, up PHP 17.8 billion from the previous reporting date. The ratio of net debt to LTM EBITDA is 7.05. This is a high level that limits the company's financial flexibility.
Total debt rose to PHP 39,548 million, of which PHP 10,381.3 million is short-term and PHP 29,166.6 million is long-term. The company raised significant funds from the sale of RCR shares (PHP 6,917.4 million), which increased cash to PHP 21,716.9 million but also led to higher liabilities. Interest expenses fell 19% to PHP 429.0 million, but EBIT coverage remains comfortable at 8.48x.
High leverage combined with low operating profitability creates refinancing risk, especially if interest rates remain high. The company does not disclose its repayment schedule, but the current portion of debt accounts for 26% of the total.
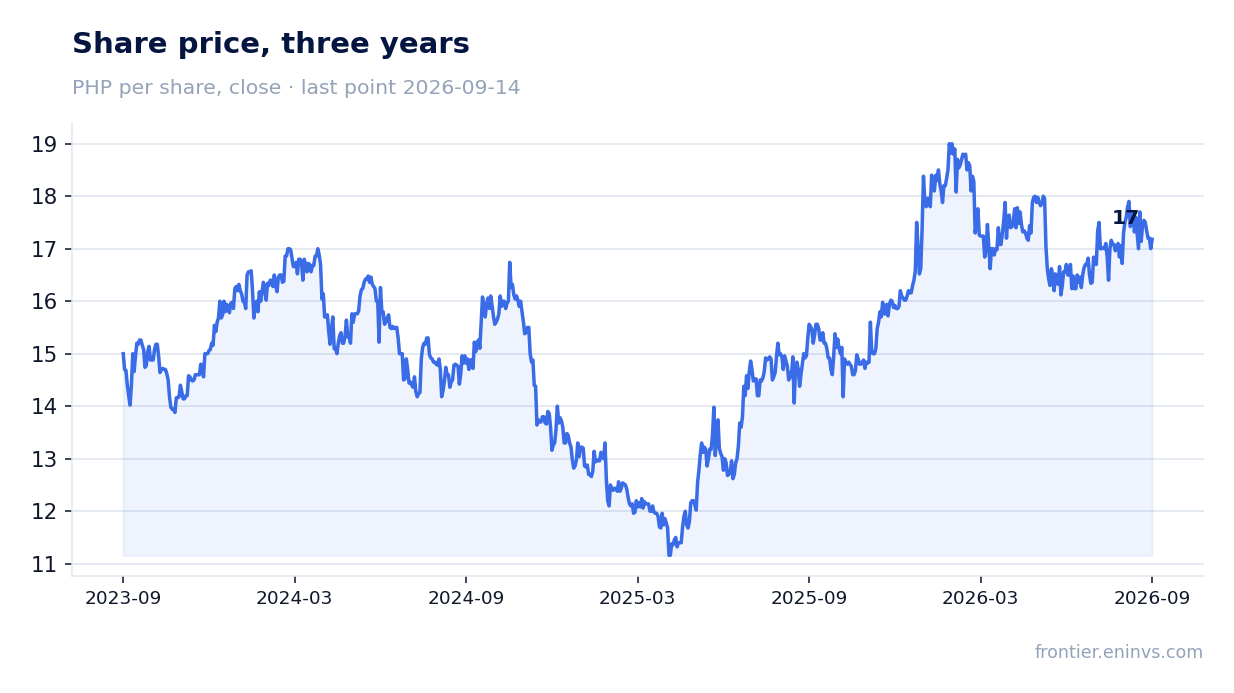
Dividend yield of 5.88% with a payout ratio of about 26% of LTM profit supports interest in the stock
Robinsons Land's dividend yield over the last twelve months is 5.88%. The company paid dividends of PHP 963.7 million in Q1 2026 and PHP 573.5 million a year earlier. With net profit over the last twelve months of PHP 18,392.2 million, the payout ratio is about 26%, leaving room for dividend increases.
However, dividend payments depend on cash flow, not accounting profit. Operating cash flow over the last twelve months was PHP 16,700.0 million, which covers dividends, but after capital expenditure (about PHP 2,500 million per quarter), free cash flow may be insufficient for significant payout growth.
Our estimate: if current profit and the payout ratio are maintained, the dividend for 2026 could be about PHP 1.0–1.1 per share, corresponding to a yield of 5.5–6.0% at the current price. This is close to the current level and does not imply significant growth. The key risk is a decline in non-operating income that supports profit.
The portal model's valuation implies a 38% downside to fair value, outweighing the low P/E of 4.44
Robinsons Land shares trade at a P/E of 4.44 and EV/EBITDA of 21.76. The low P/E is explained by high net profit, which includes significant non-operating income. EV/EBITDA, by contrast, is high because EBITDA is small relative to market value. According to the portal model, the fair value of the share is 38% below the current market price.
The company's market capitalisation is PHP 81,686.8 million, and net debt is PHP 39,175.8 million, giving an EV of about PHP 120,862.6 million. With LTM EBITDA of PHP 5,555.2 million, the EV/EBITDA multiple is 21.76. This is significantly above historical levels, indicating overvaluation relative to operating profit.
The dividend yield of 5.88% may attract investors, but it does not compensate for the risk of profit decline if one-off income does not recur. The portal model, based on EBITDA growth and a target multiple, implies negative upside, confirming a cautious view.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 81.7 bn PHP |
| P/E (LTM) | 4.4 |
| EV/EBITDA (LTM) | 21.8 |
| P/B | 0.51 |
| Net debt / EBITDA (LTM) | 7.05 |
| Operating cash flow (LTM) | 16.7 bn |
| ROE | 9.5% |
| Dividend yield (12m) | 5.9% |
Bottom line
Q1 2026 brought Robinsons Land revenue growth of 11.3% and net profit growth of 15.5%, but these results rely on non-operating income and lower interest expenses rather than improved operating efficiency. LTM EBITDA was only PHP 5,555.2 million against net profit of PHP 18,392.2 million, indicating low earnings quality. Leverage remains high, and the portal model implies a 38% downside. The dividend yield of 5.88% and low P/E of 4.44 support the price but do not provide a sufficient margin of safety. Verdict – neutral: the current price fairly reflects both strong dividend payments and the risks associated with the gap between profit and cash flow.
Open the company's financial profile RLC →
See also: market overview · valuation map · stock screeners