PLDT: revenue grows for a second quarter, but EBITDA halves on one-off items
On August 13, PLDT released its H1 2026 results. Half-year revenue rose 2% to PHP 112,006 million, with Q2 revenue up 2.2% year-on-year to PHP 55,493 million. However, Q2 net profit fell 16.4% to PHP 7,616 million, and the net margin dropped to 13.7% from 16.8% a year earlier. Half-year adjusted EBITDA grew 1% to PHP 56,050 million, but quarterly EBITDA was only PHP 13,361 million versus PHP 25,938 million a year ago. At the current price, the stock trades at 8.7x trailing 12-month earnings and 8.7x EBITDA, below historical levels, while the 8.0% dividend yield remains the main support. Verdict: neutral — the dividend and valuation are attractive, but the quarterly EBITDA collapse and rising debt require confirmation of business stability.
Key takeaways
— Revenue grows for a second quarter, but growth is driven mainly by non-core segments
— Quarterly EBITDA halved due to one-off items, not operational deterioration
— Q2 net profit fell 16.4%, and the margin compressed to 13.7%
— Debt rose to PHP 286.4 billion, with net debt/EBITDA LTM at 4.69x
— The 8.0% dividend yield remains the main support for the stock
— Valuation at 8.7x earnings and 8.7x EBITDA LTM is below historical levels
Attractiveness
Key figures, PHP bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 54.3 | 55.5 | +2.2% |
| EBITDA | 23.8 | — | — |
| Operating profit | 14.8 | 13.4 | -9.8% |
| Net profit | 9.11 | 7.62 | -16.4% |
| Operating cash flow | 22.2 | — | — |
| Capex | 17.9 | — | — |
| EBITDA margin | 43.9% | — | — |
| Net margin | 16.8% | 13.7% | -3.1 pp |
Revenue grows for a second quarter, but growth is driven mainly by non-core segments
Consolidated revenue for H1 2026 was PHP 112,006 million, up 2% from PHP 109,501 million a year earlier. Q2 revenue reached PHP 55,493 million, up 2.2% year-on-year. This is the second consecutive quarter of 2.2% year-on-year growth, following 2.2% in Q1 2026.
The wireless segment and device sales drove growth. Wireless revenue for the half-year rose 2% to PHP 52,292 million, while Fixed Line revenue fell 2% to PHP 65,897 million. Sales of devices and accessories increased to PHP 3,274 million from PHP 3,266 million a year earlier.
Within Fixed Line, dynamics were mixed: voice revenue rose to PHP 17,908 million from PHP 16,887 million, while data revenue fell to PHP 47,829 million from PHP 49,891 million. Corporate data and ICT declined to PHP 21,376 million from PHP 23,363 million, indicating weakness in the corporate segment.
Quarterly EBITDA halved due to one-off items, not operational deterioration
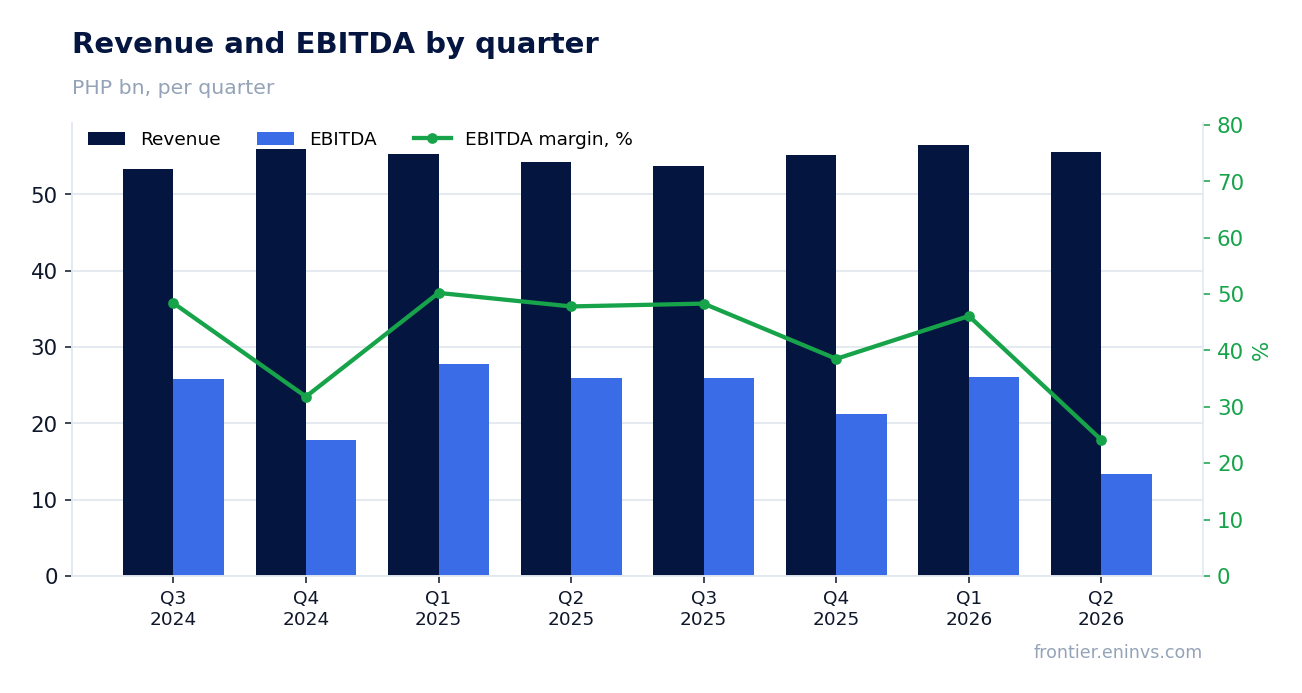
Adjusted EBITDA for H1 2026 was PHP 56,050 million, up 1% from PHP 55,250 million a year earlier. However, in the standalone second quarter, EBITDA was only PHP 13,361 million versus PHP 25,938 million in Q2 2025. This sharp decline contrasts with stable growth in Q1, where EBITDA was PHP 26,046 million.
The quarterly EBITDA drop is explained by one-off items in the financial statements. In H1 2026, the company recorded manpower rightsizing program (MRP) expenses of PHP 375 million, accelerated depreciation of PHP 668 million, and write-down of noncurrent assets of PHP 118 million. Additionally, the reporting period lacked the one-time gain from the sale and leaseback of towers, which amounted to PHP 942 million in H1 2025.
Operating profit in Q2 2026 was PHP 13,361 million, matching EBITDA, whereas a year earlier operating profit was PHP 14,819 million with EBITDA of PHP 25,938 million. This discrepancy indicates that depreciation and one-off write-downs were minimal in the reporting quarter, and the main pressure on EBITDA came from one-time factors.
Q2 net profit fell 16.4%, and the margin compressed to 13.7%
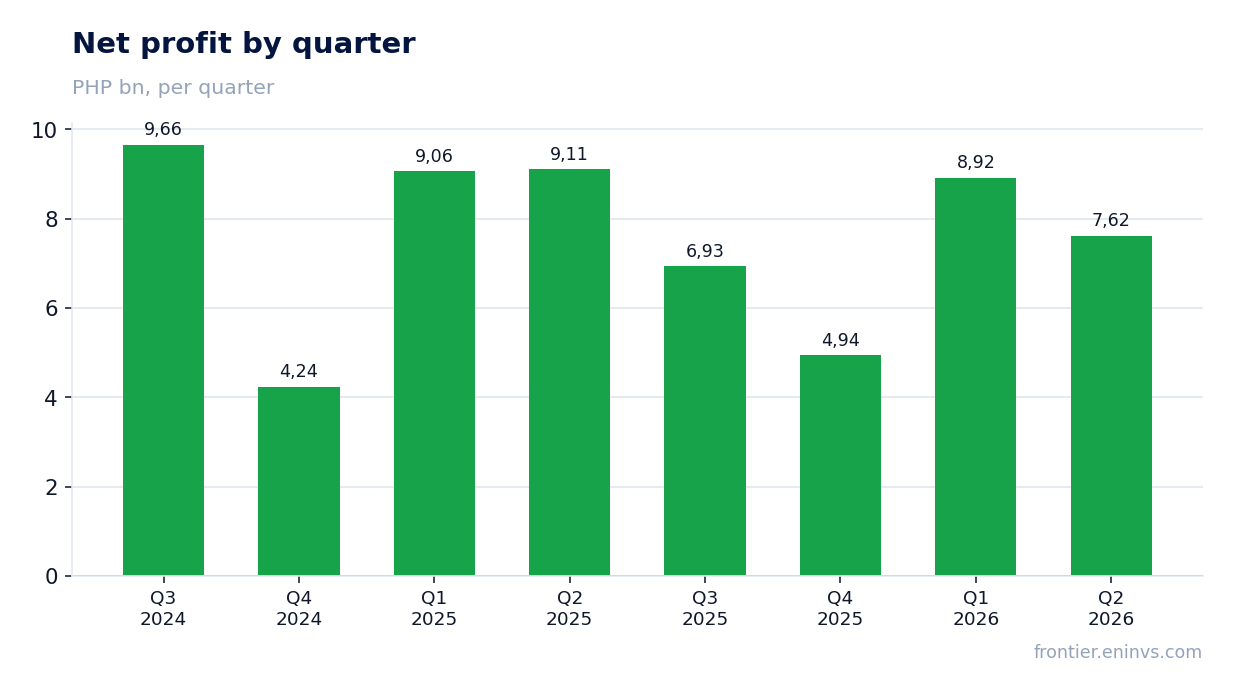
Q2 2026 net profit was PHP 7,616 million, down 16.4% from PHP 9,112 million in the same period of 2025. The net margin fell to 13.7% from 16.8% a year earlier. For H1, net profit was PHP 16,534 million versus PHP 17,513 million a year earlier, a 6% decline.
The profit decline is linked to higher expenses and the absence of one-off gains. Consolidated expenses for the half-year rose 4% to PHP 84,884 million, mainly due to higher depreciation, interconnection costs, and device costs. Other expenses net increased 7% to PHP 5,842 million due to net foreign exchange losses of PHP 1,365 million versus foreign exchange gains of PHP 1,406 million a year earlier.
Core income for the half-year remained virtually unchanged at PHP 17,329 million versus PHP 17,358 million a year earlier. This indicates that operational efficiency did not deteriorate, and the net profit decline was driven by volatile and one-off items.
Debt rose to PHP 286.4 billion, with net debt/EBITDA LTM at 4.69x
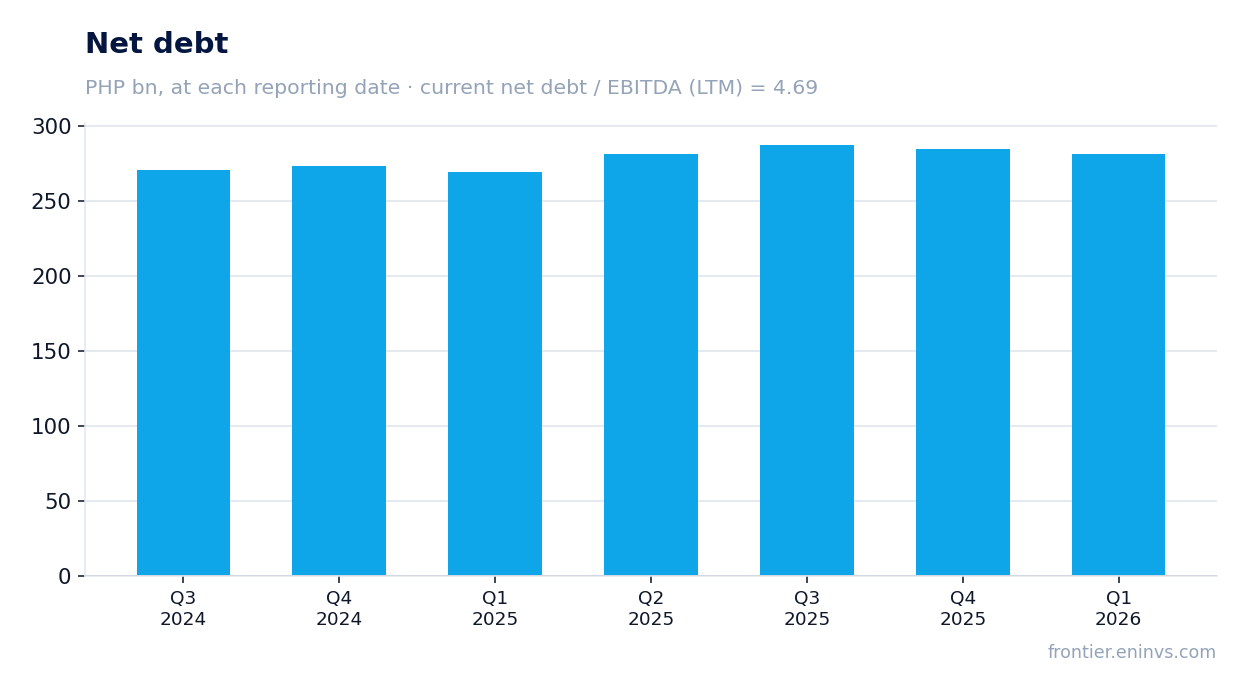
Net debt at the latest reporting date was PHP 286,396 million, up PHP 13.9 billion from the previous reporting date and up PHP 11.7 billion over the past 12 months. The net debt to EBITDA ratio for the trailing 12 months is 4.69x. This is a level that warrants attention, although the direction of the ratio change is not disclosed.
Operating cash flow for the trailing 12 months was PHP 98,700 million. Capital expenditures for the half-year fell 30% to PHP 23,736 million from PHP 34,078 million a year earlier, freeing up cash. However, debt continued to rise, which may be linked to financing investments and dividend payments.
Interest expenses remain significant: net financing costs for the half-year were PHP 8,723 million. At the current debt and EBITDA levels, debt servicing remains manageable, but further growth in leverage could limit financial flexibility.
The 8.0% dividend yield remains the main support for the stock
The trailing 12-month dividend yield is 7.99%. This is a high level that supports investor interest in the stock. The company has historically paid out a significant portion of earnings as dividends, and the current yield exceeds that of many fixed-income instruments.
Core income for the half-year was PHP 17,329 million, virtually in line with last year. This provides a basis for stable dividend payments. However, net profit declined, and if one-off factors persist, this could pressure future dividend payments.
The company's dividend policy targets a payout of at least 60% of core income. At the current price and a yield of 8.0%, the stock looks attractive for income-oriented investors. The main risk is a decline in profit, which could lead to a dividend cut.
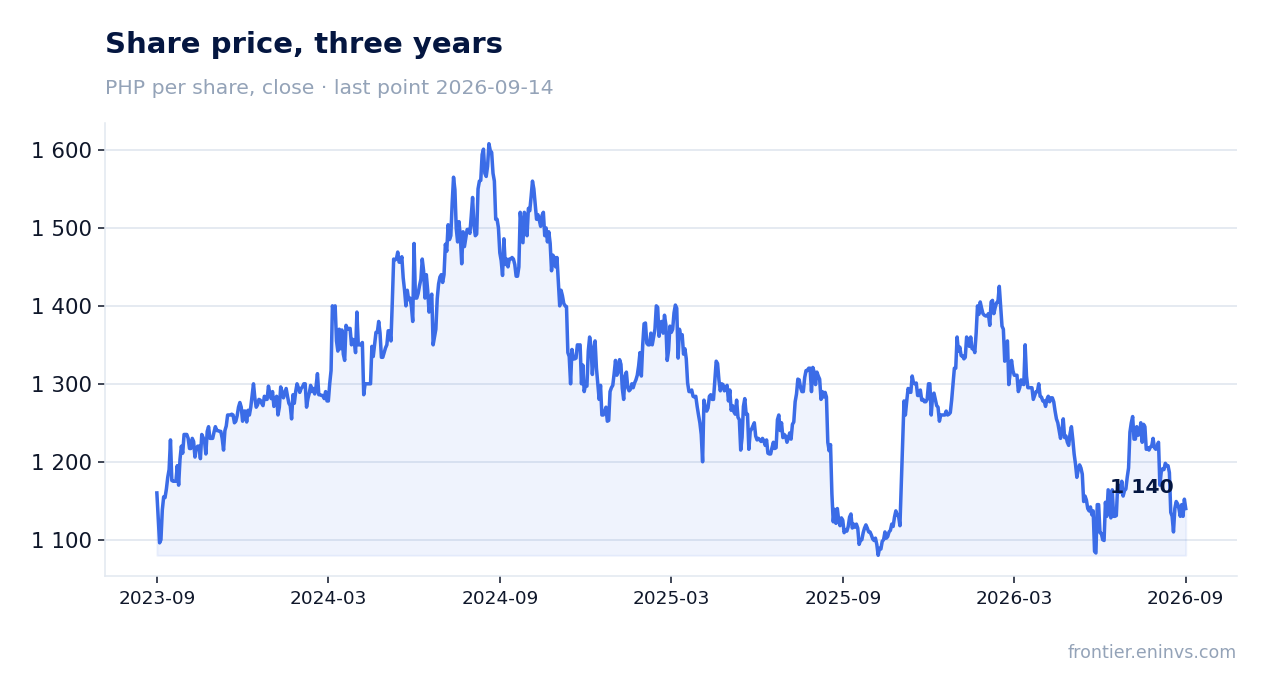
Valuation at 8.7x earnings and 8.7x EBITDA LTM is below historical levels
The trailing 12-month price-to-earnings ratio is 8.73x, and EV/EBITDA is 8.74x. These levels are below the company's historical averages, which may indicate undervaluation. Market capitalisation is PHP 248,032 million.
Return on equity (ROE) for the trailing 12 months is 23.2%, a high figure indicating efficient use of capital. However, the high ROE is partly due to significant debt, which increases financial risk.
According to the portal's model, the upside to fair value is +10%. This is the portal's own estimate, not a market consensus. The stock is held in the portal's live model strategies, Frontier AI Selection, reflecting its compliance with the selection criteria.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 248 bn PHP |
| P/E (LTM) | 8.7 |
| EV/EBITDA (LTM) | 8.7 |
| P/B | 1.94 |
| Net debt / EBITDA (LTM) | 4.69 |
| Operating cash flow (LTM) | 98.7 bn |
| ROE | 23.2% |
| Dividend yield (12m) | 8.0% |
Bottom line
PLDT delivered mixed results for H1 2026. Revenue grew for a second consecutive quarter, and core income remained stable, indicating the health of the core business. However, quarterly EBITDA halved due to one-off items, and net profit fell 16.4%. Debt rose to PHP 286.4 billion, with a net debt/EBITDA ratio of 4.69x. The 8.0% dividend yield and valuation at 8.7x trailing earnings make the stock attractive for income-oriented investors, but high debt and profit volatility warrant caution. Verdict: neutral — the current valuation and dividend compensate for risks, but a sustained increase in EBITDA without one-off factors is needed to improve attractiveness.
Open the company's financial profile TEL →
See also: market overview · valuation map · stock screeners