Altria: profit and EBITDA decline, but a 6.4% dividend yield holds the stock
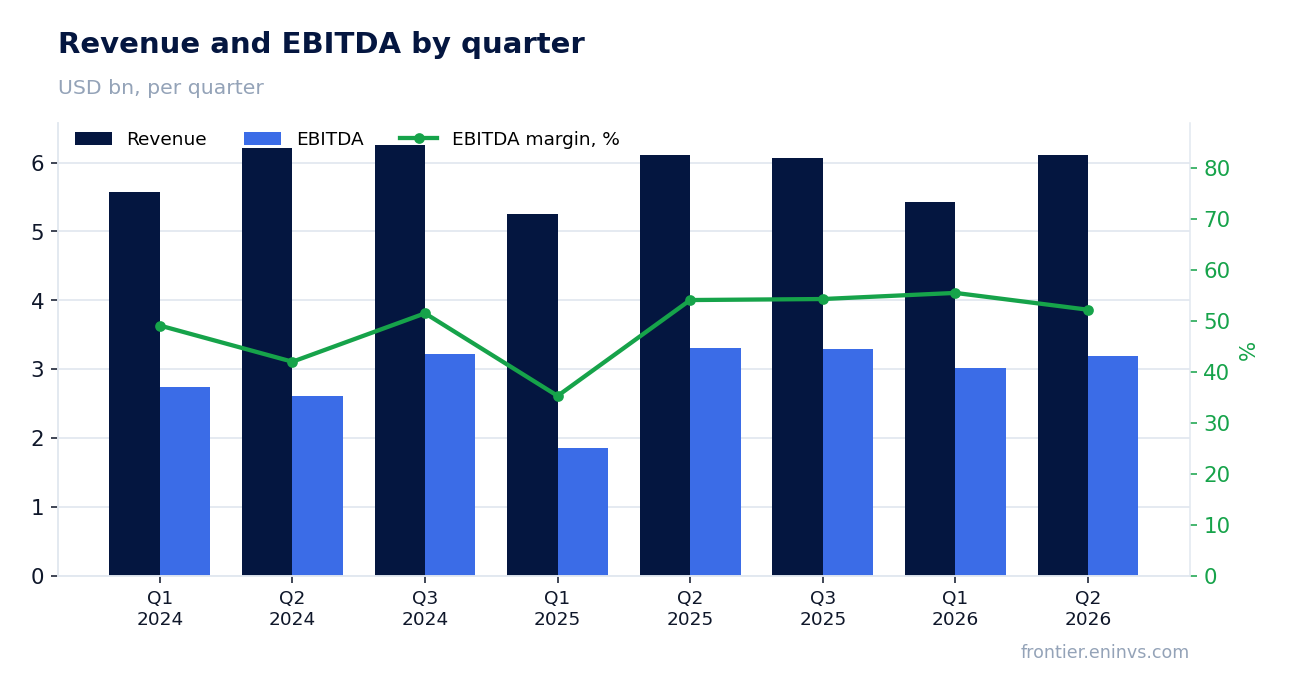
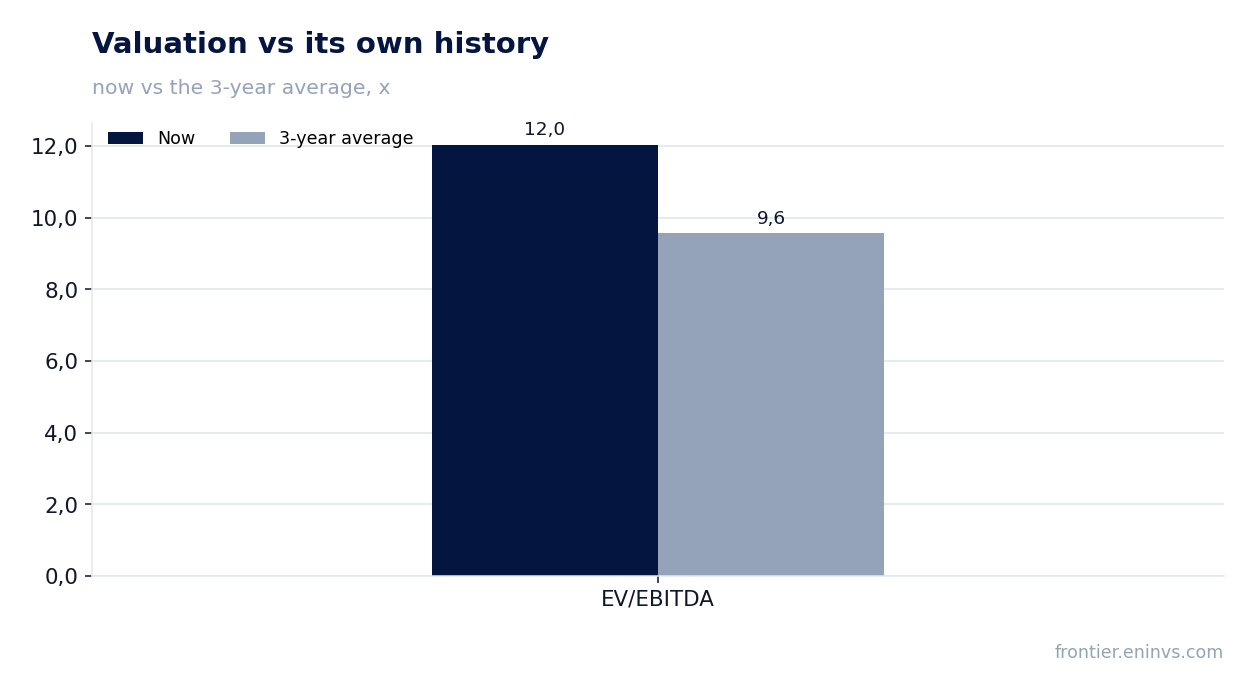
On July 30, Altria Group reported second-quarter 2026 results. Revenue was essentially flat at $6,111 million, up just 0.1% year on year, versus 3.2% growth in the prior quarter. EBITDA fell 3.3% to $3,192 million, and net profit declined 3.4% to $2,298 million. The stock trades at 12.0x EV/EBITDA against its own three-year average of 9.6x, while the trailing dividend yield is 6.4%. The assessment is neutral: the dividend and cash flow support the price, but decelerating revenue and margin pressure leave little room for upside.
Key takeaways
— Revenue growth decelerated to 0.1% – from 3.2% in the prior quarter
— EBITDA and net profit are declining, margin is compressing
— One-off charges and litigation costs weigh on reported profit
— Leverage at 2.0x LTM EBITDA is moderate, but debt rose over the quarter
— Free cash flow remains positive, but the quarter was weak
— A 6.4% dividend yield is the main support for investors
— Valuation is above its own history: EV/EBITDA 12.0x vs. 9.6x average
Attractiveness
Key figures, USD bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 6.10 | 6.11 | +0.1% |
| EBITDA | 3.30 | 3.19 | -3.3% |
| Operating profit | 3.23 | 3.14 | -2.9% |
| Net profit | 2.38 | 2.30 | -3.4% |
| Operating cash flow | 0.20 | 0.72 | +250.7% |
| Capex | 0.03 | 0.06 | +78.1% |
| EBITDA margin | 54.1% | 52.2% | -1.9 pp |
| Net margin | 39.0% | 37.6% | -1.4 pp |
Revenue growth decelerated to 0.1% – from 3.2% in the prior quarter
In the second quarter of 2026, Altria's revenue was $6,111 million, up just 0.1% year on year. This is a marked deceleration from the first quarter, when growth reached 3.2%. The main segment – smokeable products – saw revenue rise 0.7% to $5,392 million, while oral tobacco revenue fell 5.3% to $713 million.
Revenue was supported by higher pricing and growth in contract manufacturing of export cigarettes – shipment volume in that area rose 54.9%. However, these factors were almost entirely offset by lower shipment volumes and higher promotional spending. Smokeable segment volume declined 3.2%, while oral tobacco volume fell 8.5%.
The slowdown in revenue growth to 0.1% is a warning sign. The company is offsetting volume declines with price increases, but the scope for further price hikes is limited by pressure on consumer incomes and a rising share of discount brands. Without an acceleration in new products, such as oral nicotine pouches, returning to previous growth rates will be difficult.
EBITDA and net profit are declining, margin is compressing
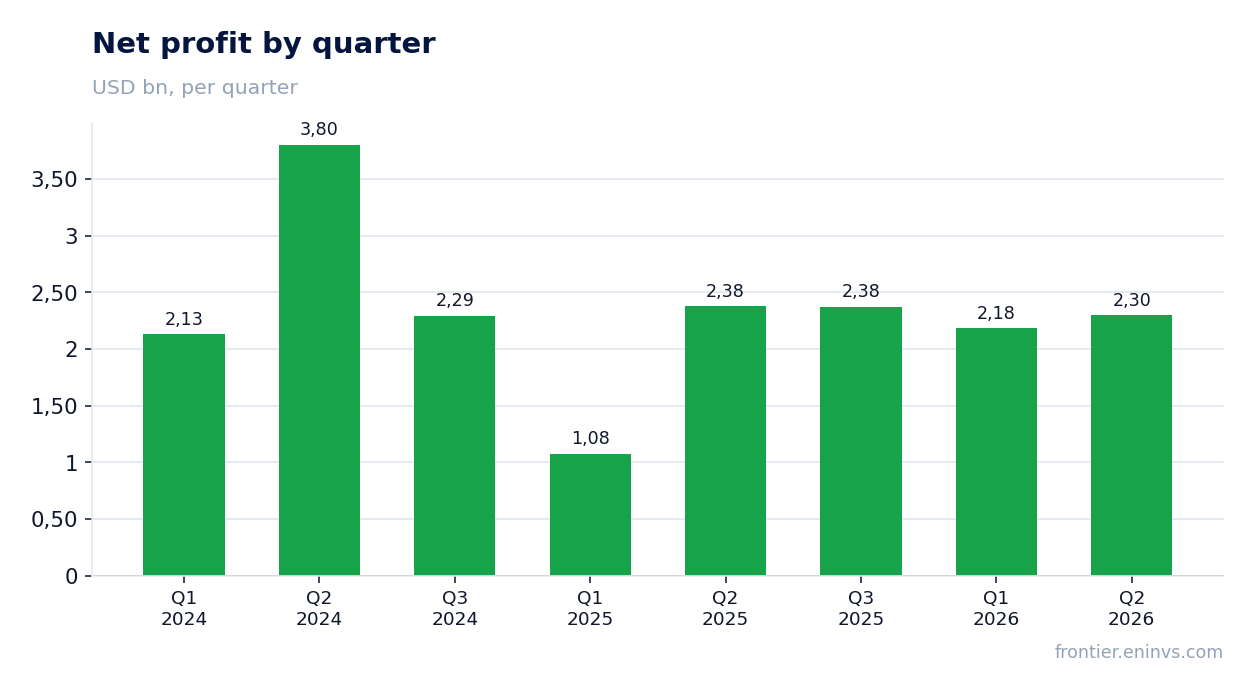
EBITDA for the second quarter of 2026 was $3,192 million, down 3.3% from a year earlier. The EBITDA margin fell to 52.2% from 54.1% a year earlier. Net profit declined 3.4% to $2,298 million, and the net margin fell to 37.6% from 39.0%.
The main reason for the margin decline is higher operating expenses. General corporate expenses rose to $87 million from $53 million a year earlier, while marketing, administration and research costs increased to $553 million from $529 million. In addition, the company incurred costs related to the consolidation of USSTC manufacturing facilities, resulting in $88 million in charges.
The decline in profit and margin is not solely due to one-off factors but also reflects pressure on operating efficiency. The company is investing in new products and optimisation, but so far these investments are not generating returns sufficient to maintain profit at previous levels.
One-off charges and litigation costs weigh on reported profit
Reported net profit for the second quarter of 2026 includes a number of one-off items that reduced it by $0.11 per share. In particular, tobacco and health litigation costs amounted to $95 million ($0.05 per share), while USSTC consolidation charges and write-offs were $88 million ($0.04 per share). Losses on ABI investments of $77 million ($0.04 per share) were also recorded.
Adjusted diluted earnings per share, by contrast, rose 2.8% to $1.48, driven by higher adjusted operating income and fewer shares outstanding. This suggests the underlying business remains profitable, but one-off factors significantly distort reported figures.
One-off charges and litigation costs are a constant backdrop for tobacco companies. In this quarter they were particularly noticeable, adding pressure to reported profit. Investors should focus on adjusted metrics, which better reflect the resilience of the business.
Leverage at 2.0x LTM EBITDA is moderate, but debt rose over the quarter
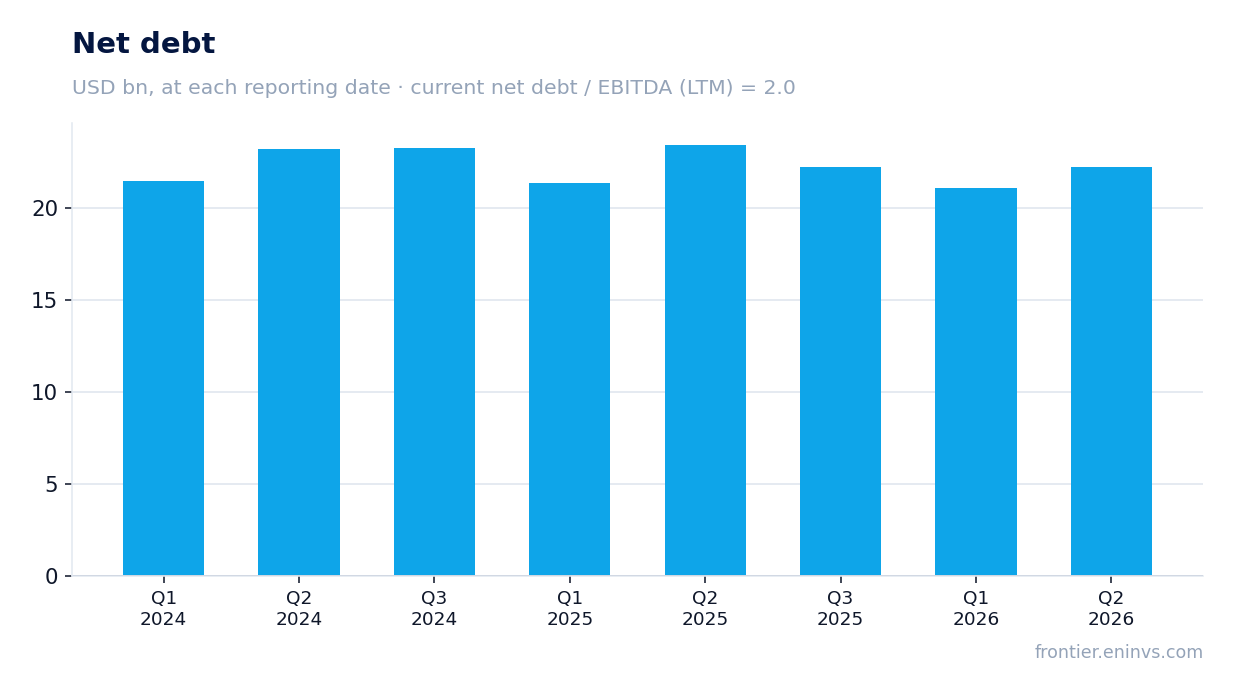
Altria's net debt as of June 30, 2026, was $22,210 million. The ratio of net debt to LTM EBITDA is 2.0. This is a moderate level for a company with stable cash flow. However, net debt increased over the quarter: from $21,071 million on March 31, 2026, to $22,210 million on June 30, 2026, a rise of $1.1 billion.
The increase in debt over the quarter is linked to dividend payments and share buybacks. The company paid $1.8 billion in dividends and spent $55 million on share repurchases. Operating cash flow for the quarter was only $719 million, which did not cover these payments.
A leverage level of 2.0x LTM EBITDA is not a cause for concern, but the trend of rising debt against weak cash flow warrants attention. If operating cash flow does not recover, the company may need to increase borrowings to sustain dividends.
Free cash flow remains positive, but the quarter was weak
Operating cash flow in the second quarter of 2026 was $719 million, significantly lower than in the first quarter ($2,324 million) and the second quarter of 2025 ($205 million). Capital expenditures were small at $57 million, so free cash flow remained positive at around $662 million.
The weak operating cash flow in the quarter is explained by an increase in working capital and one-off payments, including litigation and consolidation costs. The company confirmed its 2026 capital expenditure guidance of $375–450 million, up from the previous forecast of $300–375 million.
Despite the quarterly decline, operating cash flow over the last 12 months was $9,408 million, which comfortably covers dividends and capital expenditures. However, the weak quarter highlights the vulnerability of cash flow to one-off factors.
A 6.4% dividend yield is the main support for investors
Altria paid $1.8 billion in dividends in the second quarter and $3.6 billion in the first half of 2026. The trailing 12-month dividend yield is 6.4%. This is one of the highest among large companies and significantly above current deposit rates.
The company confirmed its 2026 adjusted diluted EPS guidance of $5.61–$5.72, implying growth of 3.5–5.5% from a base of $5.42 in 2025. At the current annual dividend of about $4.08 per share, the payout ratio is approximately 73% of projected earnings. This is a high but sustainable level for a tobacco company.
The main risk to the dividend is a further decline in profit and cash flow. If adjusted earnings fall short of guidance, the company may maintain the dividend, but the payout ratio would rise, limiting room for increases. Nevertheless, the current 6.4% yield makes the stock attractive for income-oriented investors.
Valuation is above its own history: EV/EBITDA 12.0x vs. 9.6x average
Based on the trailing 12-month EV/EBITDA multiple, Altria trades at 12.0x, above its own three-year average of 9.6x. This means the market values the company more highly than its average over the past three years, despite declining profit and margin. The LTM P/E is 14.1x.
Our fundamental valuation model, based on EBITDA growth and a target multiple, implies only +4% upside to fair value. This is a modest figure that does not compensate for the risks associated with decelerating revenue and margin pressure.
The current valuation looks inflated relative to its own history. To justify a 12.0x multiple, the company needs to return to EBITDA growth, but current dynamics are the opposite. If EBITDA continues to decline next quarter, the multiple could correct downward, putting pressure on the share price.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 113 bn USD |
| P/E (LTM) | 14.1 |
| EV/EBITDA (LTM) | 12.0 |
| Net debt / EBITDA (LTM) | 2.00 |
| Operating cash flow (LTM) | 9.41 bn |
| ROE | -226.0% |
| Dividend yield (12m) | 6.4% |
| EV/EBITDA, 3-year average | 9.6 |
Bottom line
In the second quarter of 2026, Altria showed virtually zero revenue growth (+0.1%) and a 3.3% decline in EBITDA and a 3.4% decline in net profit. Adjusted EPS rose 2.8%, but this was achieved through share count reduction and one-off factors. The 6.4% dividend yield remains the main support for investors, but the valuation at 12.0x EV/EBITDA versus the three-year average of 9.6x looks inflated. The portal's model implies only +4% upside. The question for a holder now is whether the company can return to EBITDA growth to justify the current multiple, or whether the dividend will remain the only source of return.
Open the company's financial profile MO →
See also: market overview · valuation map · stock screeners