UZ_TRUST: profit up by a third, but revenue growth has slowed for a fourth straight quarter
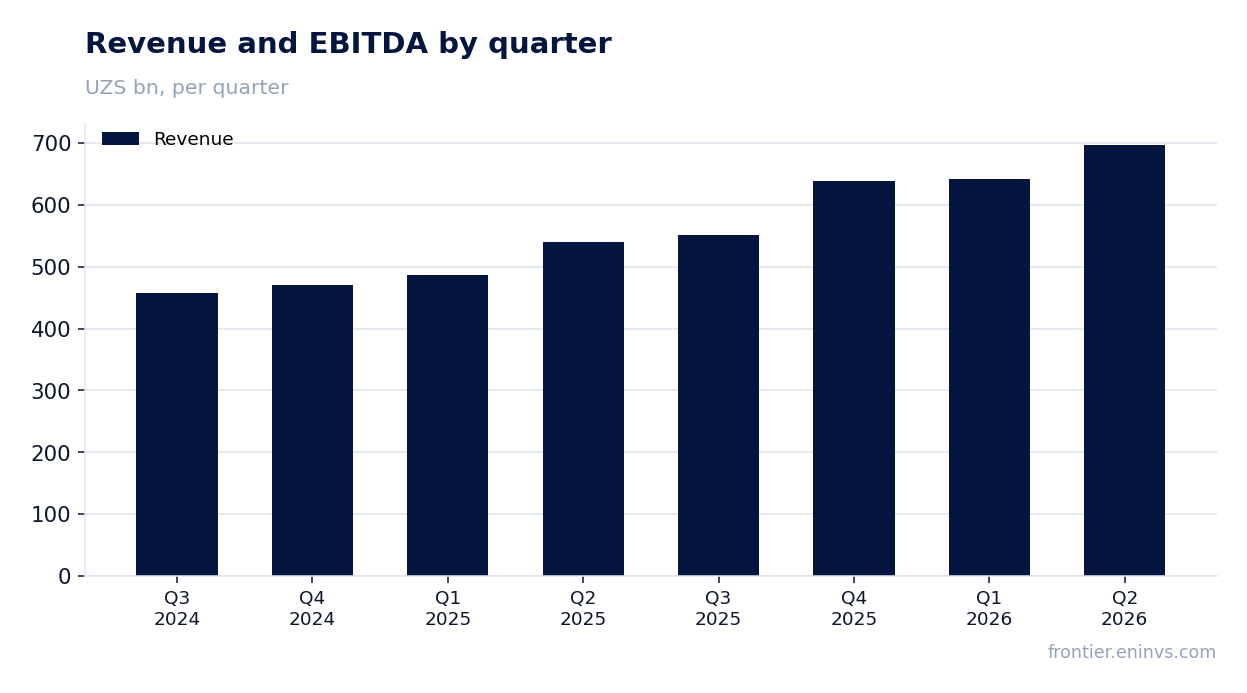
On 25 August UZ_TRUST reported results for the second quarter of 2026. Revenue rose 29.0% year on year to UZS 697,436.1 mn, net profit was up 34.5% to UZS 271,123.3 mn, and the net margin improved to 38.9% from 37.3% a year earlier. Revenue growth, however, has slowed for a fourth consecutive quarter, from 35.7% in the fourth quarter of 2025 to 29.0% now. The stock trades at 12.4 times trailing twelve-month earnings with a 28.2% return on equity and a 6.1% dividend yield; on the portal's model the upside to fair value is 9%. We see the share as rather attractive: profitability and the dividend outweigh the revenue slowdown, but confirmation of the valuation requires that trend to turn.
Key takeaways
— Revenue rose 29.0% year on year but has slowed for a fourth straight quarter
— The net margin rose to 38.9% – profit is growing faster than revenue
— Return on equity of 28.2% against a multiple of 12.4 times trailing earnings
— A 6.1% dividend yield – more than a deposit can offer
— On the portal's model the share is 9% undervalued versus fair value
Attractiveness
Key figures, UZS bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 541 | 697 | +29.0% |
| Operating profit | — | 289 | — |
| Net profit | 202 | 271 | +34.5% |
| Net margin | 37.3% | 38.9% | +1.6 pp |
Revenue rose 29.0% year on year but has slowed for a fourth straight quarter
In the second quarter of 2026 revenue reached UZS 697,436.1 mn, up 29.0% year on year. That is a strong result in itself, but growth has decelerated for a fourth consecutive quarter: in the fourth quarter of 2025 revenue was growing at 35.7%, in the first quarter of 2026 at 32.2%, now at 29.0%. The slowdown is sequential and persistent, not a one-off fluctuation.
The absolute quarter-on-quarter increase also narrowed: while in the first quarter of 2026 revenue rose by UZS 54,870 mn from the previous quarter, in the second it added UZS 54,866 mn. This means the company is not accelerating but stabilising at a new level. For an investor it is important to understand where the saturation point lies: if the slowdown continues, the valuation could prove stretched.
Over the trailing twelve months revenue amounted to UZS 1,404,400.0 mn. This figure covers four quarters and is not a reported-period metric – it cannot be compared with second-quarter growth. But it shows the scale of the business and the base for future growth rates.
The net margin rose to 38.9% – profit is growing faster than revenue
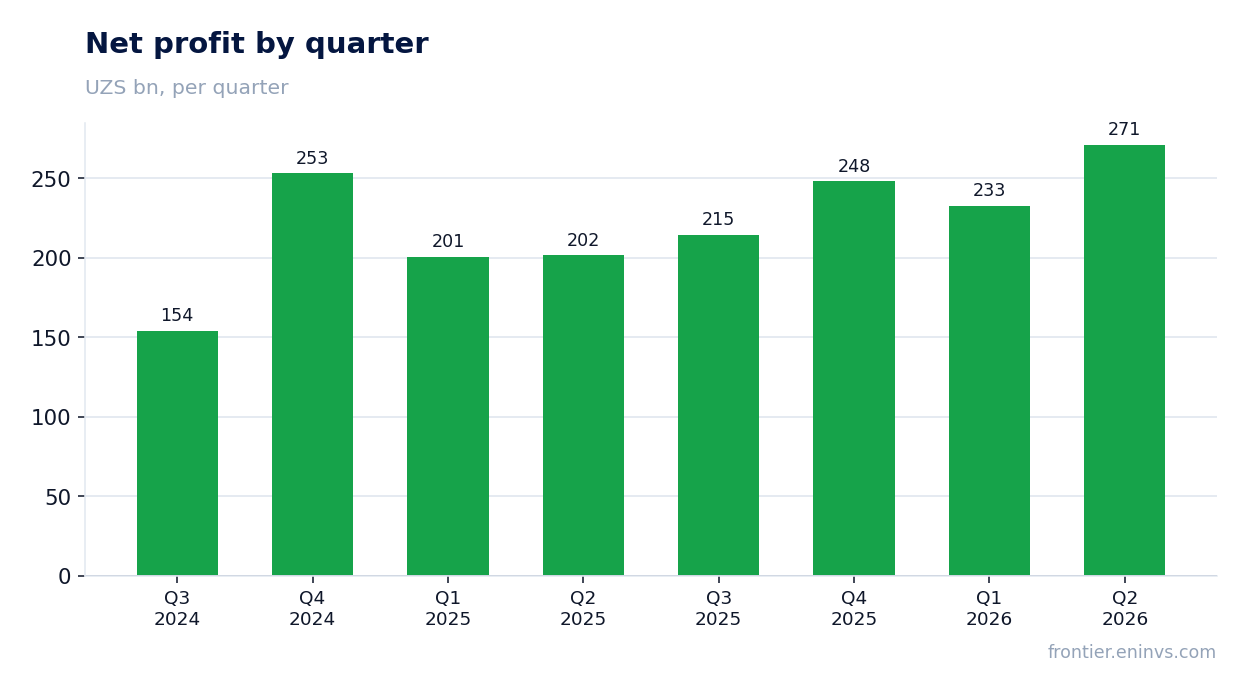
Net profit in the second quarter of 2026 came to UZS 271,123.3 mn, up 34.5% year on year. That is faster than revenue growth, which drove the margin expansion from 37.3% a year earlier to 38.9%. The company is not just growing turnover but doing so more efficiently.
Operating profit for the quarter was UZS 289,154.0 mn. It exceeds net profit, indicating a low tax burden or an absence of large one-off charges below the operating line. The gap between operating and net profit is about UZS 18 bn – a moderate level that does not distort the picture.
Over the trailing twelve months net profit reached UZS 966,649.7 mn. This sum also relates to the trailing period and should not be mixed with quarterly figures. Return on equity (ROE) over the same period is 28.2%, confirming the company's ability to generate profit on invested capital.
Return on equity of 28.2% against a multiple of 12.4 times trailing earnings
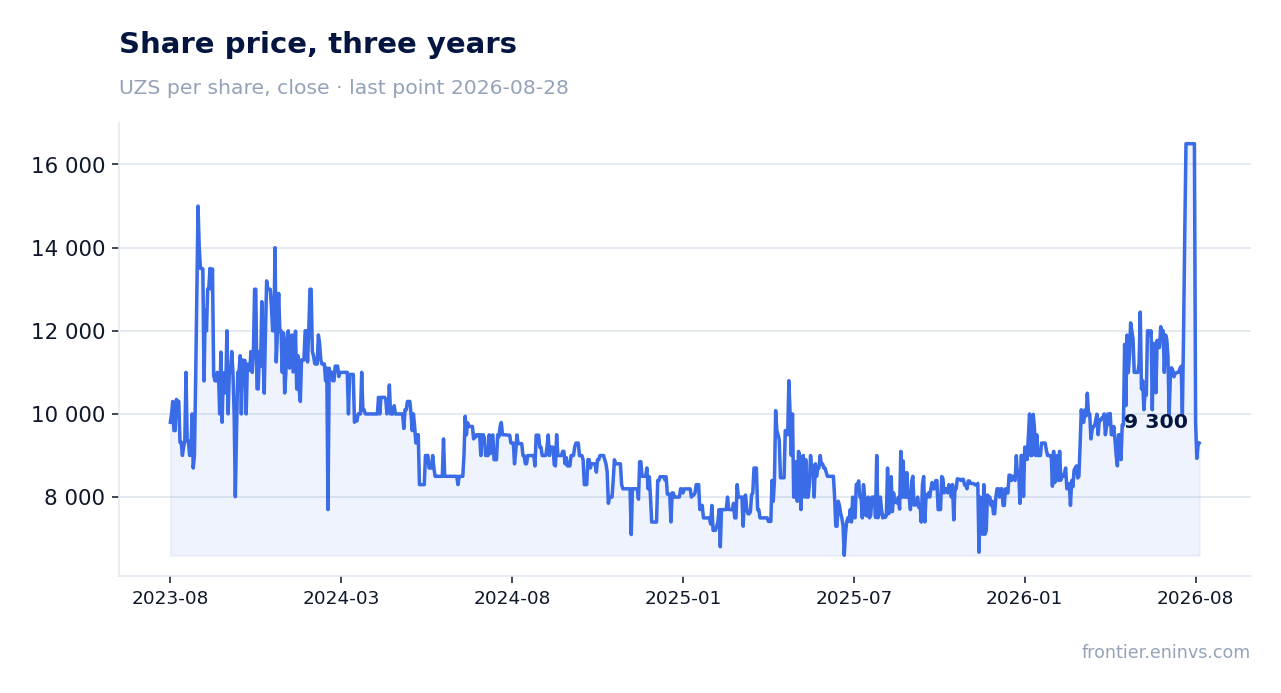
The price-to-earnings ratio for the trailing twelve months (P/E LTM) is 12.4. That is a moderate valuation for a company with a 28.2% return on equity. If profit is sustainable, the investor gets an earnings yield close to 8% (the inverse of P/E), comparable to long-term bonds but with growth potential.
A comparison of the current multiple with its three-year average is not possible: the FACTS contain no historical P/E values. However, the combination of 28.2% ROE and 12.4 P/E looks balanced – the market is not overpaying for growth, but it is not ignoring the quality of the business either. If the revenue slowdown continues, the multiple could compress, and then the current price would not look so low.
On the portal's model, which compares return on equity with the price-to-book ratio, the fair value of the share is 9% above the current market price. This is our own estimate, not a market consensus. It assumes that current profitability persists, which means the revenue slowdown is the main risk to this calculation.
A 6.1% dividend yield – more than a deposit can offer
The dividend yield over the trailing twelve months is 6.1%. That is above current bank deposit rates in Uzbekistan, making the share attractive for income-oriented investors. Payouts appear regular, and the company shares a significant portion of its profit.
Based on the payout ratio, which can be estimated from the relationship between dividends and profit, the company distributes a substantial share of net profit. If profit for 2026 remains at the trailing twelve-month level (UZS 966,649.7 mn), the dividend base will stay stable. However, the exact payout for the current year depends on the board's decision and could be adjusted if capital expenditure rises or market conditions deteriorate.
A yield of 6.1% is not a record for the market, but it noticeably exceeds the risk-free rate. If the company maintains profit at the current level, the dividend stream will remain attractive. The risk is that a slowdown in revenue could lead to lower profit and, consequently, a smaller dividend.
On the portal's model the share is 9% undervalued versus fair value
Our model, which compares return on equity with the price-to-book ratio, gives a fair value 9% above the current market price. This is not a consensus forecast or a target price, but the result of a calculation based on current ROE and P/B. If profitability persists, the share could rise to that level.
However, the model is sensitive to the sustainability of profit. If the revenue slowdown leads to a lower ROE, fair value will also decline. Therefore, the 9% cushion is more of a moderate buffer than a significant undervaluation. To confirm the valuation, we need to see revenue growth stabilise in the next quarter.
A comparison with the company's historical multiples is not possible due to the absence of data in the FACTS. But the current P/E of 12.4 and ROE of 28.2% look balanced. If the company returns to revenue growth above 30%, the multiple could expand, and then the upside would be greater than 9%.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 12 001 bn UZS |
| P/E (LTM) | 12.4 |
| P/B | 4.11 |
| ROE | 28.2% |
| Dividend yield (12m) | 6.1% |
Bottom line
Bottom line: UZ_TRUST delivered a strong quarter – profit rose 34.5%, the margin improved to 38.9%, and the 6.1% dividend yield remains attractive. However, the fourth consecutive quarter of slowing revenue growth is a warning signal that could cap further gains. The valuation at 12.4 times earnings and 28.2% ROE looks balanced, while the portal's model points to 9% upside. We see the share as rather attractive for investors willing to tolerate the slowdown risk, but confirmation of the valuation requires a turnaround in revenue dynamics.
Open the company's financial profile TRUST →
See also: market overview · valuation map · stock screeners