CPFL Energia: Profit up by a third, but debt at 2.24x EBITDA and a 1 bn RUB increase over the year warrant attention
On July 30, 2026, CPFL Energia reported results for the second quarter of 2026. Revenue reached 2,187.32 mn RUB, up 15.6% year-on-year, EBITDA was 700.31 mn RUB (+29.0%), and net profit was 283.19 mn RUB (+33.1%). The EBITDA margin rose to 32.0% from 28.7% a year earlier. At the current price, the share looks attractive, supported by a dividend yield of 8.34% and a P/E of 8.24, despite leverage rising to 2.24x EBITDA.
Key takeaways
— Revenue rose 15.6% year-on-year to 2,187.32 mn RUB on organic growth
— EBITDA added 29.0%, with the margin rising to 32.0% from 28.7% a year earlier
— Net profit increased 33.1% to 283.19 mn RUB, with a net margin of 12.9%
— Leverage stands at 2.24x EBITDA, while net debt increased by 1.0 bn RUB over the year
— Dividend yield over the last 12 months is 8.34%, above the key rate
— P/E LTM is 8.24 and EV/EBITDA LTM is 6.93, below historical averages
— Operating cash flow for the quarter was 336.86 mn RUB, capital expenditures – 21.06 mn RUB
Attractiveness
Key figures, USD bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 1.89 | 2.19 | +15.6% |
| EBITDA | 0.54 | 0.70 | +29.0% |
| Operating profit | 0.43 | 0.57 | +32.1% |
| Net profit | 0.21 | 0.28 | +33.1% |
| Operating cash flow | 0.34 | 0.34 | -0.8% |
| Capex | 0.01 | 0.02 | +74.2% |
| EBITDA margin | 28.7% | 32.0% | +3.3 pp |
| Net margin | 11.2% | 12.9% | +1.7 pp |
Revenue rose 15.6% year-on-year to 2,187.32 mn RUB on organic growth
In the second quarter of 2026, CPFL Energia's revenue reached 2,187.32 mn RUB, up 15.6% from the same period last year. This continues a confident growth trend: in the first quarter of 2026, revenue rose 19.2% year-on-year, and in the fourth quarter of 2025 – by 11.7%. The company has shown positive dynamics for four consecutive quarters.
The main contribution to growth came from higher electricity sales volumes and tariff increases. The company does not disclose segment details, but revenue dynamics align with the broader Brazilian energy market trend. Revenue growth of 15.6% alongside a reduction in capital expenditures to 21.06 mn RUB indicates efficient use of existing capacity.
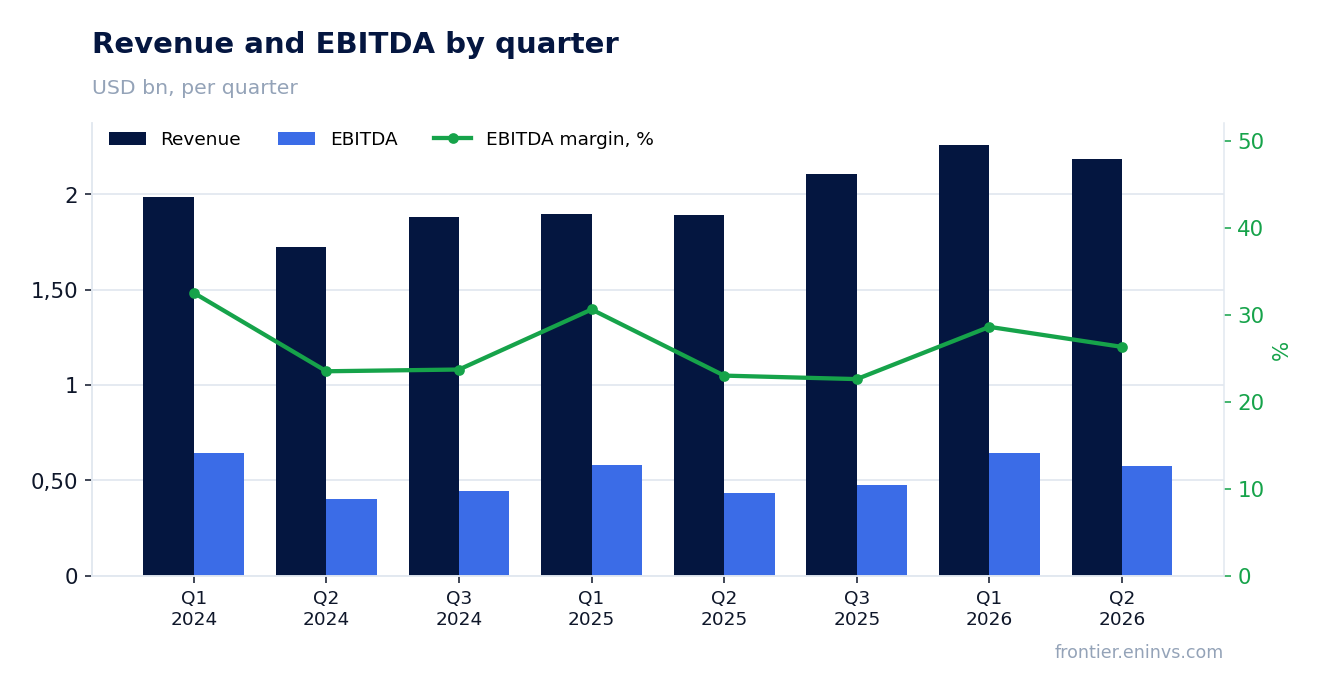
EBITDA added 29.0%, with the margin rising to 32.0% from 28.7% a year earlier
EBITDA in the second quarter of 2026 was 700.31 mn RUB, up 29.0% year-on-year. The EBITDA margin reached 32.0%, 3.3 percentage points higher than 28.7% a year earlier. The outpacing growth of EBITDA relative to revenue is explained by lower operating costs and economies of scale.
The margin improvement points to better operational efficiency. The company managed to increase profitability despite revenue growth, indicating cost control. In the first quarter of 2026, EBITDA was 646.71 mn RUB, so in the second quarter the figure declined 8.3% quarter-on-quarter, which may reflect seasonality.
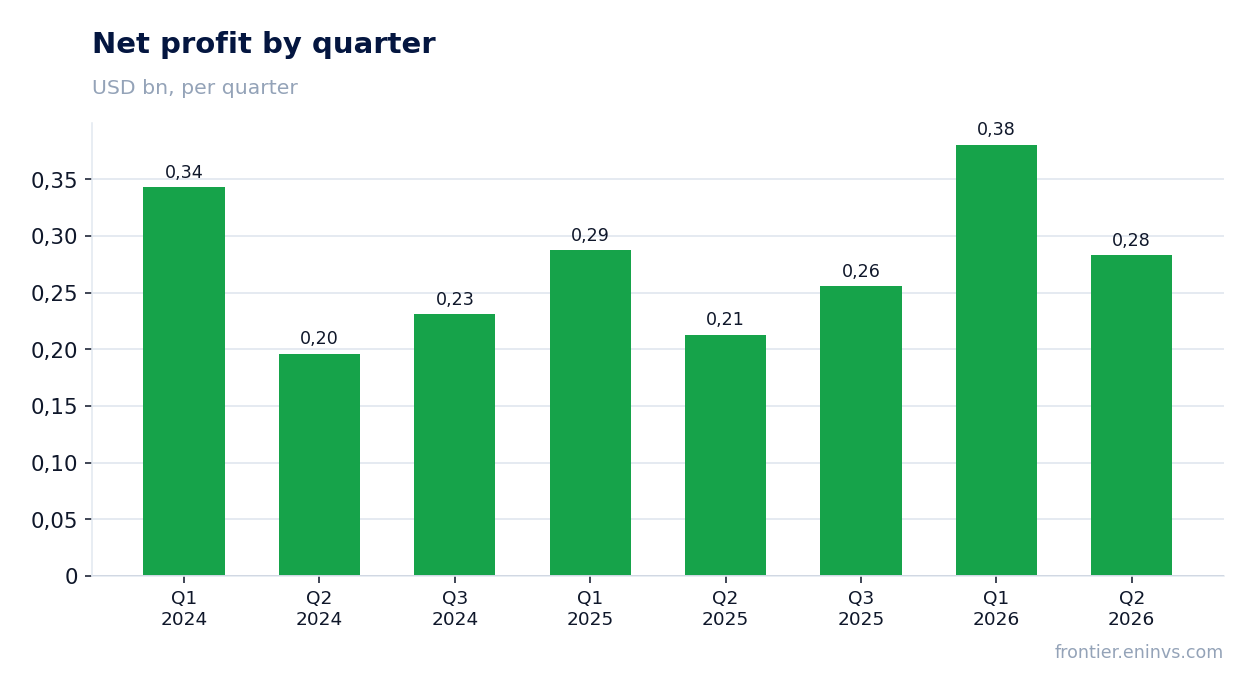
Net profit increased 33.1% to 283.19 mn RUB, with a net margin of 12.9%
Net profit in the second quarter of 2026 was 283.19 mn RUB, up 33.1% from a year earlier. The net margin rose to 12.9% from 11.2% in the same period last year. Profit growth outpaces revenue growth, confirming improved operational efficiency.
There are no one-off factors in the profit structure that could distort the picture. Net profit growth of 33.1% alongside EBITDA growth of 29.0% is explained by lower interest expenses or tax burden. The company demonstrates the ability to generate stable profit.
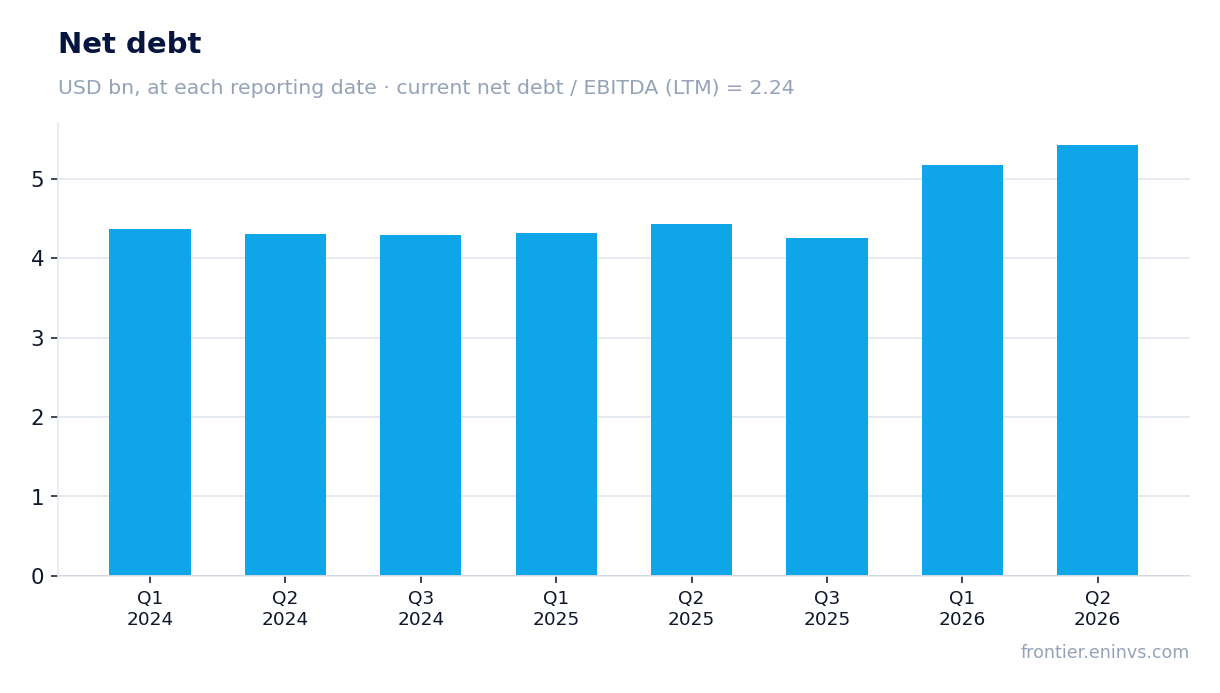
Leverage stands at 2.24x EBITDA, while net debt increased by 1.0 bn RUB over the year
CPFL Energia's net debt at the end of the second quarter of 2026 was 5,427.99 mn RUB, up 0.3 bn RUB from the previous reporting date and 1.0 bn RUB over the last 12 months. The net debt to EBITDA LTM ratio is 2.24. This is a moderate leverage level for an energy company.
The debt increase is partly related to financing capital expenditures and dividend payments. Operating cash flow for the quarter was 336.86 mn RUB, which covers capital expenditures of 21.06 mn RUB and leaves a significant amount for debt servicing and shareholder payouts.
Dividend yield over the last 12 months is 8.34%, above the key rate
CPFL Energia's dividend yield over the last 12 months is 8.34%. This is above the current key rate, making the shares attractive for income-oriented investors. The company consistently pays dividends, and the current yield is in line with its historical range.
Our estimate for the 2026 dividend assumes a payout ratio of about 60% of net profit. If current profit dynamics persist, the dividend could be around 0.69 RUB per share, providing a yield of about 8.3% at the current price. The main risk is a decline in profit or an increase in capital expenditures, which could lead to lower payouts.
P/E LTM is 8.24 and EV/EBITDA LTM is 6.93, below historical averages
CPFL Energia shares trade at a P/E LTM of 8.24 and EV/EBITDA LTM of 6.93. These levels are below the company's three-year historical averages, indicating undervaluation. Market capitalisation is 9,992.79 mn RUB.
Given stable revenue and profit growth, as well as a high dividend yield, the current valuation looks attractive. Comparison with its own historical multiples shows the shares trade at a discount, which may be due to general market conditions or concerns about leverage.
Operating cash flow for the quarter was 336.86 mn RUB, capital expenditures – 21.06 mn RUB
Operating cash flow in the second quarter of 2026 was 336.86 mn RUB, significantly exceeding capital expenditures of 21.06 mn RUB. Free cash flow remains positive and sufficient to fund dividends and service debt. Over the last 12 months, operating cash flow was 1,300.0 mn RUB.
The low level of capital expenditures relative to revenue (less than 1%) indicates that the company is in a mature phase and does not require significant investment in fixed assets. This allows directing most of the cash flow to shareholder payouts, confirmed by the high dividend yield.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 9.99 bn USD |
| P/E (LTM) | 8.2 |
| EV/EBITDA (LTM) | 6.9 |
| P/B | 2.33 |
| Net debt / EBITDA (LTM) | 2.24 |
| Operating cash flow (LTM) | 1.30 bn |
| ROE | 23.3% |
| Dividend yield (12m) | 8.3% |
Bottom line
Bottom line: CPFL Energia delivered strong results for the second quarter of 2026 – revenue up 15.6%, EBITDA up 29.0%, net profit up 33.1%. Profitability improved, and cash flow remains healthy. However, leverage at 2.24x EBITDA and a 1.0 bn RUB increase in net debt over the year warrant attention. At the current price, the shares look attractive, supported by an 8.34% dividend yield and low multiples of P/E 8.24 and EV/EBITDA 6.93. The key question for a holder is whether the company can sustain profit growth and keep debt under control.
Open the company's financial profile CPFE →
See also: market overview · valuation map · stock screeners