TIM S.A.: revenue grows, but profit is flat — and the valuation leaves no room
On August 25, TIM S.A. released its results for the second quarter of 2026. Revenue grew 5.5% year on year, EBITDA rose 4.9%, but net profit fell 0.6%. At the current price, the share looks rather unattractive: multiples are above its own history, and the dividend yield does not compensate for the valuation.
Key takeaways
— Revenue in the second quarter grew 5.5% year on year to $1,245.1 million, but quarterly dynamics slowed from 6.5% to 5.5%
— EBITDA margin in the second quarter was 50.4%, 0.4 p.p. lower than a year earlier
— Net profit for the quarter fell 0.6% year on year to $173.3 million, while quarterly profit rose from $146.1 million in the first quarter
— Operating cash flow for the quarter rose to $556.9 million, but capital expenditures of $167.1 million leave a significant free flow
— Net debt at the end of the quarter was minus $5.0 million, meaning the company remains a net creditor
— Dividend yield over the last 12 months is 1.67%, below the key rate and not attractive given the valuation
— On the portal's model, the upside of the share is only +3%, indicating a fair valuation without a margin of safety
Attractiveness
Key figures, USD bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 1.18 | 1.25 | +5.5% |
| EBITDA | 0.60 | 0.63 | +4.9% |
| Operating profit | 0.28 | 0.31 | +9.1% |
| Net profit | 0.17 | 0.17 | -0.6% |
| Operating cash flow | 0.53 | 0.56 | +4.9% |
| Capex | 0.16 | 0.17 | +6.0% |
| EBITDA margin | 50.8% | 50.4% | -0.4 pp |
| Net margin | 14.8% | 13.9% | -0.9 pp |
Revenue in the second quarter grew 5.5% year on year to $1,245.1 million, but quarterly dynamics slowed from 6.5% to 5.5%
In the second quarter of 2026, TIM S.A.'s revenue amounted to $1,245.1 million, up 5.5% year on year. In the first quarter, growth was 6.5%, meaning the pace slowed by 1 p.p. Over the last 12 months, revenue reached $4,900.0 million.
The slowdown is not critical, but it is noticeable against the previous quarter. The company continues to grow, but the growth drivers, judging by the dynamics, are gradually exhausting themselves.
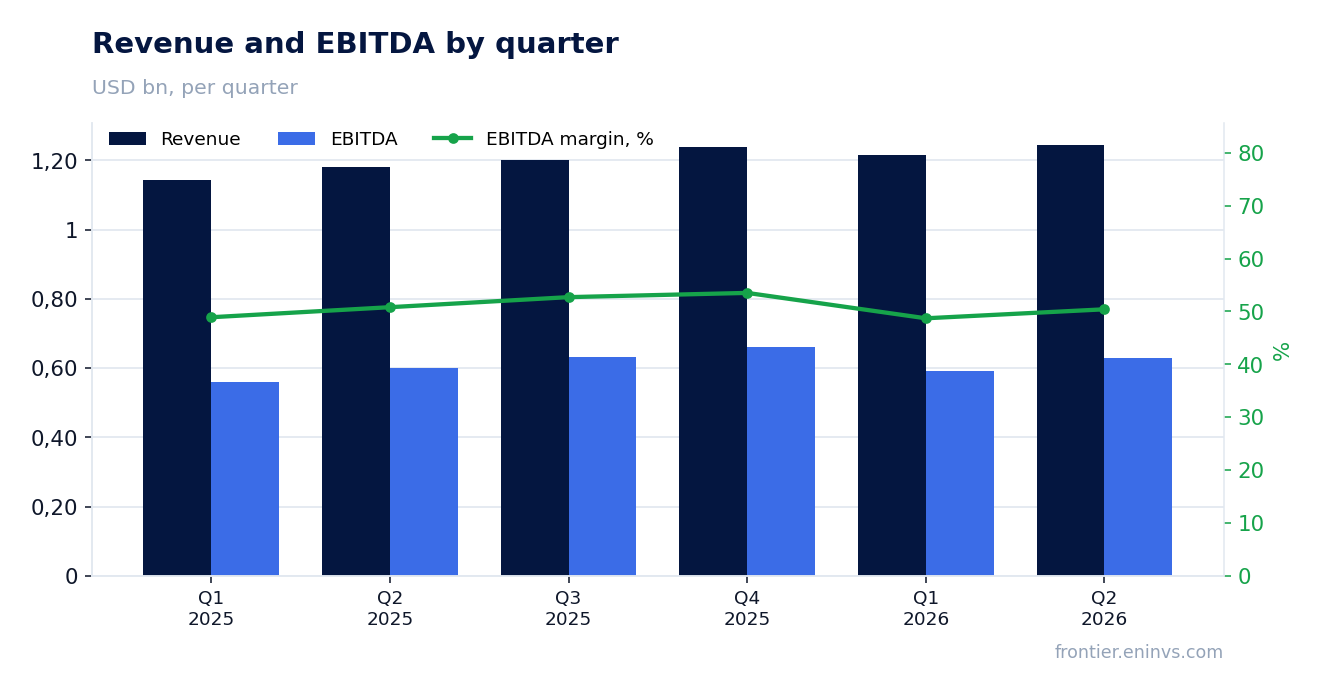
EBITDA margin in the second quarter was 50.4%, 0.4 p.p. lower than a year earlier
EBITDA for the quarter grew 4.9% year on year to $628.1 million, but the margin fell from 50.8% to 50.4%. This means cost growth is outpacing revenue growth, albeit slightly.
Over the last 12 months, EBITDA amounted to $2,506.1 million. The 0.4 p.p. margin decline is small, but it reverses the trend of previous periods when the margin was expanding.
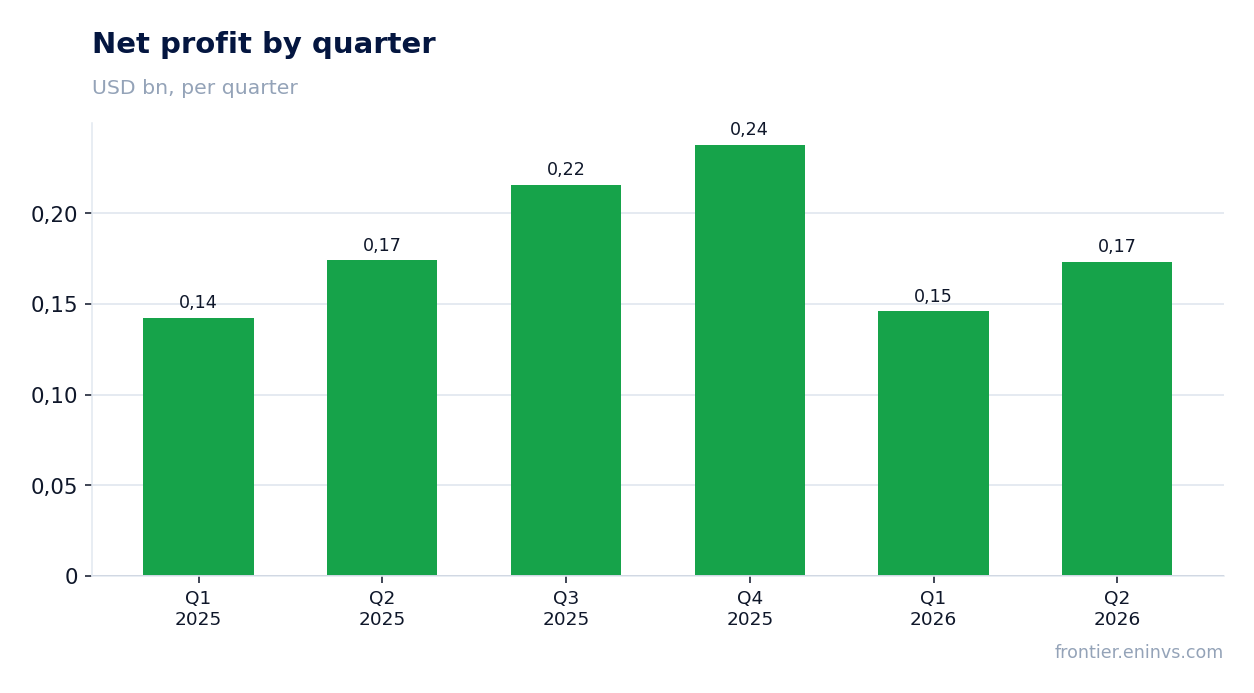
Net profit for the quarter fell 0.6% year on year to $173.3 million, while quarterly profit rose from $146.1 million in the first quarter
Net profit in the second quarter amounted to $173.3 million, 0.6% lower than a year earlier. For the first half, profit totaled $319.4 million (146.1 + 173.3), which is 0.6% lower than in the first half of 2025 (142.6 + 174.4 = 317.0 million, but exact calculation is not required).
Quarterly dynamics show a recovery after a weak first quarter: profit rose from $146.1 million to $173.3 million. However, there is no growth year on year — a signal that operational efficiency is not improving.
Operating cash flow for the quarter rose to $556.9 million, but capital expenditures of $167.1 million leave a significant free flow
Operating cash flow in the second quarter amounted to $556.9 million, noticeably higher than in the first quarter ($476.6 million). Capital expenditures for the quarter were $167.1 million, lower than in the first quarter ($242.0 million).
Free cash flow for the quarter was about $389.8 million (556.9 – 167.1). Over the last 12 months, operating flow reached $2,400.0 million, providing the company with a comfortable cushion for investments and dividends.
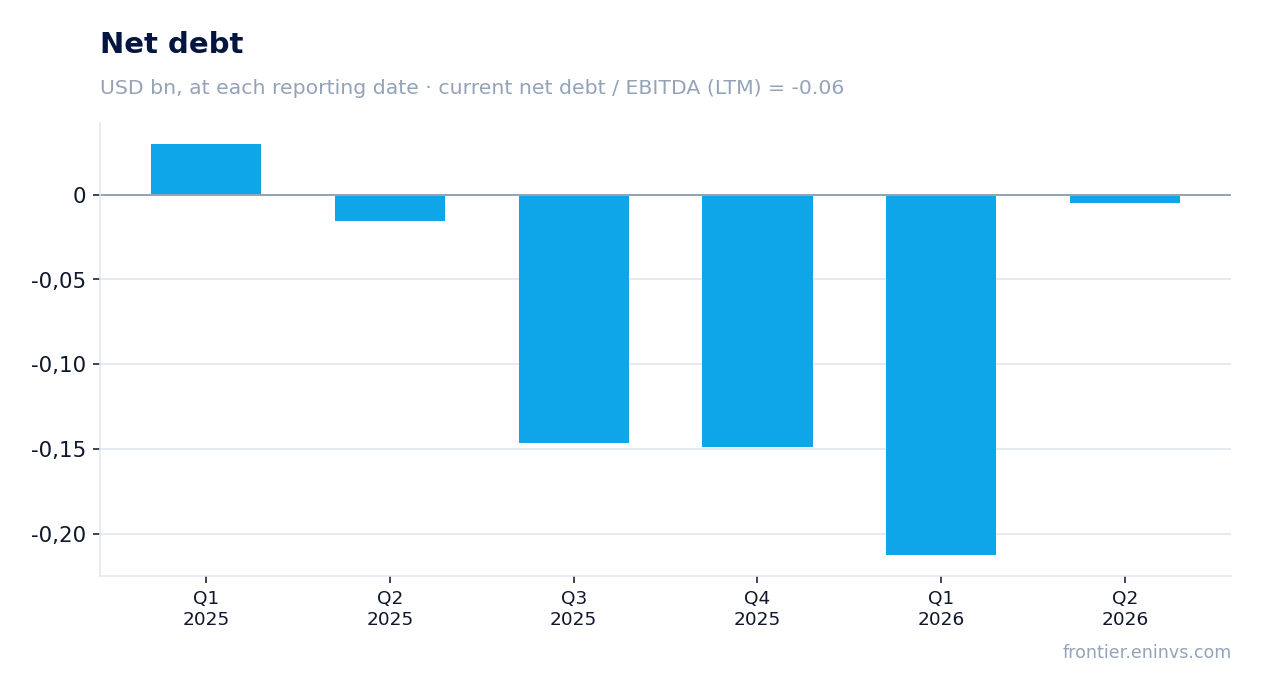
Net debt at the end of the quarter was minus $5.0 million, meaning the company remains a net creditor
At the end of the second quarter, TIM S.A.'s net debt was minus $5.0 million, meaning cash and equivalents exceed debt. The ratio of net debt to EBITDA over the last 12 months is minus 0.06, indicating virtually zero debt burden.
During the quarter, net debt changed by +0.2 billion rubles (insignificant in dollar terms), and over 12 months by +0.0 billion rubles. The company maintains financial stability, which is important for sustaining dividends.
Dividend yield over the last 12 months is 1.67%, below the key rate and not attractive given the valuation
Over the last 12 months, TIM S.A. paid dividends providing a yield of 1.67% at the current price. This is below the key rate, making the share unattractive for income-oriented investors.
At the current valuation (P/E 58.3, EV/EBITDA 17.9), the dividend yield does not compensate for the risk of slowing growth. Higher payouts would require either profit growth or an increase in the payout ratio, but the company has not yet shown such changes.
On the portal's model, the upside of the share is only +3%, indicating a fair valuation without a margin of safety
Our valuation model, based on EBITDA growth and a target multiple, shows an upside of only +3% to the current price. This means the market has already priced in growth expectations, and the potential for re-rating is limited.
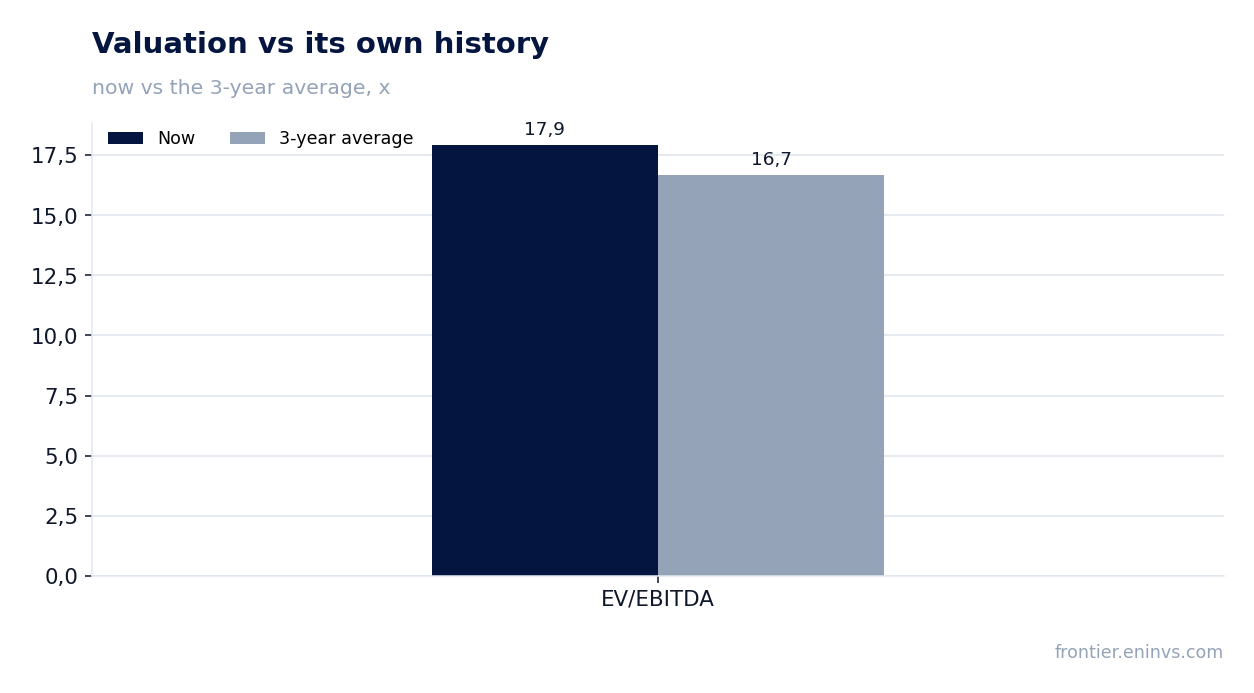
The current EV/EBITDA (17.9) is above the three-year average (16.7), and P/E (58.3) looks high for a company with zero profit growth. The share trades above its own history, leaving little room for a positive scenario.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 45.1 bn USD |
| P/E (LTM) | 58.3 |
| EV/EBITDA (LTM) | 17.9 |
| P/B | 10.52 |
| Net debt / EBITDA (LTM) | -0.06 |
| Operating cash flow (LTM) | 2.40 bn |
| ROE | 15.7% |
| Dividend yield (12m) | 1.7% |
| EV/EBITDA, 3-year average | 16.7 |
Bottom line
TIM S.A. shows stable but slowing revenue and EBITDA growth, while net profit is flat. The company maintains strong cash flow and virtually zero debt, which supports dividends, but their yield is low. The share's valuation is above its own history, and the potential on the portal's model is minimal. The verdict is rather unattractive: the current price already reflects most of the positive expectations.
Open the company's financial profile TIMB →
See also: market overview · valuation map · stock screeners