Lion Finance Group: profit outpaces interest income, but the gap is narrowing
Lion Finance Group reported third-quarter 2026 results on 6 November: net profit reached 661.9 million lari, up 21.0% year on year, while net interest income came in at 1,318.8 million lari, up 21.6% year on year. Top-line growth accelerated from 20.8% in the second quarter to 21.6% in the third, and profit is growing at almost the same pace. With a trailing twelve-month P/E of 7.8 and a return on equity of 27.4%, the share looks attractive at the current price, and the portal's model puts its upside at +49%.
Key takeaways
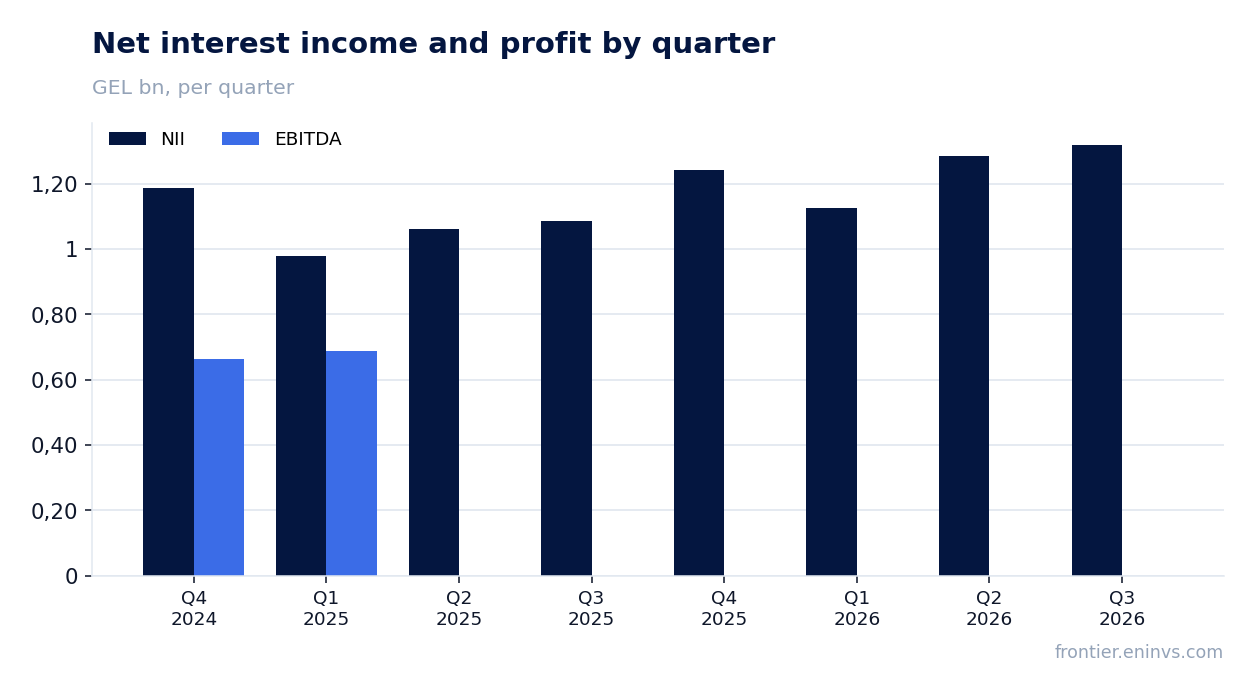
— Net interest income rose 21.6% year on year, accelerating from 20.8% a quarter earlier
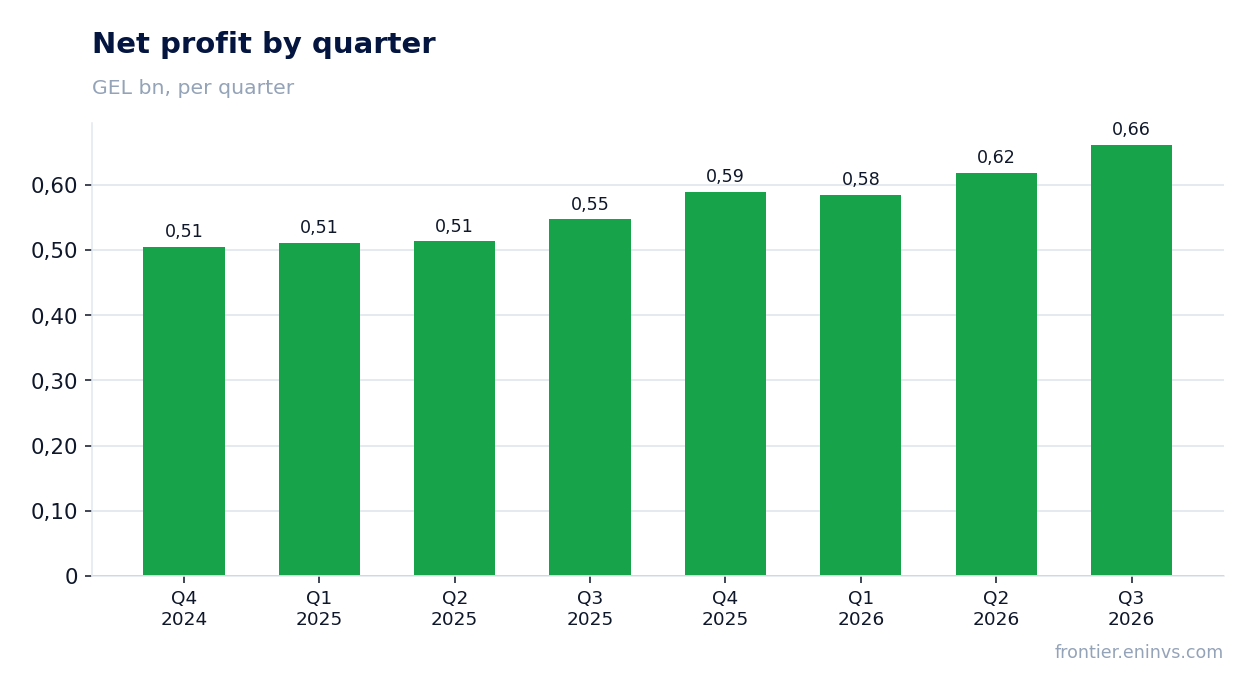
— Net profit added 21.0% year on year, almost keeping pace with interest income
— A 27.4% return on equity against a P/E of 7.8 leaves room for a re-rating
— Trailing twelve-month dividend yield is 2.5% – modest against the key rate
— The portal's model puts the share's upside at +49% to the current price
Attractiveness
Key figures, GEL bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Net profit | 0.55 | 0.66 | +21.0% |
Net interest income rose 21.6% year on year, accelerating from 20.8% a quarter earlier
In the third quarter of 2026, net interest income reached 1,318.8 million lari, up 21.6% year on year. A quarter earlier growth was 20.8%, so the pace accelerated. This is the third consecutive quarter of acceleration: growth was 15.0% in the first quarter of 2026 and 20.8% in the second.
The acceleration rests on a stable base: interest income has grown every quarter since the fourth quarter of 2024, when it stood at 1,186.3 million lari. In the third quarter of 2026 it added 234.7 million lari to the year-earlier level. Without a breakdown of assets and rates in the report, it is impossible to say whether loan volumes or funding costs drove the increase, but the acceleration itself is telling.
For a bank, accelerating interest income is the main indicator of business health. If the pace holds above 20%, profit will grow at similar rates with stable cost of risk.
Net profit added 21.0% year on year, almost keeping pace with interest income
Net profit for the third quarter of 2026 was 661.9 million lari, up 21.0% from the third quarter of 2025. Profit growth almost matches interest income growth (21.6%), meaning costs and cost of risk are rising in proportion to income without eating into the margin.
Profit has grown every quarter: 505.5 million lari in the fourth quarter of 2024, 511.1 million in the first quarter of 2025, 513.3 million in the second, 547.2 million in the third, 589.7 million in the fourth quarter of 2025, 585.0 million in the first quarter of 2026, 618.8 million in the second and 661.9 million in the third. Over the last twelve months profit reached 2,455.4 million lari.
The matching growth rates of profit and interest income indicate that operating leverage is not being diluted. If costs or provisions were growing faster than income, profit would lag – here it does not.
A 27.4% return on equity against a P/E of 7.8 leaves room for a re-rating
Lion Finance Group's return on equity is 27.4%, and its trailing twelve-month P/E is 7.8. With such a return on capital the market values the bank modestly: a price-to-earnings ratio below 8 with a return above 25% means investors are pricing in either a sustained slowdown or high risk.
Market capitalisation is 19,098.0 million lari. With trailing twelve-month profit of 2,455.4 million lari, that gives the P/E of 7.8. The portal's model, comparing return on equity with price-to-book, puts the share's upside at +49% to the current price.
The model's estimate is not a market consensus or a target price but the portal's own calculation. It shows that, if the current return holds, the share trades below its fair value. A re-rating is possible if the market comes to believe in the sustainability of profit growth.
Trailing twelve-month dividend yield is 2.5% – modest against the key rate
The trailing twelve-month dividend yield is 2.5%. That is a modest level for a bank with a 27.4% return on equity: with such profit one might expect more generous payouts. The yield is below the key rate, making the share less appealing to income-oriented investors.
Our estimate for the current year's dividend is based on trailing twelve-month profit of 2,455.4 million lari and the current 2.5% yield. It hinges on the payout ratio, which the company does not disclose in the facts, and on profit, which one-off items could reduce. If the payout ratio stays at its current level, the annual dividend will be close to last year's.
A cut could come from lower profit or higher capital requirements. While profit is growing 21% year on year, the risk of a dividend cut is small, but a 2.5% yield provides no margin of safety for the investor.
The portal's model puts the share's upside at +49% to the current price
The portal's model, comparing return on equity with price-to-book, gives +49% upside to the current price. This is not a target price or a consensus but the portal's own calculation based on current profit and capital.
The estimate rests on trailing twelve-month profit of 2,455.4 million lari and market capitalisation of 19,098.0 million lari. With a P/E of 7.8 and a return on equity of 27.4%, the share trades below its fair value unless the market is pricing in a profit decline.
The 49% upside is significant, but it materialises only if current growth rates hold. If profit slows or cost of risk rises, the model's estimate will fall.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 19.1 bn GEL |
| P/E (LTM) | 7.8 |
| P/B | 2.27 |
| ROE | 27.4% |
| Dividend yield (12m) | 2.5% |
Bottom line
The report's strength is the acceleration of interest income growth to 21.6% and profit growth to 21.0% year on year. A 27.4% return on equity with a P/E of 7.8 and the portal model's +49% upside makes the share attractive at the current price. The weak spot is the 2.5% dividend yield, which provides no margin of safety. The key question for a holder is whether profit growth above 20% will hold in the coming quarters.
Open the company's financial profile BGEO →
See also: market overview · valuation map · stock screeners