Royal Bank of Canada: profit up 11.2%, but a 5.6% ROE does not justify 19x earnings
RY →Royal Bank of Canada reported third-quarter 2026 results. Net profit came in at CAD 6,022 million, up 11.2% year on year, while net interest income rose 9.1% year on year to 18,511 million. Yet return on equity remains low at 5.6%, and the stock trades at 19.1 times earnings, making it unattractive at current levels.
Key takeaways
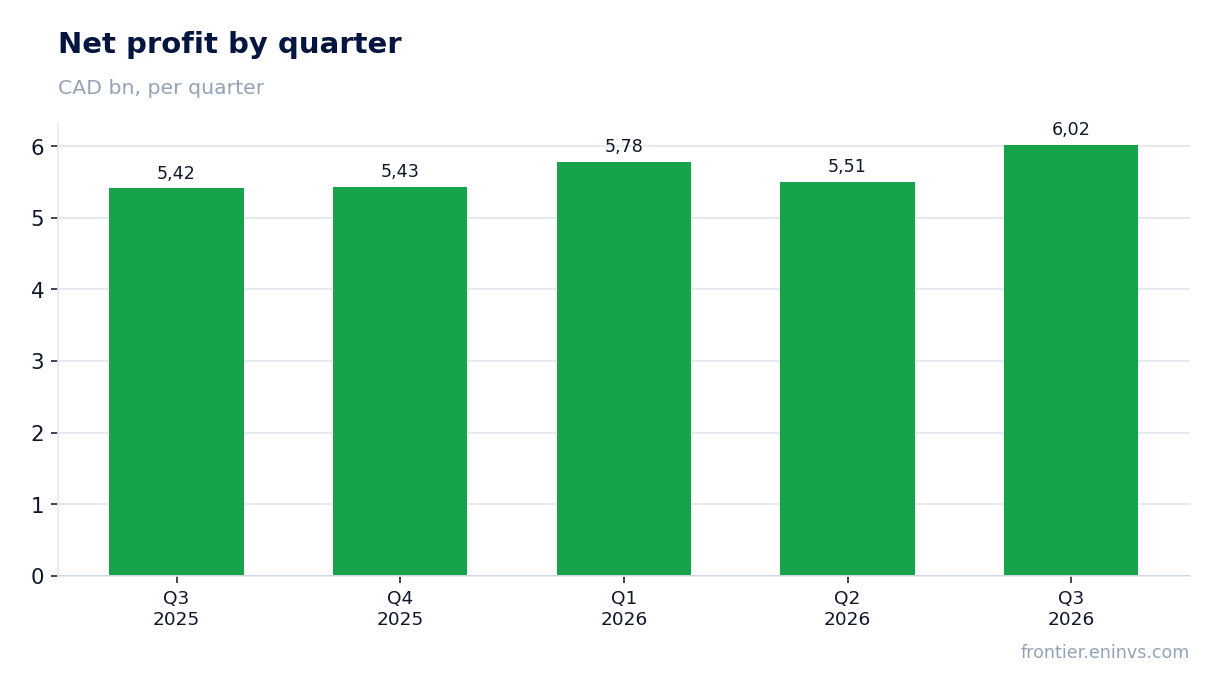
— Net profit rose 11.2% year on year to CAD 6,022 million, but that is only 11% above the quarterly profit level a year ago
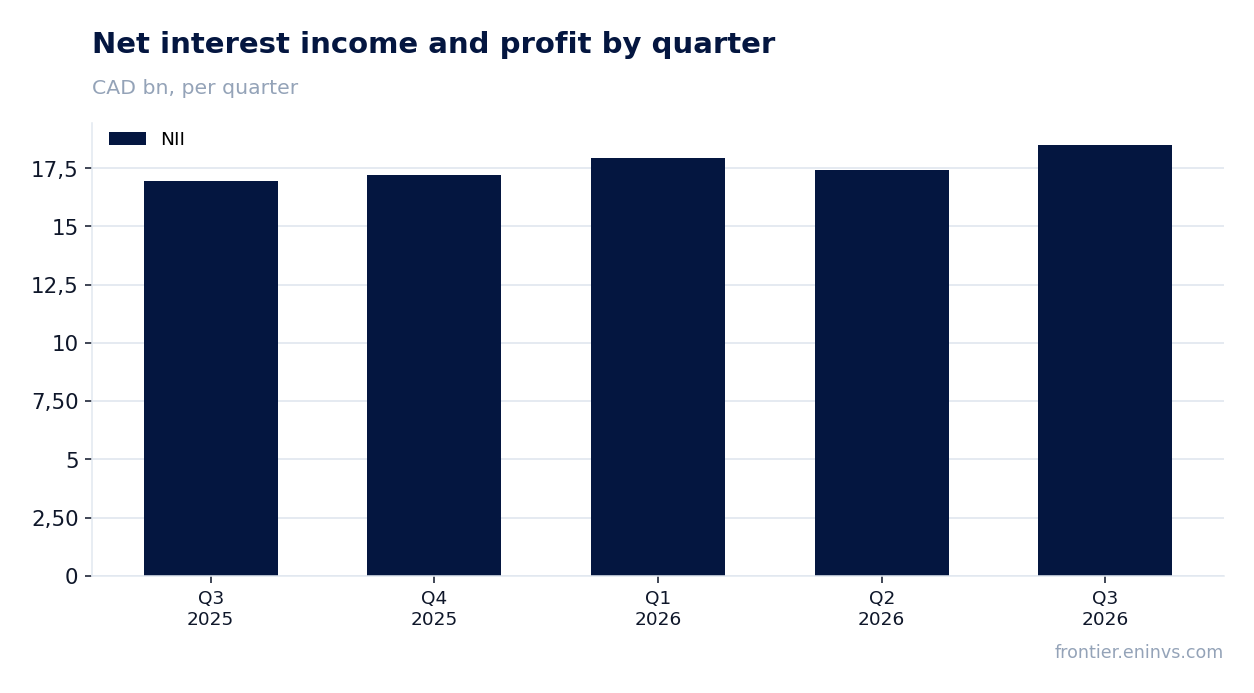
— Net interest income added 9.1% year on year to 18,511 million, becoming the main driver of profit growth
— Return on equity at 5.6% remains low and does not even cover the risk-free rate, limiting investment appeal
— Dividend yield of 2.35% lags the yield on ten-year Canadian government bonds, making the stock less attractive for conservative investors
— A valuation of 19.1 times earnings looks stretched against a 5.6% ROE and no acceleration in profit growth
— The portal model estimates upside to fair value at +6%, which does not compensate for the risks associated with low profitability
Attractiveness
Key figures, CAD bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Net profit | 5.42 | 6.02 | +11.2% |
| Capex | -0.53 | -0.74 | — |
Net profit rose 11.2% year on year to CAD 6,022 million, but that is only 11% above the quarterly profit level a year ago
In the third quarter of 2026, Royal Bank of Canada earned CAD 6,022 million in net profit. That is 11.2% more than in the same quarter last year, when profit was 5,415 million. The growth looks solid, but compared with the previous quarter (5,507 million), profit increased by only 9.3%, indicating no acceleration.
The main source of growth was net interest income, which rose 9.1% year on year to 18,511 million. This is the highest quarterly figure in the last four quarters: in the previous three it ranged from 16,960 to 17,923 million. Thus, profit growth relies on an increase in interest income, not on one-off factors.
Net interest income added 9.1% year on year to 18,511 million, becoming the main driver of profit growth
Net interest income in the third quarter of 2026 reached CAD 18,511 million, up 9.1% from 16,960 million a year earlier. This is the highest quarterly level in at least four quarters: in Q4 2025 it was 17,196 million, in Q1 2026 – 17,923 million, in Q2 – 17,429 million.
The growth in interest income provided the bulk of the profit increase. However, the growth rate of this indicator slowed compared with the first quarter of 2026, when it rose 5.7% quarter on quarter. In the reporting quarter, the quarter-on-quarter increase was 6.2%, slightly higher, but the year-on-year dynamics are more modest than over the trailing twelve months, where net interest income totalled 66,500 million.
Return on equity at 5.6% remains low and does not even cover the risk-free rate, limiting investment appeal
Royal Bank of Canada's return on equity is 5.6%. This is a very low figure for a bank: it is not only significantly below the historical levels of Canadian banks but also does not cover the yield on ten-year Canadian government bonds, which in recent years has fluctuated between 3–4%. At such a profitability level, the bank does not create sufficient value for shareholders.
The low ROE is explained by the fact that the profit of CAD 6,022 million was earned on a substantial equity base. With a market capitalisation of 388,165 million and a P/E of 19.1, earnings per share are low relative to the price. This means investors are paying a significant premium for growth that is not yet supported by the level of profitability.
Dividend yield of 2.35% lags the yield on ten-year Canadian government bonds, making the stock less attractive for conservative investors
Royal Bank of Canada's dividend yield over the trailing twelve months is 2.35%. This is below the yield on ten-year Canadian government bonds, which in recent years has often exceeded 3%. Thus, an investor buying the stock for dividends receives a lower current income than from investing in risk-free government securities.
With a payout ratio that can be estimated as the ratio of dividend per share to earnings per share, and current profit of CAD 6,022 million, the dividend burden looks moderate. However, the low ROE of 5.6% means the bank cannot rapidly increase profits, and therefore dividend payments will grow slowly. This limits the stock's appeal for income-oriented investors.
A valuation of 19.1 times earnings looks stretched against a 5.6% ROE and no acceleration in profit growth
Royal Bank of Canada's P/E ratio on trailing twelve-month earnings is 19.1. This is a high level for a bank with a return on equity of 5.6%. For comparison, Canadian banks have historically traded at P/E ratios of 10–15, and the current valuation implies either significant future profit growth or a sustainable quality premium that is not supported by current metrics.
The bank's market capitalisation is CAD 388,165 million. With trailing twelve-month profit of 20,362 million, this gives the stated P/E. However, if profit remains at the current level or grows at the same pace, the valuation is unlikely to decline to historical levels without a fall in the share price. This creates a risk for investors buying the stock at current levels.
The portal model estimates upside to fair value at +6%, which does not compensate for the risks associated with low profitability
According to the portal model, the fair value of Royal Bank of Canada shares implies upside of +6% to the current price. This calculation is based on comparing return on equity and the P/B ratio. Such upside is not significant and does not compensate for the risks associated with a low ROE of 5.6% and a high valuation of 19.1 times earnings.
For comparison, with a current dividend yield of 2.35%, the total return (price growth plus dividends) could be around 8.35%, which only slightly exceeds the yield on risk-free bonds. Given the uncertainty in financial markets and the absence of clear drivers for accelerating profit growth, such a return appears insufficient to justify taking on investment risk.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 388 bn CAD |
| P/E (LTM) | 19.1 |
| P/B | 2.79 |
| ROE | 5.6% |
| Dividend yield (12m) | 2.4% |
Bottom line
Royal Bank of Canada delivered solid profit growth of 11.2% year on year and a 9.1% increase in net interest income, which is a strong point of the report. However, return on equity remains low at 5.6%, and a valuation of 19.1 times earnings with a dividend yield of 2.35% does not make the stock attractive. The portal model indicates upside of only +6%, which does not compensate for the risks. Ultimately, at current levels, the stock looks unattractive for purchase.