Japan Tobacco: double-digit revenue growth, but Q3 profit slipped as margin came under pressure
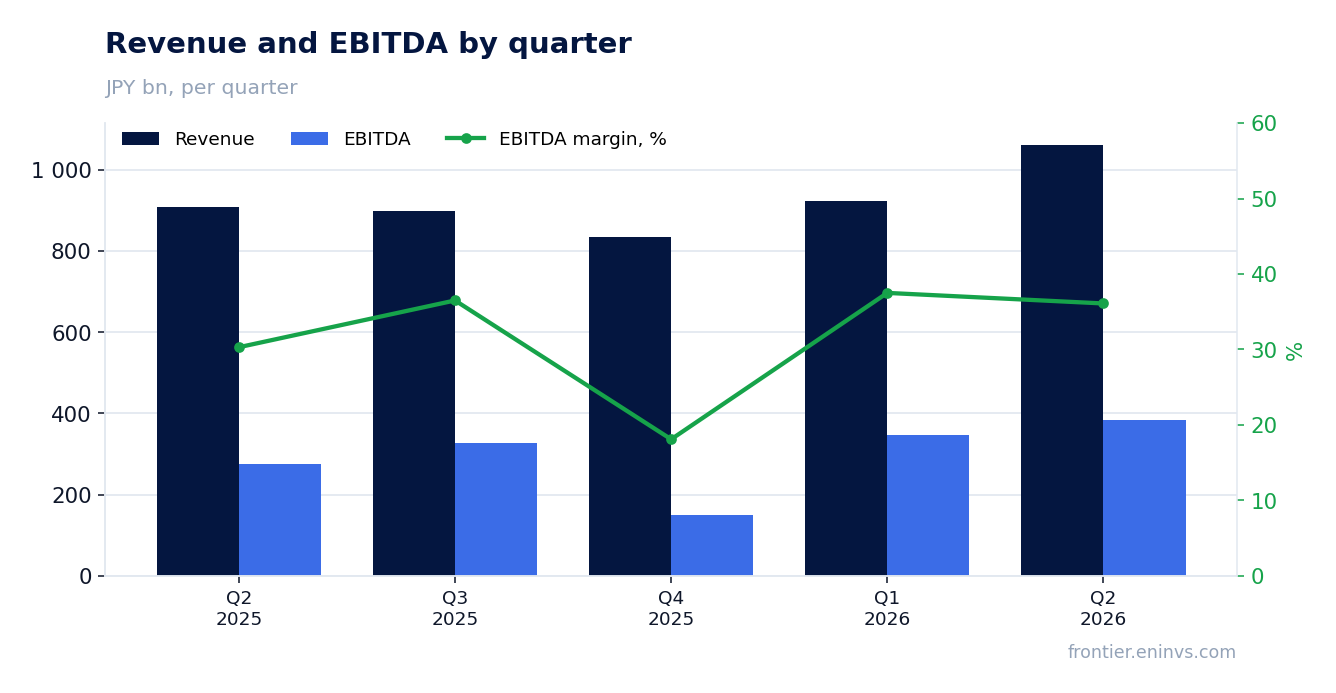
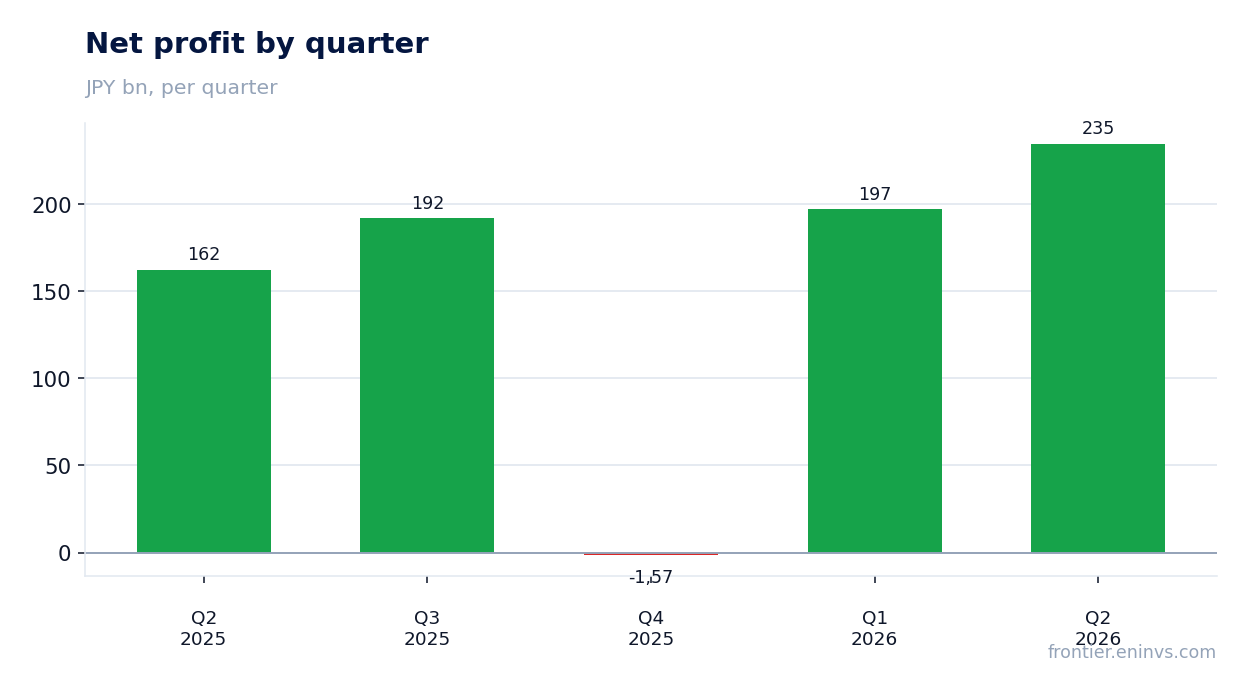
2914 →On 13 November Japan Tobacco reported results for the third quarter of 2026. Revenue rose 11.8% year on year to JPY 1,005.3 bn, EBITDA added 10.3% to JPY 362.2 bn, while net profit fell 2.5% to JPY 187.1 bn. Growth slowed from the second quarter, when revenue was up 17.0%, and the EBITDA margin narrowed from 36.5% to 36.0%. Our conclusion: fairly valued – on the portal's model the upside to fair value is +7%. Our view: the share is fairly valued; upside on the portal model +7%.
Our view: is there upside
Our view in numbers
| Metric | Our read |
|---|---|
| Verdict | Neutral |
| Upside on the portal model | +7% |
| How the model works | fundamental value-creation model: EBITDA growth times the target multiple, against market cap |
| EV/EBITDA now and 3-year average | 8.6 vs 11.5 – a 25% discount to its history |
| Dividend yield, 12m | 4.8% |
| Net debt / EBITDA | 0.64 – low leverage |
| Strongest case for | A 25% discount to its own three-year EV/EBITDA average and a 4.8% dividend yield with debt at 0.64 of EBITDA provide a cushion for the holder. |
| Strongest case against | The net margin fell from 21.3% to 18.6% and revenue growth slowed from 17.0% to 11.8%, limiting profit potential. |
| What would change the view | A recovery in the net margin above 20% while revenue growth holds would move the verdict one step up. |
Key takeaways
— Q3 revenue grew 11.8%, slower than the 17.0% seen in Q2
— EBITDA added 10.3%, while its margin narrowed from 36.5% to 36.0%
— Net profit fell 2.5%, with the margin down from 21.3% to 18.6%
— Operating cash flow of JPY 399.9 bn covers capex of JPY 40.0 bn almost tenfold
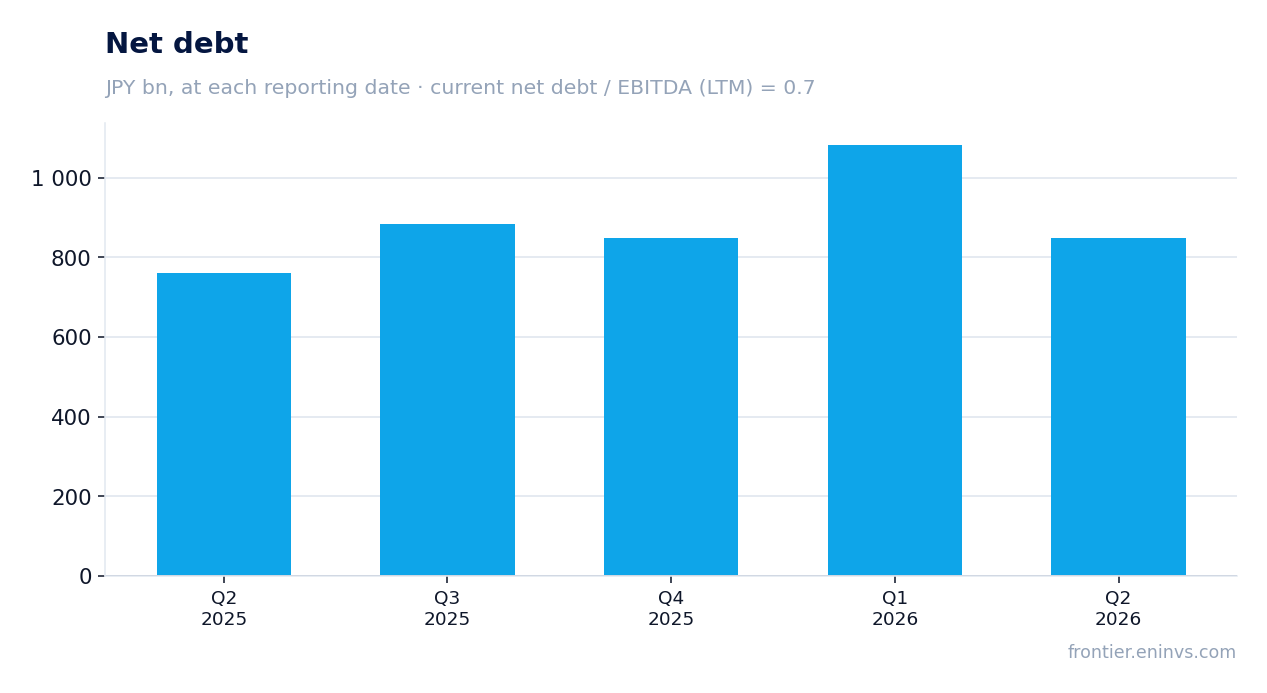
— Net debt fell from JPY 884.6 bn a year earlier to JPY 786.1 bn, with the ratio to LTM EBITDA at 0.64
— A dividend yield of 4.8% remains the main support for the shareholder
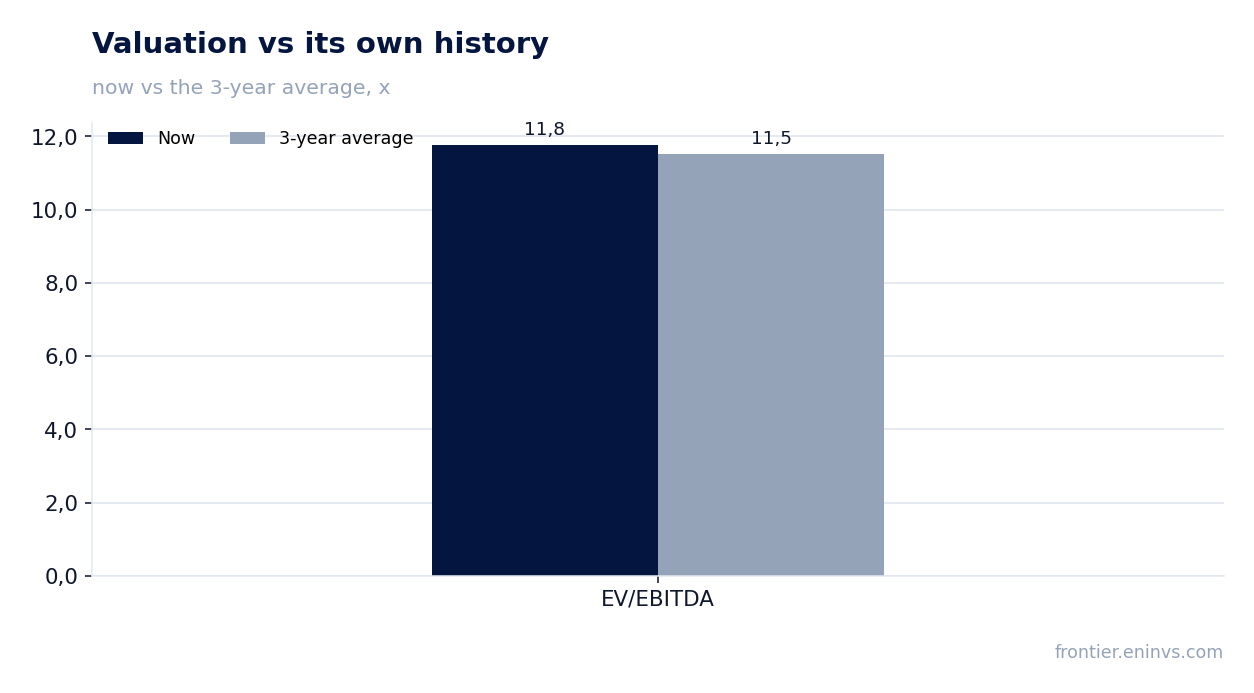
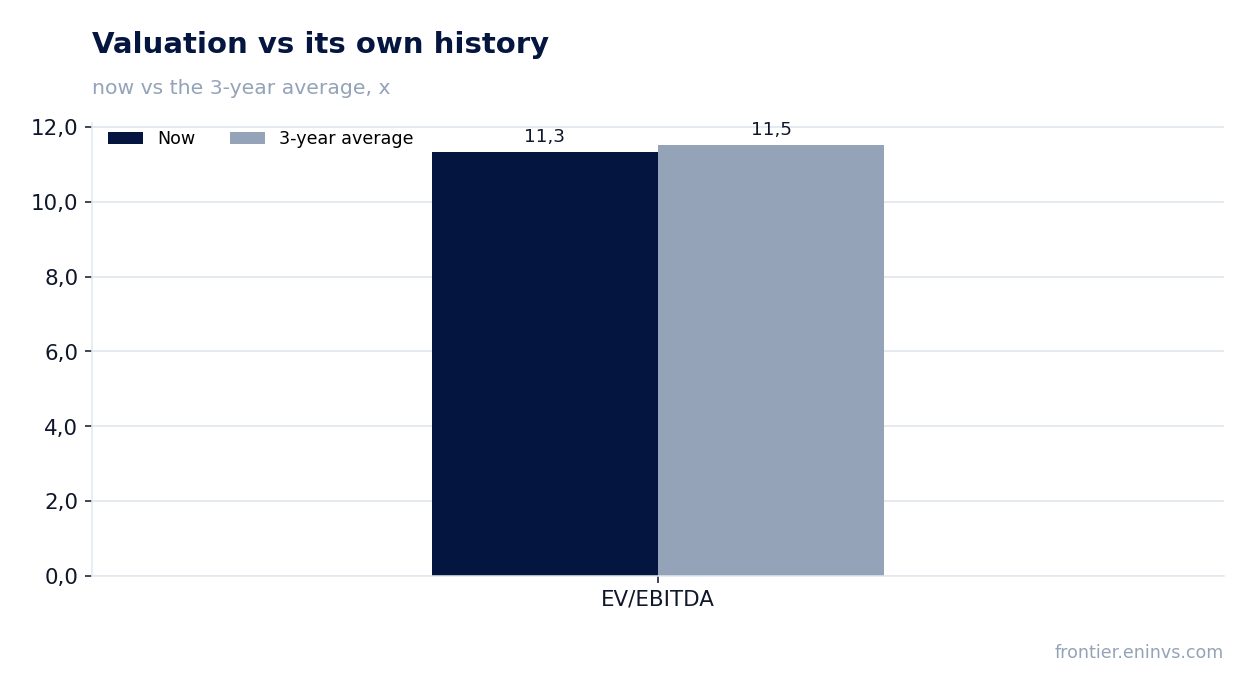
— EV/EBITDA LTM of 8.6 is 25% below its own three-year average of 11.5
Key figures, JPY bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 899 | 1 005 | +11.8% |
| EBITDA | 328 | 362 | +10.3% |
| Operating profit | 280 | 300 | +7.3% |
| Net profit | 192 | 187 | -2.5% |
| Operating cash flow | 120 | 400 | +234.5% |
| Capex | 45.3 | 40.0 | -11.7% |
| EBITDA margin | 36.5% | 36.0% | -0.5 pp |
| Net margin | 21.3% | 18.6% | -2.7 pp |
Q3 revenue grew 11.8%, slower than the 17.0% seen in Q2
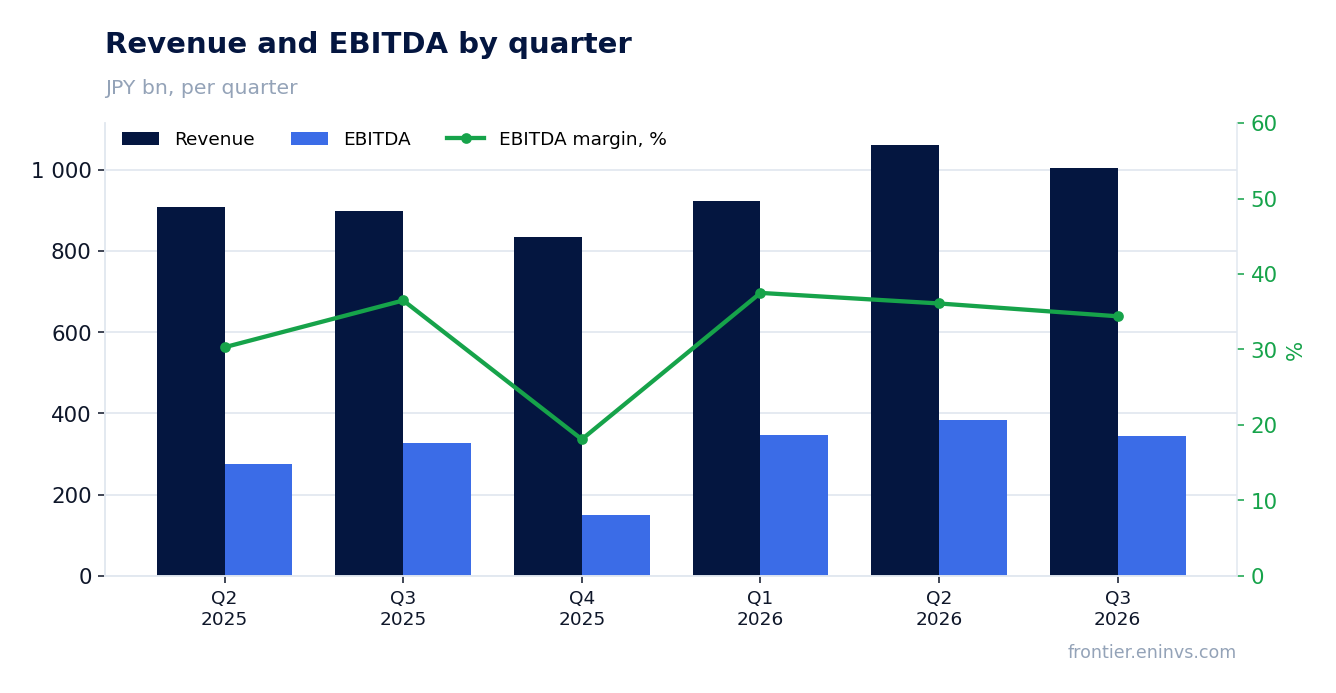
Revenue for the third quarter of 2026 came in at JPY 1,005.3 bn, 11.8% above the level a year earlier. Growth remains in double digits, but the pace slowed: in the second quarter revenue was adding 17.0%. The deceleration of 5.2 percentage points shows that quarter-on-quarter momentum is weakening.
Over the trailing twelve months revenue amounted to JPY 3,825.0 bn. That base includes both strong quarters and a weak fourth quarter of 2025 with revenue of JPY 833.6 bn. The current quarterly level of JPY 1,005.3 bn is above the four-quarter average, confirming the recovery after the slump at the end of last year.
EBITDA added 10.3%, while its margin narrowed from 36.5% to 36.0%
EBITDA for the third quarter was JPY 362.2 bn, 10.3% more than a year earlier. Growth lags revenue slightly, so the EBITDA margin declined from 36.5% to 36.0%. The 0.5 percentage point compression is small, but it shows that costs are rising faster than income.
Over the trailing twelve months EBITDA amounted to JPY 1,233.1 bn. The quarterly level of JPY 362.2 bn corresponds to roughly 29% of the annual base, which fits normal seasonality. Operating profit for the quarter was JPY 300.0 bn, and its gap to EBITDA is explained by depreciation.
Net profit fell 2.5%, with the margin down from 21.3% to 18.6%
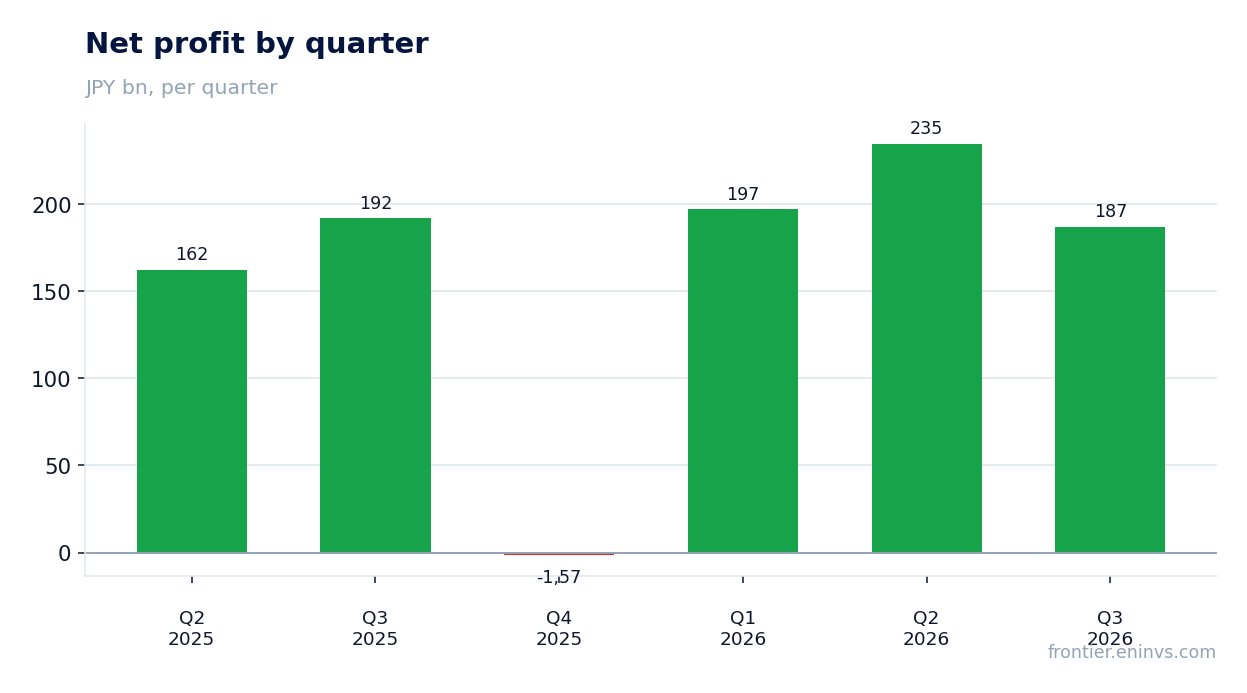
Net profit for the third quarter was JPY 187.1 bn, 2.5% less than a year earlier. The net margin fell from 21.3% to 18.6%. A 2.7 percentage point margin decline alongside EBITDA growth suggests the pressure came below the operating line – from financial items or tax.
Over the trailing twelve months net profit amounted to JPY 617.3 bn. The quarterly result of JPY 187.1 bn is about 30% of the annual base, close to the revenue share. The gap between EBITDA growth and the profit decline points to items outside operating activity weighing on the bottom line.
Operating cash flow of JPY 399.9 bn covers capex of JPY 40.0 bn almost tenfold
Operating cash flow for the third quarter was JPY 399.9 bn, while capital expenditure was JPY 40.0 bn. Free cash flow after investment exceeds JPY 350 bn for the quarter. That is strong conversion: the flow is almost twice quarterly net profit.
Over the trailing twelve months operating cash flow amounted to JPY 958.3 bn. The quarterly level of JPY 399.9 bn is about 42% of the annual base, above the revenue and profit shares. Such a flow gives the company room to pay shareholders and reduce debt without external financing.
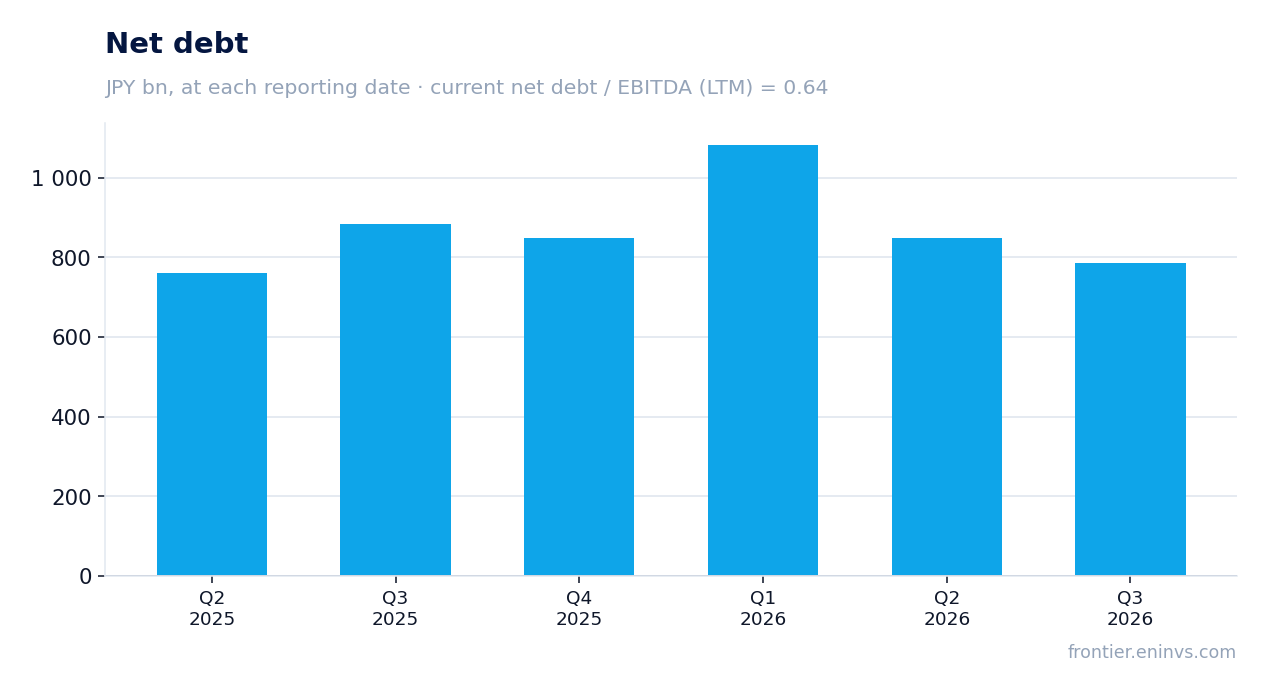
Net debt fell from JPY 884.6 bn a year earlier to JPY 786.1 bn, with the ratio to LTM EBITDA at 0.64
Net debt at 30 September 2026 was JPY 786.1 bn versus JPY 884.6 bn at 30 September 2025, a twelve-month reduction of JPY 98.5 bn. From the previous reporting date of 30 June 2026, debt fell from JPY 848.9 bn by JPY 62.7 bn. The reduction rests on strong quarterly operating cash flow.
The ratio of net debt to trailing twelve-month EBITDA is 0.64. That is a moderate level: debt is about one and a half times less than annual EBITDA. With such a cushion, interest expense does not create noticeable pressure on profit.
A dividend yield of 4.8% remains the main support for the shareholder
The trailing twelve-month dividend yield is 4.8%. That is noticeably above the return an investor could get from risk-free instruments and provides a regular cash flow to the holder. Payments rest on strong annual operating cash flow of JPY 958.3 bn.
Our estimate of the current-year dividend assumes the payout ratio and LTM profit of JPY 617.3 bn are maintained. The risk to the payment is further net margin compression: if profit keeps falling, the dividend could be revised. For now, free cash flow after capex of JPY 40.0 bn covers the payments with room to spare.
EV/EBITDA LTM of 8.6 is 25% below its own three-year average of 11.5
The trailing twelve-month EV/EBITDA multiple is 8.6 against its own three-year average of 11.5. A 25% discount suggests the market values the company below its usual level over the past three years. P/E LTM stands at 15.8, and market capitalisation is JPY 9,764.9 bn.
On the portal's model the upside to fair value is +7%. That is a moderate cushion that does not fully offset the margin compression risk. The combination of a discount to history and modest model upside leaves the share in fairly valued territory.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 9 765 bn JPY |
| P/E (LTM) | 15.8 |
| EV/EBITDA (LTM) | 8.6 |
| P/B | 2.39 |
| Net debt / EBITDA (LTM) | 0.64 |
| Operating cash flow (LTM) | 958 bn |
| ROE | 17.6% |
| Dividend yield (12m) | 4.8% |
| EV/EBITDA, 3-year average | 11.5 |
Bottom line
The quarter's strong point remains cash flow: JPY 399.9 bn of operating flow with capex of JPY 40.0 bn. Net debt fell to JPY 786.1 bn, and the ratio to LTM EBITDA is 0.64. The weak spot is profit: the net margin dropped from 21.3% to 18.6%, and revenue growth slowed to 11.8%. The key question for the holder is whether the 4.8% dividend yield holds up amid margin compression. Our conclusion: fairly valued – on the portal's model the upside to fair value is +7%. Our view: the share is fairly valued; upside on the portal model +7%.