Solidcore: H1 profit up 5.3x, but the year was spoiled by concentrate shipment delays

On 30 January 2026, Solidcore Resources plc released its Q4 and FY 2025 production results. For H1 2026, revenue reached $971.7 million, EBITDA – $641.0 million, net profit – $453.0 million, with an EBITDA margin of 66.0% versus 46.8% a year earlier. However, these figures relate to the reporting period, while the release itself covers 2025, when gold production fell 19% due to concentrate processing disruptions in H1. The shares look attractive: EV/EBITDA LTM stands at 3.34, P/E LTM at 5.38, and a net cash position of $461 million confirms a strong balance sheet.
Key takeaways
— H1 2026 revenue grew 199.0% to $971.7 million, but the release covers 2025, where revenue was $1.5 billion with sales down 23%
— H1 EBITDA reached $641.0 million with a 66.0% margin, up 19.2 pp from 46.8% a year earlier, driven by favourable gold prices
— H1 net profit was $453.0 million, while LTM net profit reached $1,030.0 million, giving a P/E LTM of just 5.38
— Net cash at end-2025 rose to $461 million from $355 million a quarter earlier, while net debt/EBITDA LTM stands at minus 0.31
— FY 2025 CAPEX came in below guidance at about $270 million versus $300 million, but 2026 CAPEX will nearly double to $510 million due to Ertis POX construction
— Gold production fell 19% in 2025 to 395 Koz, but 2026 output is expected to rise to 540 Koz on the release of accumulated inventories
— No dividend has been declared, but with a 50% payout ratio and LTM profit of $1,030 million, the potential yield could be around 9%
Attractiveness
Key figures, USD bn
| Metric | H1 2025 | H1 2026 | Change |
|---|---|---|---|
| Revenue | 0.33 | 0.97 | +199.0% |
| EBITDA | 0.15 | 0.64 | +321.7% |
| Operating profit | 0.13 | 0.60 | +369.3% |
| Net profit | 0.09 | 0.45 | +432.9% |
| Operating cash flow | -0.09 | 0.44 | в прибыль |
| Capex | 0.13 | 0.19 | +50.8% |
| EBITDA margin | 46.8% | 66.0% | +19.2 pp |
| Net margin | 26.2% | 46.6% | +20.4 pp |
H1 2026 revenue grew 199.0% to $971.7 million, but the release covers 2025, where revenue was $1.5 billion with sales down 23%
In H1 2026, Solidcore's revenue reached $971.7 million, up 199.0% year-on-year. This growth is explained by the low base of H1 2025, when the company faced delays in concentrate processing at a third-party plant. The 30 January 2026 release provides 2025 data: full-year revenue was $1.5 billion, up 13% due to high gold prices, which offset a 23% drop in sales.
Gold sales in 2025 fell to 412 Koz from 536 Koz a year earlier. The main reason was disruptions in H1, when concentrate from Kyzyl could not be processed at a third-party POX. In Q4, sales rose 24% year-on-year to 152 Koz, and quarterly revenue reached $639 million. This confirms that the company was selling down accumulated inventories in H2.
For 2026, the company plans to produce about 540 Koz of gold equivalent, up 37% from 2025. The increase will be driven by the release of accumulated concentrate inventories. However, costs will rise: TCC is forecast at $1,350–1,550 per ounce, 15–35% higher than in 2025, due to the progressive MET rate and inflation.
H1 EBITDA reached $641.0 million with a 66.0% margin, up 19.2 pp from 46.8% a year earlier, driven by favourable gold prices
H1 2026 EBITDA was $641.0 million, with an EBITDA margin of 66.0% versus 46.8% a year earlier. This margin growth is explained by favourable gold prices, which in 2025 were significantly higher than in 2024. The release notes that 2025 revenue grew 13% solely due to prices, despite lower sales.
Operating profit for H1 was $596.0 million, and net profit was $453.0 million. The net margin reached 46.6% versus 26.2% a year earlier. This reflects high operational efficiency at current gold prices. However, the company warns that costs will rise in 2026: AISC is forecast at $1,850–2,050 per ounce, 15–30% higher than in 2025.
The cost increase is due to the introduction of a progressive MET rate in Kazakhstan, linked to the gold price. At a price above $3,800 per ounce, the MET rate reaches its ceiling of 11%. This means that part of the gain from high gold prices will be taken away through taxes, which could limit margin growth in the future.
H1 net profit was $453.0 million, while LTM net profit reached $1,030.0 million, giving a P/E LTM of just 5.38
Solidcore's net profit for H1 2026 was $453.0 million, up 432.9% year-on-year. Over the last 12 months, net profit reached $1,030.0 million. With a market capitalisation of $5,539.3 million, this gives a P/E LTM of just 5.38. Such a low multiple is explained by record profits amid high gold prices and a low base last year.
Return on equity (ROE) is 36.7%, confirming high business efficiency. However, it is important to understand that LTM profit includes one-off factors related to inventory sell-down, which will not be repeated to the same extent in the future. In 2026, the company expects production growth, but also cost growth, which could lead to margin compression.
H1 net profit includes operating profit of $596.0 million. The company does not disclose one-off items, but notes that in 2025 there were sales delays that led to inventory accumulation. Their sale in 2026 will support profit, but the effect will be smaller than in 2025.
Net cash at end-2025 rose to $461 million from $355 million a quarter earlier, while net debt/EBITDA LTM stands at minus 0.31
Solidcore's net cash position at end-2025 was $461 million, up from $355 million at end-Q3 and $374 million at end-2024. This reflects strong operating cash flow, which in H1 2026 amounted to $436.0 million. The company has no debt burden, and the net debt/EBITDA LTM ratio stands at minus 0.31.
Operating cash flow over the last 12 months reached $603.0 million. With capital expenditures of $193.0 million in H1, free cash flow remains positive. The company plans to increase CAPEX in 2026 to $510 million, nearly double that of 2025. The main expenses will be for the construction of Ertis POX ($315 million) and the development of underground mining at Kyzyl.
Despite the increase in capital expenditures, the net cash position allows financing projects without debt. The company is also negotiating with international banks for loan facilities of $500–600 million for Ertis POX, which it expects to sign in Q2 2026. This provides additional financial flexibility.
FY 2025 CAPEX came in below guidance at about $270 million versus $300 million, but 2026 CAPEX will nearly double to $510 million due to Ertis POX construction
Solidcore's capital expenditures in 2025 were about $270 million, below the $300 million guidance. The reduction is due to the deferral of some Ertis POX expenses to 2026. In H1 2026, CAPEX already amounted to $193.0 million. For 2026, the company plans to increase capital investments to $510 million, nearly double that of 2025.
The main expense items for 2026: construction of Ertis POX ($315 million), construction of underground infrastructure at Kyzyl, fleet replacement at Varvara, and expansion of tailings storage facilities. In addition, the company will provide a $30 million loan to the Syrymbet joint venture to finance the feasibility study and pre-construction works. This increases the debt burden on the balance sheet, but the company still maintains a net cash position.
The increase in capital expenditures could lead to negative free cash flow in 2026 if operating cash flow does not grow proportionally. However, the company expects production and revenue growth, which should support operating cash flow. The question is whether Solidcore can maintain a balance between investments and dividends.
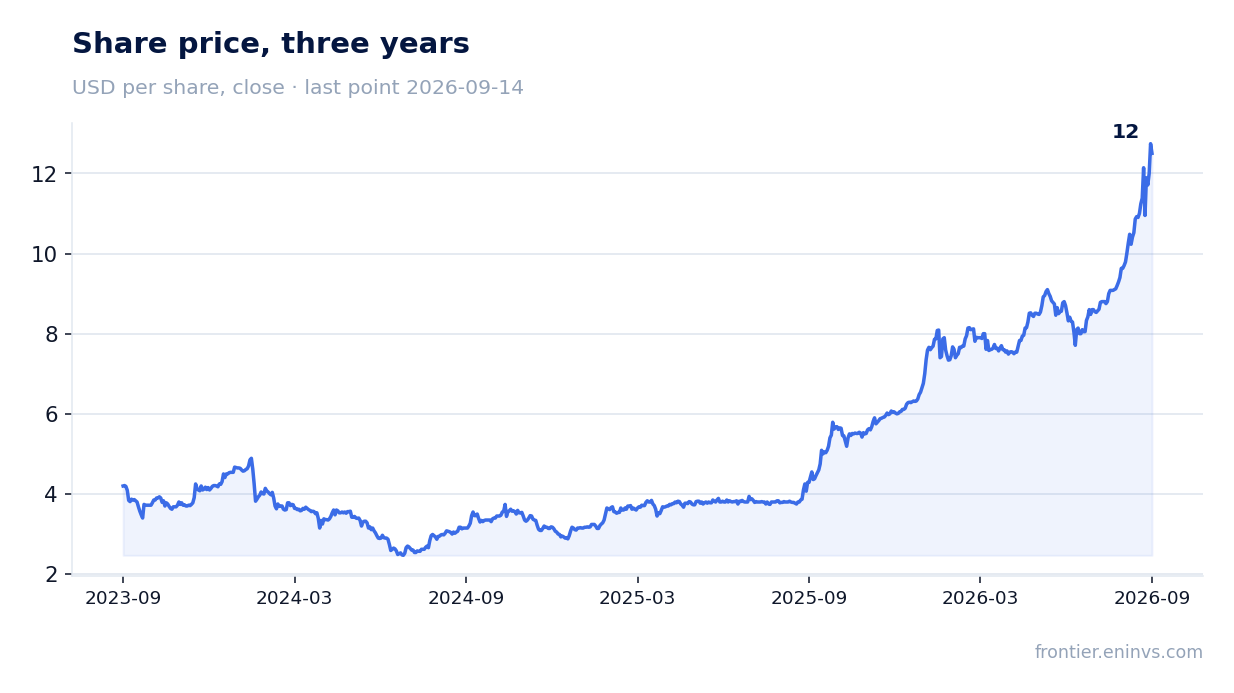
Gold production fell 19% in 2025 to 395 Koz, but 2026 output is expected to rise to 540 Koz on the release of accumulated inventories
Solidcore's gold equivalent production in 2025 was 395 Koz, down 19% from 2024. The main reason was delays in concentrate processing at a third-party plant in H1. In Q4, production rose 23% year-on-year to 146 Koz as processing stabilised. Sales for the year fell 23% to 412 Koz.
For 2026, the company forecasts production of about 540 Koz, up 37% from 2025. The increase will be driven by the release of accumulated concentrate inventories that were not sold in 2025. For 2027, preliminary guidance is about 500 Koz. This means that peak production will be in 2026, followed by a possible decline.
The key risk is dependence on third-party processing capacity. In 2025, disruptions at a third-party POX led to significant losses. The company is building its own Ertis POX, which should reduce this dependence, but the project will not be completed before 2026–2027. Until then, production remains vulnerable to supply chain disruptions.
No dividend has been declared, but with a 50% payout ratio and LTM profit of $1,030 million, the potential yield could be around 9%
Solidcore did not declare dividends for 2025 in this release. However, the company has a net cash position of $461 million and LTM profit of $1,030.0 million. If the company allocates 50% of profit to dividends, this would be about $515 million, which at a market capitalisation of $5,539.3 million gives a dividend yield of about 9.3%. This is significantly above the key rate, making the shares attractive for income-oriented investors.
However, the dividend decision depends on the board of directors and may be adjusted considering capital expenditures. In 2026, CAPEX will rise to $510 million, nearly double that of 2025. This could limit the ability to pay large dividends. The company also provides a $30 million loan to the Syrymbet joint venture, which increases cash outflow.
Solidcore's historical dividend policy is not disclosed in the release. If the company follows a conservative approach and allocates 30% of profit to dividends, the yield would be about 5.6%. In any case, even under a conservative scenario, the yield remains above the risk-free rate. The main risk is a decline in profit in 2027 due to falling production and rising costs.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 5.54 bn USD |
| P/E (LTM) | 5.4 |
| EV/EBITDA (LTM) | 3.3 |
| P/B | 2.52 |
| Net debt / EBITDA (LTM) | -0.31 |
| Operating cash flow (LTM) | 0.60 bn |
| ROE | 36.7% |
Bottom line
Solidcore delivered strong H1 2026 results: revenue up 199.0%, EBITDA up 321.7%, net profit up 432.9%. However, these figures reflect a low base last year and one-off factors related to inventory sell-down. The company has a strong balance sheet with a net cash position of $461 million and low multiples: EV/EBITDA LTM 3.34, P/E LTM 5.38. The key question for a holder is whether Solidcore can maintain its margin in 2026 amid rising costs and capital expenditures. The shares look attractive, but upside is limited by the portal's model, which values fair value 16% below the current price.
Open the company's financial profile SOLIDCORE →
See also: market overview · valuation map · stock screeners