Bajío: Q2 2026 profit fell again, and higher rates have not helped yet
On July 29, 2026, Grupo Financiero Bajío reported results for the second quarter of 2026. Net profit came in at 2,118 million pesos, down 2.2% year on year, while net interest income fell 2.9% year on year to 6,172 million pesos. The bank earns steadily, but growth is slowing: over the trailing twelve months ROE stands at 17.4%, and the stock trades at a P/E of 7.6 with a dividend yield of 8.25%. In our view, the share looks rather attractive for an income-oriented investor, but weak net interest income growth and no clear catalyst for acceleration limit capital upside.
Key takeaways
— Net profit in Q2 2026 fell 2.2% year on year to 2,118 million pesos, marking the second consecutive quarterly decline
— Net interest income has fallen for two straight quarters: down 6.8% in Q1 2026 and down 2.9% in Q2 2026
— Return on equity at 17.4% remains high, but trailing-twelve-month profit of 9,079 million pesos is only marginally above the year-ago level
— The 8.25% dividend yield is more than double the key rate, making the stock attractive for income, but the payout depends on sustaining current profit
— A P/E of 7.6 and ROE of 17.4% imply a fair value about 12% above the current price on the portal's model
— Capex rose to 156.9 million pesos in Q1 2026, but it does not offset the decline in net interest income, and margin pressure persists
Attractiveness
Key figures, MXN bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Net profit | 2.17 | 2.12 | -2.2% |
Net profit in Q2 2026 fell 2.2% year on year to 2,118 million pesos, marking the second consecutive quarterly decline
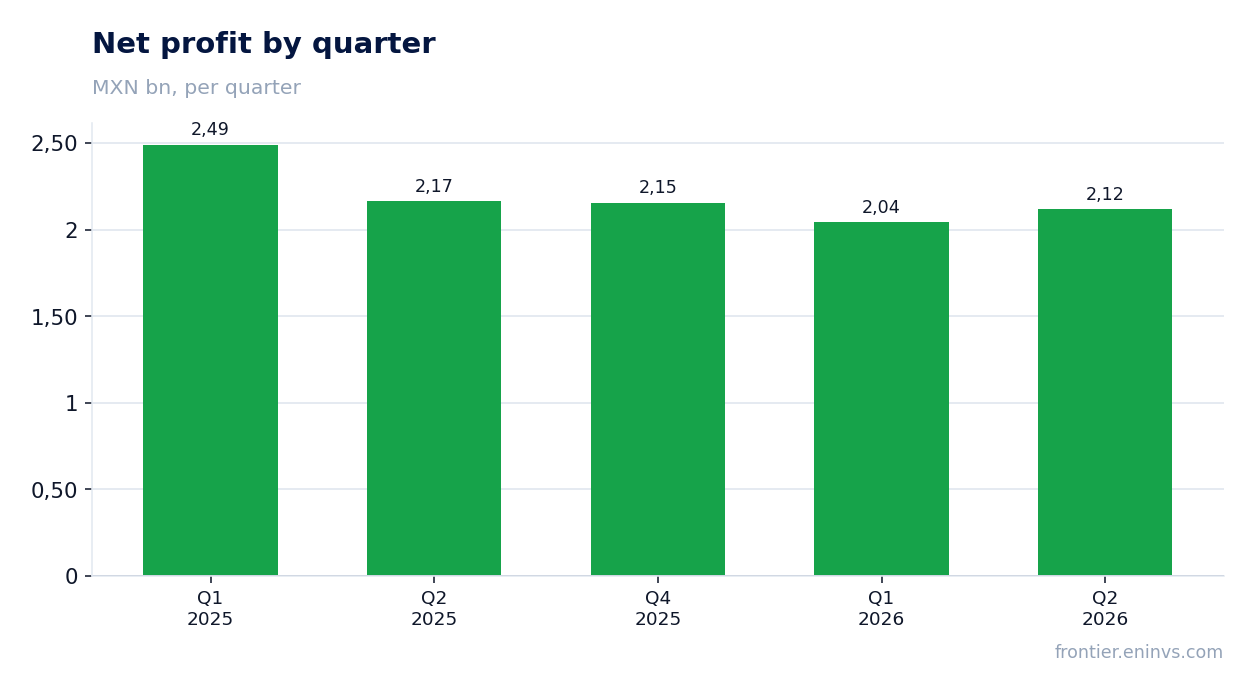
In Q2 2026, net profit came in at 2,118 million pesos, down 2.2% from the same period last year. This extends the negative trend: in Q1 2026, profit also declined, to 2,041.5 million pesos from 2,491.1 million pesos a year earlier. The profit decline comes amid a fall in net interest income, the bank's main revenue source.
Quarterly profit over the last four quarters has fluctuated in a narrow range from 2,041.5 to 2,166.0 million pesos, indicating business stability but not growth. Over the trailing twelve months, net profit reached 9,079 million pesos, only marginally above the year-ago level. The bank is profitable, but growth has stalled.
Net interest income has fallen for two straight quarters: down 6.8% in Q1 2026 and down 2.9% in Q2 2026
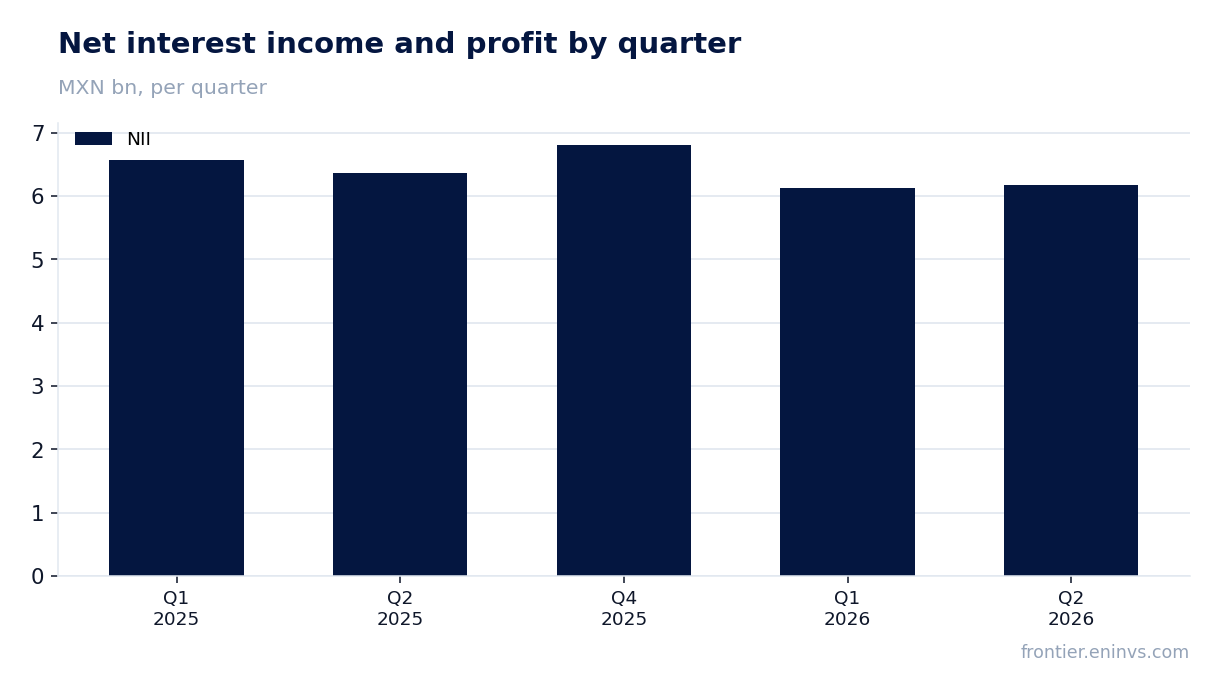
Net interest income in Q2 2026 was 6,172 million pesos, down 2.9% year on year. In Q1 2026, the decline was steeper at 6.8% year on year, to 6,127.9 million pesos. This is a key metric for the bank, and its decline directly limits profit growth potential.
Over the trailing twelve months, net interest income reached 26,200 million pesos. However, quarterly dynamics show that income is not growing but fluctuating around 6.1–6.8 billion pesos. The decline is due to pressure on the interest margin, which the bank has not yet been able to offset by increasing lending volumes. Without a reversal of this trend, profit is unlikely to show sustained growth.
Return on equity at 17.4% remains high, but trailing-twelve-month profit of 9,079 million pesos is only marginally above the year-ago level
Return on equity (ROE) over the trailing twelve months stands at 17.4%, a high level for the banking sector. However, absolute profit for the same period – 9,079 million pesos – shows that the bank is not increasing profit but merely maintaining it. A high ROE with stagnant profit means capital is not growing quickly, limiting the scope for dividend increases.
Maintaining ROE at 17.4% amid declining net interest income may be possible through cost control or one-off factors, but the sustainability of this level is questionable. If net interest income continues to fall, ROE will also start to decline, putting pressure on the stock's valuation.
The 8.25% dividend yield is more than double the key rate, making the stock attractive for income, but the payout depends on sustaining current profit
The dividend yield over the trailing twelve months is 8.25%. This is more than double the current key rate, making the stock attractive for income-oriented investors. With a P/E of 7.6, the market values the bank cheaply relative to its earnings.
However, dividend sustainability depends on the bank's ability to maintain profit at current levels. Over the trailing twelve months, net profit was 9,079 million pesos, and if it declines, dividend payments could be cut. Q2 2026 profit already fell 2.2% year on year, and a continuation of this trend poses a risk to the dividend.
A P/E of 7.6 and ROE of 17.4% imply a fair value about 12% above the current price on the portal's model
According to the portal's model, which compares ROE to P/B, the fair value of the stock is about 12% above the current market price. This indicates potential upside for the investor. The model is based on current profitability metrics and capital valuation, and if ROE remains at 17.4%, the stock may be undervalued.
However, the model does not account for the risk of declining profit. If net interest income continues to fall, ROE could decline, and fair value would be lower. Thus, the current valuation is attractive, but its realisation depends on stabilising the bank's revenues.
Capex rose to 156.9 million pesos in Q1 2026, but it does not offset the decline in net interest income, and margin pressure persists
In Q1 2026, capital expenditures amounted to 156.9 million pesos. This is the only quarter with disclosed capex, and its volume is small relative to quarterly profit of 2,041.5 million pesos. The investments may be aimed at technological upgrades or expansion, but so far they have not led to an increase in net interest income.
Margin pressure persists: net interest income has fallen for two consecutive quarters. Without an increase in lending volumes or higher loan rates, it will be difficult for the bank to reverse this trend. Capex alone does not solve the revenue problem, and investors should monitor interest margin dynamics in upcoming reports.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 69.0 bn MXN |
| P/E (LTM) | 7.6 |
| P/B | 1.44 |
| ROE | 17.4% |
| Dividend yield (12m) | 8.3% |
Bottom line
Bottom line: in Q2 2026, net profit fell 2.2% year on year to 2,118 million pesos, while net interest income dropped 2.9%. The bank remains highly profitable (ROE 17.4%) and pays generous dividends (8.25% yield), but revenue growth is absent. According to the portal's model, the stock is undervalued by 12%, making it rather attractive for income-oriented investors. However, a reversal in net interest income dynamics is needed for sustainable capital growth; otherwise, the dividend may be at risk.
Open the company's financial profile BBAJIO →
See also: market overview · valuation map · stock screeners