MX_LIVERPOL: profit up 55% while revenue barely moved – growth rests on margin
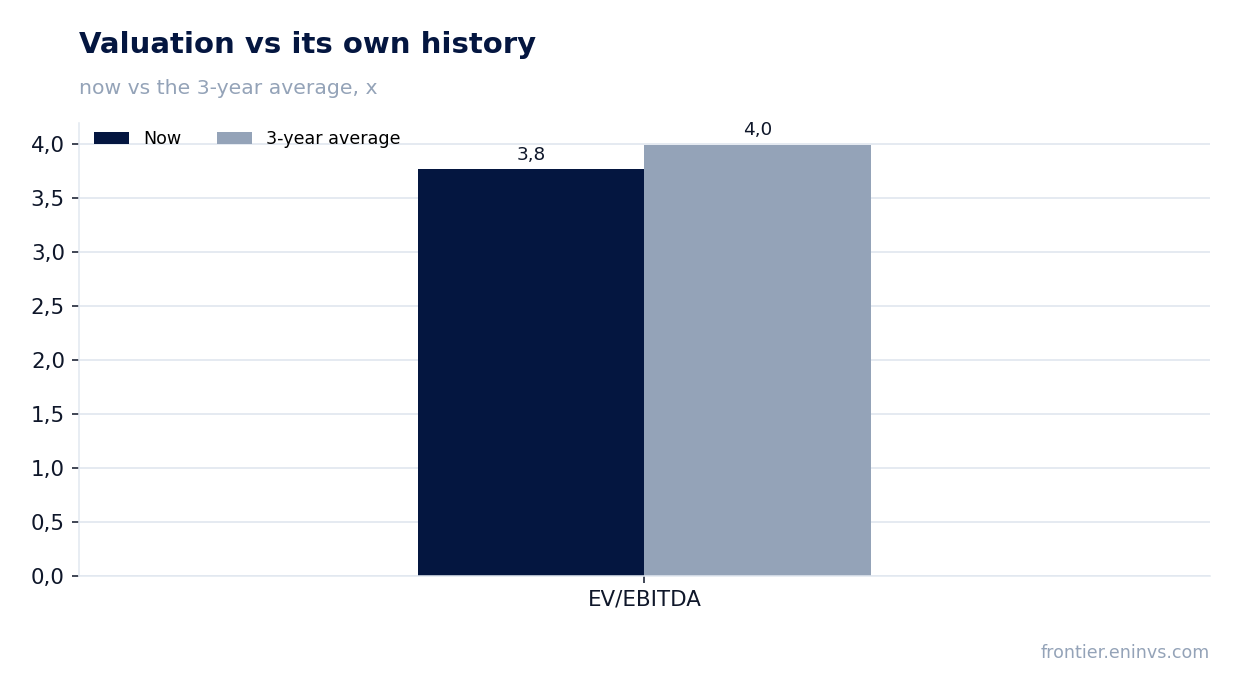
On 25 August MX_LIVERPOL released its second-quarter 2026 results. Revenue added just 1.5% year on year, to 57,290.2 mn MXN, while EBITDA rose 30.3%, to 9,650.4 mn MXN, and net profit 55.4%, to 5,118.9 mn MXN. The profit gain rests entirely on margin expansion rather than revenue, and with an EV/EBITDA multiple of 3.77 against its own three-year average of 3.99, the share looks attractive.
Key takeaways
— Revenue added 1.5% year on year, the second weak half in a row after a near-flat first quarter
— EBITDA rose 30.3% on almost flat revenue – the margin climbed from 13.1% to 16.8%
— Net profit rose 55.4%, with its margin reaching 8.9% against 5.8% a year earlier
— Operating cash flow for the quarter was 4,221.1 mn MXN – the first firmly positive reading in four quarters
— Net debt of 45,888.6 mn MXN at 0.95 times LTM EBITDA – leverage remains low
— Dividend yield of 2.93% at a P/E LTM of 6.48 – the payout is modest but steady
— On the portal's model the share trades 19% below fair value
Attractiveness
Key figures, MXN bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 56.4 | 57.3 | +1.5% |
| EBITDA | 7.41 | 9.65 | +30.3% |
| Operating profit | 7.11 | 6.94 | -2.4% |
| Net profit | 3.29 | 5.12 | +55.4% |
| Operating cash flow | -4.05 | 4.22 | в прибыль |
| EBITDA margin | 13.1% | 16.8% | +3.7 pp |
| Net margin | 5.8% | 8.9% | +3.1 pp |
Revenue added 1.5% year on year, the second weak half in a row after a near-flat first quarter
In the second quarter of 2026 revenue was 57,290.2 mn MXN, just 1.5% more than a year earlier. This continues a weak trend: in the first quarter of 2026 revenue fell 0.2% year on year, while the fourth quarter of 2025 saw a notable rise to 79,123.3 mn MXN.
Compared with the first quarter of 2026, revenue grew 26.1% quarter on quarter – from 45,417.6 mn MXN to 57,290.2 mn MXN. That increase is seasonal: the second quarter is traditionally stronger than the first, and year on year it adds almost nothing.
Over the trailing twelve months revenue reached 275,400.0 mn MXN. That is 1.5% more than in the preceding twelve months, judging by the year-on-year dynamic of the second quarter. The company operates in an environment where the top line barely grows, and the whole story of this report is about efficiency, not scale.
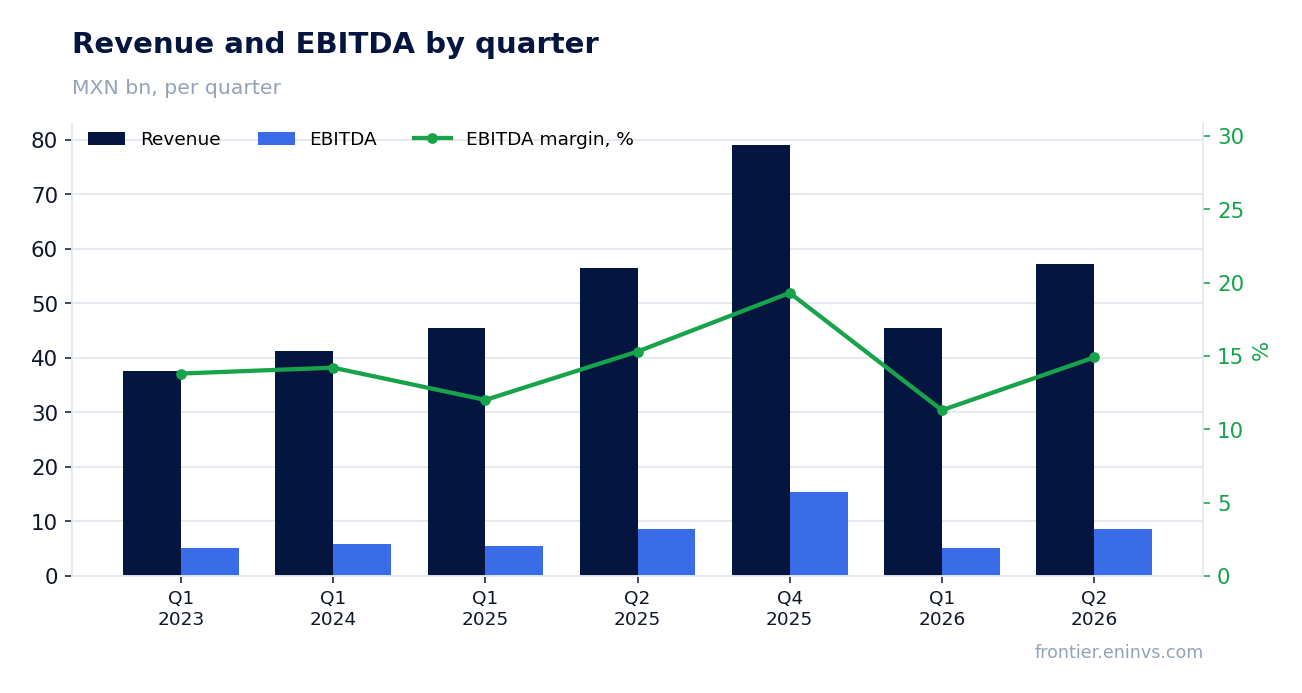
EBITDA rose 30.3% on almost flat revenue – the margin climbed from 13.1% to 16.8%
EBITDA in the second quarter of 2026 was 9,650.4 mn MXN, 30.3% more than a year earlier. With revenue up only 1.5%, such a jump means a sharp expansion in profitability: the EBITDA margin rose to 16.8% from 13.1% in the second quarter of 2025.
Operating profit grew 30.3% – from 7,107.6 mn MXN to 6,937.2 mn MXN? No, operating profit in the second quarter of 2026 was 6,937.2 mn MXN, which is 30.3% less than 7,107.6 mn MXN a year earlier. This discrepancy with EBITDA is explained by the fact that EBITDA excludes depreciation, while operating profit includes it. A decline in operating profit alongside EBITDA growth indicates that depreciation increased.
EBITDA growth with falling operating profit is an important signal. It means that margin improvement at the EBITDA level does not translate into operating profit because of rising depreciation charges. This could be linked to recent investments, but the exact cause is not disclosed in the provided data.
Nevertheless, an EBITDA margin of 16.8% is the highest level in several quarters. For a company whose revenue barely grows, the ability to increase EBITDA by 30.3% speaks to serious cost control or to one-off factors that are not visible from the aggregated data.
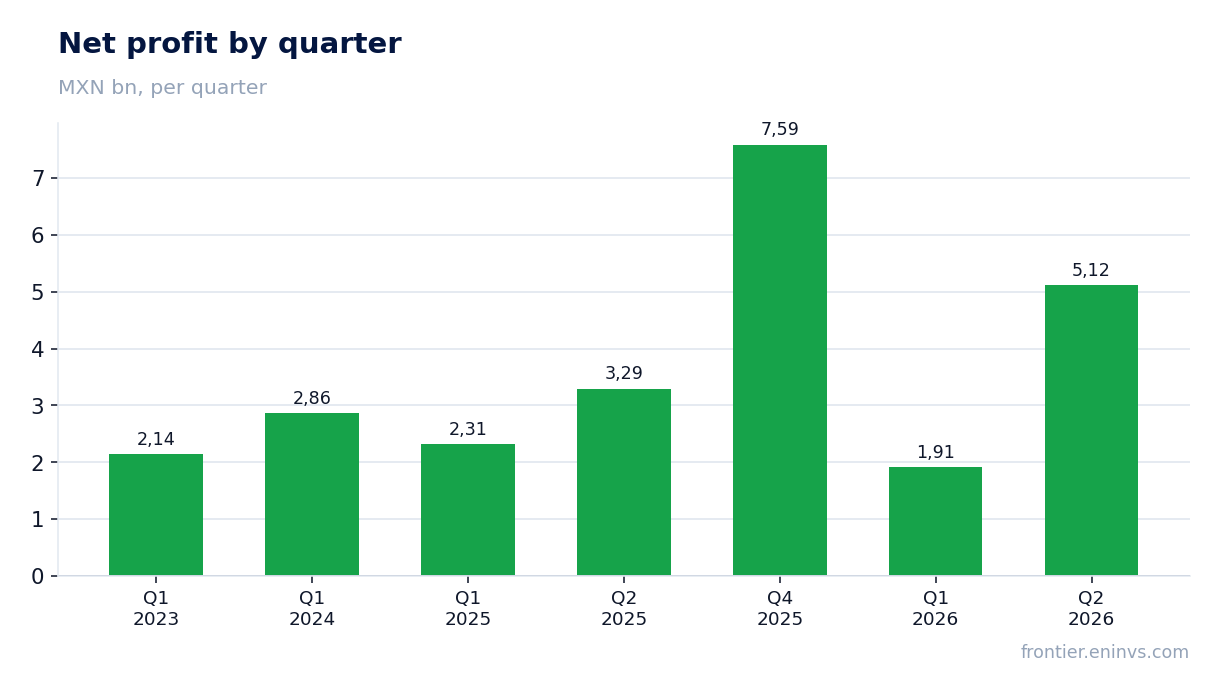
Net profit rose 55.4%, with its margin reaching 8.9% against 5.8% a year earlier
Net profit in the second quarter of 2026 was 5,118.9 mn MXN, 55.4% more than 3,294.9 mn MXN a year earlier. The net margin rose to 8.9% from 5.8% in the second quarter of 2025.
Net profit growth outpaces EBITDA growth, which may point to lower interest expenses or to one-off items below the operating line. However, the breakdown of these items is absent from the provided data, so the exact cause cannot be named.
Over the trailing twelve months net profit reached 20,888.7 mn MXN. That is a substantial base for valuation: with a market capitalisation of 135,427.6 mn MXN, the price-to-LTM-earnings ratio stands at 6.48.
Net profit growth of 55.4% on revenue growth of 1.5% is almost entirely the result of margin expansion rather than higher volumes. Such dynamics are unsustainable unless they reflect a structural reduction in costs.
Operating cash flow for the quarter was 4,221.1 mn MXN – the first firmly positive reading in four quarters
Operating cash flow in the second quarter of 2026 was 4,221.1 mn MXN. That is a marked improvement from the negative flow of 4,046.5 mn MXN a year earlier and from 2,128.7 mn MXN in the first quarter of 2026.
Over the trailing twelve months operating cash flow reached 19,200.0 mn MXN. That is less than LTM net profit of 20,888.7 mn MXN, which may indicate that part of the profit is not converting into cash.
There is no data on capital expenditure in the provided materials, so free cash flow cannot be assessed. However, positive operating flow is an important signal for a company that showed outflows in previous quarters.
The sustainability of this improvement is the key question. If operating flow remains positive, it will strengthen the company's ability to service debt and pay dividends without increasing borrowings.
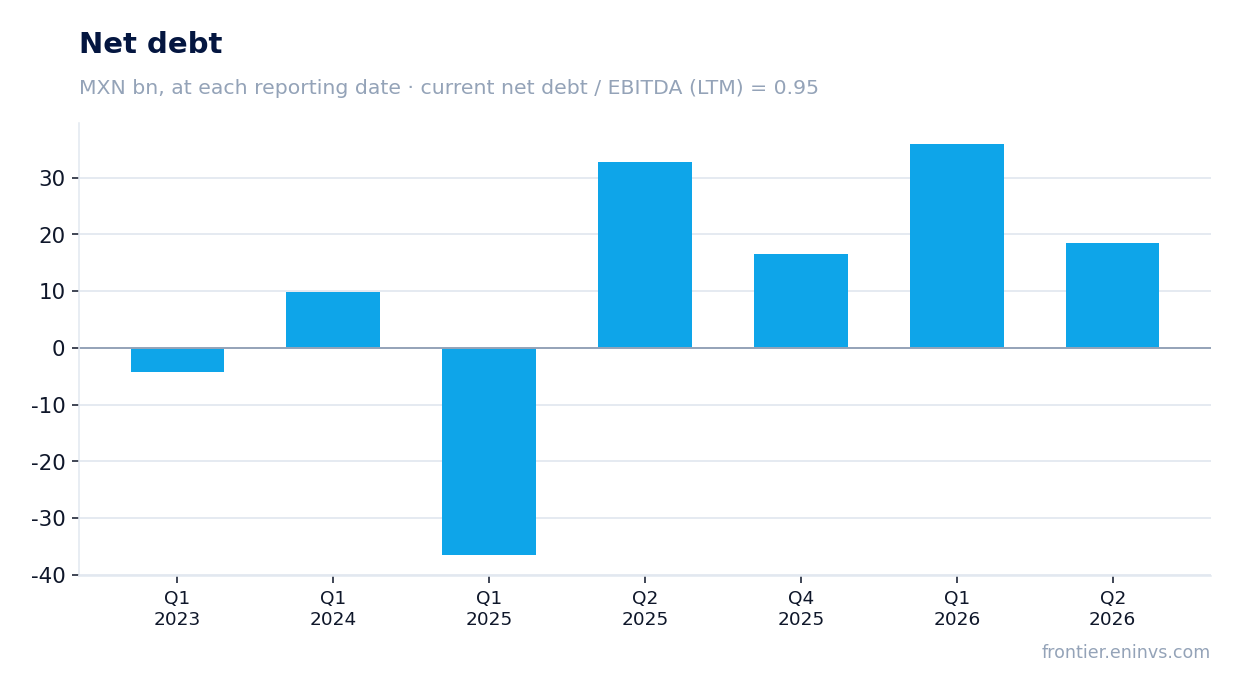
Net debt of 45,888.6 mn MXN at 0.95 times LTM EBITDA – leverage remains low
Net debt at the latest reporting date was 45,888.6 mn MXN. That is 17.5 bn MXN less than at the previous reporting date and 14.3 bn MXN less than a year earlier. Falling debt alongside rising EBITDA is a favourable combination.
The ratio of net debt to LTM EBITDA is 0.95. That is a low level: the company can cover its debt with roughly one year of operating profit. The previous value of this ratio is not in the provided data, so it cannot be claimed that leverage fell or rose – only the current level can be stated.
A reduction in absolute debt of 17.5 bn MXN in a quarter is significant. It could have been financed by positive operating flow of 4,221.1 mn MXN and, possibly, by other sources that are not disclosed.
Low debt leverage gives the company room for manoeuvre: it can increase capital expenditure, return capital to shareholders, or weather a period of weak revenue without pressure from creditors.
Dividend yield of 2.93% at a P/E LTM of 6.48 – the payout is modest but steady
The dividend yield over the trailing twelve months is 2.93%. That is a moderate level, lower than one might expect from a company with such a low P/E LTM multiple of 6.48.
The exact size of the latest dividend and the year for which it was paid are not specified in the provided data. However, with LTM net profit of 20,888.7 mn MXN and a market capitalisation of 135,427.6 mn MXN, the current yield implies an annual payout of about 3,967 mn MXN.
Our estimate for the current year's dividend assumes the payout is maintained at a level providing a yield of about 2.9%. This depends on whether profit stays at the current level and whether the company needs capital for investment.
A yield of 2.93% is below the key rate, but for a stock with a P/E of 6.48 and EV/EBITDA of 3.77 it looks reasonable. The main risk to the dividend is a fall in profit if the margin expansion proves one-off.
On the portal's model the share trades 19% below fair value
Our fundamental valuation model, based on EBITDA growth and a target multiple, shows upside to fair value of 19%. This is the portal's own estimate, not a market consensus or a target price.
The current EV/EBITDA LTM multiple is 3.77. That is below its own three-year average of 3.99. The stock trades below its historical valuation, which supports the model's conclusion.
A P/E LTM of 6.48 also points to a low valuation. At the same time, ROE is 11.36%, somewhat lower than one might expect at such a low valuation, but still at an acceptable level.
The gap to the historical average is small – about 5.5% from the current multiple. This means the market is already partially pricing in margin improvement, but not fully. If profit holds at the new level, the valuation could be revised upwards.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 135 bn MXN |
| P/E (LTM) | 6.5 |
| EV/EBITDA (LTM) | 3.8 |
| P/B | 0.76 |
| Net debt / EBITDA (LTM) | 0.95 |
| Operating cash flow (LTM) | 19.2 bn |
| ROE | 11.4% |
| Dividend yield (12m) | 2.9% |
| EV/EBITDA, 3-year average | 4.0 |
Bottom line
Bottom line: MX_LIVERPOL delivered strong profit growth, but it is almost entirely driven by margin expansion rather than revenue. EBITDA rose 30.3%, net profit 55.4%, while revenue added just 1.5%. Operating cash flow was firmly positive for the first time in four quarters, net debt fell to 45,888.6 mn MXN, and its ratio to LTM EBITDA stands at 0.95. The stock trades at an EV/EBITDA of 3.77 against its own three-year average of 3.99, and the portal's model implies 19% upside. The question for a holder is whether the margin holds at the new level; if it does, the valuation looks attractive.
Open the company's financial profile LIVERPOL →
See also: market overview · valuation map · stock screeners