Aeroflot: profit down 76%, but a 16.5% dividend yield holds the stock
On 18 September Aeroflot reported results for the second quarter of 2026. Revenue rose 1.8% year on year to RUB 228.6 bn, but EBITDA fell 43% to RUB 52.7 bn and net profit dropped 76% to RUB 11.4 bn. The EBITDA margin compressed to 23.0% from 41.2% a year earlier. At the same time, the stock trades at a P/E of 4.2 and EV/EBITDA of 5.0 versus a three-year average of 4.0, while the trailing twelve-month dividend yield is 16.5% against what we consider a fair yield of 8.0%. The valuation looks attractive for a dividend investor, but the sustainability of the payout depends on profit recovery.
Key takeaways
— Revenue grew just 1.8% – growth slowed despite flight programme expansion
— EBITDA fell 43% as fuel and staff costs outpaced revenue
— Net profit dropped 76% – prior-year one-off gains did not repeat
— Net debt/EBITDA of 4.05 is high, but a RUB 30.6 bn reduction in net debt during the quarter provides breathing room
— Dividend yield of 16.5% is above fair, but the payout may be cut
— Valuation at P/E 4.2 and EV/EBITDA 5.0 is above the three-year average, limiting upside
Attractiveness
Key figures, RUB bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 225 | 229 | +1.8% |
| EBITDA | 92.4 | 52.7 | -43.0% |
| Operating profit | 63.5 | 24.3 | -61.8% |
| Net profit | 47.4 | 11.4 | -76.0% |
| Operating cash flow | 52.1 | 48.0 | -7.9% |
| Capex | 70.7 | 14.1 | -80.0% |
| EBITDA margin | 41.2% | 23.0% | -18.2 pp |
| Net margin | 21.1% | 5.0% | -16.1 pp |
Revenue grew just 1.8% – growth slowed despite flight programme expansion
In the second quarter of 2026, Aeroflot's revenue amounted to RUB 228.6 bn, up 1.8% year on year. This is a marked slowdown from growth of 10.3% in Q2 2025 and 5.7% in Q1 2026. Scheduled passenger traffic was the main contributor, with revenue of RUB 214.8 bn, while cargo traffic brought in RUB 7.8 bn.
According to the report, the flight programme continued to expand on domestic and international routes, and passenger seat occupancy increased, which should have supported revenue. However, the growth rate was the lowest in several quarters. This may indicate demand saturation or a high base effect from last year, when revenue grew 10.3%.
For the investor, it is important that the revenue slowdown occurs against the backdrop of ongoing sanctions and closed airspace in several countries. The company continues to optimise its route network, but further revenue growth is likely to be constrained.
EBITDA fell 43% as fuel and staff costs outpaced revenue
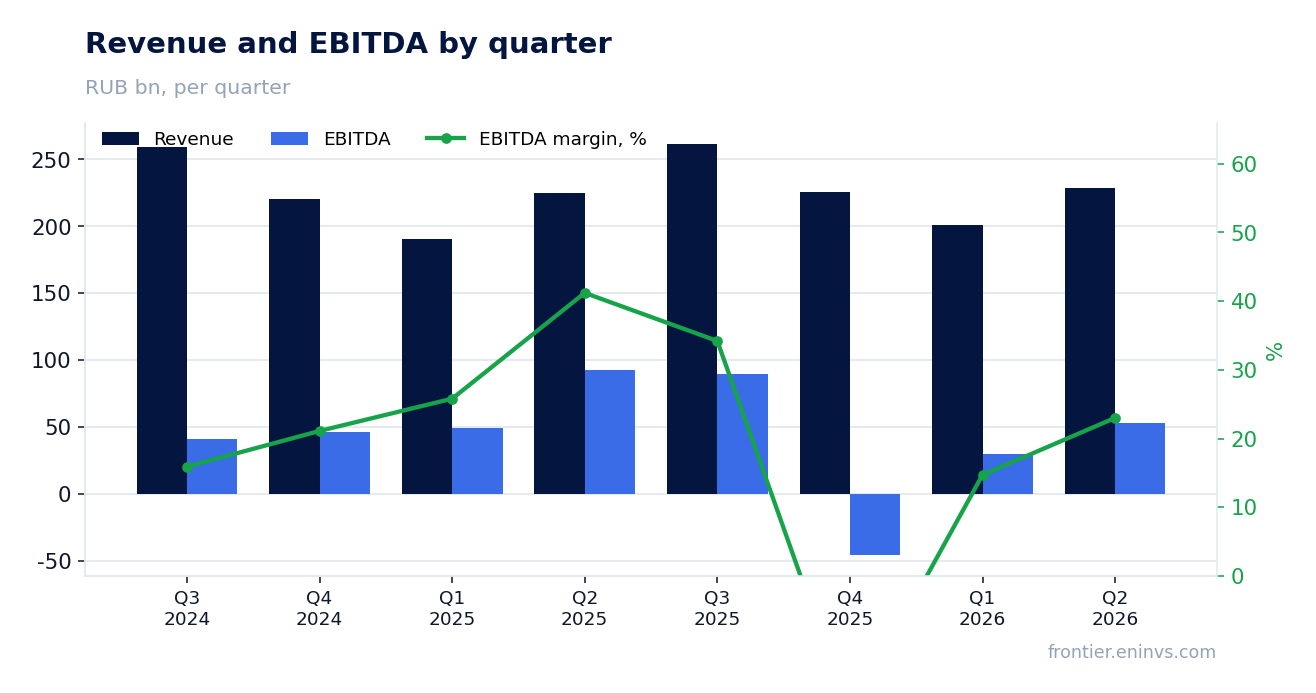
EBITDA in Q2 2026 was RUB 52.7 bn, down 43% from RUB 92.4 bn a year earlier. The EBITDA margin compressed to 23.0% from 41.2%. The main reason is the outpacing growth of operating expenses. Fuel costs rose to RUB 92.2 bn from RUB 74.0 bn, and staff costs increased to RUB 35.2 bn from RUB 29.6 bn.
Total operating expenses, excluding staff costs and depreciation, increased to RUB 176.3 bn from RUB 153.6 bn a year earlier. Thus, cost growth significantly outpaced revenue growth, leading to margin compression. The report also notes an increase in aircraft maintenance and airport service costs.
Such a sharp drop in EBITDA is a key negative of the report. While in previous quarters the company demonstrated high margins, now it has returned to a level seen before the pandemic. Profit recovery will require either accelerated revenue growth or cost containment.
Net profit dropped 76% – prior-year one-off gains did not repeat
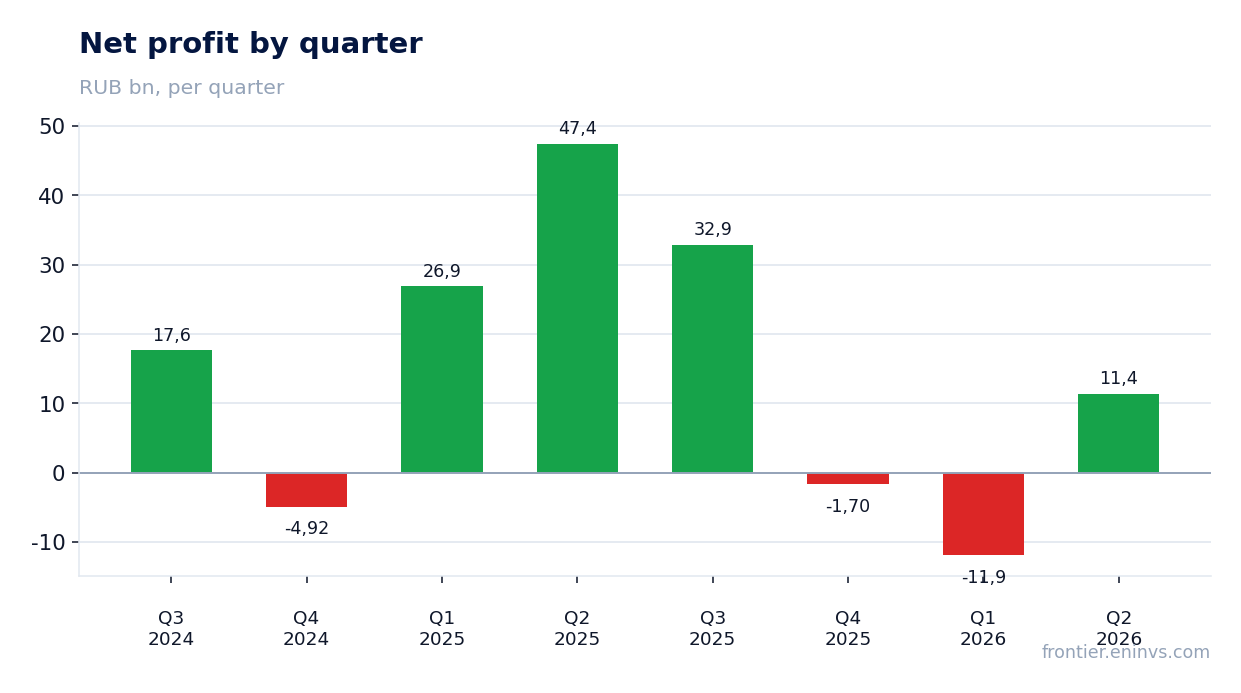
Net profit in Q2 2026 was RUB 11.4 bn, down 76% from RUB 47.4 bn a year earlier. The net margin fell to 5.0% from 21.1%. Besides weak EBITDA, financial expenses weighed on profit: interest expenses rose to RUB 7.6 bn from RUB 3.7 bn, and lease interest expenses amounted to RUB 4.9 bn.
In the previous year, significant one-off factors contributed to profit. In particular, the H1 2025 report reflected a gain from early termination of lease contracts of RUB 32.4 bn, which did not repeat in 2026. Also in 2025, a gain from writing off accounts payable of RUB 4.6 bn was recorded. These inflows artificially inflated the comparison base.
Excluding one-off factors, the current quarter's profit looks more sustainable, but it remains under pressure from high interest expenses and weak operating efficiency. To grow net profit, the company needs to improve operating margin and reduce debt burden.
Net debt/EBITDA of 4.05 is high, but a RUB 30.6 bn reduction in net debt during the quarter provides breathing room
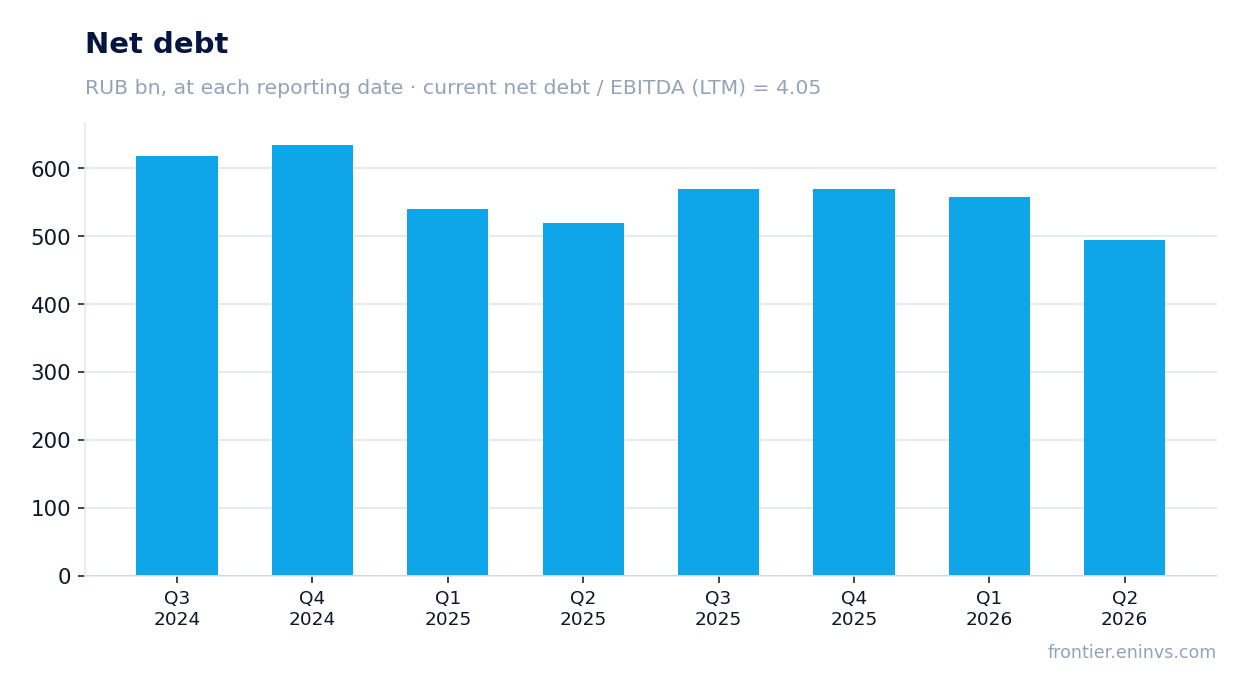
Net debt at the end of Q2 2026 was RUB 495.1 bn, down RUB 30.6 bn from the previous reporting date. However, over the last 12 months net debt increased by RUB 35.4 bn. The net debt to EBITDA ratio for the trailing twelve months is 4.05. This is a high level that limits the company's financial flexibility.
Operating cash flow in Q2 2026 was RUB 48.0 bn, which financed capital expenditures of RUB 14.1 bn and partially repaid debt. However, interest expenses remain significant: interest expenses on loans and borrowings alone amounted to RUB 7.6 bn for the quarter.
The reduction in net debt during the quarter is a positive signal, but the sustainability of this trend is questionable. If weak EBITDA and high interest expenses persist, the debt burden may continue to weigh on profit and dividend capacity.
Dividend yield of 16.5% is above fair, but the payout may be cut
Over the last 12 months, Aeroflot paid dividends of RUB 5.29 per share, providing a yield of 16.5% to the current price. This is significantly above what we consider a fair yield of 8.0% and the central bank key rate of 14.0%. The payout for 2026 has already been made, and no further payout is planned this calendar year.
Our estimate for the dividend for the current financial year (to be paid next year) is RUB 1.54 per share, corresponding to a yield of 4.7% on the current price. We calculate it as 20% of trailing twelve-month net profit, which matches the share of profit paid out last year. This is our estimate; the board makes the final decision.
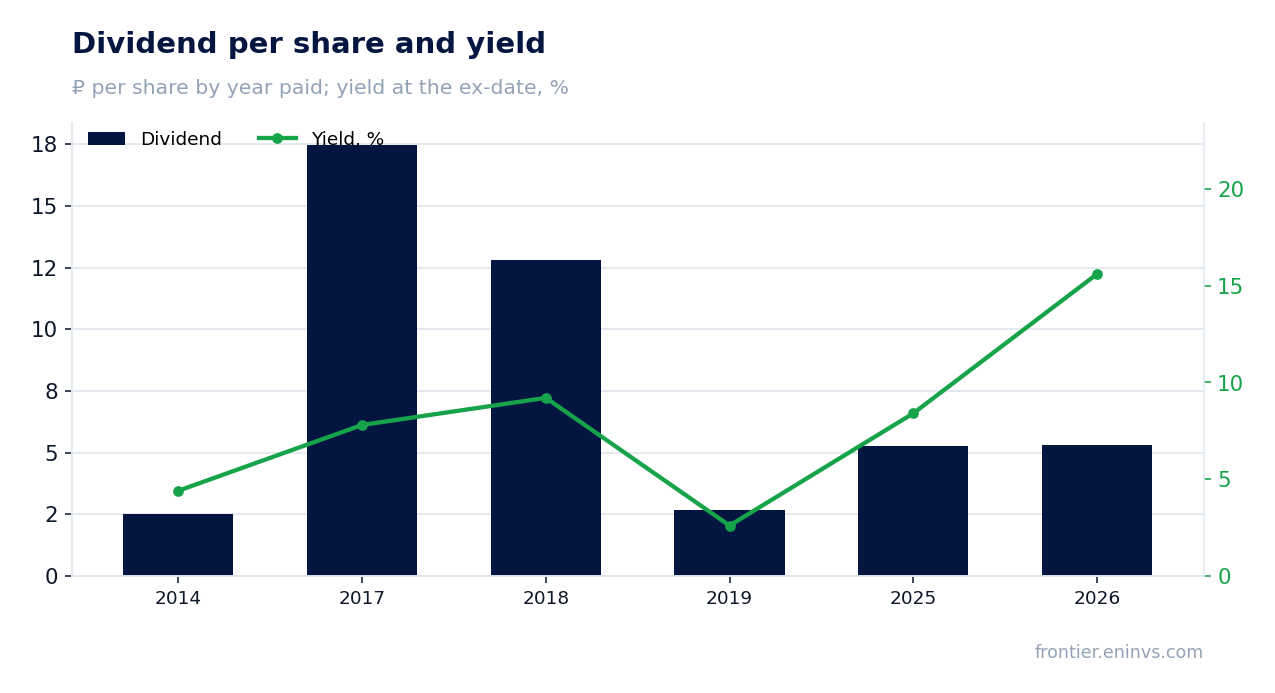
Aeroflot's historical dividend yields have been volatile: from 2.6% in 2019 to 15.6% in 2026. The current high yield is explained by the low share price. If profit does not recover, the company may cut the payout, and the yield will fall. The key risk is further pressure on profit from high costs and debt burden.
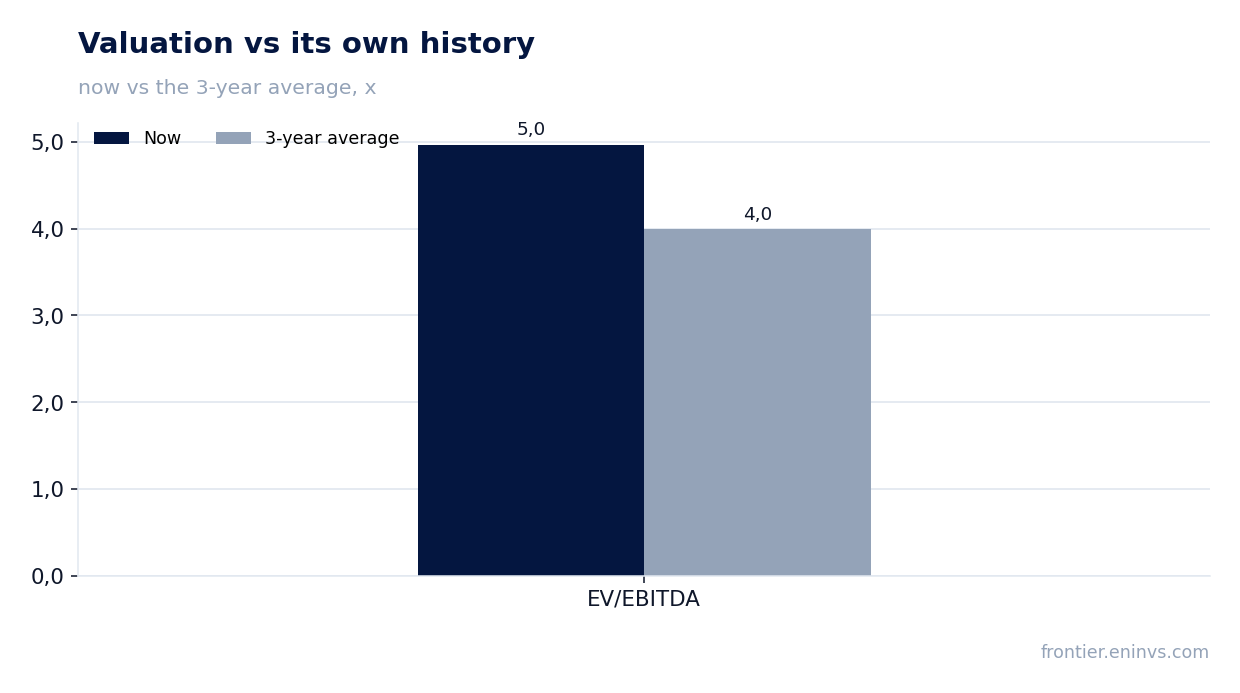
Valuation at P/E 4.2 and EV/EBITDA 5.0 is above the three-year average, limiting upside
According to our calculations, Aeroflot shares trade at a P/E of 4.2 and EV/EBITDA of 5.0. The three-year average EV/EBITDA is 4.0. Thus, the current valuation is above its own historical average, which may indicate limited upside. For comparison, the dividend yield of 16.5% looks attractive, but it may be unsustainable.
Our fundamental valuation model, which considers EBITDA growth and a target multiple, shows a downside to fair value of 100% (the value is at the model's lower bound). This is our own model, not a consensus forecast. It reflects high risks associated with debt burden and weak profit.
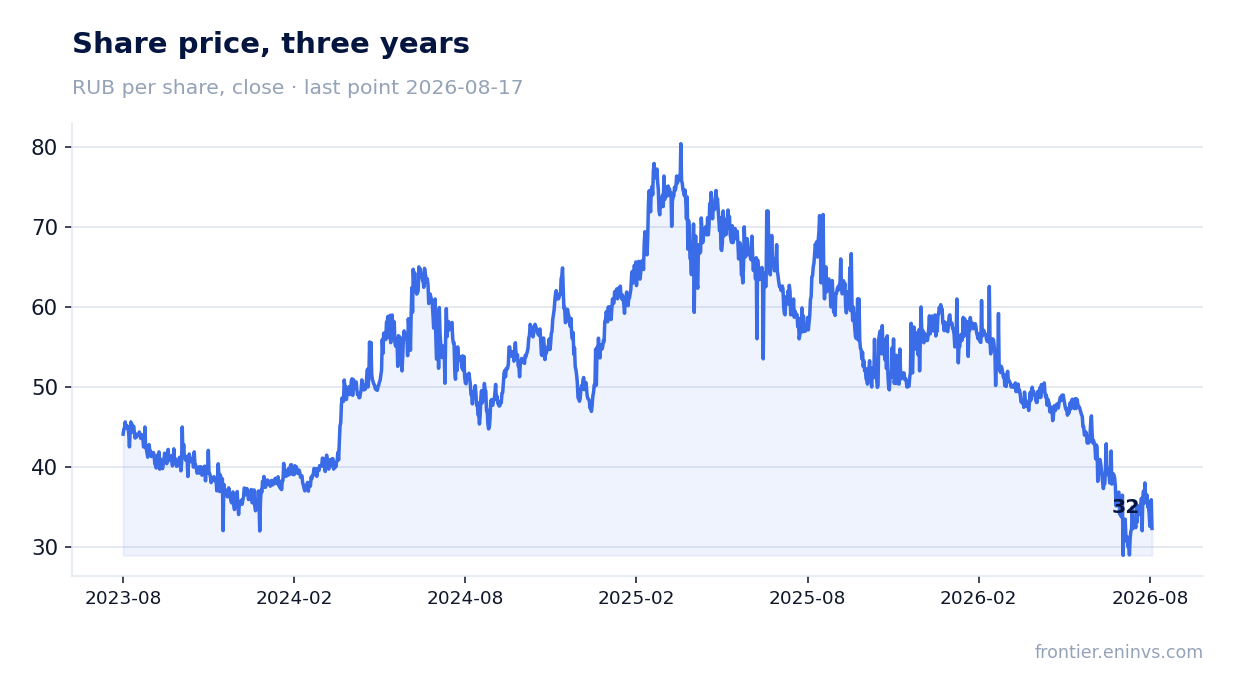
The market appears to have already priced in the company's challenges: the low P/E and high dividend yield may be compensation for risks. A re-rating upwards would require sustainable profit growth and debt reduction. So far, these prerequisites are insufficient.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 129 bn ₽ |
| P/E (LTM) | 4.2 |
| EV/EBITDA (LTM) | 5.0 |
| P/B | 2.55 |
| Net debt / EBITDA (LTM) | 4.05 |
| Operating cash flow (LTM) | 164 bn |
| ROE | 156.3% |
| Dividend yield (12m) | 16.5% |
| EV/EBITDA, 3-year average | 4.0 |
Dividend per share, ₽, and yield at the ex-date
| Year paid | Dividend | Yield |
|---|---|---|
| 2014 | 2.50 | 4.4% |
| 2017 | 17.48 | 7.8% |
| 2018 | 12.81 | 9.2% |
| 2019 | 2.69 | 2.6% |
| 2025 | 5.27 | 8.4% |
| 2026 | 5.29 | 15.6% |
| Our estimate, current year | 1.54 | 4.7% on the current price |
Bottom line
Bottom line: Aeroflot reported Q2 2026 with a 76% drop in profit and a 43% fall in EBITDA. Weak operating dynamics and rising costs outweighed 1.8% revenue growth. However, a dividend yield of 16.5% and a RUB 30.6 bn reduction in net debt during the quarter support the investment case. Valuation at P/E 4.2 and EV/EBITDA 5.0 is above the three-year average, limiting upside. For a dividend investor, the stock looks attractive, but the sustainability of the payout depends on profit recovery.
Open the company's financial profile AFLT →
See also: market overview · valuation map · stock screeners