GDP growth 2026 (proj.)1.0%Inflation YoY (proj.)6.0%FX vs USD (3y avg p.a.)-5.1%Macro: IMF World Economic Outlook, April 2026 (Annex tables 1.1.2–1.1.4)
Our recommended portfolios
Performance & current holdings of our strategies for this market — why it makes sense to join.
AI conviction (Claude)Model portfolio: 15 Jun 2026
Three-year models: revenue and margin from four independent sources, dividends from the company's policy, exit at today's multiple without re-rating. 'Model error' is the median EBITDA miss (profit for banks) in the backtest, with the number of measurements.
Build a moderately diversified income portfolio from our coverage — with quality and liquidity gates and per-issuer-group limits. Profiles: insurer, corporate treasury, qualified individual.
ММК 6,2% · ФосАгро 5,3% · Московский кредитный банк 5,0%
Смешанные фонды — выходят ли из акций
β к IMOEX = оценка доли акций; снижение β за 3 мес против года = сокращение акций (риск-офф).
TRURТ-Капитал – Стратегия вечного — β к индексу 0,43 (3 мес 0,25)сокращают акции, топ-10 акций 16%
AKUPАльфа-Капитал Умный портфель — β к индексу 0,53 (3 мес 0,72)наращивают акции, топ-10 акций 31%
SBPSПервая – Фонд Моя цель 2035 — β к индексу 0,54 (3 мес 0,70)наращивают акции, топ-10 акций 54%
Изменения в составе за месяц(к раскрытию 31.07.2026)
SBMXПервая - Фонд Топ Российских акций + Корпоративный Центр Икс 2,5%− МКПАО Озон↑ Лукойл +1,3 п.п.↑ Татнефть +0,8 п.п.↑ Сбербанк России +0,7 п.п.↑ ГМК Норильский никель +0,5 п.п.
SCFTТехнологии будущего + ГМК Норильский никель 3,9%+ Татнефть 3,8%− Корпоративный Центр Икс− НОВАТЭК
СЧА и стоимость пая — investfunds.ru (ежедневно). «Приток» — оценка нетто-привлечения (изменение СЧА за вычетом доходности пая). Доходность — по биржевой цене (MOEX). β — бета Дименсона к IMOEX за ~год (с поправкой на несинхронность котировок). «Динамика акций» — β за 3 мес против β за год: падение = фонд сокращает долю акций (уходит в кэш/облигации), рост = наращивает. Структура активов раскрывается УК ежемесячно.
Earnings analysis
Short take-aways from recent corporate results and commodity trends.
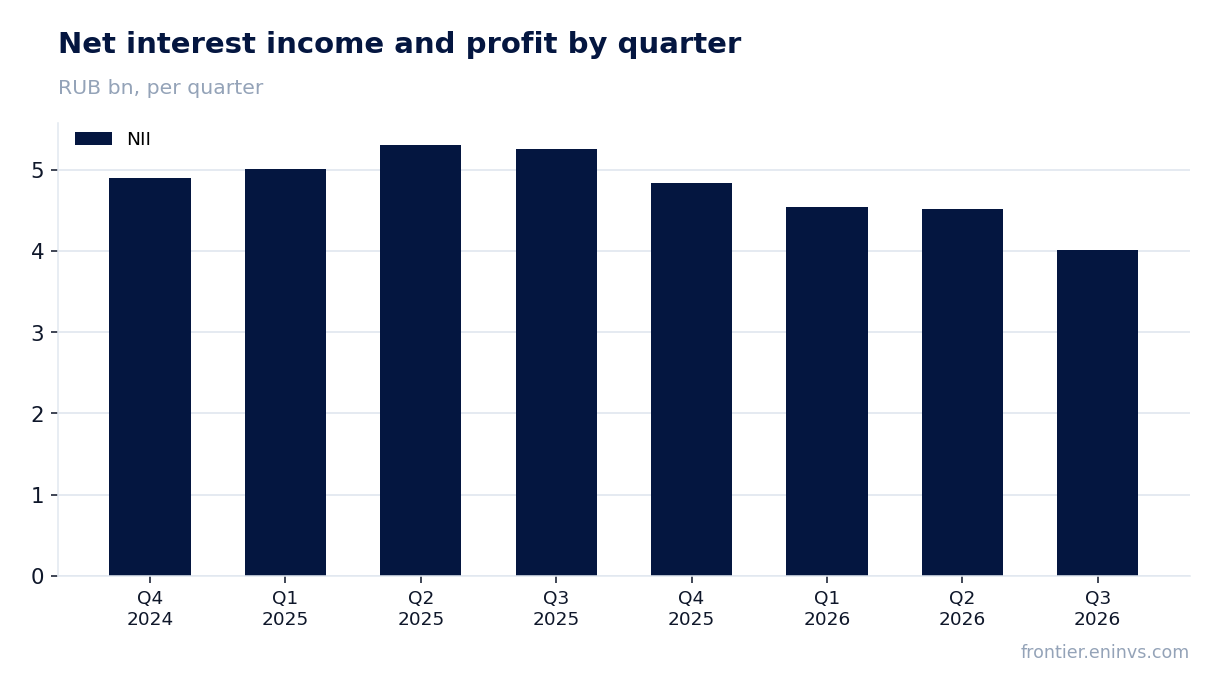
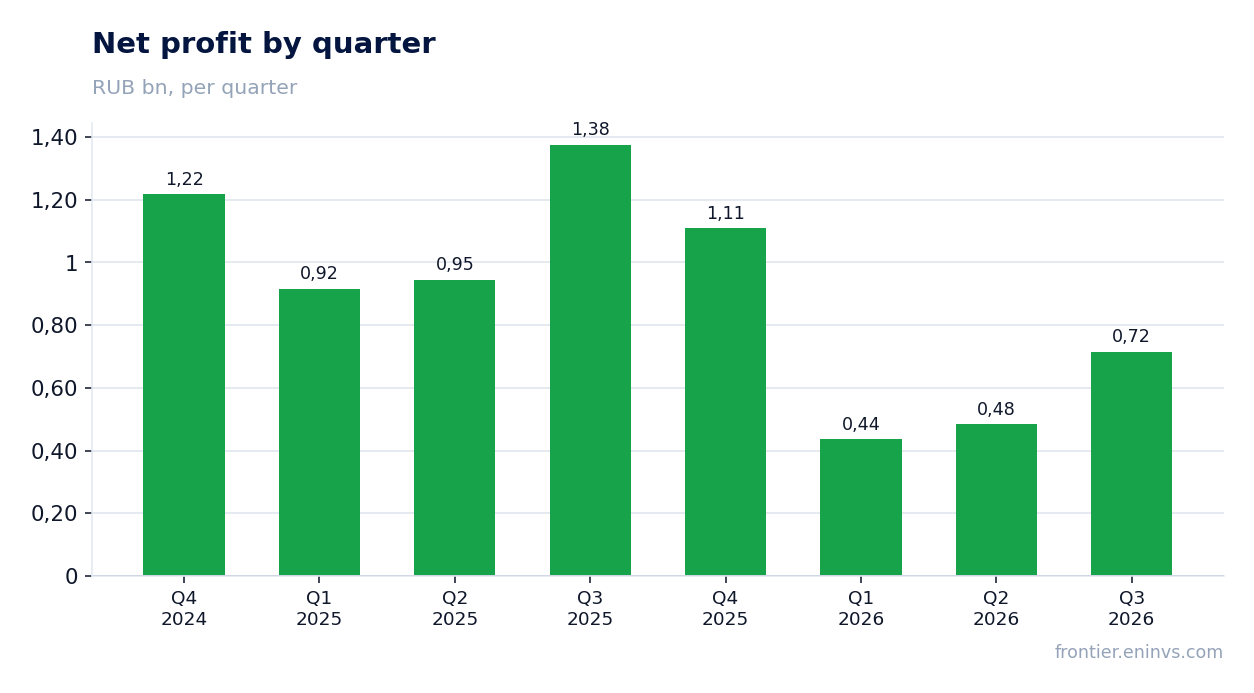
On 28 October Zaymer MFK reported third-quarter 2026 results. Net interest income came in at 4,007.5 mn RUB, down 23.8% year on year, and net profit at 715.6 mn RUB, 48.0% below the prior-year level. The top line keeps decelerating: after a 15.0% decline in the second quarter, the third quarter fell 23.8%. The stock trades at a P/E LTM of 4.8 with a 25.1% dividend yield, and the portal's model puts upside to fair value at +22%. At the current price the share looks rather attractive, but mainly on the dividend – the fundamental trend has not yet turned.
Key takeaways
— Profit fell twice as fast as revenue – the profit share of net interest income compressed from 26.2% to 17.9%
— The customer loan book shrank from 12,108.7 mn to 10,878.6 mn RUB since the start of the year
— Fee and commission income rose to 534.1 mn RUB in the quarter and partly offset the interest-income decline
— The 31.93 RUB per share dividend yields 25.1% – nearly double the 14.6% level we consider fair
— P/E LTM of 4.8 and ROE of 6.8% show the market is already pricing in further profit compression
Attractiveness
Key figures, RUB bn
Metric
Q3 2025
Q3 2026
Change
Net interest income
5.26
4.01
-23.8%
Net profit
1.38
0.72
-48.0%
Capex
0.38
0.06
-85.0%
Net margin
26.2%
17.9%
-8.3 pp
Net interest income in Q3 2026 came to 4,007.5 mn RUB versus 5,260.1 mn RUB a year earlier. This is the third consecutive quarterly decline in year-on-year terms: after -1.1% in Q4 2025, the fall accelerated to -9.3% in Q1 2026, then to -15.0% in Q2 and to -23.8% in Q3.
The main cause is the shrinking loan book. Gross customer loans fell from 33,706.1 mn RUB at end-2025 to 29,804.2 mn RUB at 30 September 2026, and the number of borrowers from 1,815,138 to 1,551,394. The company issued 32,212.9 mn RUB of new loans in nine months versus 43,189.3 mn RUB a year earlier – it deliberately scaled lending down.
The average monthly principal balance over nine months of 2026 was 17,843.7 mn RUB versus 21,093.3 mn RUB a year earlier. This confirms the decline in interest income is not a one-off but a consequence of business contraction.
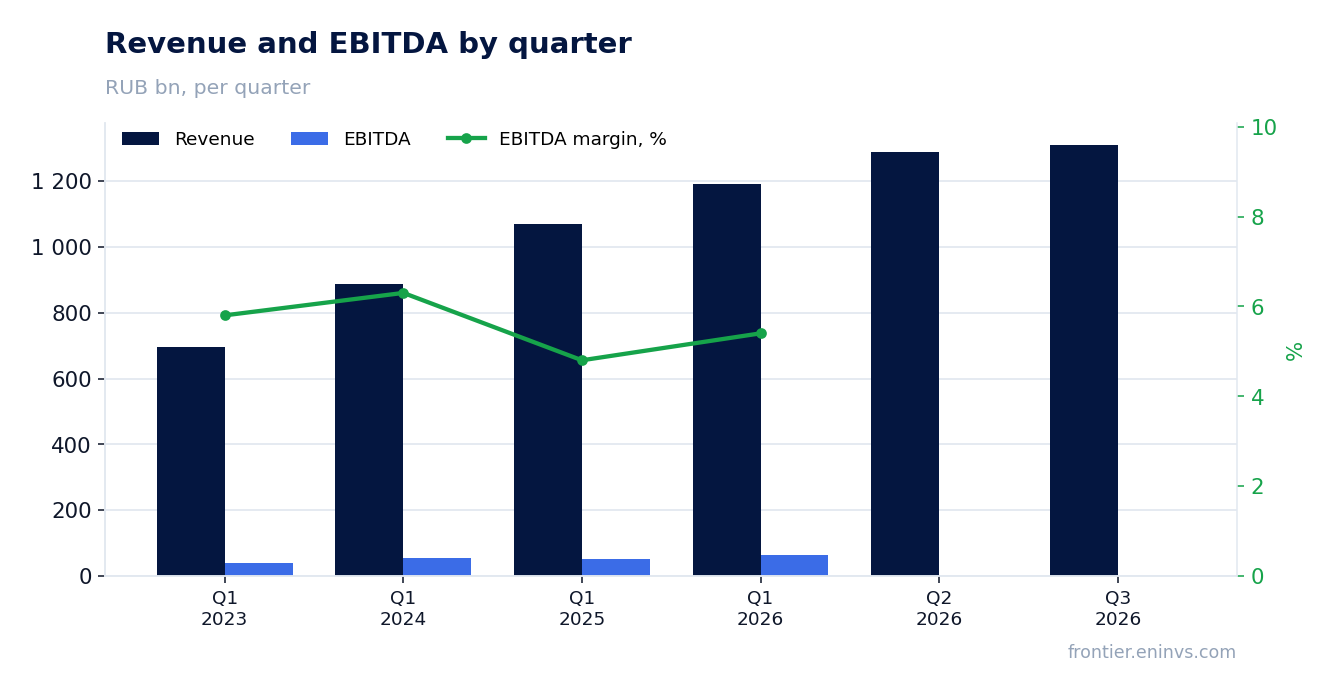
Revenue and EBITDA by quarter
Profit fell twice as fast as revenue – the profit share of net interest income compressed from 26.2% to 17.9%
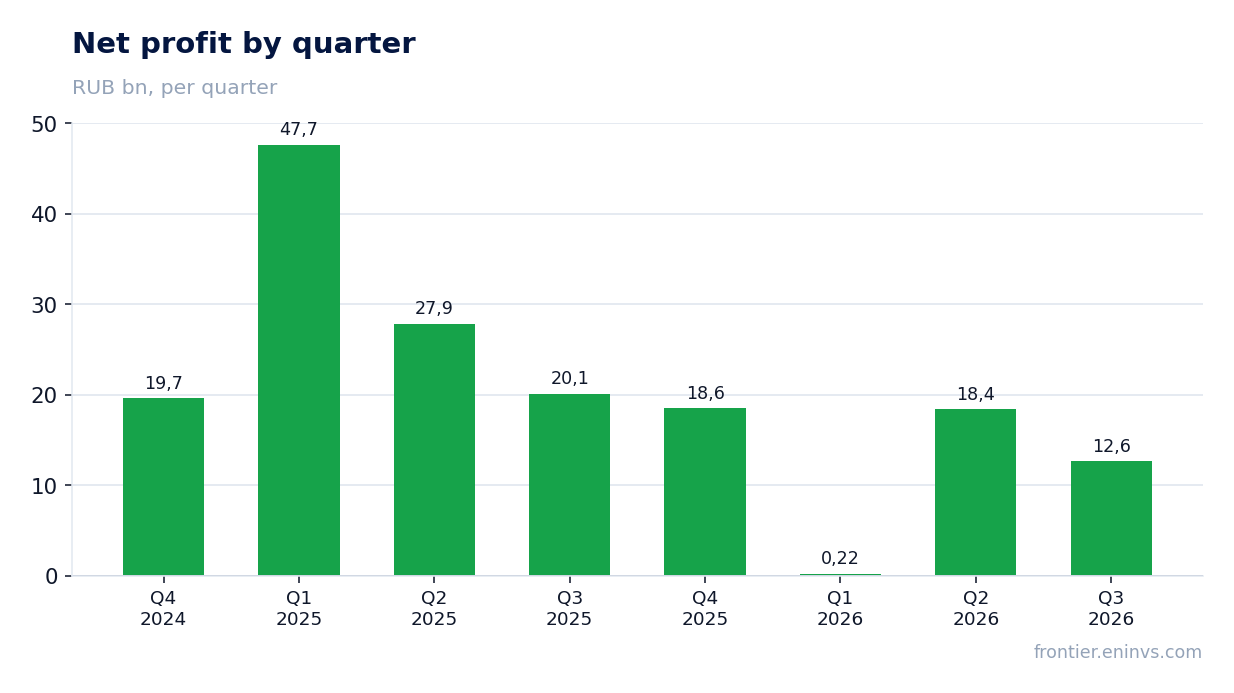
Net profit in Q3 came to 715.6 mn RUB versus 1,375.9 mn RUB a year earlier, a 48.0% decline against a 23.8% fall in net interest income. The profit share of net interest income dropped from 26.2% to 17.9%.
Several factors weighed on profit. The credit-loss impairment charge for nine months was 5,069.9 mn RUB versus 6,530.6 mn RUB a year earlier – the absolute amount fell, but the share of defaulted loans in the book remains high: 23,922.2 mn RUB out of 29,804.2 mn RUB gross, or 80.3%.
General and administrative expenses rose to 6,729.1 mn RUB from 5,278.7 mn RUB a year earlier. Personnel costs more than doubled, from 1,099.7 mn to 2,205.8 mn RUB, and depreciation from 209.3 mn to 405.8 mn RUB. Marketing expenses, by contrast, were cut from 2,756.0 mn to 2,648.4 mn RUB.
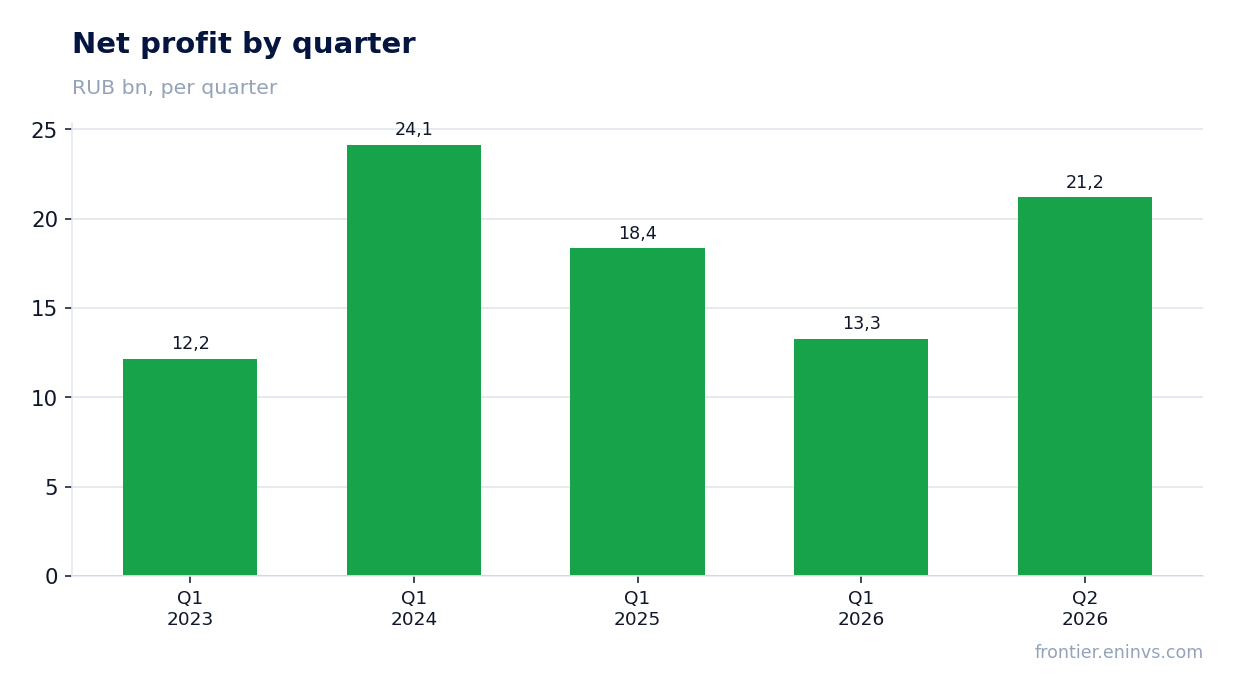
Net profit by quarter
The customer loan book shrank from 12,108.7 mn to 10,878.6 mn RUB since the start of the year
Net customer loans stood at 10,878.6 mn RUB at 30 September 2026 versus 12,108.7 mn RUB at end-2025. The contraction is a direct result of issuing fewer new loans and writing off problem debt more actively.
Write-offs over nine months of 2026 were 1,777.1 mn RUB versus 2,399.0 mn RUB a year earlier. Defaulted loans make up 80.3% of the gross book, and the provision covers 74.5% of them. Even as the absolute provision falls, portfolio quality remains weak.
The company also sells distressed portfolios: the loss on loan-portfolio sales over nine months of 2026 was 373.6 mn RUB versus 710.7 mn RUB a year earlier. The smaller loss on sales is one of the few positive shifts in the report.
Fee and commission income rose to 534.1 mn RUB in the quarter and partly offset the interest-income decline
Fee and commission income in Q3 2026 was 534.1 mn RUB versus 598.9 mn RUB a year earlier. Over nine months it rose to 2,138.1 mn RUB from 1,471.9 mn RUB, but the quarterly trend is already negative.
The nine-month increase came mainly from new lines: payment and transfer commissions brought 457.4 mn RUB, a line that did not exist a year earlier. Penalty income rose to 121.0 mn RUB from 96.6 mn RUB.
Commission expenses also rose, to 592.6 mn RUB from 276.5 mn RUB over nine months. Of that, 390.3 mn RUB was payment and transfer service fees, absent a year earlier. The net effect of the new payment services on profit is still small.
The 31.93 RUB per share dividend yields 25.1% – nearly double the 14.6% level we consider fair
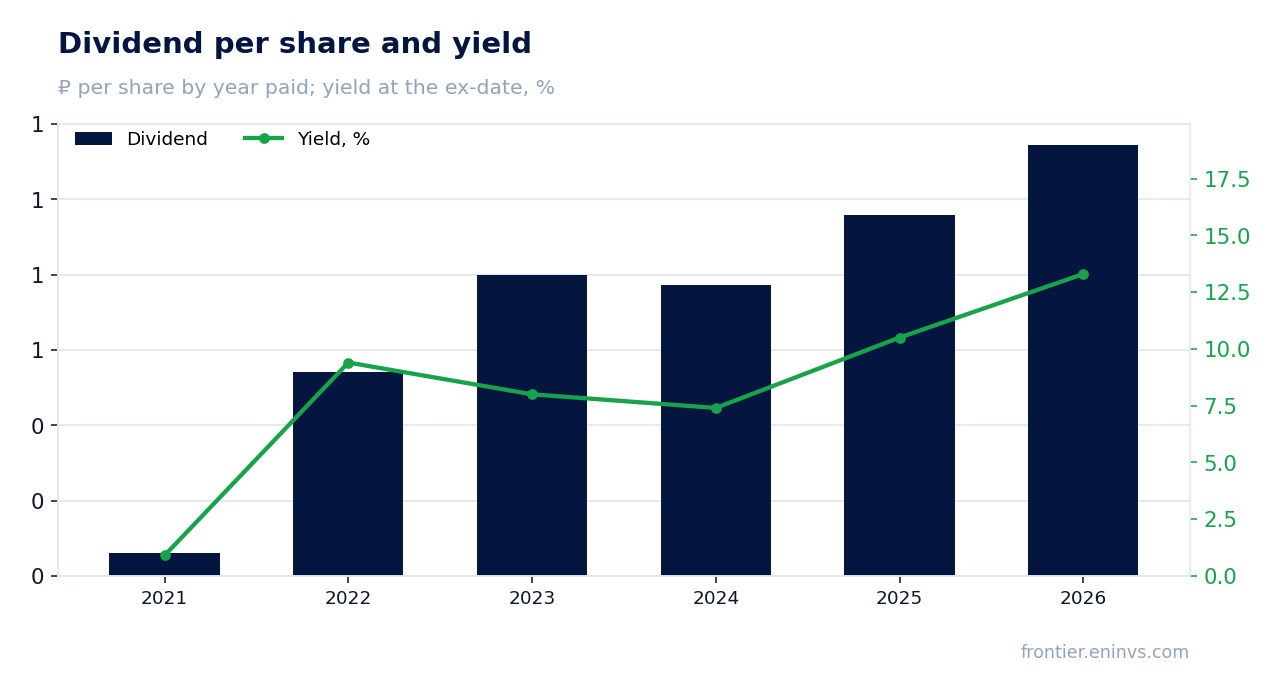
Over the last 12 months the company paid 31.93 RUB per share, a 25.1% yield to the current price. Our model estimates the next dividend at the same 31.93 RUB per share, so the forward yield is also 25.1%. We consider 14.6% a fair yield for this name.
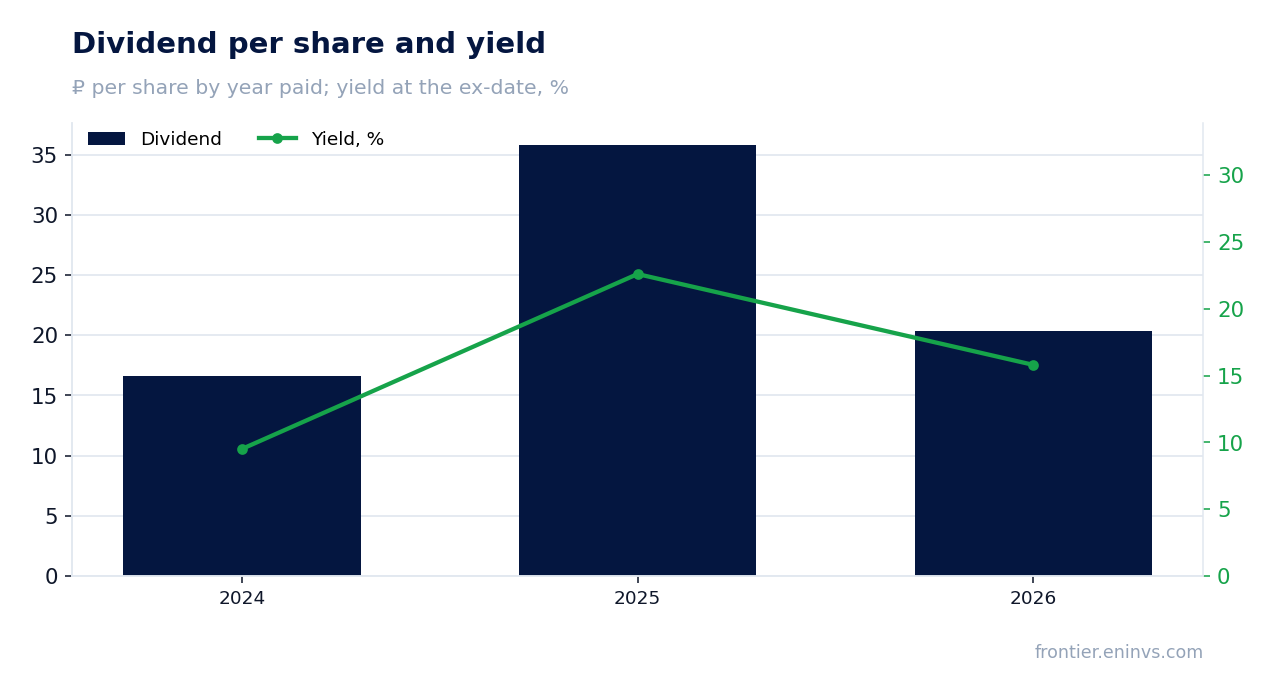
The payout history is uneven: 16.6 RUB per share for 2024 (9.5% at the ex-date price), 35.83 RUB for 2025 (22.6%), and 20.32 RUB for 2026 (15.8%). Dividends declared over nine months of 2026 were 2,032.0 mn RUB versus 1,371.0 mn RUB a year earlier, with 1,545.8 mn RUB actually paid.
The key risk to the dividend is profit. With a payout ratio of 0.61 of profit and a falling profit base, the company may cut the payout. If profit keeps declining at the same pace, the 31.93 RUB dividend could come under pressure. The 14.0% central bank key rate makes the current yield especially attractive relative to deposits.
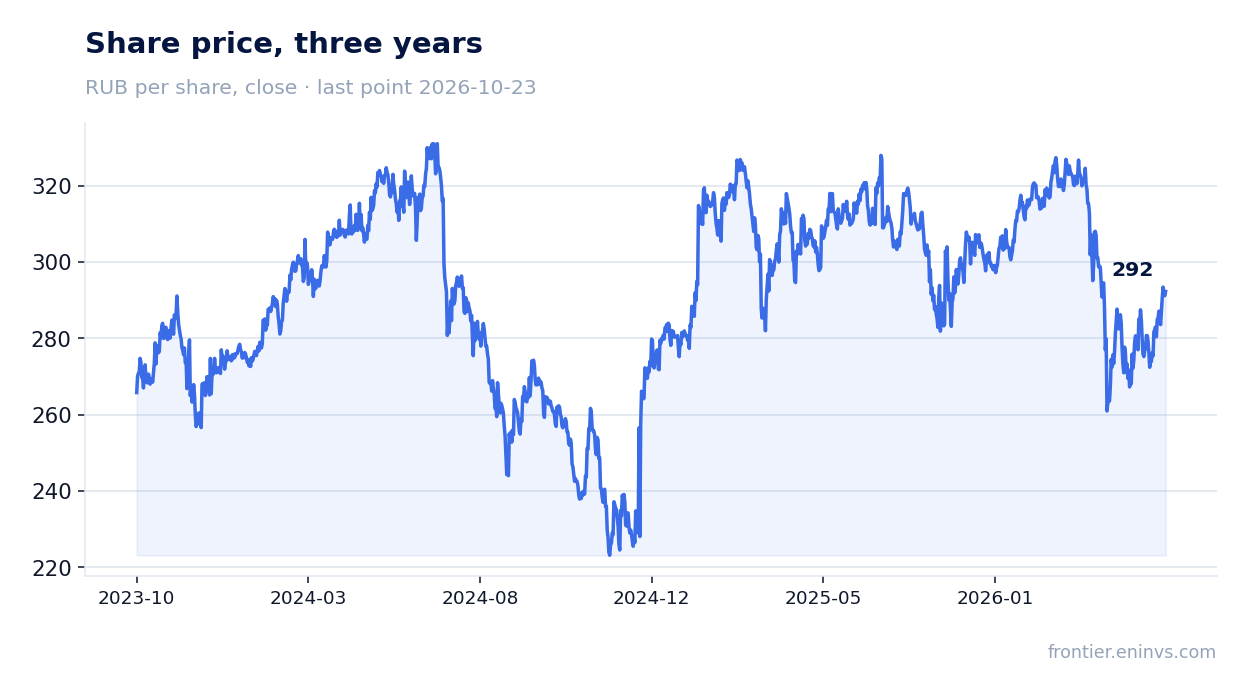
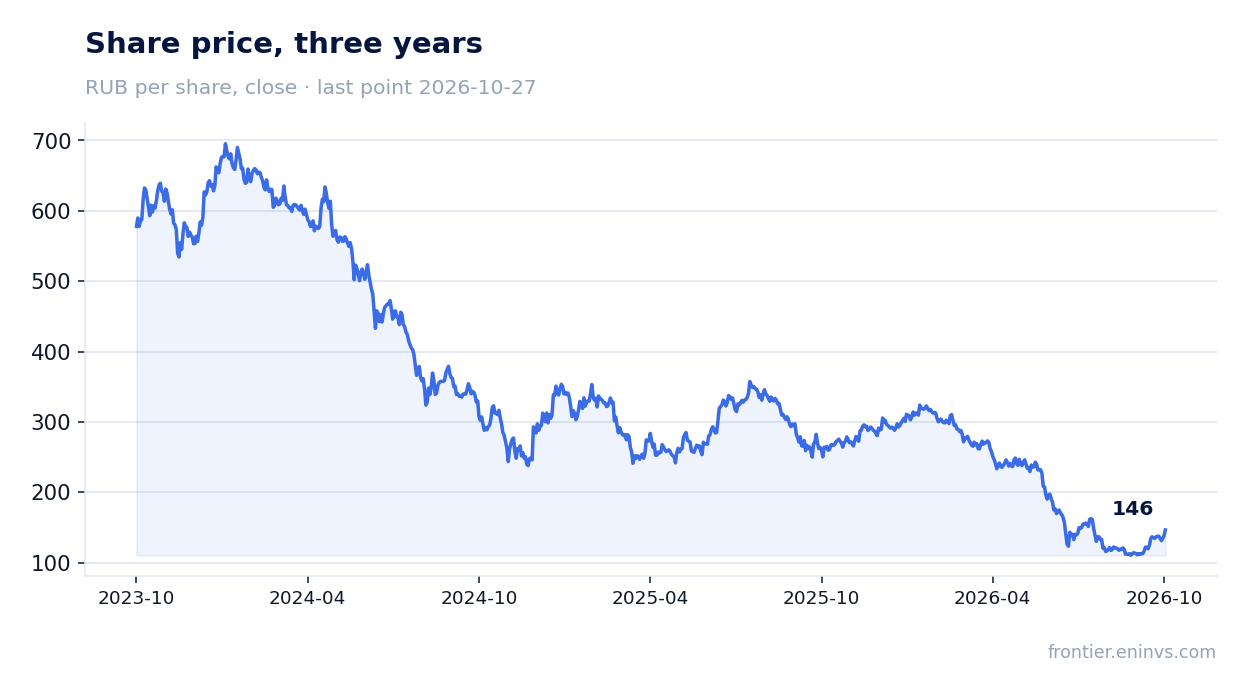
Share price, three years
P/E LTM of 4.8 and ROE of 6.8% show the market is already pricing in further profit compression
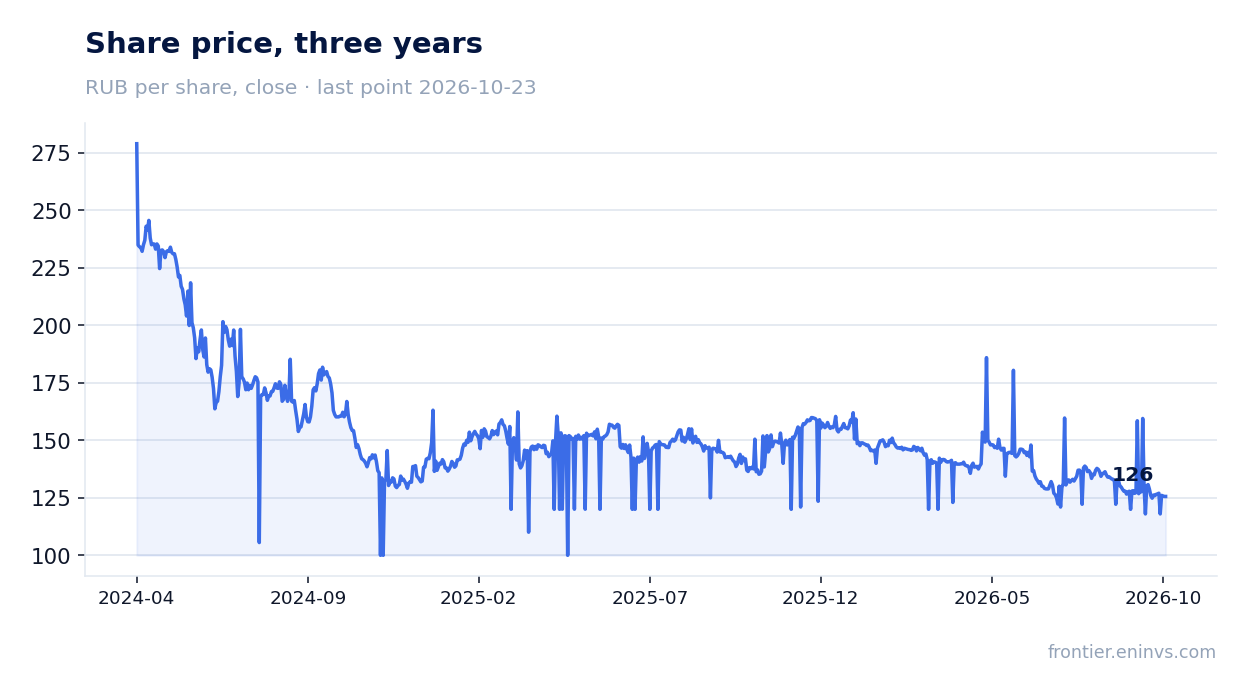
With a market capitalisation of 13,125.0 mn RUB and trailing twelve-month profit of 2,746.1 mn RUB, the P/E LTM is 4.8. ROE is 6.8%, modest for a microfinance company. The portal's model puts upside to fair value at +22%.
The market values the company cheaply, but that reflects falling profit: 2,746.1 mn RUB over the last 12 months versus 3,237.0 mn RUB over nine months of 2025. If the current quarterly pace persists, annual profit could be even lower.
A 25.1% dividend yield against a 14.0% key rate creates a wide spread. But if profit keeps falling, the dividend may be cut, and the current yield would prove deceptive. A P/E of 4.8 looks low, but without a profit turnaround a re-rating is unlikely.
Valuation on the latest reported figures
Metric
Value
Market cap
13.1 bn ₽
P/E (LTM)
4.8
P/B
0.91
ROE
6.8%
Dividend yield (12m)
25.1%
Dividend per share, ₽, and yield at the ex-date
Year paid
Dividend
Yield
2024
16.60
9.5%
2025
35.83
22.6%
2026
20.32
15.8%
Dividend per share and yield at the ex-date
Bottom line
The report's strong point remains the dividend: 31.93 RUB per share yields 25.1% against a 14.0% key rate, and declared payouts over nine months rose to 2,032.0 mn RUB. But profit fell 48.0%, revenue 23.8%, and the decline has accelerated for three quarters in a row. The loan book is shrinking, quality remains weak, and personnel costs more than doubled. At a P/E LTM of 4.8 and +22% upside on the portal's model, the share looks rather attractive – but only for those willing to hold it for the dividend and accept the risk of a cut.
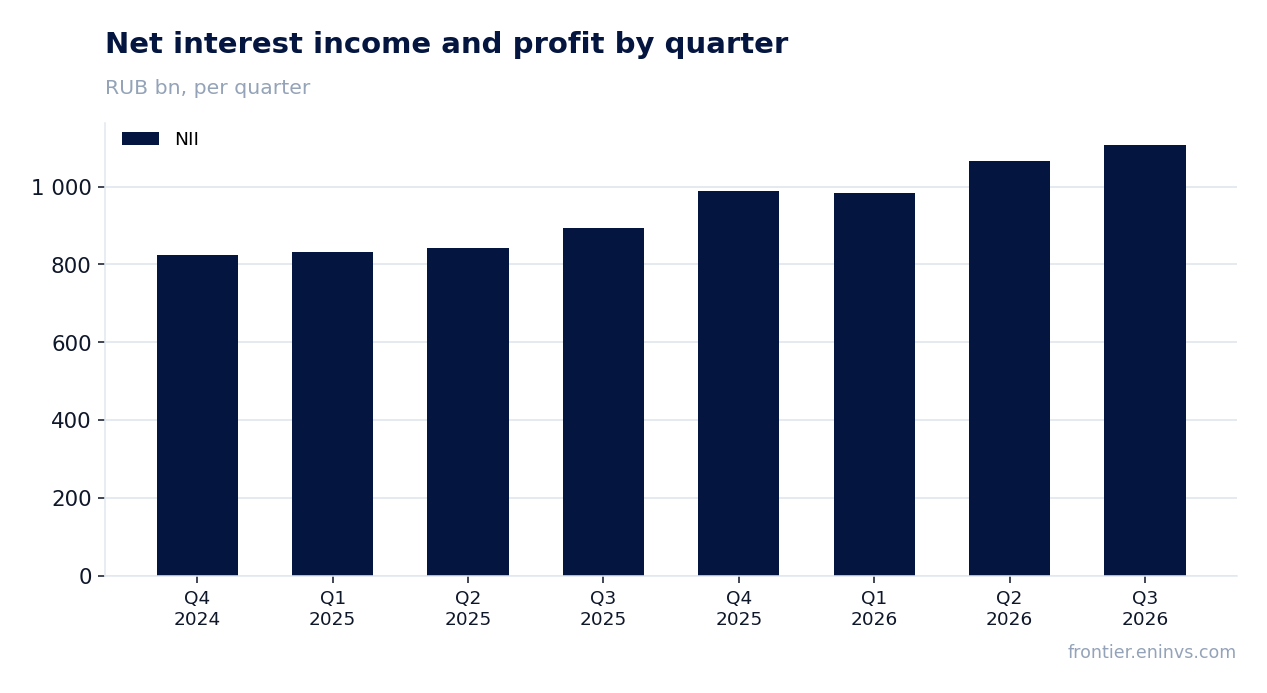
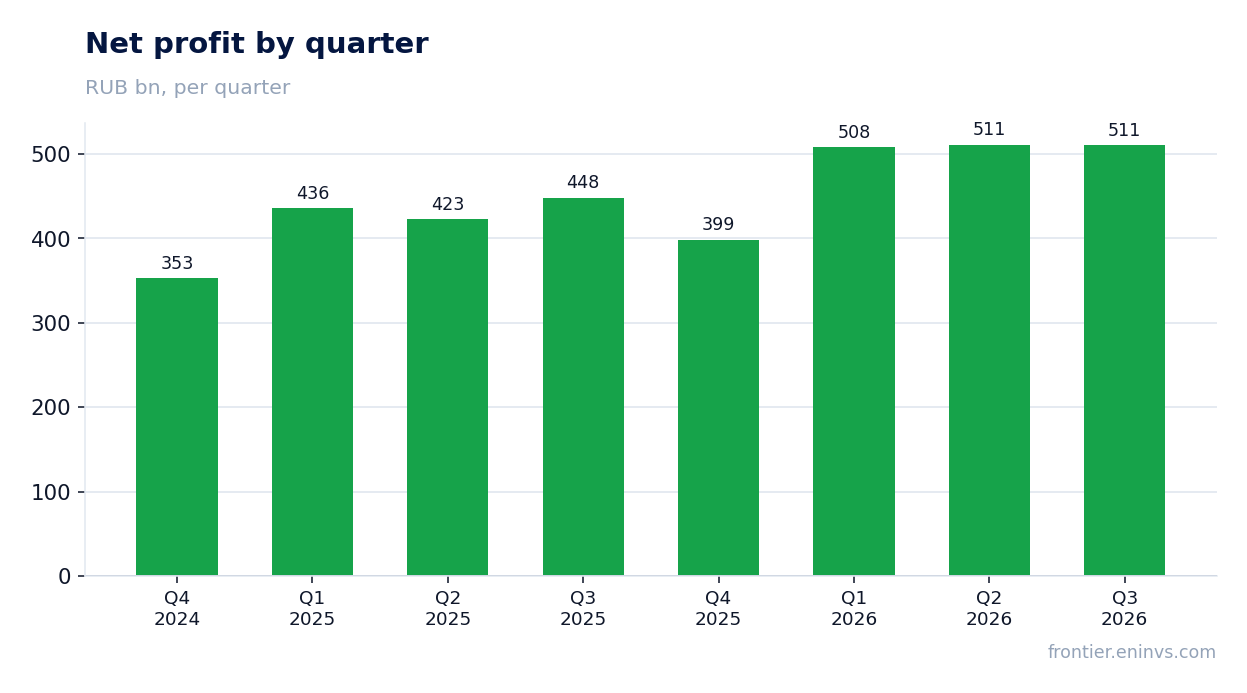
In its Q3 2026 report Sberbank posted net interest income of RUB 1,107.7 bn, up 24.0% year on year, and net profit of RUB 510.8 bn (+13.9%). Profit growth is markedly slower than interest income growth, and its ratio to net interest income fell to 46.1% from 50.2% a year earlier. The stock trades at a P/E LTM of 3.5 and offers a trailing dividend yield of 12.6% – our estimate for the next payout is 42.33 per share, or 14.2% at the current price. Given the discount to its own multiple, a strong dividend record and the portal model's +30% upside, the share looks attractive, although the deceleration in interest income growth from 26.7% in Q2 to 24.0% in Q3 warrants monitoring.
Key takeaways
— Net interest income grew 24.0% year on year, but the pace decelerated from 26.7% in Q2
— Profit added only 13.9%, and its share of net interest income fell to 46.1%
— Fee and commission income is nearly flat and does not offset pressure on profit
— Dividend yield of 12.6% and an estimated next payout of 42.33 per share
— P/E LTM of 3.5 and +30% upside on the portal's model
— ROE of 7.7% against a 14.0% key rate – capital earns less than money costs
Attractiveness
Key figures, RUB bn
Metric
Q3 2025
Q3 2026
Change
Net interest income
894
1 108
+24.0%
Net profit
448
511
+13.9%
Net margin
50.2%
46.1%
-4.1 pp
Net interest income grew 24.0% year on year, but the pace decelerated from 26.7% in Q2
In Q3 2026 Sberbank's net interest income reached RUB 1,107.7 bn, up 24.0% from the same quarter a year earlier. That is a strong result, but it is slower than the 26.7% growth seen in Q2. The deceleration of 2.7 percentage points is the first signal that the growth rate in interest income is starting to level off.
The figure is supported by the high key rate of 14.0%, which allows the bank to earn on placing funds. Further dynamics will depend on how quickly the regulator begins to cut rates. For now, quarterly growth of 24.0% remains solid, and against the previous three quarters (18.2%, 26.7% and 24.0%) it is clear the bank is holding a high base.
For shareholders, it matters that interest income is the main source of profit, and its deceleration feeds into profit with a lag. If the slowdown continues, it will limit the ability to grow dividend payments at the same pace as in recent years.
Revenue and EBITDA by quarter
Profit added only 13.9%, and its share of net interest income fell to 46.1%
Net profit in Q3 2026 was RUB 510.8 bn, up 13.9% year on year. That is almost half the growth rate of net interest income. As a result, the ratio of profit to net interest income fell to 46.1% from 50.2% a year earlier. This is not a margin or a profitability measure, but a ratio of two absolute figures, and it shows that revenue growth is accompanied by faster growth in costs or charges.
Profit is growing, but its conversion from interest income is deteriorating. The cause may be higher funding costs, rising operating expenses or provisioning – the report does not provide a breakdown within our review. Nevertheless, the 4.1 percentage point decline in profit's share of interest income is a significant signal for assessing the sustainability of the dividend base.
It is worth remembering that Q3 2026 profit is a standalone figure, not a cumulative total. For an annual assessment, the LTM profit of RUB 1,928.5 bn is more important, and it is this figure that feeds into the dividend calculation.
Net profit by quarter
Fee and commission income is nearly flat and does not offset pressure on profit
Fee and commission income in Q3 2026 was RUB 212.3 bn, essentially in line with the previous quarter (RUB 215.3 bn) and slightly below the year-earlier figure (RUB 216.5 bn). In effect, the fee business is stagnating: it is not growing and does not help offset the slowdown in net interest income.
Fees account for a smaller share of the bank's income than interest, but their contribution is important for diversification. The lack of growth here means that the entire burden of supporting profit falls on net interest income, which is itself starting to decelerate. This increases the vulnerability of the financial result to a decline in the key rate.
For shareholders, this is another argument that the current profit level may come under pressure if interest income stops growing as fast as it did in recent quarters.
Dividend yield of 12.6% and an estimated next payout of 42.33 per share
Over the last 12 months Sberbank paid RUB 37.64 per share, which at the current price gives a dividend yield of 12.6%. That is above the yield we consider fair for this name (10.5%) and well above the key rate of 14.0% after tax advantages for long-term holders. Our model estimates the next payout at RUB 42.33 per share, corresponding to a forward yield of 14.2%.
The payout estimate is based on a payout ratio of about 0.49 of profit and LTM profit of RUB 1,928.5 bn. If profit holds at the current level, a dividend of RUB 42.33 looks achievable. However, the decline in profit's share of interest income to 46.1% and stagnating fee income are factors that could limit profit growth and, consequently, the dividend.
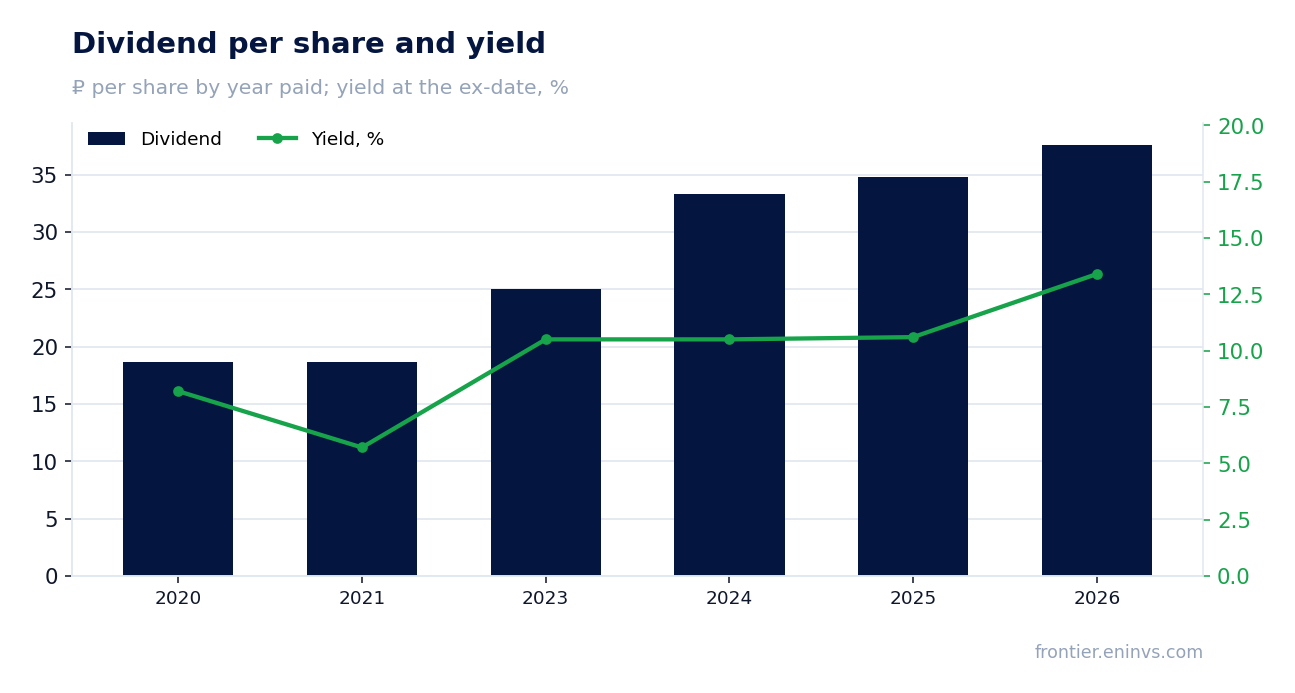
The payment history shows stability: RUB 18.7 in 2020 and 2021, RUB 25.0 in 2023, RUB 33.3 in 2024, RUB 34.84 in 2025 and RUB 37.64 in 2026. The yield at the ex-date ranged from 5.7% to 13.4%, and the current level of 12.6% is in the upper part of the historical range. This supports the appeal of the stock for income investors.
What could reduce the payout: a further slowdown in net interest income, higher provisions or operating expenses, or a change in dividend policy. For now, the combination of high yield and a moderate payout ratio leaves room for manoeuvre.
P/E LTM of 3.5 and +30% upside on the portal's model
Sberbank's stock trades at a P/E LTM of 3.5 – a very low multiple that reflects both high profit and persistent country risks. The three-year history of the multiple is not provided in the facts, so we cannot compare the current level with its historical average. However, an absolute value of 3.5 looks modest for a bank with an ROE of 7.7% and a stable dividend record.
According to the portal's model, which compares ROE with P/B, the upside to fair value is estimated at +30%. This is our own estimate, not a market consensus. It rests on the assumption that current profit is sustainable and the P/B multiple will gradually move towards a level consistent with the return on capital.
It is worth noting that the stock is held in several of the portal's model strategies: RU AI conviction, RU AI long-short, RU Banks & financials and RU Dividend growers. This is a fact, not an argument for the verdict, but it shows that the stock passes the screens of different approaches – from dividend to quantitative.
Share price, three years
ROE of 7.7% against a 14.0% key rate – capital earns less than money costs
Sberbank's LTM return on equity is 7.7%, below the key rate of 14.0%. This means the bank earns less on capital than a risk-free placement would yield. Such a gap weighs on valuation: investors demand a higher dividend yield as compensation for low capital efficiency.
Low ROE alongside a high P/E may be explained by the structure of profit: a significant portion of income comes from interest operations, which are sensitive to the rate. If the rate starts to decline, ROE could recover through lending growth, but that will take time. For now, the ratio of ROE to the cost of capital remains the weak link in the investment case.
For the dividend record this is not critical: a payout ratio of about 0.49 allows payments to be maintained even at moderate profitability. However, the long-term sustainability of the dividend depends on the bank's ability to raise ROE or at least keep it at the current level.
Valuation on the latest reported figures
Metric
Value
Market cap
6 751 bn ₽
P/E (LTM)
3.5
P/B
0.82
ROE
7.7%
Dividend yield (12m)
12.6%
Dividend per share, ₽, and yield at the ex-date
Year paid
Dividend
Yield
2020
18.70
8.2%
2021
18.70
5.7%
2023
25.00
10.5%
2024
33.30
10.5%
2025
34.84
10.6%
2026
37.64
13.4%
Dividend per share and yield at the ex-date
Bottom line
The report's strengths remain net interest income growth of 24.0% and a stable dividend record with a current yield of 12.6%. However, profit is growing more slowly at 13.9%, and its share of interest income is declining, pointing to pressure on the conversion of revenue into profit. The dividend yield is above what we consider fair for the stock, and the portal model implies +30% upside. The key question for a holder now is whether the bank can sustain interest income growth and return on equity against a possible rate cut. The verdict is attractive, but with a caveat on deceleration.
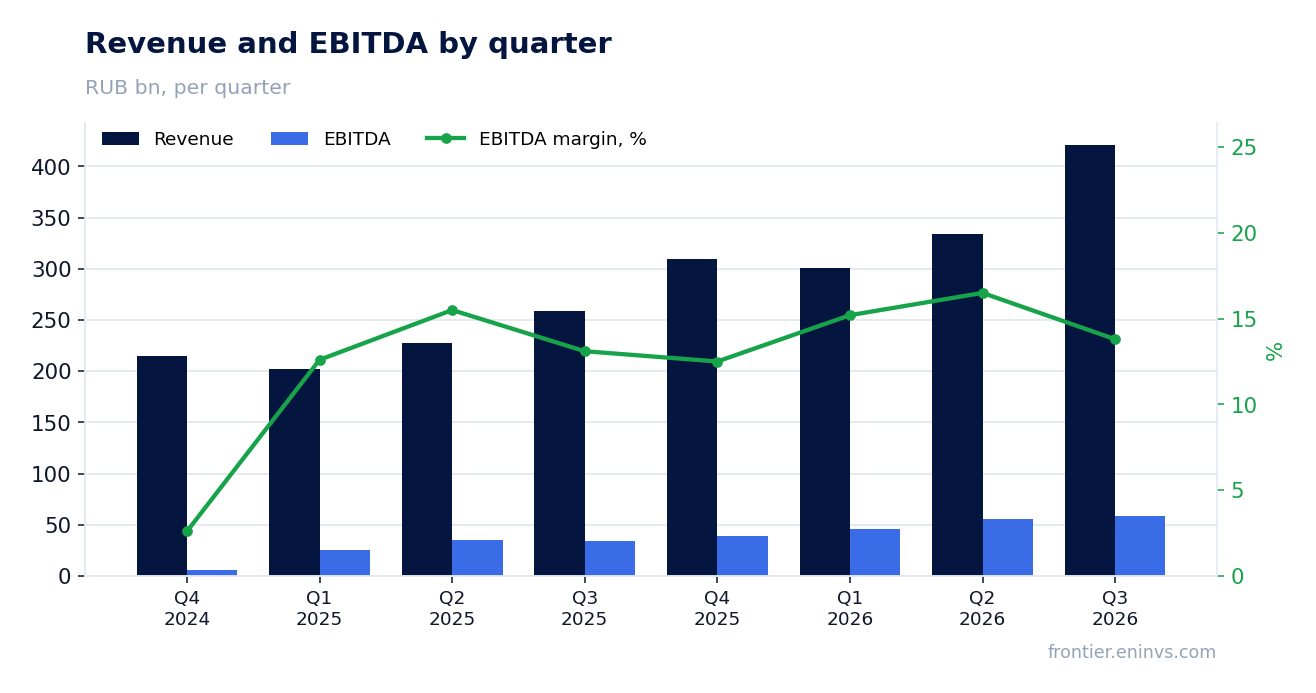
On November 25, OZON released its third-quarter 2026 results. Revenue rose 62.7% year on year to RUB 421.2 bn, EBITDA – by 49.4% to RUB 58.3 bn, but its margin fell to 13.8% from 15.1% a year earlier. Growth accelerated versus the second quarter (+46.8%), while leverage at 1.53x LTM EBITDA remains moderate. At the current price the share looks rather attractive: revenue growth is accelerating and a 5.9% dividend yield supports holders.
Key takeaways
— Q3 revenue grew 62.7% year on year to RUB 421.2 bn, an acceleration from 46.8% in Q2
— EBITDA rose 49.4% year on year, but its margin compressed to 13.8% from 15.1% a year earlier
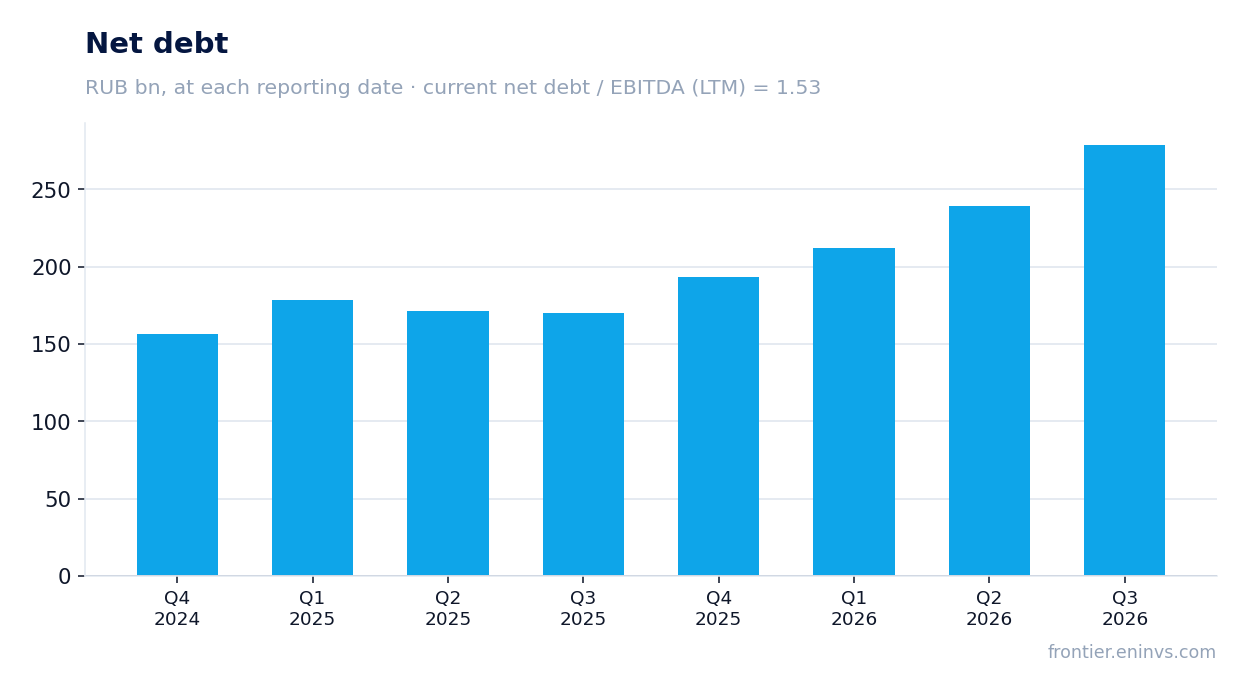
— Net debt rose to RUB 278.8 bn on September 30, 2026 from RUB 239.3 bn on June 30, with net debt/LTM EBITDA at 1.53x
— Dividends paid over the last 12 months amounted to RUB 213.55 per share, a 5.9% yield
— The portal's model puts upside to fair value at +55%
— The share is held in the portal's live model strategies: RU AI conviction, RU AI long-short and RU Growth-stories
Attractiveness
Key figures, RUB bn
Metric
Q3 2025
Q3 2026
Change
Revenue
259
421
+62.7%
EBITDA
39.0
58.3
+49.4%
Operating profit
17.8
—
—
Net profit
-157
—
—
Operating cash flow
173
—
—
Capex
13.5
—
—
EBITDA margin
15.1%
13.8%
-1.3 pp
Net margin
-60.5%
—
—
Q3 revenue grew 62.7% year on year to RUB 421.2 bn, an acceleration from 46.8% in Q2
OZON's Q3 2026 revenue reached RUB 421.2 bn, up 62.7% year on year. In Q2 growth was slower at 46.8%, so the current quarter shows acceleration. This is the highest growth rate in the last four quarters: 48.9% in Q1 2026 and 44.1% in Q4 2025.
The acceleration matters for valuation: it means the business is scaling faster than the previous quarters' trend implied. The absolute quarterly revenue increase of about RUB 162 bn is comparable to the company's entire quarterly revenue two years ago.
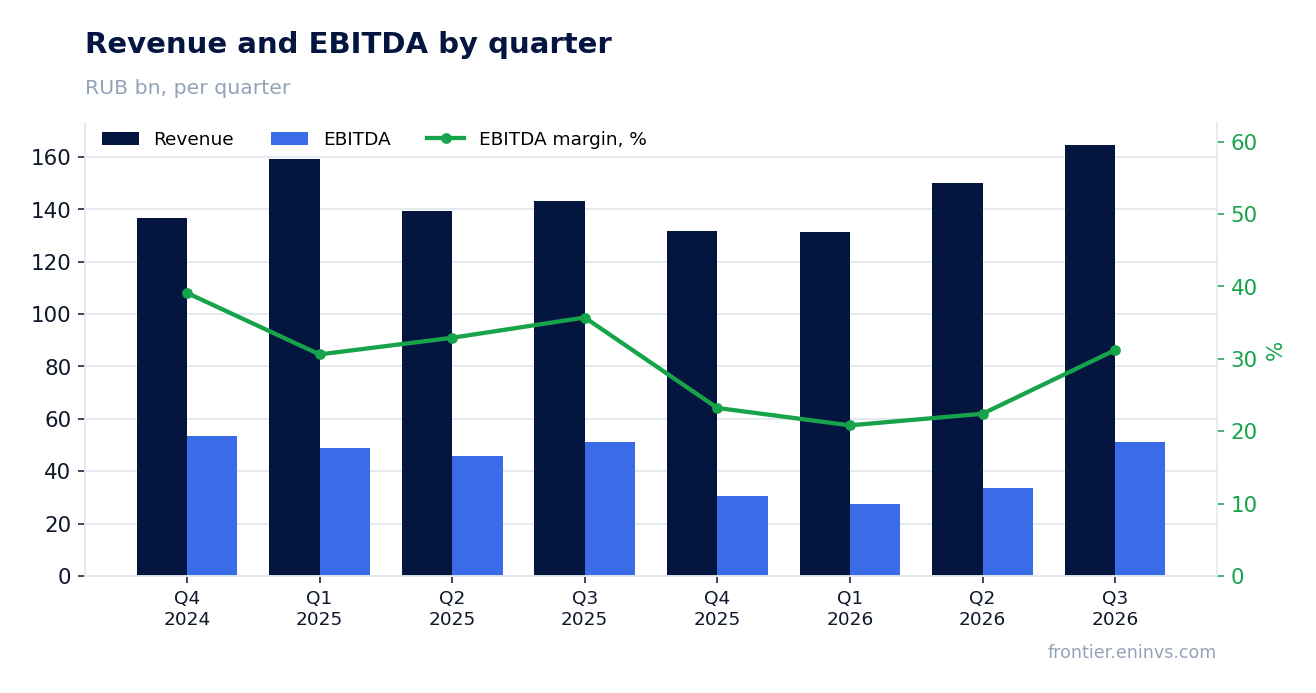
Revenue and EBITDA by quarter
EBITDA rose 49.4% year on year, but its margin compressed to 13.8% from 15.1% a year earlier
Q3 2026 EBITDA came in at RUB 58.3 bn, up 49.4% year on year. However, EBITDA growth lags revenue growth (+62.7%), pushing the margin down to 13.8% from 15.1% in Q3 2025.
The 1.3 percentage point margin compression means costs are rising faster than revenue. The company did not disclose in the provided facts which cost line drove this, so we state the fact: EBITDA is growing in absolute terms, but efficiency per ruble of revenue declined. For an investor this signals that scaling is not yet accompanied by improving profitability.
Net profit by quarter
Net debt rose to RUB 278.8 bn on September 30, 2026 from RUB 239.3 bn on June 30, with net debt/LTM EBITDA at 1.53x
Net debt on September 30, 2026 stood at RUB 278.8 bn, up RUB 39.5 bn from RUB 239.3 bn on June 30, 2026. Over the year, from RUB 170.2 bn on September 30, 2025, debt rose by RUB 108.7 bn. Debt growth accompanies business expansion but requires monitoring.
The net debt to LTM EBITDA ratio is 1.53x. This is a moderate level that leaves room for further growth financing. The facts do not include earlier values of this ratio, so we do not assess its direction.
Net debt at reporting dates
Dividends paid over the last 12 months amounted to RUB 213.55 per share, a 5.9% yield
Over the last 12 months OZON paid dividends of RUB 213.55 per share, giving a current yield of 5.9%. In 2026 the payout was RUB 70.0 per share with a 1.7% yield at the ex-date, and in 2025 – RUB 143.55 with a 3.4% yield.
For a dividend history these are substantial payments. The 5.9% yield is well above the 2025 and 2026 levels, reflecting both the dividend growth and the current share price. The company remains a growth story, and payouts may vary depending on profit and investment needs. Our estimate for the current year assumes payouts remain at the last-12-month level, provided profit and cash flow support them.
The portal's model puts upside to fair value at +55%
The portal's model, which compares EBITDA growth with a target multiple and market capitalization, puts the upside to fair value at +55%. This is the portal's own estimate, not a market consensus or a target price.
The current EV/EBITDA LTM multiple is 5.54x, and P/E LTM is 38.52x. For a growing company with accelerating revenue these levels look moderate, especially given the dividend yield. However, the facts do not include a comparison with the company's own multiple history, so we limit ourselves to stating current values.
Share price, three years
The share is held in the portal's live model strategies: RU AI conviction, RU AI long-short and RU Growth-stories
OZON is included in three live model strategies on the portal: RU AI conviction (Claude), RU AI long-short (market-neutral) and RU Growth-stories (GARP). Inclusion reflects passing these strategies' screens and is not an argument for the verdict.
For holders this means the share is present in model portfolios, but each investor makes their own buy or sell decision based on their goals and constraints.
Valuation on the latest reported figures
Metric
Value
Market cap
818 bn ₽
P/E (LTM)
38.5
EV/EBITDA (LTM)
5.5
Net debt / EBITDA (LTM)
1.53
ROE
-26.2%
Dividend yield (12m)
5.7%
Dividend per share, ₽, and yield at the ex-date
Year paid
Dividend
Yield
2025
143.55
3.4%
2026
70.00
1.7%
Bottom line
The strong point of the report was revenue growth of 62.7% year on year with acceleration versus Q2. However, EBITDA grew slower at 49.4%, and the margin compressed to 13.8%. Leverage at 1.53x LTM EBITDA remains moderate, and a 5.9% dividend yield supports holders. The portal's model puts upside at +55%. Verdict – rather attractive: revenue acceleration and the dividend outweigh the margin compression, but margin sustainability remains the key question.
On 21 May 2026, VK company released its operational and unaudited financial results for the first quarter of 2026, along with data for the nine months of 2026. Revenue for the reporting period reached RUB 128 bn, adjusted EBITDA came in at RUB 20.2 bn with a 15.8% margin, and operating cash flow was RUB 17.4 bn. Net profit for the nine months remains negative, while the net debt to EBITDA ratio over the last twelve months stands at 2.34. The shares look neutral: revenue and EBITDA are growing, but negative profit and leverage leave no room for a higher rating.
Key takeaways
— Revenue for the nine months rose to RUB 128 bn, but without a segment breakdown for this period it is impossible to tell what is driving it
— EBITDA of RUB 20.2 bn at a 15.8% margin is a level that has not yet translated into positive net profit
— Operating cash flow of RUB 17.4 bn is almost equal to EBITDA, but capex and interest consume that cushion
— Net debt of RUB 82.3 bn at 2.34x EBITDA is a burden that limits room for manoeuvre
— A valuation of 4.78x LTM EBITDA looks inexpensive, but negative profit and debt prevent that valuation from materialising
— Management's guidance of EBITDA above RUB 24 bn for 2026 is the main benchmark to be tested at year-end
Attractiveness
Key figures, RUB bn
Metric
—
9M 2026
Change
Revenue
—
128
—
EBITDA
—
20.2
—
Operating cash flow
—
17.4
—
EBITDA margin
—
15.8%
—
Revenue for the nine months rose to RUB 128 bn, but without a segment breakdown for this period it is impossible to tell what is driving it
VK company's revenue for the nine months of 2026 amounted to RUB 128 bn. This is the only comparable figure for the reporting period disclosed in the press release. The segment breakdown in the document is given only for the first quarter of 2026, so it cannot be extrapolated to the full nine-month period.
In the first quarter of 2026, group revenue was RUB 37.6 bn, up 6% year on year. The main contribution came from the Social Platforms and Media Content segment at RUB 26.1 bn, up 6%. The Business Technologies segment (VK Tech) grew 59% to RUB 4.29 bn, and Educational Technologies grew 23% to RUB 2.5 bn.
This growth structure means that the fastest-growing segments are small in revenue terms, while the core segment adds a modest 6%. For the nine months, this means the overall revenue dynamic of RUB 128 bn rests on a large but slow-growing social segment rather than on the fast-growing technology lines.
EBITDA of RUB 20.2 bn at a 15.8% margin is a level that has not yet translated into positive net profit
Adjusted EBITDA for the nine months of 2026 was RUB 20.2 bn at a 15.8% margin. This means that for every rouble of revenue, the company earns about 16 kopecks of operating profit before depreciation, interest and taxes.
In the first quarter of 2026, EBITDA was RUB 6.4 bn at a 17% margin, up 27% year on year. All operating segments showed positive EBITDA margins. The Social Platforms and Media Content segment generated RUB 6.2 bn of EBITDA at a 24% margin, Educational Technologies RUB 0.6 bn at 24%, and VK Tech RUB 0.28 bn at 7%.
The 15.8% margin for the nine months is below the 17% seen in the first quarter. This means that margins in the second and third quarters were weaker than at the start of the year. At the same time, net profit for the nine months remains negative, and return on equity is minus 3.3%. EBITDA does not cover depreciation, interest and taxes sufficiently to bring the company into profit.
Operating cash flow of RUB 17.4 bn is almost equal to EBITDA, but capex and interest consume that cushion
Operating cash flow for the nine months of 2026 was RUB 17.4 bn. This is roughly 86% of EBITDA for the same period. Such a gap means the company converts operating profit into cash fairly efficiently, but not fully.
The press release does not disclose capital expenditure for the nine months. However, with revenue of RUB 128 bn and negative net profit, it is fair to say that capex and interest expenses together exceed the difference between EBITDA and operating cash flow. Otherwise the company would have shown a positive profit.
In the first quarter of 2026, the company sold a 25% stake in AO Tochka for RUB 21.2 bn and placed exchange-traded bonds worth RUB 10 bn. These one-off inflows increase the cash cushion but are not an operating result. Without them, the cash reserve would be smaller and leverage higher.
Net debt of RUB 82.3 bn at 2.34x EBITDA is a burden that limits room for manoeuvre
VK company's net debt at the end of the latest annual balance sheet was RUB 82.3 bn. The net debt to EBITDA ratio over the last twelve months is 2.34. This level cannot be called critical, but it is not comfortable either for a company with negative net profit.
In the first quarter of 2026, net debt decreased by RUB 20 bn to RUB 62 bn compared with the end of 2025, and the net debt to EBITDA ratio was 2.6. This decrease was partly due to the sale of a 25% stake in AO Tochka for RUB 21.2 bn and the placement of bonds worth RUB 10 bn.
The difference between RUB 62 bn at the end of April 2026 and RUB 82.3 bn at the end of the latest annual balance sheet is explained by different dates. For the investor, what matters is that the company actively manages its debt, but does so partly through asset sales rather than solely through operating cash flow.
A valuation of 4.78x LTM EBITDA looks inexpensive, but negative profit and debt prevent that valuation from materialising
The EV/EBITDA ratio over the last twelve months is 4.78. With a market capitalisation of RUB 85.9 bn and net debt of RUB 82.3 bn, this means investors value the company at about 4.8 times annual EBITDA. For a growing technology business, this is not a high valuation.
However, negative net profit and a return on equity of minus 3.3% mean the company is not yet earning on equity capital. Until profit turns positive, the low EBITDA multiple will remain more a reflection of risks than of undervaluation.
Comparing the current multiple with its own three-year history is not possible: the facts do not include a three-year average. So we limit ourselves to stating: 4.78x EBITDA is a level that implies either significant future profit growth or the persistence of current risks.
Share price, three years
Management's guidance of EBITDA above RUB 24 bn for 2026 is the main benchmark to be tested at year-end
In the press release for the first quarter of 2026, the company raised its EBITDA guidance for 2026 to above RUB 24 bn. That is RUB 3.8 bn more than the RUB 20.2 bn for the nine months of 2026. To meet the guidance, the company needs to earn about RUB 3.8 bn of EBITDA in the fourth quarter.
For comparison, EBITDA in the first quarter of 2026 was RUB 6.4 bn. If the fourth quarter is no worse than the first, the guidance is achievable. However, the 15.8% margin for the nine months is below the 17% seen in the first quarter, which points to a possible slowdown.
The main risk to meeting the guidance is the persistence of negative net profit. If interest expenses and depreciation remain high, even meeting the EBITDA guidance will not lead to positive profit. The investor should watch the dynamics of net profit and leverage in the next report.
Valuation on the latest reported figures
Metric
Value
Market cap
85.9 bn ₽
EV/EBITDA (LTM)
4.8
P/B
0.65
Net debt / EBITDA (LTM)
2.34
ROE
-3.3%
Bottom line
The strong side of the report remains revenue growth to RUB 128 bn and EBITDA to RUB 20.2 bn for the nine months, along with operating cash flow of RUB 17.4 bn, which almost covers EBITDA. The weak side is negative net profit and leverage of 2.34x EBITDA, which prevent the 4.78x EBITDA valuation from being called undervaluation. The main question for a holder now is whether the company can turn profitable while maintaining current growth. The verdict is neutral: the arguments for and against roughly balance each other out.
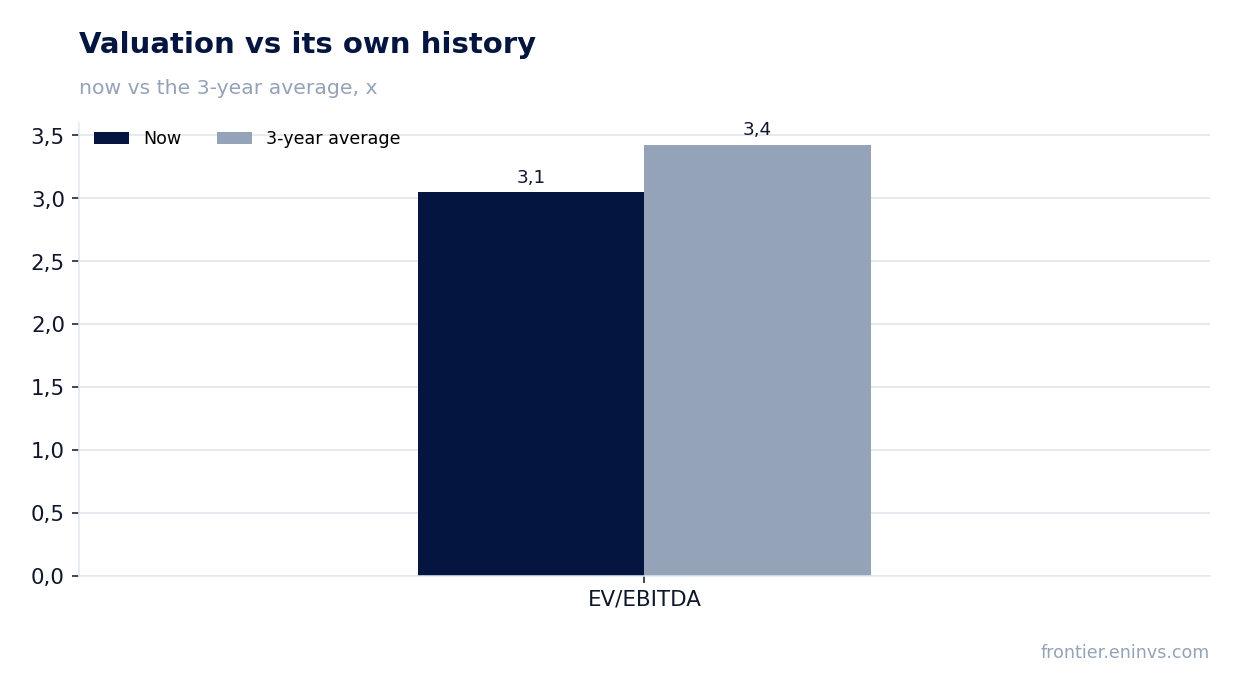
On 30 September 2026, X5 Retail released its third-quarter 2026 results. Revenue reached RUB 1,311.0 bn, up 11.3% year on year, but EBITDA and net profit for the reported quarter were not disclosed. Over the trailing twelve months, revenue amounted to RUB 5,029.5 bn, net profit to RUB 67.9 bn, and the dividend yield on last year's payouts stands at 26.2%. At the current price the share looks attractive: the EV/EBITDA multiple of 3.1 is below its own three-year average of 3.4, and the dividend yield exceeds the fair level of 22.5%.
Key takeaways
— Q3 revenue grew 11.3% year on year, but the pace decelerated from 20.7% a year earlier
— EBITDA and net profit for Q3 were not disclosed, so the margin for the reported period cannot be assessed
— Over the trailing twelve months, net profit reached RUB 67.9 bn on revenue of RUB 5,029.5 bn
— Dividends paid over the last year were RUB 613 per share, a 26.2% yield versus the 22.5% we consider fair
— Our estimate for the current financial year's dividend is RUB 239.16 per share, or a 10.2% yield on the current price
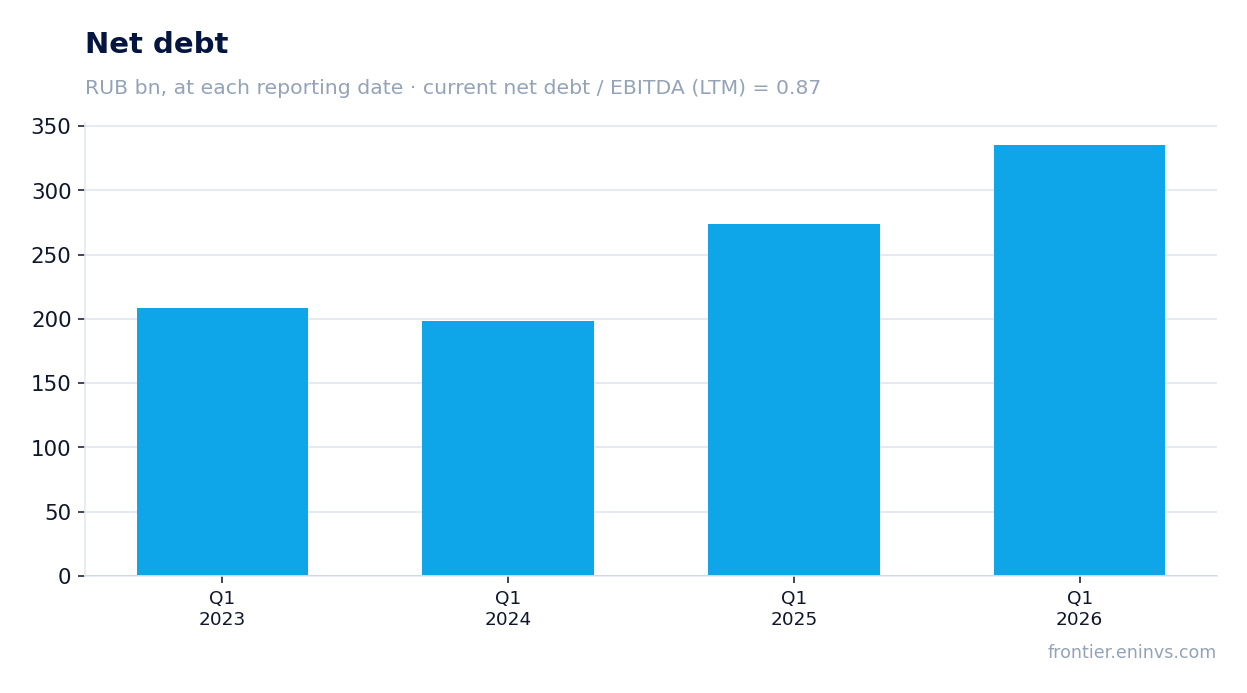
— Leverage on the latest balance sheet is 0.87 net debt to LTM EBITDA, a moderate level
— EV/EBITDA of 3.1 is below its own three-year average of 3.4, and the portal model implies 43% upside to fair value
Attractiveness
Key figures, RUB bn
Metric
—
Q3 2026
Change
Revenue
—
1 311
—
Q3 revenue grew 11.3% year on year, but the pace decelerated from 20.7% a year earlier
Q3 2026 revenue reached RUB 1,311.0 bn, up 11.3% from the same quarter a year earlier. This is a deceleration from the 20.7% growth in Q1 2025 and from 11.3% in Q1 2026. The slowdown in revenue growth has been observed since early 2025.
Over the trailing twelve months, revenue amounted to RUB 5,029.5 bn, reflecting the scale of the business. The company did not disclose which factors drove the slowdown in Q3. Without additional data, one can only note that growth remains in double digits but is decelerating.
For an investor, it is important that the revenue slowdown is not accompanied by disclosed quarterly margins. This limits the assessment of operating efficiency in the reported period.
Revenue and EBITDA by quarter
EBITDA and net profit for Q3 were not disclosed, so the margin for the reported period cannot be assessed
In the reported quarter, the company did not disclose EBITDA or net profit. This prevents an assessment of margin dynamics for Q3 2026. In Q1 2026, EBITDA was RUB 64.3 bn, operating profit RUB 56.7 bn, and net profit RUB 13.3 bn.
The absence of Q3 data creates uncertainty for profitability assessment. An investor can rely only on trailing twelve-month figures: net profit of RUB 67.9 bn and EBITDA of RUB 263.6 bn.
Without quarterly data, one cannot judge whether margins held at prior levels or changed. This limits the analysis but does not overturn the overall picture of a profitable business.
Net profit by quarter
Over the trailing twelve months, net profit reached RUB 67.9 bn on revenue of RUB 5,029.5 bn
Over the trailing twelve months, net profit reached RUB 67.9 bn on revenue of RUB 5,029.5 bn. The net margin is about 1.3%, a low figure typical of high-turnover retail.
LTM EBITDA reached RUB 263.6 bn, giving an EBITDA margin of about 5.2%. Operating profit in Q1 2026 was RUB 56.7 bn but was not disclosed for Q3.
LTM profit is the base for dividend calculations and multiple valuation. The LTM P/E of 8.5 indicates a low market valuation of earnings.
Net debt at reporting dates
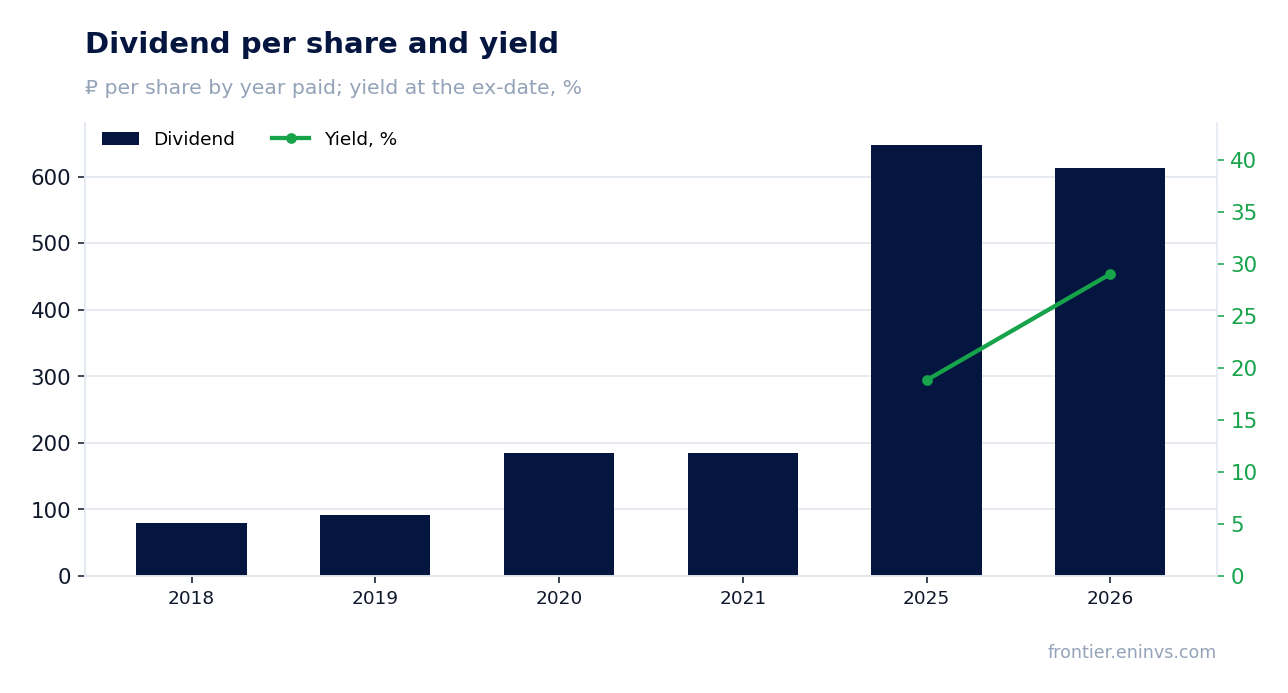
Dividends paid over the last year were RUB 613 per share, a 26.2% yield versus the 22.5% we consider fair
Over the last twelve months, the company paid RUB 613 per share. At the current price, this gives a dividend yield of 26.2%. We consider a 22.5% yield fair for this name, so the current payout exceeds our benchmark.
The payout history shows growth: RUB 648 per share was paid in 2025 with an 18.8% yield at the ex-date price, and RUB 613 in 2026 with a 29.0% yield. The lower absolute payout in 2026 is offset by the share price decline, which raised the yield.
The payout ratio is 0.86 of profit. This is a high level that supports the yield but limits room for growth without higher profit.
Valuation vs its own history
Our estimate for the current financial year's dividend is RUB 239.16 per share, or a 10.2% yield on the current price
We estimate the dividend for the current financial year at RUB 239.16 per share. This is our own calculation based on LTM profit and a payout ratio of 0.864. At the current price, this implies a 10.2% yield.
The estimate is well below actual payouts over the last year. This is because the calculation relies on LTM profit rather than peak profit from prior periods. The board decides on the payout; our estimate is not a guarantee.
Key risks to the payout size are lower profit and possible changes to dividend policy. With a payout ratio of 0.86, any decline in profit directly reduces the dividend.
Share price, three years
Leverage on the latest balance sheet is 0.87 net debt to LTM EBITDA, a moderate level
Net debt on the latest balance sheet is RUB 228.5 bn. The ratio of net debt to LTM EBITDA is 0.87. This is a moderate level for a retailer and leaves room for manoeuvre.
We do not have an earlier value for this ratio, so we cannot judge its direction of change. The level of 0.87 by itself does not create a debt burden that threatens dividends.
Interest expenses are not disclosed in the provided data, but with the key rate at 14.0%, debt servicing remains a significant factor for profit. However, the current debt level does not look critical.
Dividend per share and yield at the ex-date
EV/EBITDA of 3.1 is below its own three-year average of 3.4, and the portal model implies 43% upside to fair value
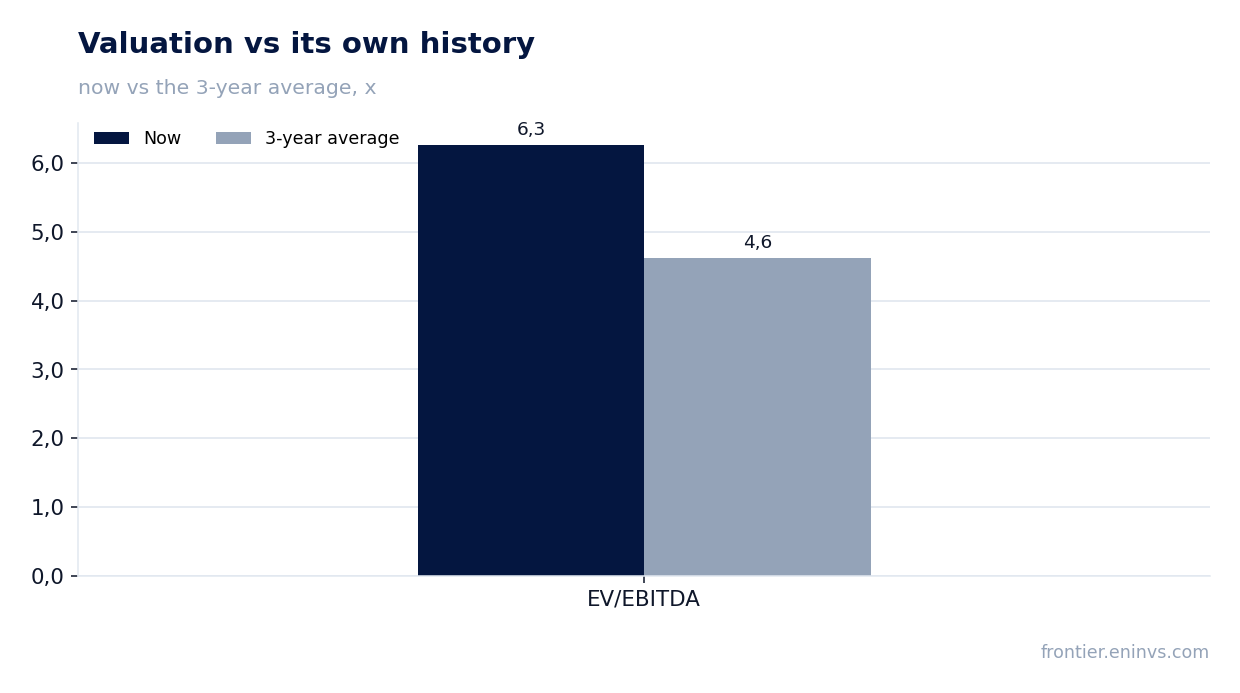
The LTM EV/EBITDA multiple is 3.1, which is 11% below its own three-year average of 3.4. This indicates the share trades cheaper than its historical valuation on this multiple.
According to the portal model, which compares EBITDA growth with the target multiple, the upside to fair value is 43%. This is our own estimate, not a market consensus or a target price.
The LTM P/E of 8.5 also points to a low valuation of earnings. The combination of low multiples and a high dividend yield makes the share attractive for income-oriented investors.
Valuation on the latest reported figures
Metric
Value
Market cap
575 bn ₽
P/E (LTM)
8.5
EV/EBITDA (LTM)
3.1
P/B
5.94
Net debt / EBITDA (LTM)
0.87
ROE
80.9%
Dividend yield (12m)
26.2%
EV/EBITDA, 3-year average
3.4
Dividend per share, ₽, and yield at the ex-date
Year paid
Dividend
Yield
2018
79.50
—
2019
92.06
—
2020
184.12
—
2021
184.14
—
2025
648.00
18.8%
2026
613.00
29.0%
Our estimate, current year
239.16
10.2% on the current price
Bottom line
The strong side of the report is maintained double-digit revenue growth and moderate leverage of 0.87. The weak side is the absence of quarterly profit data and decelerating growth. The dividend yield of 26.2% exceeds the fair level of 22.5%, and the EV/EBITDA multiple of 3.1 is below its own history. Verdict: the share is attractive at the current price, but the key question for a holder is whether profit will remain sufficient for payouts.
Inkab Holding reported H1 2026 results: revenue fell 15.9% year on year to RUB 2,120.0 mn, but EBITDA rose 57.1% to RUB 699.0 mn and net profit reached RUB 301.0 mn against a loss a year earlier. The EBITDA margin reached 33.0% versus 17.7%, the net margin 14.2% versus minus 8.9%, and leverage at 1.02x LTM EBITDA remains moderate. With P/E LTM at 10.9 and the portal model implying 46% upside, the share looks attractive, although the durability of the new margin against falling revenue is the main question for the story.
Key takeaways
— Revenue fell 15.9% but EBITDA rose 57.1% – margin did all the work
— EBITDA margin of 33.0% versus 17.7% a year earlier – doubling on lower sales volume
— Net profit of RUB 301.0 mn against a loss a year earlier – margin 14.2% instead of minus 8.9%
— Net debt fell from RUB 3.8 bn at end-2025 to RUB 1.6 bn on 30 June 2026
— Leverage at 1.02x LTM EBITDA – debt is serviced with headroom
— P/E LTM 10.9 and EV/EBITDA LTM 6.4 – valuation does not look stretched
— The portal model implies 46% upside to the current price
Attractiveness
Key figures, RUB bn
Metric
H1 2025
H1 2026
Change
Revenue
2.52
2.12
-15.9%
EBITDA
0.45
0.70
+57.1%
Operating profit
0.34
0.61
+81.2%
Net profit
-0.22
0.30
to profit
EBITDA margin
17.7%
33.0%
+15.3 pp
Net margin
-8.9%
14.2%
+23.1 pp
Revenue fell 15.9% but EBITDA rose 57.1% – margin did all the work
In H1 2026 Inkab Holding's revenue was RUB 2,120.0 mn, 15.9% below the same period a year earlier. Lower sales in fibre-optic cable coincided with a sharp improvement in profitability: EBITDA rose 57.1% to RUB 699.0 mn.
This gap means the company sold less but earned substantially more per unit. Operating profit was RUB 607.0 mn on revenue of RUB 2,120.0 mn – about 28.6% of revenue, confirming a shift towards higher-margin orders or a reduction in low-margin deliveries.
For a holder, the important point is that profit growth was not accompanied by rising debt: net debt fell instead. The question is how durable the new sales mix is and whether the revenue decline reflects a one-off cut in less profitable contracts.
EBITDA margin of 33.0% versus 17.7% a year earlier – doubling on lower sales volume
The EBITDA margin in H1 2026 was 33.0% versus 17.7% a year earlier. The near-doubling on falling revenue indicates that the main contribution came from cost and sales structure rather than volume growth.
With revenue of RUB 2,120.0 mn and EBITDA of RUB 699.0 mn, the company retained a significant share of revenue after variable costs. Operating profit of RUB 607.0 mn shows that depreciation and other operating expenses did not erode this effect.
The durability of the 33.0% margin is the key question for the next report. If it holds near this level as revenue recovers, profit could grow multiple-fold; if it is a one-off from the order mix, the margin will revert to historical levels.
Net profit of RUB 301.0 mn against a loss a year earlier – margin 14.2% instead of minus 8.9%
Net profit in H1 2026 was RUB 301.0 mn at a net margin of 14.2%. A year earlier the company posted a loss at a margin of minus 8.9%, so the result reversed within a single year.
The gap between operating profit of RUB 607.0 mn and net profit of RUB 301.0 mn – about RUB 306.0 mn – covers interest, taxes and other items. This means debt service is still visible in the income statement but no longer overwhelms the operating result.
A net margin of 14.2% on revenue of RUB 2,120.0 mn is the level that, if the EBITDA margin holds, supports sustainable profit and possibly dividends in future, although the current dividend policy is not disclosed in the facts.
Net debt fell from RUB 3.8 bn at end-2025 to RUB 1.6 bn on 30 June 2026
Net debt on 30 June 2026 was RUB 1.6 bn versus RUB 3.8 bn on 31 December 2025 – a reduction of RUB 2.1 bn. Over twelve months, from 30 June 2025, debt fell from RUB 3.0 bn to RUB 1.6 bn, a reduction of RUB 1.4 bn.
Debt reduction alongside EBITDA growth means the company directed part of its earnings to repay obligations. This confirms the quality of profit: it did not get stuck in working capital or capex but reached the balance sheet.
Leverage at 1.02x LTM EBITDA is a moderate level that leaves room for manoeuvre. At such leverage interest expenses should not consume a significant share of operating profit, as the gap between operating and net profit shows.
Leverage at 1.02x LTM EBITDA – debt is serviced with headroom
The ratio of net debt to LTM EBITDA is 1.02. This is a level at which the company can service debt from current cash flow without strain.
For comparison: with LTM EBITDA of RUB 1,612.8 mn and net debt of RUB 1,640.0 mn, annual EBITDA almost fully covers the debt. This means that even if EBITDA falls by a third, leverage would remain below 1.5x, typically considered comfortable.
Low leverage matters against falling revenue: if sales continue to decline, the company has time to adjust without risking covenant breaches. However, the facts do not disclose covenant terms, so this remains a general judgement.
Share price, three years
P/E LTM 10.9 and EV/EBITDA LTM 6.4 – valuation does not look stretched
With a market capitalisation of RUB 6,600.0 mn and LTM profit of RUB 605.0 mn, the P/E LTM is 10.9. EV/EBITDA LTM is 6.4 on LTM EBITDA of RUB 1,612.8 mn.
These multiples do not look high for a company that has just doubled its margin and reduced debt. However, they cannot be compared with its own three-year history: the facts contain no averages for prior periods.
The portal model implies 46% upside to the current price. This is our own model, not a market consensus, and it relies on EBITDA growth and a target multiple. At current multiples the market appears not to price in the durability of the new margin.
The portal model implies 46% upside to the current price
On the portal's model, the fair value of an Inkab Holding share is 46% above the current market price. The model links EBITDA growth to a target multiple and compares the result with the market capitalisation of RUB 6,600.0 mn.
This upside does not come from a re-rating of the multiple but from EBITDA growth: over the last twelve months the figure was RUB 1,612.8 mn, which at EV/EBITDA of 6.4 implies an enterprise value of about RUB 10.3 bn against the current market capitalisation of RUB 6.6 bn.
This is our estimate, not a market consensus. It materialises if the margin holds and revenue stops falling. If the margin reverts to 17.7%, LTM EBITDA will shrink and the upside will disappear.
Valuation on the latest reported figures
Metric
Value
Market cap
6.60 bn ₽
P/E (LTM)
10.9
EV/EBITDA (LTM)
6.4
P/B
2.44
Net debt / EBITDA (LTM)
1.02
ROE
3.0%
Bottom line
The strong side of the report is the profit reversal: net profit of RUB 301.0 mn against a loss a year earlier, an EBITDA margin of 33.0% versus 17.7%, all while debt fell from RUB 3.8 bn to RUB 1.6 bn over six months. However, profit growth on a 15.9% revenue decline is a bet on the durability of the new margin, not on business growth. The P/E LTM of 10.9 and EV/EBITDA LTM of 6.4 do not look stretched, and the portal model implies 46% upside, but realising that upside depends on whether the margin holds in the next report. The verdict is attractive: the combination of low leverage, a doubled margin and a moderate multiple outweighs the risk of the margin reverting to historical levels.
On 25 November NMTP reported results for the third quarter of 2026. Revenue fell 32.3% year on year to RUB 11,944 mn, EBITDA – by 49.0% to RUB 5,613 mn, net profit – by 47.2% to RUB 5,426 mn. The EBITDA margin compressed to 47.0% from 62.4%, but the company remains in a net cash position of RUB 5,379 mn and pays generous dividends. At the current price the stock looks rather attractive: EV/EBITDA of 2.9 is below its own three-year average of 3.8, and the dividend yield of 16.3% is well above the 10.5% we consider fair for the name.
Key takeaways
— Revenue collapsed 32.3% year on year in Q3 after a 5.3% rise in Q2 – the transshipment portfolio failed to hold last year's level
— EBITDA fell twice as fast as revenue – the margin dropped to 47.0% from 62.4%, and each tonne of cargo now brings noticeably less operating profit
— Net profit fell 47.2% but remained above operating profit – items below the operating line supported it in the reported quarter
— The company sits on net cash of RUB 5,379 mn with negative net debt and EV/EBITDA of 2.9 – the market values it below its own three-year average of 3.8
— Dividends remain the main argument: RUB 1.1448 per share paid over the last 12 months with a 16.3% yield, and we estimate RUB 1.05 per share for the current year
— Operating cash flow for the quarter was RUB 2,592 mn – it covers capital expenditure but leaves no cushion for higher payouts
— On our fair-value model the stock trades 23% above its estimated fair value – upside is exhausted, and it is worth holding for dividends, not for re-rating
Attractiveness
Key figures, RUB bn
Metric
Q3 2025
Q3 2026
Change
Revenue
17.6
11.9
-32.3%
EBITDA
11.0
5.61
-49.0%
Operating profit
9.39
4.00
-57.4%
Net profit
10.3
5.43
-47.2%
Operating cash flow
7.43
2.59
-65.1%
Capex
5.21
—
—
EBITDA margin
62.4%
47.0%
-15.4 pp
Net margin
58.2%
45.4%
-12.8 pp
Revenue collapsed 32.3% year on year in Q3 after a 5.3% rise in Q2 – the transshipment portfolio failed to hold last year's level
In the third quarter of 2026 NMTP's revenue amounted to RUB 11,944 mn, 32.3% below the same quarter a year earlier. This is a sharp deceleration after 5.3% growth in the second quarter: the top-line dynamic reversed from a slight plus to a deep minus.
A revenue decline of this magnitude means that cargo turnover and tariffs did not offset the lost volumes. The company did not disclose a line-by-line breakdown in the facts, so it is impossible to name the segment that fell most. One thing is clear: the quarter was a failure compared with last year's level, when revenue was RUB 17,632 mn.
Revenue and EBITDA by quarter
EBITDA fell twice as fast as revenue – the margin dropped to 47.0% from 62.4%, and each tonne of cargo now brings noticeably less operating profit
EBITDA in the third quarter was RUB 5,613 mn, down 49.0% year on year – faster than revenue, which fell 32.3%. Operating profit declined to RUB 4,002 mn, and that fall was deeper than the top line's.
The EBITDA margin compressed to 47.0% from 62.4% a year earlier, the net margin – to 45.4% from 58.2%. This gap suggests that fixed costs did not adjust quickly enough to the smaller transshipment volume. Each rouble of revenue now brings almost half as much operating profit as a year ago.
Net profit by quarter
Net profit fell 47.2% but remained above operating profit – items below the operating line supported it in the reported quarter
Net profit for the third quarter was RUB 5,426 mn against RUB 10,268 mn a year earlier, a decline of 47.2%. At the same time profit exceeded operating profit, which was RUB 4,002 mn. The difference of RUB 1,424 mn came from items below the operating line – likely interest on the cash position and other income, but the exact composition is not disclosed in the facts.
For the investor it matters that net profit remains positive and exceeds operating profit. This means that even in a weak quarter the company generates profit sufficient to support the dividend base. However, the sustainability of this support depends on how one-off or recurring the income below the operating line is.
Net debt at reporting dates
The company sits on net cash of RUB 5,379 mn with negative net debt and EV/EBITDA of 2.9 – the market values it below its own three-year average of 3.8
Net debt as of 30 September 2026 was minus RUB 5,379 mn, meaning the company has a net cash position. The ratio of net debt to EBITDA over the last twelve months is minus 0.13. This is a level, not a direction: it cannot be compared with past values, but the net cash position itself removes debt pressure.
The EV/EBITDA multiple over the last twelve months is 2.9, 24% below its own three-year average of 3.8. The stock trades cheaper than usual on this multiple. P/E over the last twelve months is 3.6 – a low level reflecting both the weakness of profit and general undervaluation.
On our fair-value model, which compares EBITDA growth with the target multiple, the stock trades 23% above its estimated fair value. This is our own calculation, not a market consensus. It suggests that the current price already prices in a recovery, and one should not count on re-rating upwards.
Valuation vs its own history
Dividends remain the main argument: RUB 1.1448 per share paid over the last 12 months with a 16.3% yield, and we estimate RUB 1.05 per share for the current year
Over the last twelve months NMTP paid RUB 1.1448 per share, which at the current price gives a yield of 16.3%. In calendar 2026, RUB 1.14 per share has already been paid, and no further payouts are planned for this year. This is a generous stream: the yield is more than double the key rate of 14.0%.
Our estimate of the payout for the current financial year, to be paid next year, is RUB 1.05 per share, corresponding to 15.0% on the current price. This is our calculation: we take net profit over the last twelve months, multiply by the share of profit paid out last year (0.54), and divide by the number of shares. The board decides, and the actual payout may differ.
The yield history shows that the current level is not anomalous: in 2025 the yield at the ex-date was 10.5%, in 2026 – 13.3%. We consider a yield of 10.5% fair for this name. The current yield of 16.3% is above both the fair and historical levels, which compensates for the weakness of profit.
A further fall in revenue and profit, as well as rising capital expenditure, could reduce the payout. Capital expenditure is not disclosed for the third quarter, but in the second quarter it was RUB 7,689 mn – a significant burden. If profit continues to decline, the dividend base will narrow, and the board may revise the payout ratio.
Share price, three years
Operating cash flow for the quarter was RUB 2,592 mn – it covers capital expenditure but leaves no cushion for higher payouts
Operating cash flow in the third quarter was RUB 2,592 mn against RUB 7,435 mn a year earlier. The more than twofold decline reflects lower revenue and profit. Over the last twelve months the flow was RUB 31,990 mn – a solid base, but the quarterly dynamic shows that the margin of safety is shrinking.
Capital expenditure is not disclosed for the reported quarter, but in the second quarter it was RUB 7,689 mn, and in the first – RUB 5,419 mn. With quarterly flow of RUB 2,592 mn, the company does not cover such investment from current flow and is spending its accumulated cash. The net cash position of RUB 5,379 mn still allows this, but the cushion is not endless.
For dividends this means that payouts are financed not only by flow but also by cash balances. If operating flow does not recover and capital expenditure remains high, the dividend may be cut. For now the company pays more than it earns in the quarter – a warning signal for the sustainability of payouts.
Dividend per share and yield at the ex-date
On our fair-value model the stock trades 23% above its estimated fair value – upside is exhausted, and it is worth holding for dividends, not for re-rating
Our fair-value model, which compares EBITDA growth with the target multiple, shows that the stock trades 23% above its estimated fair value. This is our own calculation, not a market consensus. It suggests that the current price already prices in a recovery of profit, and one should not count on re-rating upwards.
At the same time, the EV/EBITDA multiple of 2.9 is 24% below its own three-year average of 3.8. This indicates that the stock is cheaper than usual on this multiple. The discrepancy with the model is explained by the fact that the model takes into account not only the current multiple but also the EBITDA dynamic, which was weak in the third quarter.
For the investor this means that the main return will come from dividends, not from share price growth. A yield of 16.3% against the fair 10.5% is a weighty argument in favour of holding the stock. But if profit continues to fall, the dividend base will narrow, and then the current price will not look so low.
Valuation on the latest reported figures
Metric
Value
Market cap
135 bn ₽
P/E (LTM)
3.6
EV/EBITDA (LTM)
2.9
P/B
0.79
Net debt / EBITDA (LTM)
-0.13
Operating cash flow (LTM)
32.0 bn
ROE
3.6%
Dividend yield (12m)
16.2%
EV/EBITDA, 3-year average
3.8
Dividend per share, ₽, and yield at the ex-date
Year paid
Dividend
Yield
2021
0.06
0.9%
2022
0.54
9.4%
2023
0.80
8.0%
2024
0.77
7.4%
2025
0.96
10.5%
2026
1.14
13.3%
Our estimate, current year
1.05
15.0% on the current price
Bottom line
The strong side of the report remains financial stability: a net cash position of RUB 5,379 mn and an EV/EBITDA multiple of 2.9 below its own three-year average of 3.8. However, revenue fell 32.3%, EBITDA – by 49.0%, and the margin compressed to 47.0% from 62.4%. The dividend yield of 16.3% against the fair 10.5% is the main argument in favour of the stock, but operating flow of RUB 2,592 mn does not cover capital expenditure. On our fair-value model the stock trades 23% above its estimated fair value, so it is worth holding for dividends, not for share price growth.
This season's defining split is not between oil and tech but between companies riding volume and price upside and those still digesting the 2024-2025 cost shock. Mining and electricity delivered the widest spread: the mining median rose 30.1% year over year while metallurgy fell 10.8%, a 41-point gap. Construction and chemicals also contracted, with medians of -4.5% and -4.7%. The market is rewarding volume and pricing power and punishing anything tied to domestic capex or export tariffs.
Revenue growth by industry (median YoY)
median revenue YoY, %
Gold and power grids delivered the cleanest upside
The mining median of +30.1% is not a single-name fluke. Seligdar posted revenue +46.5%, EBITDA +145.6% and net profit +257.3%, while Yuzhuralzoloto grew revenue +90.5% and EBITDA +197.2%. Even Nornickel, the diversified giant, lifted revenue +12.6% and net profit +108.4%. In electricity, IDGC South was the standout with revenue +150.0%, EBITDA +233.6% and net profit +425.4%, and Rushydro added revenue +18.9% with net profit +90.1%.
The breadth matters as much as the headline. Six of the seven IDGC subsidiaries reported double-digit revenue growth, and Rosseti Moscow Region grew revenue +22.2% with net profit +46.5%. This is a sector where regulated tariffs and volume recovery are finally flowing through to the bottom line.
Steel and construction are the season's warning sign
Metallurgy's -10.8% median is ugly across the board. Severstal saw revenue -10.1%, EBITDA -27.9% and net profit -61.2%; NLMK reported revenue -11.6% and net profit -54.3%; TMK was the worst with revenue -36.9% and EBITDA -78.0%. Construction is no better: Samolet's revenue fell 31.3% and EBITDA 39.9%, while PIK declined 11.6% in revenue with net profit down 54.1%. These are not one-off misses; they are a capex and demand cycle turning down.
The plot twist: Lukoil's profit surge is the outlier nobody priced
Oil and gas as a sector grew just 3.5% in revenue, but Lukoil accelerated from an unspecified prior period to revenue +8.0%, EBITDA +93.3% and net profit +387.3%. That is a genuine surprise in a sector where Gazprom's net profit fell 9.8% and Rosneft's dropped 18.4%. The divergence suggests Lukoil's downstream and trading mix is doing heavy lifting while peers are squeezed by export economics.
Cheap for growth: Sberbank and Sovcombank screen as value traps or bargains
Sberbank trades at 3.5x earnings while growing revenue 22.5% and net profit 18.6%. Sovcombank is even cheaper at 2.9x P/E with revenue +70.4% and net profit +158.2%. Both look mispriced if growth holds. At the other extreme, Ozon trades at 35.9x earnings with revenue +47.8% but EBITDA -181.0% and net profit -222.6% — priced for perfection in a business still burning cash. Diasoft at 23.0x P/E with revenue -2.8% and net profit -77.3% is expensive for the wrong reason.
Income: FGC UES and Inter RAO offer yield with growth
FGC UES looks like the income play of the season: P/E 0.5x, EV/EBITDA 1.7x, with revenue +16.3%, EBITDA +28.5% and net profit +50.2%. Inter RAO at P/E 1.7x and EV/EBITDA 0.3x is even cheaper on cash flow, though its net profit fell 17.2%. For a value investor, these are the names where the market is paying you to wait.
The long view belongs to ArenaData and Positive: three-year revenue CAGRs of +52.0% and +30.9% respectively, yet both trade at single-digit EV/EBITDA multiples (5.3x and 6.2x). If the IT cycle holds, these are the compounders hiding in plain sight. Watch the next two quarters for whether the growth deceleration in some IT names (Head Hunter at 0.0% revenue) spreads — that is the key risk to the value case.
The published operating data point to uneven momentum. In Transport and logistics, Aeroflot carried 4.8 mln passengers in September 2026, down 4.2% y/y. In Finance, MOEX total volume reached 205.2 trln RUB in September 2026, up 18.3% y/y, while Europlan new business (incl. VAT) was 49.1 bln RUB in H1 2026, up 13.1% y/y. In Retail, X5 net retail revenue was 1270 bln RUB in Q2 2026, up 9.4% y/y, and Magnit LFL sales rose 6.4% y/y in H1 2026.
Operating momentum, latest reported period (YoY)
%
In Metals and mining, steel output rose: Severstal produced 2.8 mln t in Q2 2026 (+11.8% y/y), MMK 2.7 mln t (+7.3% y/y), NLMK 6.8 mln t in H1 2026 (n/a). Rusal produced 2.0 mln t of aluminium in H1 2026 (n/a). In Mining, Norilsk Nickel produced 85 ths t of nickel in H1 2026 (n/a), Polyus gold output was 1286.9 koz in H1 2026 (-1.8% y/y), and Uzhuralzoloto gold output was 12 t in FY 2025 (+13.2% y/y).
In IT, Ozon GMV reached 1311 bln RUB in Q2 2026 (+36.8% y/y), Whoosh trips were 56.5 mln in H1 2026 (+0.0% y/y), Delimobil sold minutes were 560 mln in Q2 2026 (n/a), and Astra shipments (excl. VAT) were 7.3 bln RUB in H1 2026 (n/a). Elsewhere, Inarctica biomass in water was 27.7 ths t in H1 2026 (+32.5% y/y), Etalon contract value was 23.2 bln RUB in Q2 2026 (n/a), Novatek gas production was 43.7 bln m3 in H1 2026 (n/a), and PhosAgro agrochemicals totaled 12.2 mln t in FY 2025 (+3.4% y/y).
In upcoming reporting, attention should focus on whether the positive y/y dynamics in Finance, Retail, IT (Ozon) and Metals translate into margins and cash flow, and on the negative or flat signals: Aeroflot passengers (-4.2% y/y), Polyus gold (-1.8% y/y) and Whoosh trips (+0.0% y/y). For companies with n/a comparisons, the key is disclosure of absolute volumes and their consistency with prior periods.
Phosagro reported results for the third quarter of 2026. Revenue rose 15.0% year on year to RUB 164.7 bn, EBITDA added only 0.5% to RUB 51.3 bn, and net profit fell 37.2% to RUB 12.6 bn. Revenue growth accelerated versus the second quarter (+7.7%), but the EBITDA margin declined to 31.2% from 35.7% a year earlier, and leverage at 2.64 EBITDA together with a valuation above its own history make the share unattractive at the current price.
Key takeaways
— Revenue rose 15.0% year on year in the third quarter, an acceleration from +7.7% in the second quarter
— EBITDA added only 0.5% because the margin fell to 31.2% from 35.7%
— Net profit fell 37.2% to RUB 12.6 bn with a margin of 7.7% versus 14.1% a year earlier
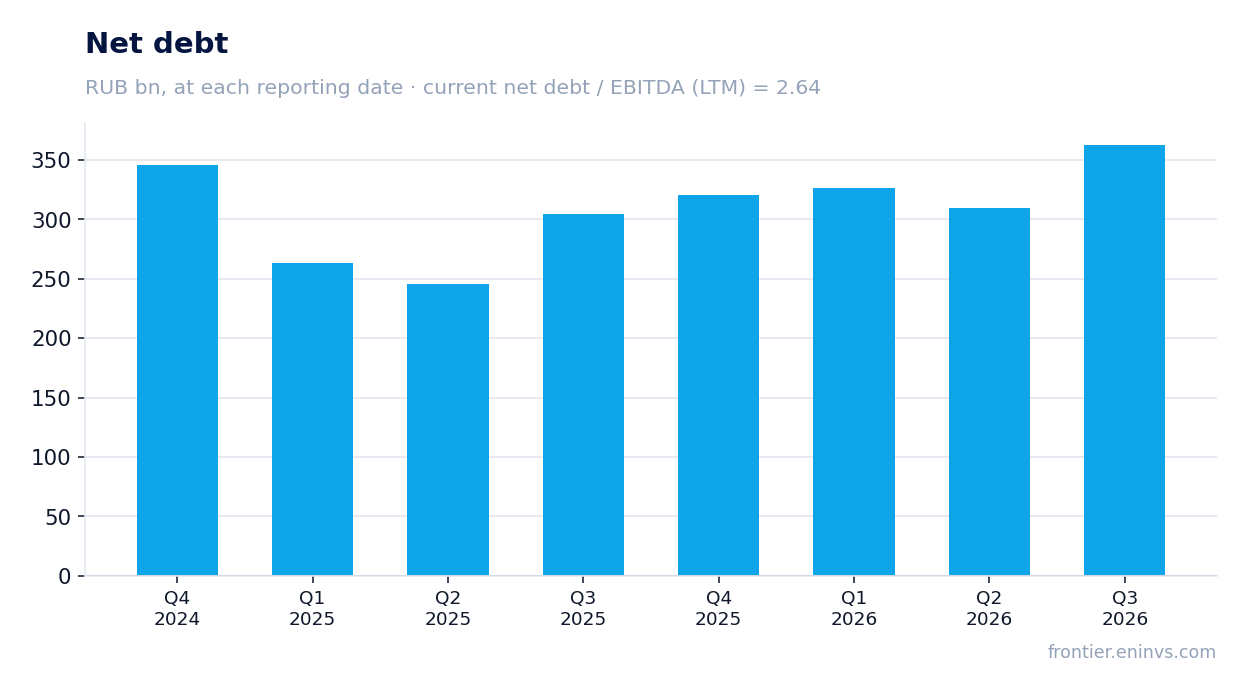
— Net debt rose to RUB 362.7 bn at the end of September from RUB 309.2 bn at the end of June
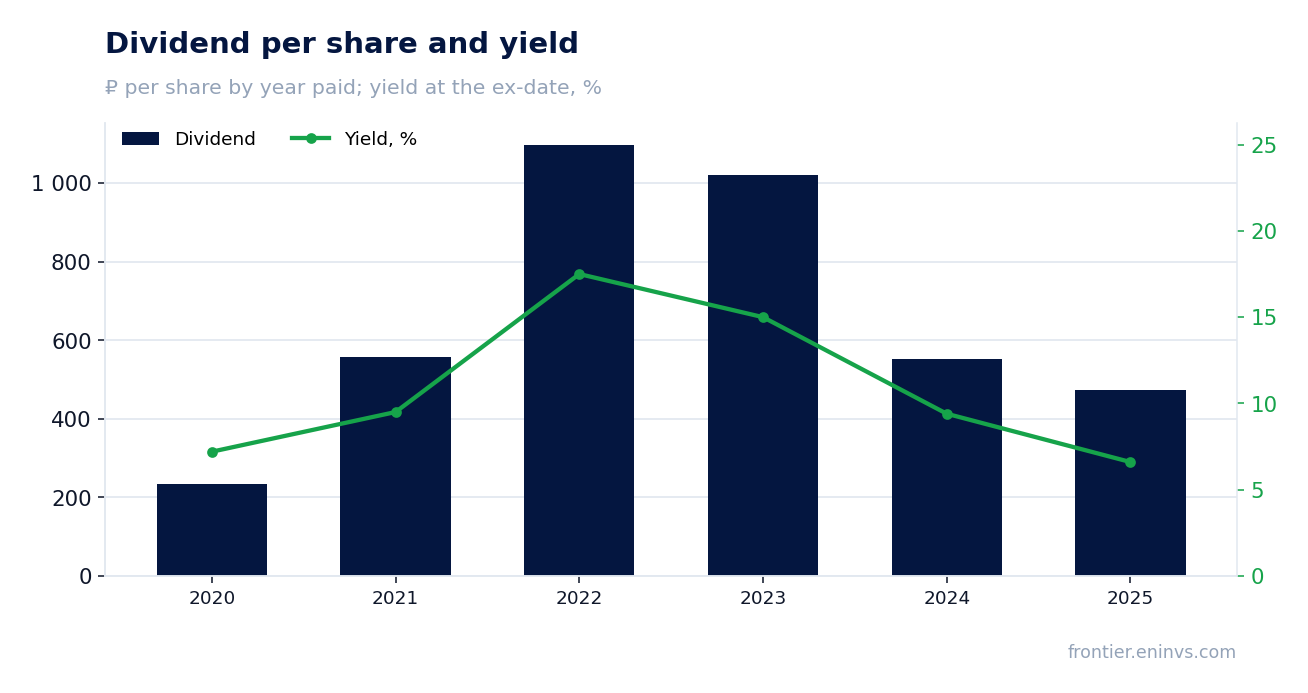
— The dividend for 2025 was RUB 474 per share, while our estimate for the current year is RUB 207.88 per share
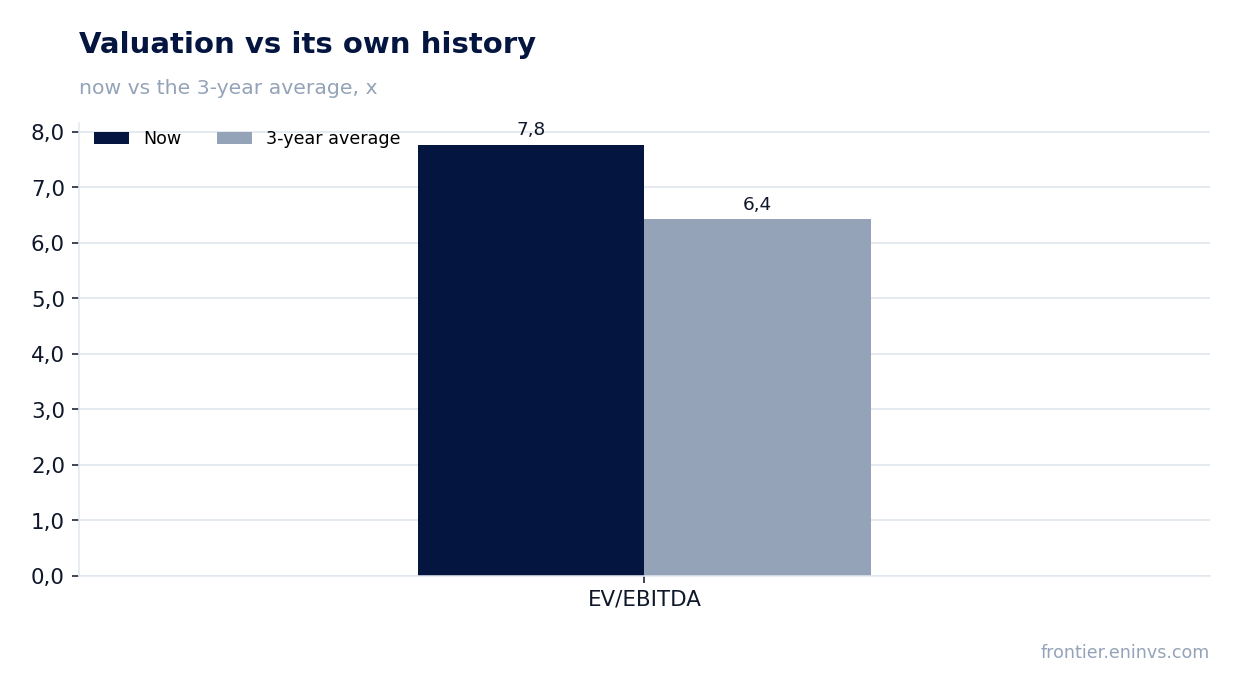
— EV/EBITDA LTM of 7.8 is 21% above its own three-year average of 6.4
Attractiveness
Key figures, RUB bn
Metric
Q3 2025
Q3 2026
Change
Revenue
143
165
+15.0%
EBITDA
51.1
51.3
+0.5%
Operating profit
40.5
39.2
-3.2%
Net profit
20.1
12.6
-37.2%
Operating cash flow
40.5
39.2
-3.2%
Capex
15.7
21.1
+34.5%
EBITDA margin
35.7%
31.2%
-4.5 pp
Net margin
14.1%
7.7%
-6.4 pp
Revenue rose 15.0% year on year in the third quarter, an acceleration from +7.7% in the second quarter
Revenue for the third quarter of 2026 was RUB 164.7 bn, 15.0% more than a year earlier. In the second quarter growth was more modest at 7.7%, so the pace accelerated. This is the best quarterly revenue result since the fourth quarter of 2024.
The acceleration rests on recovery from a weak base: in the first quarter of 2026 revenue fell 17.5% year on year, in the second it grew 7.7%. The third consecutive quarter shows improvement, but the absolute level of revenue is still below the peaks of 2024–2025.
For profit this growth does not yet convert: EBITDA added only 0.5%, and net profit fell. Revenue is growing faster than costs, but not fast enough to hold the margin.
Revenue and EBITDA by quarter
EBITDA added only 0.5% because the margin fell to 31.2% from 35.7%
EBITDA for the third quarter was RUB 51.3 bn, only 0.5% more than a year earlier. With revenue growth of 15.0%, this means the EBITDA margin declined to 31.2% from 35.7% in the third quarter of 2025.
Operating profit was RUB 39.2 bn. The gap between revenue growth and stagnant EBITDA points to cost of sales or selling expenses rising faster than revenue. The facts contain no breakdown by cost line, so the specific cause cannot be named.
A margin of 31.2% is still a high level for the company, but a decline of 4.5 percentage points year on year eats into the effect of sales growth. This is exactly why profit falls while revenue rises.
Net profit by quarter
Net profit fell 37.2% to RUB 12.6 bn with a margin of 7.7% versus 14.1% a year earlier
Net profit for the third quarter of 2026 was RUB 12.6 bn, 37.2% less than a year earlier. The net margin fell to 7.7% from 14.1% in the third quarter of 2025.
The profit decline is deeper than the EBITDA decline, which points to rising expenses below the operating line — likely interest. Debt has grown, and servicing it costs more. The facts contain no interest expense figure, so the exact cause cannot be named.
Over the last twelve months net profit was RUB 49.9 bn. This is noticeably below the level of previous years, and this base determines the company's dividend capacity.
Net debt at reporting dates
Net debt rose to RUB 362.7 bn at the end of September from RUB 309.2 bn at the end of June
Net debt at 30 September 2026 was RUB 362.7 bn versus RUB 309.2 bn at 30 June 2026 — an increase of RUB 53.5 bn over the quarter. A year earlier, at 30 September 2025, debt was RUB 304.2 bn, so over 12 months it rose by RUB 58.5 bn.
The ratio of net debt to EBITDA LTM is 2.64. This is a level that limits freedom of manoeuvre: with falling EBITDA, leverage becomes more sensitive to further deterioration in results.
Operating cash flow for the third quarter was RUB 39.2 bn, capital expenditures — RUB 21.1 bn. Free cash flow is positive, but it is not enough to cover interest expenses and dividends while servicing debt.
Valuation vs its own history
The dividend for 2025 was RUB 474 per share, while our estimate for the current year is RUB 207.88 per share
No dividends were paid over the last 12 months. The last payment was RUB 474 per share for 2025, which at the ex-date price of RUB 7,182 gave a yield of 6.6%. The payment history shows a decline: RUB 1,098 per share in 2022, RUB 1,020 in 2023, RUB 552 in 2024.
Our estimate for the dividend for the current financial year is RUB 207.88 per share, which gives about 3.6% on the current price. This is our forecast, not a board decision: the calculation is based on net profit over the last 12 months and a payout ratio of 0.54 of profit, as last year.
A yield of 3.6% is noticeably below the key rate of 14.0% and below the yield we consider fair for this name — 10.5%. The dividend history of recent years shows payments declining with profit, and at the current profit base the dividend is unlikely to return to the levels of 2022–2023.
Share price, three years
EV/EBITDA LTM of 7.8 is 21% above its own three-year average of 6.4
On the EV/EBITDA LTM multiple of 7.8, the share trades 21% above its three-year average of 6.4. This means the market values the company more expensively than usual over the last three years, despite falling profit.
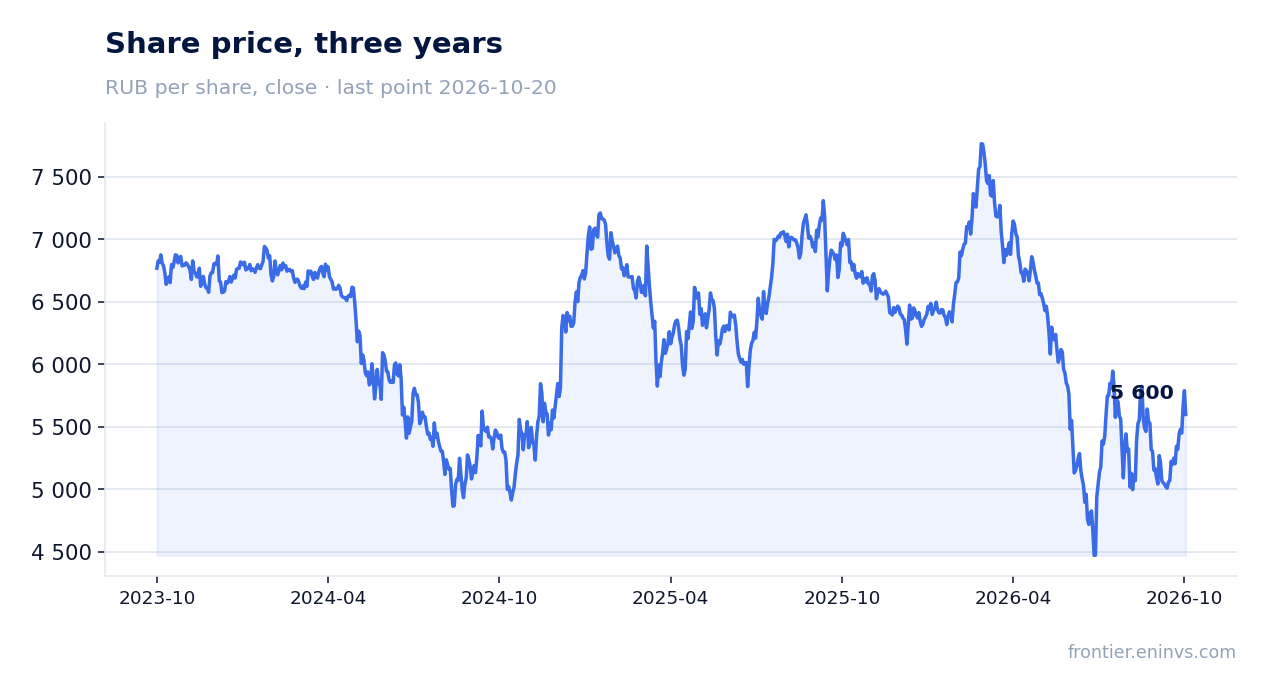
P/E LTM is 15.0. With net profit over the last 12 months of RUB 49.9 bn and a market capitalisation of RUB 747.2 bn, this does not look cheap for a company with a falling margin.
On the portal's model, which reprices EBITDA at current commodity prices at the target EV/EBITDA, the upside of the share to fair value is estimated at minus 32%. This is our own estimate, not a market consensus.
Valuation on the latest reported figures
Metric
Value
Market cap
747 bn ₽
P/E (LTM)
15.0
EV/EBITDA (LTM)
7.8
P/B
3.12
Net debt / EBITDA (LTM)
2.64
Operating cash flow (LTM)
97.4 bn
ROE
6.1%
EV/EBITDA, 3-year average
6.4
Dividend per share, ₽, and yield at the ex-date
Year paid
Dividend
Yield
2020
234.00
7.2%
2021
558.00
9.5%
2022
1098.00
17.5%
2023
1020.00
15.0%
2024
552.00
9.4%
2025
474.00
6.6%
Our estimate, current year
207.88
3.6% on the current price
Dividend per share and yield at the ex-date
Bottom line
The strong side of the report is the acceleration of revenue to 15.0% year on year, the best quarterly result since the end of 2024. But growth does not convert into profit: EBITDA added only 0.5%, net profit fell 37.2%, and the margin compressed. Debt rose to RUB 362.7 bn, the dividend forecast is modest, and the valuation is above its own history. The verdict is unattractive: the share offers neither growing profit, nor a high dividend yield, nor a discount to history.
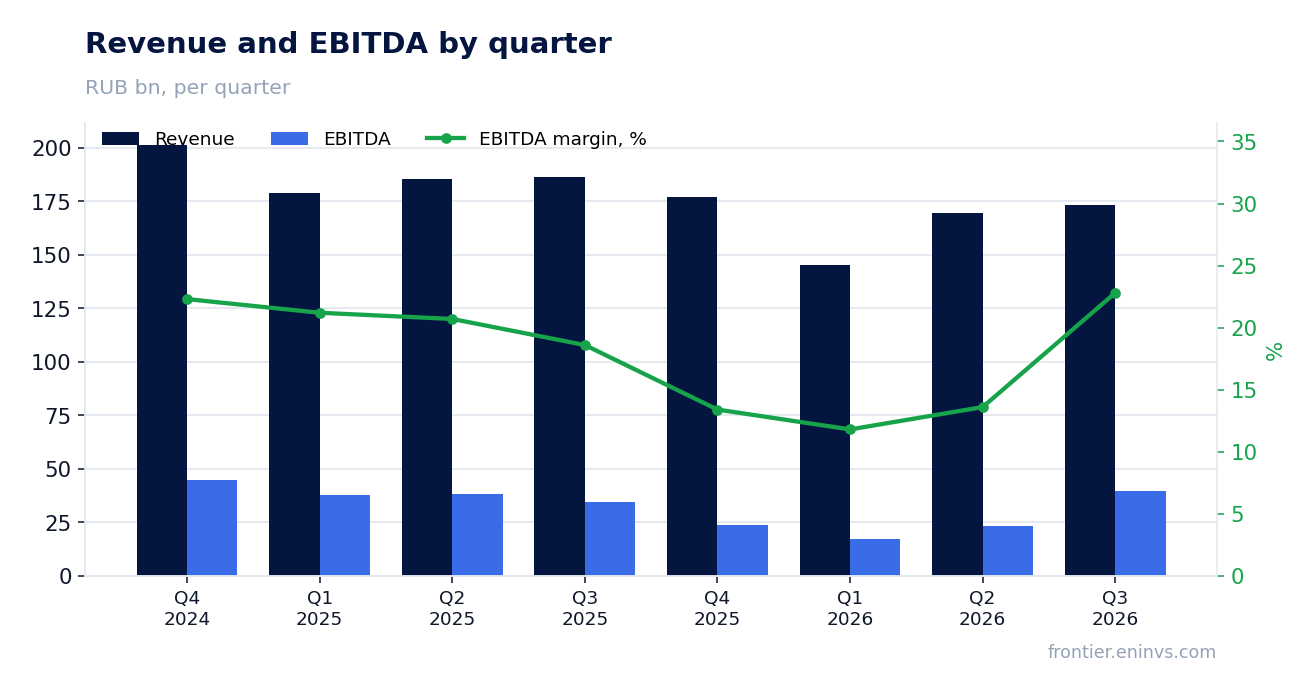
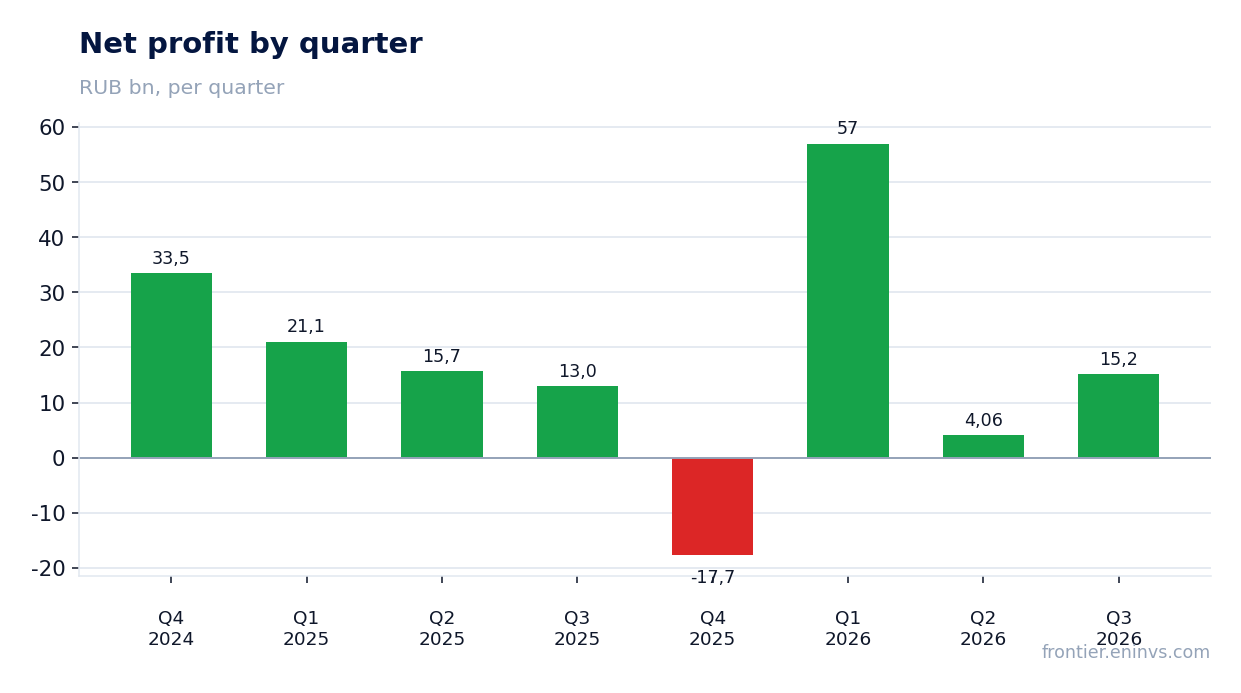
On 20 October Severstal published its results for the nine months and the third quarter of 2026. Quarterly revenue was RUB 173.5 bn (–7.0% year on year), EBITDA RUB 39.6 bn (+14.1%), net profit RUB 15.2 bn (+16.8%), and the EBITDA margin rose to 22.8% from 18.6% a year earlier. Yet the share trades above its own history: EV/EBITDA LTM 6.3 against a three-year average of 4.6, and the portal's model puts the upside to fair value at –39%. The verdict is neutral: the margin and cash flow are strong, but valuation and the absence of a dividend outweigh them.
Key takeaways
— Revenue fell 7.0%, but the decline is shallower than in the second quarter (–8.6%)
— EBITDA added 14.1% on falling revenue – the margin rose to 22.8% from 18.6%
— Quarterly net profit of RUB 15.2 bn rests on FX differences, not only on operating results
— Operating cash flow of RUB 64.5 bn for the quarter – cash arrived ahead of profit
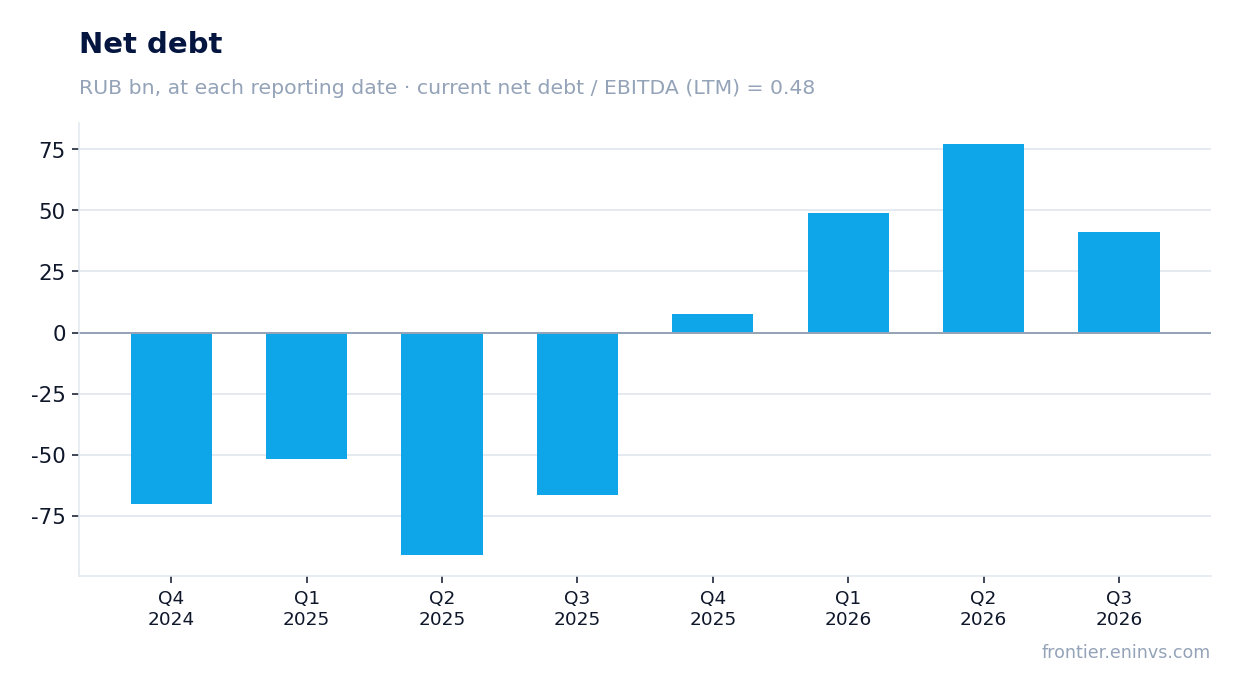
— Net debt fell to RUB 41.3 bn from RUB 77.3 bn at end-June, leverage at 0.48 EBITDA
— No dividends were paid over the last 12 months, and none is pencilled in for this year
— EV/EBITDA of 6.3 is above its own three-year average of 4.6 – the share is dearer than its history
Attractiveness
Key figures, RUB bn
Metric
Q3 2025
Q3 2026
Change
Revenue
187
174
-7.0%
EBITDA
34.7
39.6
+14.1%
Operating profit
23.3
27.3
+17.5%
Net profit
13.0
15.2
+16.8%
Operating cash flow
42.4
64.5
+52.1%
Capex
4.22
—
—
EBITDA margin
18.6%
22.8%
+4.2 pp
Net margin
7.0%
8.7%
+1.7 pp
Revenue fell 7.0%, but the decline is shallower than in the second quarter (–8.6%)
Third-quarter revenue was RUB 173.5 bn against RUB 186.5 bn a year earlier. The 7.0% decline was smaller than the 8.6% in the second quarter – the pace of contraction slowed rather than accelerated. This is the first improvement in quarterly dynamics after four consecutive quarters of deepening decline.
By product, metal products brought RUB 152.5 bn for the quarter against RUB 159.6 bn a year earlier, transport and warehousing services RUB 10.9 bn against RUB 9.7 bn, and other RUB 10.1 bn against RUB 9.8 bn. The decline is concentrated in the core steel segment, while service lines grew.
In the report management attributes weak demand to the high key rate: end consumers of steel products are not restoring purchases in 2026. While that factor persists, revenue will stay under pressure, and the better quarterly pace is stabilisation rather than a reversal.
Revenue and EBITDA by quarter
EBITDA added 14.1% on falling revenue – the margin rose to 22.8% from 18.6%
Quarterly EBITDA was RUB 39.6 bn against RUB 34.7 bn a year earlier, up 14.1%. The EBITDA margin rose to 22.8% from 18.6%, a gain of 4.2 percentage points. Operating profit increased to RUB 27.3 bn from RUB 23.3 bn.
That gap between revenue and EBITDA means cost of sales shrank faster than sales. Other taxes and levies within cost of sales fell to RUB 4.3 bn for the quarter from RUB 4.9 bn a year earlier, while depreciation of production assets rose to RUB 12.3 bn from RUB 11.4 bn – the savings came through cash cost lines, not accounting adjustments.
By segment, Severstal Resources EBITDA was RUB 9.2 bn against RUB 14.1 bn a year earlier, while Severstal Russian Steel was RUB 31.8 bn against RUB 19.4 bn. The mining division weakened and the steel division doubled its result – the margin was pulled by the processing stage, not by raw materials.
Net profit by quarter
Quarterly net profit of RUB 15.2 bn rests on FX differences, not only on operating results
Third-quarter net profit was RUB 15.2 bn against RUB 13.0 bn a year earlier, up 16.8%. The net margin rose to 8.7% from 7.0%. Yet profit before tax and financial items for the nine months was RUB 38.9 bn against RUB 73.5 bn a year earlier – the operating base over three quarters is markedly weaker than last year's.
The gap is explained by FX differences. For the quarter the net FX loss was RUB 3.7 bn against RUB 5.7 bn a year earlier, so currency revaluation weighed less on profit. For the nine months the FX loss was RUB 9.2 bn against RUB 10.1 bn. That is not operating income, and the sign may flip next quarter.
For the nine months net profit was RUB 19.3 bn against RUB 49.7 bn a year earlier. Quarterly profit growth against a weak nine-month result is a recovery from the collapse at the start of the year, not a durable trend.
Net debt at reporting dates
Operating cash flow of RUB 64.5 bn for the quarter – cash arrived ahead of profit
Quarterly operating cash flow was RUB 64.5 bn – more than four times net profit. For the nine months it came to RUB 46.8 bn after interest and tax, against RUB 89.9 bn a year earlier. The quarterly surge partly reflects working-capital release: over nine months trade payables rose by RUB 20.6 bn while inventories added RUB 8.7 bn.
Capital expenditure for the nine months was RUB 72.3 bn against RUB 122.2 bn a year earlier, so the investment programme has been almost halved. Free cash flow for the nine months was negative at minus RUB 27.6 bn, but in the third quarter it turned positive at RUB 42.6 bn.
The combination of a strong quarterly flow and a trimmed construction programme produced the cash that was missing in the first half. Unrecognised capital commitments at 30 September were RUB 41.7 bn against RUB 72.5 bn at end-2025, so pressure on investment is easing.
Valuation vs its own history
Net debt fell to RUB 41.3 bn from RUB 77.3 bn at end-June, leverage at 0.48 EBITDA
Net debt at 30 September was RUB 41.3 bn against RUB 77.3 bn at 30 June – a reduction of RUB 36.0 bn over the quarter. The ratio of net debt to trailing twelve-month EBITDA is 0.48, so leverage is moderate. A year earlier, at 30 September 2025, net debt was negative at minus RUB 66.6 bn, so over twelve months it rose by RUB 107.9 bn.
The debt portfolio is being restructured: in March the BO-06 and BO-07 exchange bonds were repaid for RUB 15.4 bn, and in July two-year 002Р-01 bonds were issued for RUB 25 bn with a floating rate and a 110 basis point spread to the key rate. Short-term debt fell to RUB 41.2 bn from RUB 56.3 bn at end-2025, while long-term debt rose to RUB 29.9 bn from RUB 3.8 bn.
Interest paid over nine months was RUB 15.3 bn against RUB 24.0 bn a year earlier. With the key rate at 14.0% and a floating coupon, the new issue means debt servicing will follow the rate: a cut eases the interest burden, a rise does not.
Share price, three years
No dividends were paid over the last 12 months, and none is pencilled in for this year
Over the last 12 months Severstal paid no dividends – RUB 0.0 per share – and no further payout is pencilled in for the current calendar year. The last payment in the history is for 2024: RUB 309.93 per share at a 29.4% yield to the ex-date price. The yield history is uneven: 8.9% in 2018, 13.4% in 2019, 8.9% in 2020, 15.9% in 2021.
Our estimate of a fair yield for this name is 15.0%, corresponding to a payout ratio of 0.72 of profit. With the key rate at 14.0%, that yield offers only a small premium to the risk-free alternative, and only if profit recovers. The base is weak: trailing twelve-month net profit is RUB 58.5 bn, but nine-month 2026 profit is only RUB 19.3 bn.
The payout could be reduced by anything that hits profit: a further fall in revenue, a weak rouble through FX differences, higher interest costs on the floating coupon. While the company directs cash to debt reduction and investment, the dividend is a question for next year, not this one.
Dividend per share and yield at the ex-date
EV/EBITDA of 6.3 is above its own three-year average of 4.6 – the share is dearer than its history
On the trailing twelve-month EV/EBITDA the share trades at 6.3 against a three-year average of 4.6 – 35% above its own history. The trailing P/E is 10.4 and ROE is 3.7%. The market is paying for a margin recovery more than it is worth by historical standards.
On the portal's model, where EBITDA is re-priced at current commodity prices at the target EV/EBITDA, the upside of the share to fair value is negative at –39%. This is our own estimate, not a market consensus, and it rests on current commodity prices.
Only a durable EBITDA recovery can justify the premium to history. A quarterly margin of 22.8% is a step in that direction, but revenue is still falling and nine-month profit is a third of last year's. Until both conditions are met, the valuation looks stretched.
Valuation on the latest reported figures
Metric
Value
Market cap
608 bn ₽
P/E (LTM)
10.4
EV/EBITDA (LTM)
6.3
P/B
1.22
Net debt / EBITDA (LTM)
0.48
Operating cash flow (LTM)
81.2 bn
ROE
3.7%
EV/EBITDA, 3-year average
4.6
Dividend per share, ₽, and yield at the ex-date
Year paid
Dividend
Yield
2018
90.33
8.9%
2019
121.70
13.4%
2020
106.39
8.9%
2021
253.42
15.9%
2024
309.93
29.4%
Bottom line
What came out strong in the report was the margin and the cash: EBITDA added 14.1%, the margin rose to 22.8%, quarterly operating cash flow was RUB 64.5 bn, and net debt fell to RUB 41.3 bn at 0.48 EBITDA. But part of the quarterly profit came from smaller FX losses rather than from operations, and nine-month net profit is a third of last year's. No dividends were paid over the last 12 months, and none is pencilled in for this year. The key question for a holder is whether a durable margin recovery justifies a multiple of 6.3 against its own 4.6 average; with no answer yet, the verdict is neutral.
Rolf bonds yield 21-22% to maturity with the key rate at 14%. The issuer itself, ROLF JSC, earns money and services its own debt with a margin of safety. The premium of 7-8 percentage points is the price for the holding company sitting above it, which bought the business on credit in 2024. Rolf guarantees that loan, which is serviced with Rolf's cash and the owner's loans. We consider the short issues maturing in January and May 2027 an acceptable risk for investors who deliberately take high-yield bond risk. The long 1R09 to 2028 depends on how the group refinances the acquisition loan, and there the yield looks fair rather than generous.
The issuer page with financials by period and all bond issues: Rolf. Below are Enhanced Investments estimates based on the IFRS statements of Rolf Group (PromAgroLogistika JSC) and the standalone IFRS of ROLF JSC for 2025 and 1H2026, releases by ACRA, NCR and Expert RA, and Moscow Exchange and Federal Tax Service data. Where a figure is our estimate, it is marked.
Key points:
In August 2024 the PAL holding company bought Rolf from the state for RUB 34.8bn. The money came from a bank, and Rolf became a guarantor of that loan (RUB 30.1bn at the end of 2025). The ultimate owner is Umar Kremlev, president of the International Boxing Association (IBA).
The issuer's own numbers are good: net debt to EBITDA of 1.4x, net profit of RUB 1.0bn for the half-year, equity of RUB 30bn. But including the guarantee, Rolf's leverage is close to the group's.
The whole group including the acquisition loan looks different. Net debt to EBITDA is 3.8x, equity is minus RUB 3.4bn, the half-year loss is RUB 1.7bn. The auditor's review report points to a material uncertainty about the group's ability to continue as a going concern.
Rolf pays dividends to the holding even when its own cash flow is negative. The owner covers the gap with interest-free loans, which reached RUB 9bn by 30 June.
The group sells new cars at a negative margin. The money comes from loans, insurance, service and used cars.
Bonds are only RUB 6bn out of the group's RUB 51bn of debt. The next maturity is RUB 2bn in January 2027, against RUB 13.9bn of undrawn bank limits.
Ratings are A-(RU) from ACRA and BBB+.ru from NCR. Expert RA cut its rating by three notches in a year and withdrew it in September 2026.
The bonds are issued by the operating company, while the loan used to buy it sits above it
Fact. Rolf is the largest car dealer in Moscow and St Petersburg; in 2026 it opened branches in Krasnodar and Kazan. In 2023 the shares were confiscated from founder Sergey Petrov in favour of the state. In August 2024 the Federal Property Management Agency sold Rolf to Avtomobilnye Tekhnologii JSC, 99% owned by PromAgroLogistika JSC (PAL). According to IFRS, the ultimate beneficiary of the group is Umar Kremlev, president of the International Boxing Association (IBA) and a prominent public figure. PAL has no board of directors, and Rolf itself has no independent directors.
The buyer paid RUB 34.8bn in cash. PAL's charter capital is RUB 10 thousand, so the purchase was made almost entirely with debt. The floating-rate loan from a Russian bank is secured by all the property and assets of the acquired companies. According to ACRA, the loan amortises until 2029, and a single bank accounts for more than 80% of the group's bank debt.
For a bondholder this is the key feature of the whole story. The bonds are issued by ROLF JSC, whose own debt is moderate. But the holding has nothing other than Rolf to service its loan with, and Rolf is legally liable for it. The Russian accounting (RAS) statements of ROLF JSC for 2025, in the note on collateral, disclose a guarantee issued for RUB 30.09bn (RUB 34.94bn at the end of 2024; less than RUB 1mn at the end of 2023). The amount matches the group's floating-rate term loan to the rouble, i.e. the acquisition loan. So the bank can claim the outstanding balance of this loan directly from Rolf. We did not find this guarantee in Rolf's standalone IFRS, and the company's investor materials show leverage without it. Rolf's bonds should therefore be assessed on group metrics, not the issuer's.
This is a standard structure for debt-funded acquisitions. The bank wants a direct claim on the company that holds the cash and assets, so the acquired company guarantees the buyer's debt. In Western markets bondholders are usually protected by the terms of the issue: a right to sell the bonds at 101% of par on a change of control, and limits on new debt, guarantees and dividends. In a number of European countries corporate law also restricts a company from guaranteeing debt taken to buy its own shares. In Russia there is no direct prohibition, such a guarantee is approved by the sole shareholder, and retail bond issues usually carry no such restrictions.
Current holders were not misled retroactively. The deal closed on 31.08.2024, and the earliest outstanding issue, 1R03, was placed on 24.09.2024, the rest later. Our complaint is about disclosure. The RUB 30bn guarantee is visible only in an image table in the RAS statements, while the company's communication emphasises an "operating perimeter" with leverage of 1.3x.
Debt as of 30.06.2026. The issuer has RUB 19.5bn (bonds and bank lines), the holding has a RUB 25.8bn acquisition term loan, plus the owner's interest-free loan. Right: net debt to adjusted EBITDA under the loan agreements' methodology, from the IFRS of the issuer and the group. Rolf guarantees the holding's loan.
The scheme in plain terms: the holding borrowed, Rolf guaranteed and pays
Group structure and cash flows. The red dashed arrow is the guarantee, i.e. Rolf's legal obligation to pay the bank if the holding does not.
How it works, step by step:
Step 1. A debt-funded purchase. A holding company with no business of its own takes a bank loan and buys 100% of Rolf's shares from the state for RUB 34.8bn.
Step 2. The guarantee. The bank wants the loan backed by whoever has the cash. Rolf provides a guarantee: if the holding does not pay, the bank is entitled to claim the debt from Rolf. Under RAS the guarantee stood at RUB 30.1bn at the end of 2025.
Step 3. Debt service. The holding pays the bank out of Rolf's dividends (RUB 3.1bn paid in 2025 and RUB 2.5bn in 1H2026) and the owner's interest-free loans (RUB 9.0bn of face value).
Step 4. If something goes wrong. The holding stops paying, and the bank comes to Rolf as a debtor. A claim of RUB 26-30bn joins the queue of unsecured creditors next to RUB 6bn of bonds, and both will have to be paid from the same dealership business.
Rolf's net debt without and with the guarantee, as a multiple of the issuer's LTM EBITDA. The acquisition loan balance as of 30.06.2026 is an authors' estimate based on group IFRS.
Authors' estimate. In the issuer's statements net debt is RUB 15.7bn, or 1.4x annual EBITDA. Adding the outstanding acquisition loan that Rolf guarantees gives RUB 41.5bn and 3.8x EBITDA, the same as the group under the banks' methodology. So for a Rolf bondholder the right starting point is the group's numbers, not the issuer's.
Rolf services its own debt with room to spare, but that excludes the guarantee
Fact, IFRS of ROLF JSC for 1H2026. Revenue was RUB 144.3bn versus RUB 70.0bn a year earlier (part of the growth came from merging subsidiaries in August 2025). Operating profit was RUB 3.24bn versus RUB 0.76bn, finance costs RUB 2.04bn versus RUB 2.67bn. Net profit was RUB 1.01bn versus a loss of RUB 0.95bn.
The issuer's debt as of 30 June was RUB 19.5bn: RUB 13.5bn of bank lines and RUB 6.0bn of bonds. Net of RUB 3.8bn of cash, net debt is RUB 15.7bn. Adjusted 12-month EBITDA excluding the lease effect was RUB 10.9bn, a ratio of 1.43x. The issuer's equity is RUB 30.0bn, most of it from revalued dealership buildings and land.
Authors' estimate and assumption. Over the 12 months to 30 June the issuer's operating profit was about RUB 9.9bn against finance costs of about RUB 4.0bn, a coverage of about 2.5x. If Rolf stood on its own, with these numbers its credit quality would, in our view, be noticeably higher than its current ratings. But it does not stand on its own: including the guarantee of the acquisition loan (about RUB 26bn outstanding as of 30 June 2026, our estimate from group IFRS), Rolf's leverage is close to the group's, about 3.8x.
The group with the acquisition loan does not yet cover its interest, and the auditor warns of going-concern risk
Fact, IFRS of Rolf Group (PromAgroLogistika JSC). 2025: revenue RUB 244.1bn, operating profit RUB 7.17bn, finance costs RUB 11.29bn, net loss RUB 4.95bn. 1H2026: revenue RUB 144.3bn (+61%), operating profit RUB 3.16bn, finance costs RUB 4.81bn, loss RUB 1.74bn versus RUB 5.01bn a year earlier.
Group operating profit and finance costs by half-year, IFRS. In 2H2025 the group broke even; in 1H2026 it was back to a loss, but three times smaller than a year earlier.
Authors' estimate. Over the 12 months to 30 June 2026 the group's operating profit was RUB 9.25bn and finance costs RUB 9.99bn, a coverage of 0.93x. EBITDA (RUB 11.4bn) against interest paid (RUB 9.6bn) gives coverage of 1.19x. Operating cash flow after interest for the same 12 months was negative at minus RUB 1.8bn, mainly because inventories grew by RUB 6.4bn in the first half.
The group's auditor, Unicon JSC, in its review of the 1H2026 statements drew attention to a material uncertainty about the group's ability to continue as a going concern. The reasons are listed in the statements themselves: negative net assets, a loss, negative operating cash flow, and operating profit not covering finance costs. Management responds that the loss shrank by 35%, interest falls along with debt and the key rate, and creditors have provided written waivers of sanctions and early repayment. According to the company, financial covenants are met; the waivers concern non-financial terms.
The group's negative equity is a direct consequence of the debt-funded purchase. There was almost no negative goodwill on the acquisition (RUB 1.4mn), and all losses in later years fell on equity that started at zero.
Equity of the issuer and the group. Excluding intangible assets (RUB 5.5bn, mostly software and trademarks), group equity as of 30.06.2026 is minus RUB 9.0bn. Authors' estimate based on IFRS.
Rolf's cash goes up the chain, and the owner tops it up with interest-free loans
Fact. ROLF JSC paid its sole shareholder RUB 3.11bn in dividends in 2025 and RUB 2.47bn in 1H2026. In the same half-year the issuer's operating cash flow was negative (minus RUB 0.68bn), and its borrowings grew by RUB 4.4bn. The half-year dividend was 2.5 times the half-year IFRS profit.
The beneficiary, for his part, provided the group with an interest-free loan: RUB 4.7bn of face value at the end of 2025 and RUB 8.99bn as of 30 June 2026, plus RUB 0.5bn of financial aid. The loan is carried at a fair value of RUB 3.5bn, with the RUB 3.0bn difference booked as a capital contribution. The group's acquisition term loan shrank from about RUB 30bn to RUB 26bn over the half-year.
Authors' assumption. The scheme looks like this: the acquisition loan is repaid partly with Rolf's dividends and partly with the owner's money. For the bonds this is rather positive as long as the owner keeps putting money in. It is direct evidence of support, not just words. The owner is a public figure, and abandoning one of the country's largest dealers, bought from the state, would be costly for his reputation. As long as he funds the group with cash, we consider a scenario in which the owner walks away unlikely. But this is our assumption, not an obligation: legally the owner is not liable for the group's debts. But the dependence works both ways. If the owner stops topping up, the holding will have to take more from Rolf, and the operating company will start borrowing to pay dividends. This direction of cash flow is what to track in every subsequent report.
The statements show no loans from Rolf to the owner or related companies: as of 30 June 2026 the balance of loans with related parties is zero. Cash goes up through dividends, and risk comes down through the guarantee. One caveat: other related-party transactions in 1H2026 amounted to RUB 0.26bn of administrative expenses, and their nature is not disclosed.
New cars are sold at a loss; loans, insurance and service make the money
Fact, group management accounts (segment note). In 1H2026 the new car segment after direct costs produced minus RUB 4.16bn of gross margin on revenue of RUB 64.3bn. A year earlier it was minus RUB 2.42bn. Used cars moved into a small positive (RUB 0.16bn), service and parts gave RUB 4.96bn, and insurance and finance brought RUB 7.87bn versus RUB 4.39bn a year earlier.
Gross margin of the group's segments after cost of sales and direct delivery, advertising and staff costs, management accounts. Under Russian accounting standards (RAS) the gross loss on new cars is smaller, RUB 0.23bn, because direct costs are not deducted there.
The model is clear: a new car is a reason to sell a loan, an insurance policy and later servicing. According to the company, more than 70% of sales are on credit. Hence the main operating risk. Group income depends on the volume of car loans and partner banks' commissions. If lending contracts or commissions are cut, there will be nothing to close the margin gap on new cars.
Inventories as of 30 June were RUB 29.4bn, of which RUB 23.3bn in cars. They grew by RUB 6.4bn since the start of the year, which is the main reason for the negative cash flow. Part of the purchases was financed by supplier deferrals: RUB 7.1bn versus RUB 5.0bn at the start of the year.
The market is recovering after the 2025 slump, but dealer margins remain thin
Fact. Sales of new passenger cars in Russia fell 15.6% in 2025, to 1.33mn units (Autostat). In 9M2026 the market grew 8%, to 968 thousand. Rolf sold 37.5 thousand new cars in 2025 (+14%), gaining share in a falling market. In 1H2026 it sold 19.6 thousand new and 26.5 thousand used cars.
Since 1 December 2025 the recycling fee has depended on engine power, and from 1 January 2026 the rates were indexed by another 10-25%. This supports prices but weighs on demand and favours locally assembled cars. Rolf works with Asian brands under non-exclusive agreements, without dependence on a single manufacturer.
Industry dealer margins hover around 1.5-2%, and according to the Russian Automobile Dealers Association almost 60% of dealers were loss-making in 2024. The key rate has been cut to 14%. For Rolf, with RUB 38bn of floating-rate debt, each percentage point of the rate costs roughly RUB 0.4bn of interest a year (authors' estimate). Rate cuts are the strongest argument for improving metrics in 2026-2027.
The company guides the market to EBITDA of RUB 11.4bn for 2026 (Interfax, SPIEF, June 2026, management forecast). Group adjusted EBITDA for the first half was RUB 4.3bn, so the guidance requires RUB 7.1bn in the second half. In 2H2025 it was RUB 7.1bn, so the forecast requires repeating last year's result with more expensive inventory. The target is achievable, but with no headroom.
Bonds are a small part of the debt. The key question is the rollover of bank lines
Fact. Group debt as of 30 June 2026 was RUB 50.7bn, including RUB 6.0bn of bonds, RUB 13.3bn of revolving lines and RUB 31.5bn of term loans, among them the acquisition loan and the owner's interest-free loan. RUB 23.0bn of it is due within 12 months. Cash is RUB 3.9bn, undrawn bank limits RUB 13.9bn, plus RUB 7.7bn of undrawn supply-finance limits.
Left: group debt due within a year against cash and undrawn bank limits, IFRS 1H2026. Right: bond maturities by date; all issues are repaid in a single payment, with no puts or amortisation.
Authors' estimate. Revolving lines finance the car inventory and are usually rolled over as long as the cars sell. So the main risk is not the RUB 2bn of bonds due in January 2027, but whether the main bank keeps rolling over the lines and tolerating non-financial covenant breaches. So far it grants waivers and keeps RUB 13.9bn of limits undrawn. Bond payments including coupons until September 2027 will total about RUB 4.9bn (authors' estimate), roughly a third of the undrawn limits.
As of 30 June 2026, RUB 5.3bn of buildings and land and RUB 7.6bn of inventories are pledged against RUB 12.0bn of loans. Over these assets the banks rank ahead of bondholders; the bonds are unsecured. In total, under RAS at the end of 2025 Rolf had pledged RUB 13.6bn of assets, without specifying whose obligations they secure. Under the guarantee, the holding's bank is a direct creditor of Rolf and as a general rule ranks alongside bondholders.
Ratings: A- from ACRA and BBB+ from NCR; Expert RA cut by three notches in a year and walked away
ACRA: A(RU) in August 2025, downgraded to A-(RU) on 04.08.2026, outlook stable. Standalone creditworthiness is assessed at bbb+, with one more notch added for beneficiary support. Downgrade triggers per the agency: debt to FFO above 5x, FFO to interest below 1x, FFO margin below 5% (currently 5.05%, i.e. at the threshold).
NCR: BBB+.ru assigned on 31.03.2026, outlook stable, also reflecting the beneficiary's role in repaying the acquisition loan.
Expert RA: ruA at the start of 2025, downgraded to ruBBB+ on 11.02.2025 and to ruBBB with a developing outlook on 06.02.2026. On 03.09.2026 the rating was withdrawn due to the expiry of the agreement and insufficient information to apply the methodology.
We read a withdrawal without a final review as a negative but not alarming signal: the two other agencies maintain their ratings. For some funds with rating constraints it narrows the pool of buyers.
Taxes and courts: no tax arrears, the story of the former owner closed by a verdict
Fact. According to Federal Tax Service open data as of 25.09.2026, ROLF JSC has no tax arrears, penalties or fines. We could not check the arbitration court records automatically. The group's statements contain the standard transfer-pricing risk disclaimer; no specific tax claims are disclosed.
On 17.08.2026 the Cheryomushkinsky court in Moscow sentenced Sergey Petrov in absentia to 9 years for siphoning about RUB 4bn out of the company (Interfax); the defence is appealing. We found no claims against the current group related to this case.
A 21-22% yield: the price of the deal structure, not of a weak business
Rolf's five outstanding issues. Simple yield is calculated the same way for fixed and floating coupons; it is what a holder actually receives without reinvestment.
Authors' estimate. The three liquid issues 1R07, 1R08 and 1R09 trade at yields to maturity of 21.3-22.5%, with simple yields of 19.5-20.7%. The 1R03 floater (key rate plus 3%) trades below par at 97.4%: the market demands a higher spread over the rate than the coupon provides. The small 1R06 (key rate plus 6%) trades rarely.
The market has already repriced the 25.5-26% fixed coupons of 1R07 and 1R08: prices are above par, and at maturity the holder loses the premium. For BBB+/A- paper, a 7-8 percentage point spread over the key rate is the upper end of the market, but the structure here is also worse than usual: negative group equity, an auditor's emphasis of matter, dividends upstream, the issuer's guarantee of the acquisition loan.
Main risks
The owner withdraws support. Without new interest-free loans the acquisition loan will be serviced only by Rolf's dividends, and the operating company will have to borrow to pay them.
The main bank's stance. One bank holds more than 80% of the group's bank debt, and Rolf guarantees its acquisition loan. If the bank refuses to roll over lines or demands early repayment for non-financial covenant breaches, a claim of RUB 26-30bn will land on Rolf directly.
Car lending. Profit comes from loan and insurance commissions. Tighter borrower terms or lower agency commissions hit the single large source of margin directly.
Inventories. RUB 23bn in cars with a negative margin on new vehicles. A new drop in demand means write-downs and further discounts.
Interest rate. RUB 38bn of floating-rate debt. If the easing cycle stops, the expected improvement in coverage will not happen.
Disclosure. The 1H2026 IFRS statements are published on e-disclosure, but as of 16.10.2026 they are not on the investor page of the company's website. In its communication the company emphasises an "operating perimeter" without the acquisition loan (net profit RUB 2.87bn and leverage of 1.3x for 2025), although the whole group will have to pay its debts. The RUB 30bn guarantee is visible only in the RAS statements.
What to take from this story into your own practice
Look at who sits above the issuer. The operating company's financials can be clean while the debt used to buy it sits one level up. In such deals (LBOs) the whole group's statements matter more than the issuer's.
Look for guarantees in the RAS statements. An operating company can be liable for the holding's loan even if its IFRS says nothing about it. Russian accounting statements contain a mandatory note on collateral for obligations. For Rolf it shows a RUB 30bn guarantee that appears neither in the issuer's IFRS nor in its investor materials.
Dividends with negative cash flow are a signal. When a company pays out more than its profit while increasing debt, creditors' money effectively goes to the shareholder.
Owner support shows up in the cash flow statement. Interest-free loans and capital contributions are a verifiable fact. Promises of support without cash flows are worth nothing.
Read the auditor's "Emphasis of matter" section. A going-concern note does not mean default, but it does mean the company lives on its creditors' consent.
A rating withdrawal after a series of downgrades is a reason to double-check. It does not mean the new rating would have been lower, but the market will never know it.
Compare yields the simple way. Coupon plus the difference between price and par per year to maturity shows what you actually keep. A bond with a 26% coupon priced at 103% yields about 21%, not 26%.
Bottom line: a profitable dealer with a heavy structure above it; short issues look more sensible than long ones
As a business, Rolf is a market leader that grew in a falling market in 2025, turned profitable at the issuer level and is reducing its interest burden along with the rate. The problem is the debt-funded purchase of the company. The loss, the group's negative equity and the auditor's emphasis of matter are consequences of this structure, not of failing sales. It rests on two supports: the bank rolls over lines and grants waivers, and the owner tops up with interest-free money. As long as both work, RUB 6bn of bonds against RUB 50bn of group debt are serviced without strain.
We would not put these bonds in the conservative part of a portfolio. The short 1R07 and 1R08 to May 2027, with a simple yield of about 20.7%, are an acceptable risk in the part of a portfolio set aside for high-yield paper. 1R09 to May 2028 at 19.5-21.3% carries the risk of refinancing the acquisition loan, and here the premium looks fair rather than generous.
What to watch next: the 2026 annual results (delivery on the RUB 11.4bn EBITDA guidance, inventory dynamics); the size of Rolf's upstream dividends; continued owner loans; continued bank waivers; ACRA and NCR rating actions; the key rate decision on 23 October; the repayment of RUB 2bn of 1R06 and 1R07 on 21 January 2027.
Sources and caveats
IFRS consolidated financial statements of PromAgroLogistika JSC (Rolf Group) for 2025 with the audit report of Unicon JSC, and condensed interim statements for 1H2026 with the review report dated 28.08.2026 – issuer disclosure.
IFRS financial statements of ROLF JSC for 2025 and 1H2026 – issuer disclosure.
RAS financial statements of ROLF JSC for 2025, note 8 "Collateral for obligations" – issuer disclosure.
ACRA press release of 04.08.2026; NCR press release of 31.03.2026; Expert RA releases of 11.02.2025, 06.02.2026 and 03.09.2026.
Prices, yields and terms of the issues as of 16.10.2026 – MOEX ISS. EBITDA guidance and share of sales on credit – Interfax, 16.06.2026; RAS results for 1H2026 – Interfax, 03.08.2026; Petrov's sentence – Interfax, 17.08.2026.
New car market – Autostat; recycling fee – Autonews; dealer margins – Russian Automobile Dealers Association via Autonews; tax arrears – Federal Tax Service open data as of 25.09.2026.
P/E and EV/EBITDA use LTM from up to four quarter rows when they look comparable (incl. Q2/Q4); if the feed is only Q1 and Q3, we use latest FY profit/EBITDA instead of summing them. P/B is market cap ÷ latest FY equity. Hover multiples for the exact formula. Financial rows: year(period_end) ≥ max(2023, current calendar year − 2) (hide older).