EconomLeasing: a small Saratov leasing company with 21% ROE and overdue payments up from 0.4% to 2% – 22-26% yields on RUB 0.6bn of bonds that are repaid from portfolio collections
EconomLeasing is a universal leasing company from Saratov with offices in the Volga region, Voronezh and Moscow, ranked 58th by Expert RA with net lease investment of RUB 2.0bn as of 1 January 2026. Its ruBBB- rating was affirmed on 08.07.2026, and it has 6 issues outstanding totalling RUB 593mn with yields of 21-26% and a spread to OFZ of 750-1,090 bp. Verdict: the nearest redemptions of RUB 100mn each in November 2026 and February 2027 are covered by portfolio collections and undrawn credit lines; the credit is small and profitable, but the trend in asset quality has turned: overdue payments above 90 days rose from 0.4% to 2.0% over the year, and the agency worsened its assessment of assets. This is a paper for those ready to hold a BBB- rated high-yield bond and to follow the reporting every quarter.
The issuer card on the portal with financials by period, our credit analysis and all issues: EconomLeasing. Below are Enhanced Investments' calculations based on the issuer's IFRS and RAS statements, the MOEX payment schedule and disclosures; where a figure is the authors' estimate, it is marked as such.
What we are buying: a RUB 2bn portfolio, 90% small-business clients, 51% of funding from banks
Fact (Expert RA, 08.07.2026). 90% of the portfolio consists of freight transport, real estate, construction equipment and passenger cars, and clients are mostly small and medium-sized businesses. Net lease investment was RUB 2.0bn at 01.01.2026 (up 5% over the year) and RUB 1.96bn at 1 April. The top three industries account for 37% of the portfolio, so diversification is high. Funding: bank loans are 51% of liabilities, bonds 21%, and undrawn limits equal 32% of liabilities. The equity ratio rose from 17% to 19%, ROE for the 12 months to April 2026 was 21.4%, ROA 3.8%, and 1Q2026 profit was RUB 23mn (up 46%).
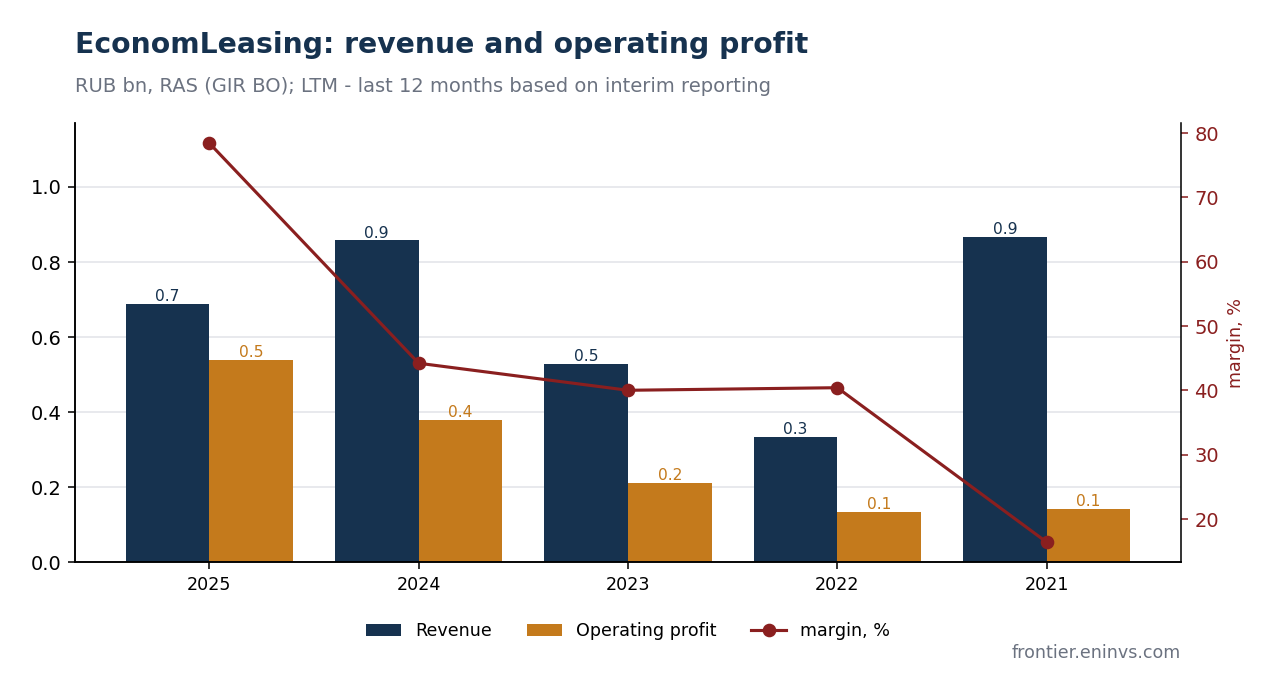
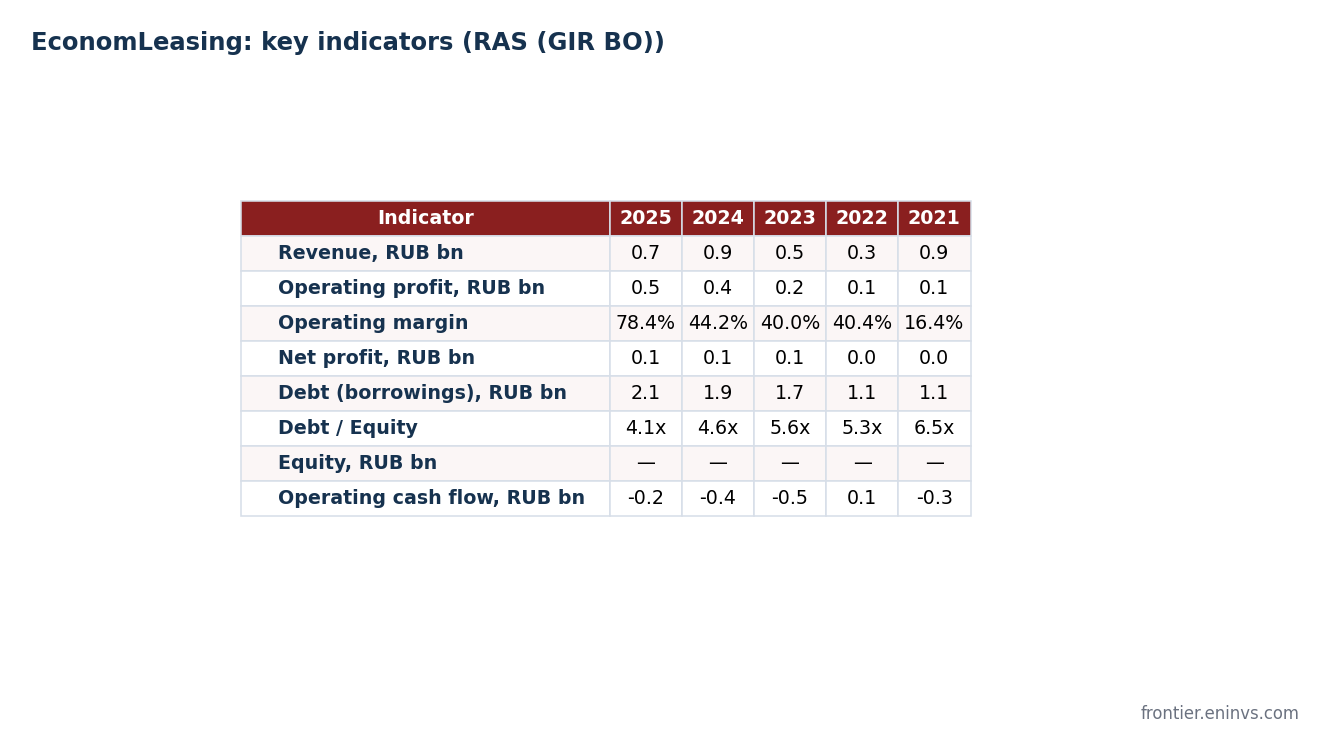
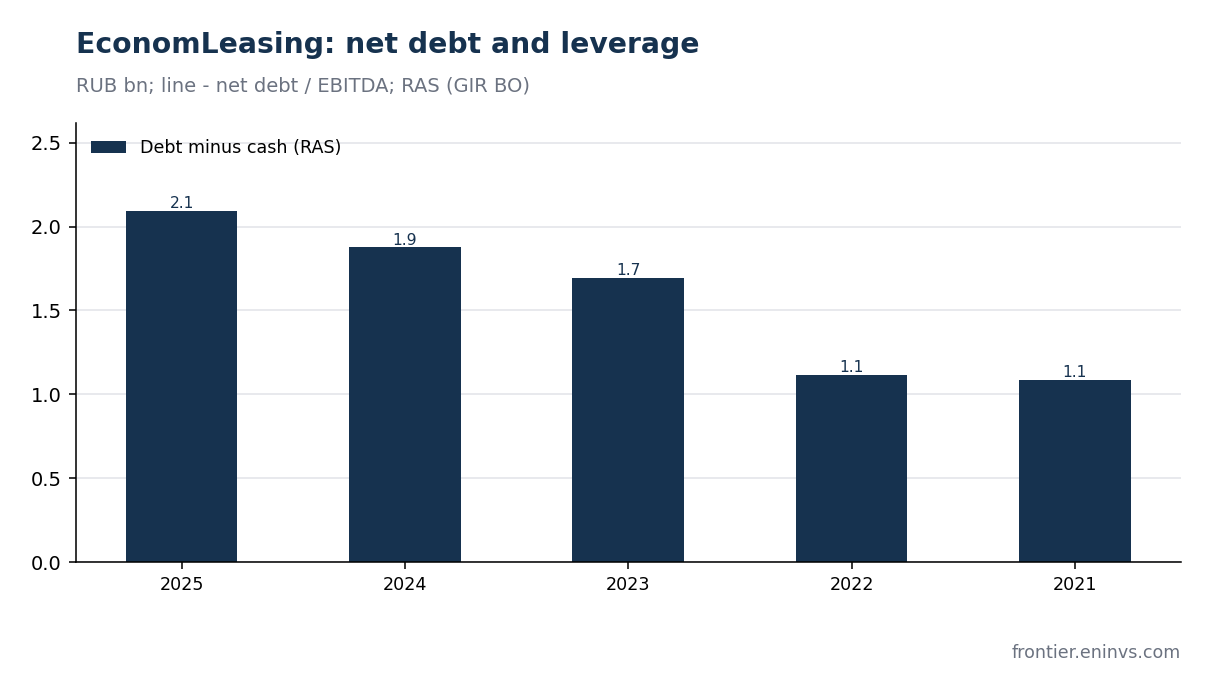
Fact (RAS, GIR BO). Revenue in 2025 was RUB 687mn, profit from sales RUB 539mn, net profit RUB 95mn (RUB 109mn in 2024), borrowings RUB 2.09bn, equity RUB 0.51bn, debt to equity 4.1x. Operating cash flow is negative (minus RUB 162mn), which is normal for a growing leasing business: new business is financed with debt, while portfolio collections appear in the investing part of the cash flow statement.
Portfolio quality: overdue payments above 90 days rose fivefold, and this is the only thing that worsened
Fact (Expert RA). The share of contracts overdue by more than 90 days rose from 0.4% to 2.0% over the year, and the asset quality assessment was lowered from adequate to moderate. Current liquidity is 115%, and projected liquidity fell from 159% to 139% because of bond repayments in 2026 and 1Q2027. Market position is limited, capital is acceptable, liquidity and funding are adequate, and corporate governance is conservative.
Authors' estimate. 2% overdue on a RUB 2bn portfolio is RUB 40mn of problem contracts against RUB 95mn of annual profit and RUB 0.5bn of equity: there is a cushion, but a fivefold rise in a year is exactly the signal that Kulikov named on air as the main one for leasing: portfolio quality and the volume of repossessed equipment. Under his fourth rule for leasing companies, more than half of the portfolio should be cars and freight transport; EconomLeasing meets this only partly: it has trucks and cars, but alongside them construction equipment and real estate, which sell worse in a downturn.
How it can pay: RUB 286mn over 12 months against RUB 222mn of cash and undrawn lines – it works if portfolio collections do not stop
Fact. Per the MOEX schedule, from September 2026 to August 2027 the company pays about RUB 86mn of coupons and RUB 193mn of redemptions: RUB 100mn on 1P6 on 19.11.2026 and RUB 93mn on 1P7 on 15.02.2027, plus the RUB 100mn put offer on 2P1 on 25.02.2027 as an upper bound. After that come RUB 100mn on 1P8 in February 2028, the 2P3 put offer in August 2028 and 2P2 in March 2029. Cash on accounts at the end of 2025 was RUB 222mn, and coverage of annual payments in our screening is 0.78x without counting credit lines.
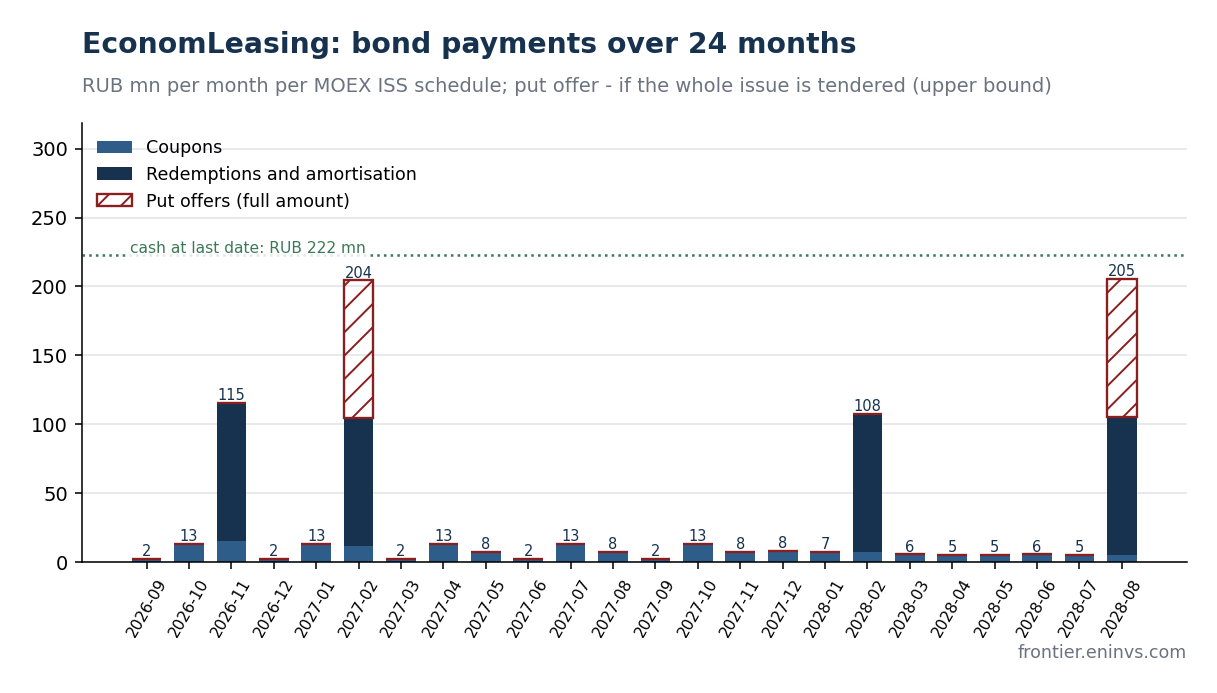
Authors' estimate. A leasing company repays debt from portfolio collections: with net lease investment of RUB 2bn and an average contract term of 2-3 years, annual portfolio receipts are RUB 0.7-1bn, and banks' undrawn limits add about RUB 0.8bn (32% of liabilities). Redemptions of RUB 100mn are not a problem against this background while banks keep the lines open; the risk lies in the cost of refinancing, not in a liquidity gap. Caveat: the exact cash balance and undrawn lines are not visible in public reporting, and we rely on the agency's data.
Market: 21-26% and a 750-1,090 bp spread – the market prices the paper as BB, not BBB-
Fact. 1P6 (16%, November 2026) – 99.3 and 20.8%; 1P7 (16%, February 2027) – 98.1 and 21.9%; 1P8 (27%, February 2028) – 104.2 and 25.1%; 2P1 (22%, put offer February 2027) – 100.1 and 21.2%; 2P2 (23%, March 2029) – 102.5 and 23.3%; 2P3 (21%, put offer August 2028) – 98.5 and 23.3%. All issues are RUB 100mn, and liquidity is low.
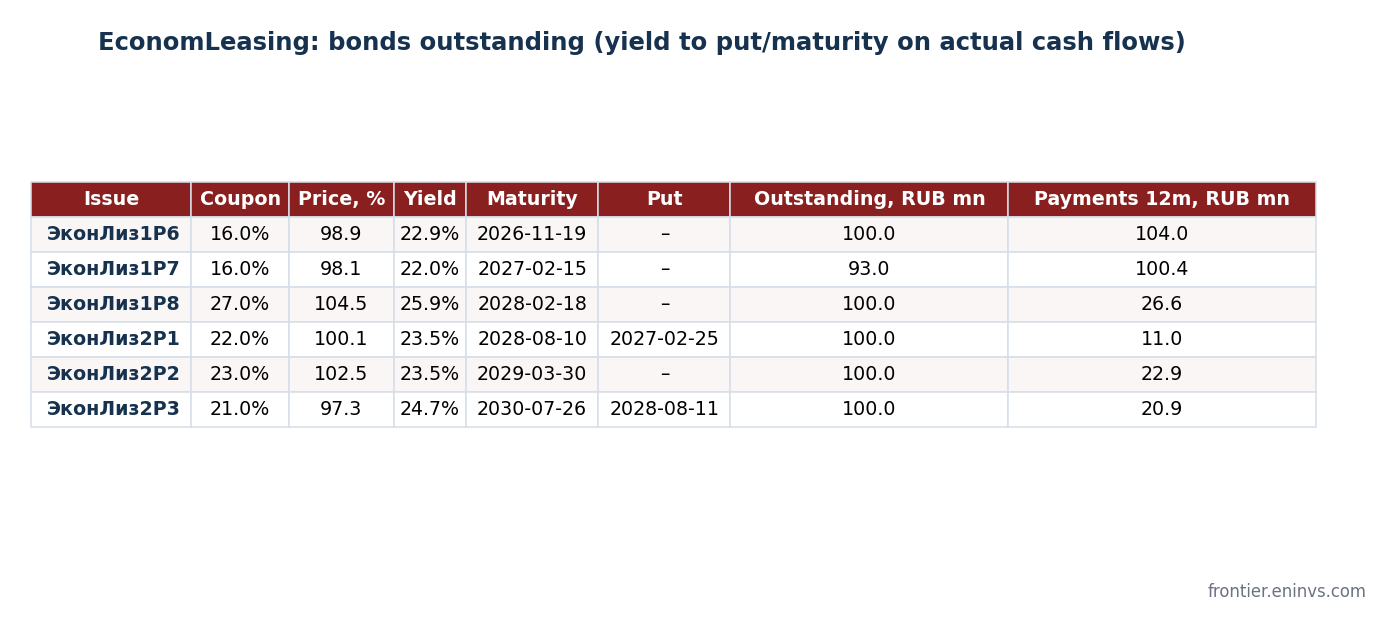
Authors' estimate. For leasing it is better to compare yield by a simple metric – coupon plus discount to redemption, the same for all issues: for the short 1P6 and 1P7 this is a 16% coupon plus a 1-2% discount over half a year, that is 18-20% "in hand", while the effective yield of 21-22% comes from reinvesting at short maturities. The highest-coupon issue, 1P8 (27%), trades above par.
Risks: size, small business as the borrower and the leasing cycle
- Scale. With a RUB 2bn portfolio and RUB 0.5bn of equity, one large lessee default would be visible in the accounts; the company ranks 58th.
- SME clients. 90% of the portfolio is small and medium-sized business, the segment most sensitive to the 14% rate and to a downturn in construction and haulage.
- Industry. The leasing market in 2025-2026 is in a crisis of stock and repossessed equipment (see our review of Baltic Leasing); EconomLeasing still shows profit growth, but overdue payments are already rising.
- Liquidity of the bonds. The issues are RUB 100mn each – exiting a position under stress will be expensive.
Conclusion: an acceptable high-yield credit for a small allocation, check overdue payments every quarter
EconomLeasing is a rare high-yield case where the numbers do not contradict each other: a profitable portfolio, growing equity, redemptions covered by collections and lines, and a rating affirmed a month ago. The price is size and overdue payments that have risen fivefold. For a high-yield portfolio this is a position within the limit for a BB-BBB- issuer, preferring the short 1P6 and 1P7 to February 2027, where risk is limited by the calendar. The next checkpoints are 9M RAS statements and the share of overdue payments in next summer's Expert RA report.
Sources and caveats
- Expert RA, press release of 08.07.2026 on the affirmation of ruBBB- (portfolio, overdue payments, funding, liquidity).
- RAS statements of OOO EconomLeasing for 2021-2025 from GIR BO of the Federal Tax Service; 2026 interim statements have been downloaded from e-disclosure and are being analysed.
- Coupon, redemption and put schedule – MOEX ISS; quotes – MOEX close on 03.09.2026.
- BCS broadcast with Anton Kulikov of 01.09.2026 – selection criteria for leasing companies are given with the source.
Reviews of other issuers and weekly analytics are in the Telegram channel Enhanced Investments @eninv, and extended cards of all issuers are on the portal.
See also: market overview · valuation map · stock screeners