Etalon: RUB 26bn of 2027 redemptions against a RUB 22bn loss and 0.5x interest cover – the 2027 bonds are priced above what the accounts support
Bonds of the developer Etalon are issued by Etalon-Finans JSC: 6 issues totalling RUB 32.5bn, rated ruBBB+ by Expert RA (downgraded from ruA- on 17.04.2026) and A-.ru by NKR. The fixed-coupon issues yield 22-25%, a spread of 830-1,080 bp over OFZ, and the floater 002P-02 trades at 90% of par. Verdict: the nearest redemption of RUB 1.2bn on 15 September will be paid; the problem is 2027: it brings RUB 6.75bn in April, RUB 8bn in September and RUB 10bn in November, about RUB 26bn in total, while the group is loss-making for a third year (minus RUB 22.3bn in 2025), operating profit covers interest 0.5x, and the issuer holds RUB 3.6bn in cash. This is a bet on refinancing and on support from AFK Sistema, and a price of 98-103% of par already includes that bet.
The issuer card on the portal with financials by period, our credit analysis and all issues: Etalon-Finans. Below are the calculations of Enhanced Investments based on the issuer's IFRS and RAS statements, the MOEX payment schedule and disclosures; where a figure is the authors' estimate, it is marked as such.
What we are buying: the debt of a developer with RUB 154bn of revenue that has lost money on interest for three years running
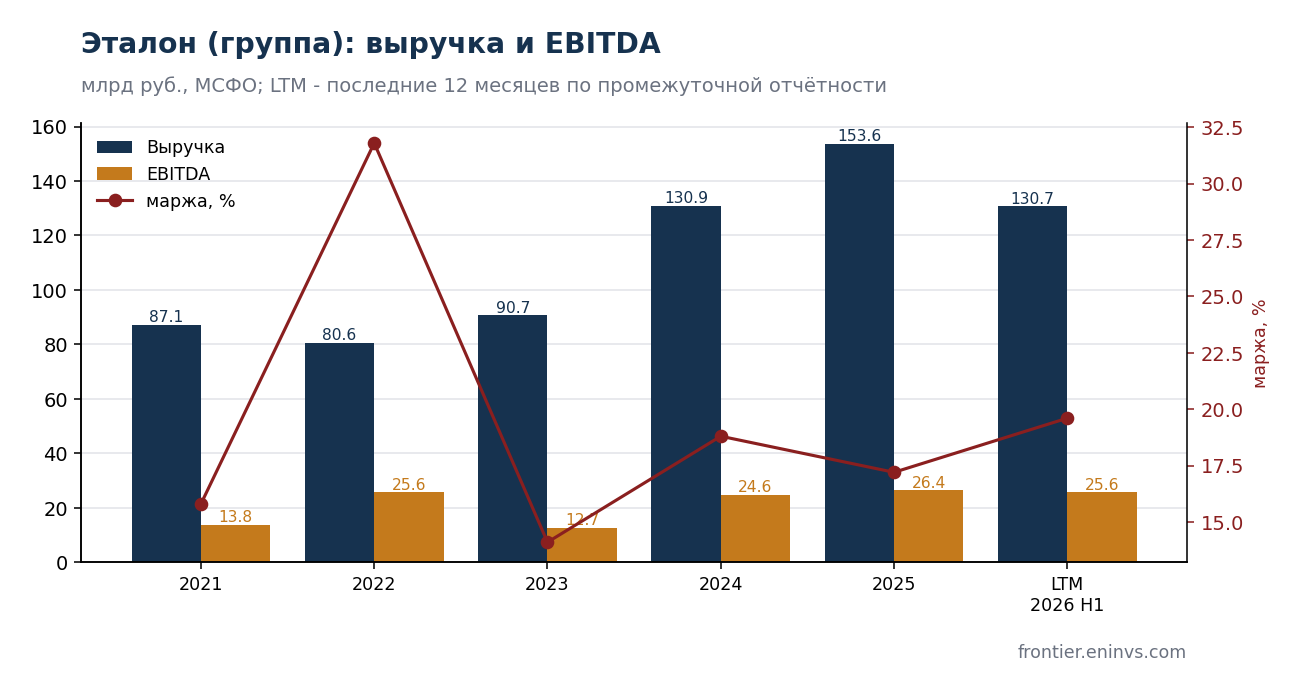
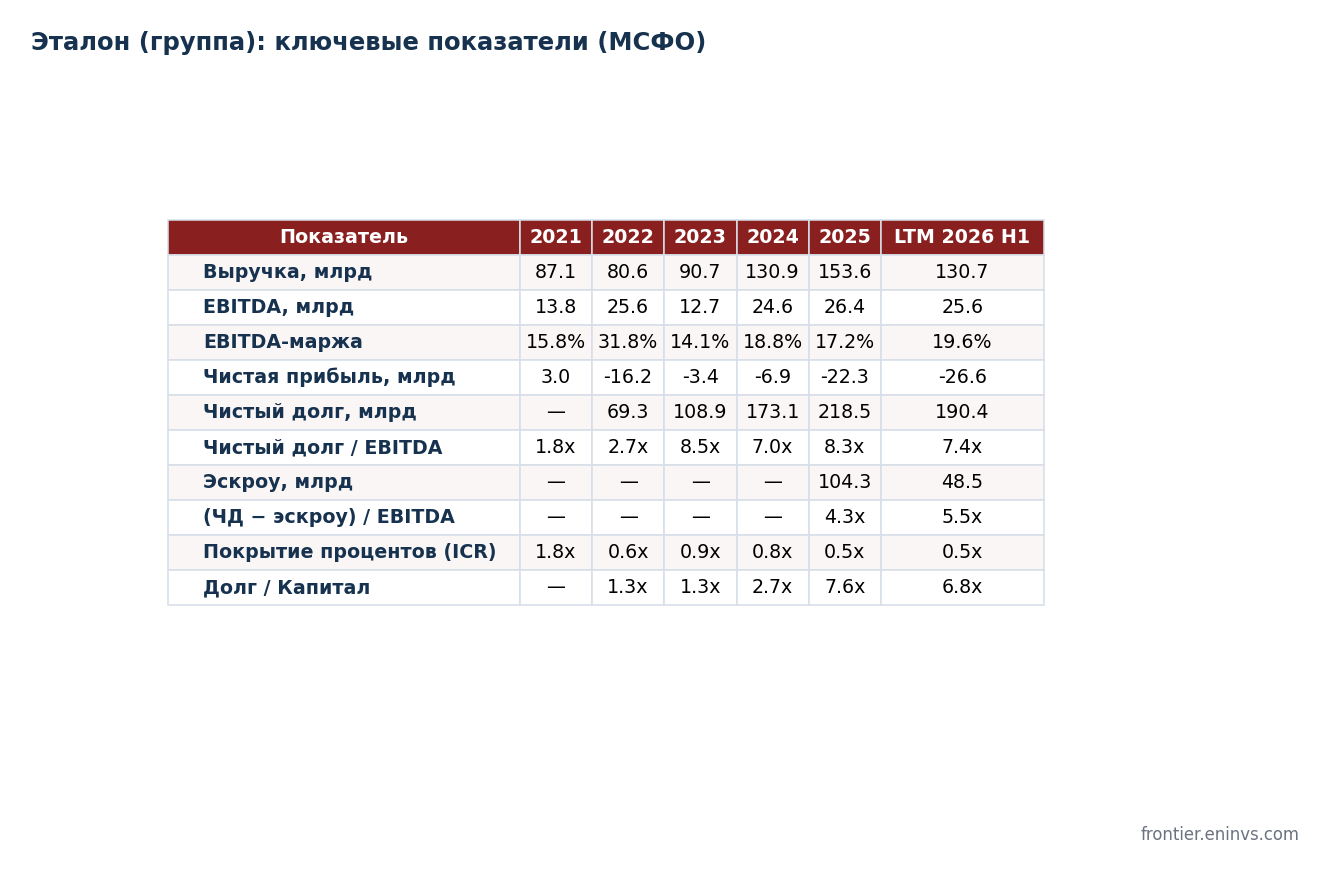
Fact (Etalon Group MKPAO, IFRS). 2025 revenue was RUB 153.6bn (+17%), operating profit RUB 25.4bn, EBITDA RUB 26.4bn at a 17% margin. But finance costs were RUB 51.4bn, and the net loss was RUB 22.3bn after a RUB 6.9bn loss in 2024. 1H2026: revenue RUB 54.4bn (minus 10%), operating profit RUB 7.4bn, finance costs RUB 25.2bn, loss RUB 13.2bn. The group's equity shrank from RUB 70.9bn at the end of 2023 to RUB 28.9bn at 30.06.2026.
Fact (Etalon-Finans JSC, IFRS). The sub-holding that carries the bonds consolidates most of the construction projects: 2025 revenue RUB 103.8bn, EBITDA RUB 16.9bn, loss RUB 21.5bn, net debt RUB 201bn. LTM at 30.06.2026: EBITDA RUB 21.4bn, net debt RUB 196bn, 9.2x EBITDA, interest cover 0.5x.
Management view (Anton Kulikov, BCS, broadcast of 01.09.2026). All of Etalon's debt was tied up in instalment plans for buyers, some of the instalments (10-20%) fell through, and the company changed its methodology: it does not recognise revenue on contracts with a large outstanding payment balance. Instalments are being converted indirectly – market mortgage issuance is at a peak, and these are not new purchases at 19% but the formalisation of apartments bought earlier.
Debt: RUB 218bn gross, RUB 114bn net of escrow at the end of 2025, and escrow is melting faster than debt
Fact. The group's net debt at the end of 2025 was RUB 218.5bn (8.3x EBITDA); buyers' balances in escrow were RUB 104.3bn, so net of escrow debt was RUB 114.2bn, or 4.3x. At 30.06.2026 net debt fell to RUB 190.4bn, but escrow balances dropped to RUB 48.5bn: net of escrow, leverage rose to 5.5x on an LTM basis. Escrow release repays project loans, while corporate debt (RUB 32.5bn of bonds, bank loans) remains.
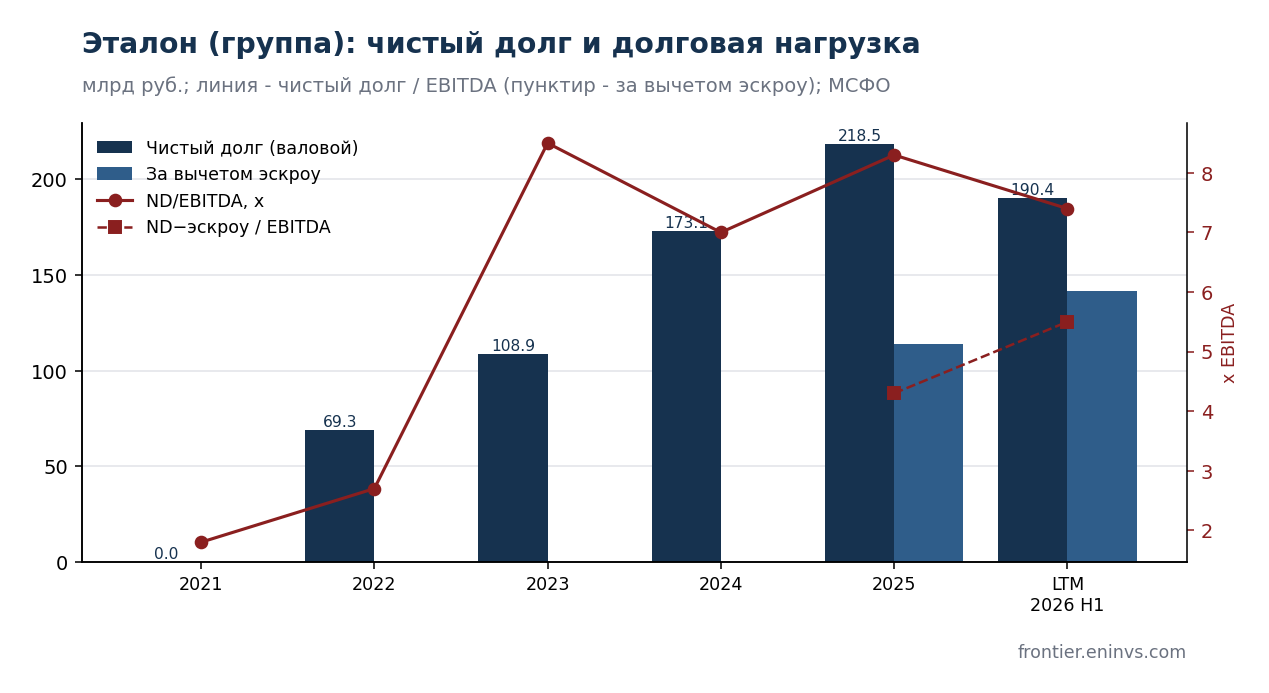
Authors' estimate. Even on the lenient measure (net of escrow), leverage of 5.5x with interest cover of 0.5x is a level at which debt is serviced with new debt. Interest of RUB 51bn a year against operating profit of RUB 25bn: the company lives on sales growth and refinancing, and a lower CBR key rate matters more to it than any operating improvement.
How it gets paid: RUB 14bn over the next 12 months against RUB 3.6bn of cash, and RUB 26bn of redemptions in 2027
Fact. According to the MOEX schedule, from September 2026 to August 2027 Etalon-Finans must pay about RUB 6.2bn of coupons and RUB 7.95bn of redemptions: RUB 1.2bn on BO-P03 on 15.09.2026 and RUB 6.75bn on 002P-03 on 01.04.2027. After that come RUB 8bn on the floater 002P-02 on 30.09.2027, RUB 10bn on 002P-04 on 11.11.2027 and a put offer of RUB 10bn on 002P-01 on 19.05.2028. The issuer's cash at the end of 2025 under RAS is RUB 3.6bn, and the sub-holding's operating cash flow is negative. The RUB 141.5mn coupon on 002P-03 was paid on time on 3 September.
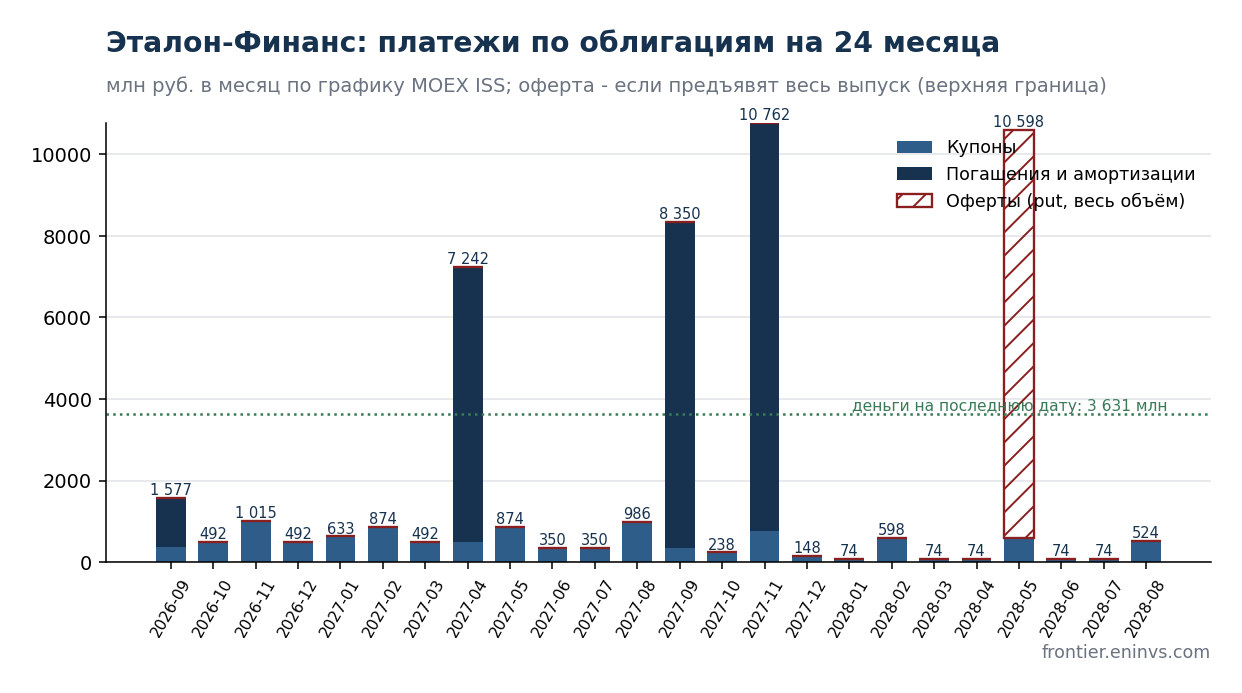
Authors' estimate. 2027 requires about RUB 26bn on bonds alone, more than the annual EBITDA of the whole group. The sources are escrow release on completed projects, new placements and AFK Sistema, which itself carries RUB 1.4trn of net debt at 4.6x EBITDA and has already been downgraded because of Ozon and Segezha. None of these sources is guaranteed, which is exactly why Expert RA took a letter A away from the issuer in April.
Fact. On 2 September the board of directors of Etalon-Finans amended the 002P bond programme and the prospectus. Authors' assumption: this is preparation for new placements against the redemptions of 15 September and April 2027 – refinancing, not cash flow, as built into our scenario.
Market: 22-25% on the fixed-coupon issues is the premium for 2027, and the floater at 90 says it more loudly
Fact. 002P-03 (25.5%, April 2027) trades at 102.8 with a 22.5% yield, 002P-04 (20%, November 2027) at 97.9 and 24.8%, 002P-05 (20%, March 2029) at 98.2 and 23.3%, 002P-01 (21%, put offer May 2028) at 97.9 and 24.3%. The RUB 8bn floater 002P-02 stands at 90% of par with a MOEX yield of 30.7% – the market prices September 2027 worst of all. The short BO-P03 is redeemed in 11 days.
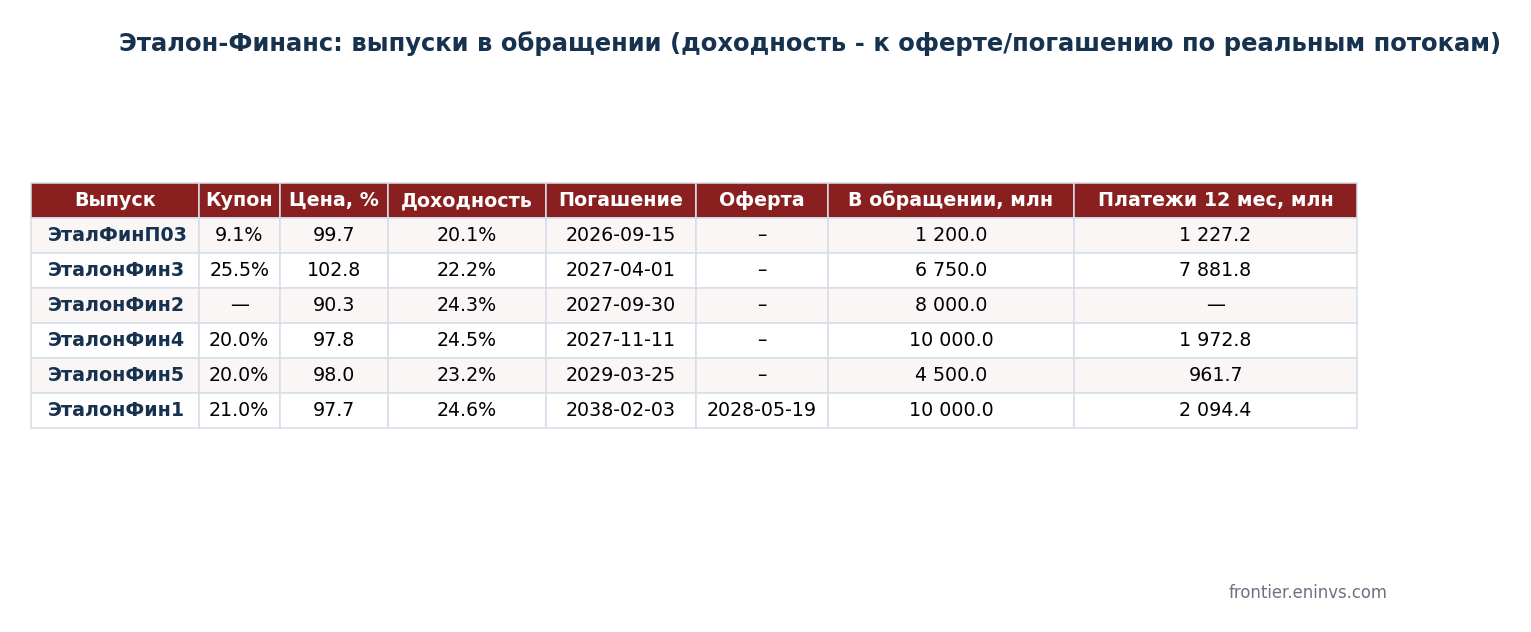
Authors' estimate. A spread of 830-1,080 bp on the fixed-coupon issues sits between the BBB and BB baskets in our sample, even though the formal ratings are BBB+/A-. Holders of the long issues count on two events: a lower CBR key rate, which would cut the RUB 51bn of interest, and support from Sistema. The RUB 8bn floater at 90 is the most honest price of 2027 risk in the lineup.
Risks: 35 unresolved disclosure violations, a rating downgrade and a parent company under pressure
- 2027 liquidity. RUB 26bn of redemptions with negative sub-holding cash flow; refinancing at the current 23-25% only worsens coverage.
- Rating. Expert RA downgraded to ruBBB+ in April 2026; NKR still holds A-.ru. A further downgrade would push the bonds out of some funds' limits.
- Formal signals. According to the Moscow Exchange index, Etalon-Finans has 39 disclosure violations, 35 of them unresolved – a record among the issuers we have reviewed. A side signal: not a leading one, but characteristic.
- Shareholder. AFK Sistema at 4.6x leverage and a rating downgraded over Ozon and Segezha – support is possible, but it is not free.
- Demand. 1H revenue is down 10%, market mortgages cost 20%; the seasonally stronger 2H is typical for developers, but it will not offset a RUB 13bn loss for the half year.
Conclusion: short issues up to April 2027 carry acceptable risk, long ones only as a bet on the key rate and Sistema
BO-P03 in September and 002P-03 in April 2027 are covered from current liquidity and escrow release, and here 22% looks like payment for an understandable risk. After that comes 2027 with RUB 18bn in September-November, for which the issuer has neither cash flow nor cash – only refinancing. We would not hold more than the standard limit per BBB issuer and would not buy 002P-02 and 002P-04 without readiness to sit through a restructuring. Kulikov places Etalon among the developers with large losses alongside Samolet and LSR, and this matches our figures.
Sources and caveats
- Consolidated IFRS statements of Etalon Group MKPAO and Etalon-Finans JSC for 2021-2025 and 1H2026 (e-disclosure); escrow – note 16 to the group's statements.
- Expert RA press releases (17.04.2026, ruBBB+) and NKR (31.03.2026, A-.ru); issuer notices on the coupon payment and board decisions of 03.09.2026.
- Schedule of coupons, redemptions and put offers – MOEX ISS; quotes – MOEX close on 03.09.2026; Moscow Exchange disclosure violations index.
- BCS broadcast with Anton Kulikov of 01.09.2026 – the speaker's position is given with attribution.
Other issuer reviews and weekly analytics are in the Telegram channel Enhanced Investments @eninv; extended cards of all issuers are on the portal.
See also: market overview · valuation map · stock screeners