Raspadskaya: H1 2026 loss halved to RUB 8.3 bn, but operating cash flow nearly dried up
On 14 August Raspadskaya released its unaudited H1 2026 financials. Revenue fell 4.4% year on year to RUB 56.7 bn, EBITDA came in at RUB 1.4 bn with a 2.4% margin versus a negative 17.6% a year earlier, and the net loss narrowed to RUB 8.3 bn from RUB 16.6 bn. The improvement in profit came mainly from an impairment reversal and a downward revision of the reclamation provision rather than from operations: operating cash flow dropped to RUB 1.9 bn, capital expenditure was RUB 7.8 bn, and at the current price the share looks unattractive.
Key takeaways
— Revenue fell 4.4% year on year to RUB 56.7 bn, and almost all of it still comes from coking coal
— EBITDA of RUB 1.4 bn at a 2.4% margin marks a reversal from minus 17.6% a year earlier, but the absolute level remains low
— The net loss narrowed to RUB 8.3 bn from RUB 16.6 bn, with most of the improvement coming from one-off items
— Operating cash flow of RUB 1.9 bn does not cover capital expenditure of RUB 7.8 bn
— Net debt remains negative: from RUB 5.0 bn on 30 June 2025 to minus RUB 2.8 bn on 30 June 2026
— No dividends were paid over the last 12 months, and with a loss no payout is expected
— On the portal's model the share is valued 90% below the current price, reflecting weak cash generation
Attractiveness
Key figures, RUB bn
| Metric | H1 2025 | H1 2026 | Change |
|---|---|---|---|
| Revenue | 59.3 | 56.7 | -4.4% |
| EBITDA | -10.4 | 1.36 | to profit |
| Operating profit | -21.5 | -9.29 | — |
| Net profit | -16.6 | -8.30 | — |
| Operating cash flow | 9.59 | 1.86 | -80.6% |
| Capex | — | 7.79 | — |
| EBITDA margin | -17.6% | 2.4% | +20.0 pp |
| Net margin | -27.9% | -14.6% | +13.3 pp |
Revenue fell 4.4% year on year to RUB 56.7 bn, and almost all of it still comes from coking coal
Revenue for the first half of 2026 was RUB 56.7 bn, down 4.4% from the same period last year. Product sales brought in RUB 56.7 bn, services – RUB 1.2 bn. The decline is primarily market-driven: 97% of the group's revenue comes from coking coal, and falling prices in that market directly hit revenue.
Related-party transactions accounted for 18% of revenue, unchanged from a year earlier. Sales to related parties in H1 2026 were RUB 10.3 bn, of which RUB 10.2 bn went to the immediate and ultimate parent companies. This means a significant portion of sales occurs within the group, limiting transparency on pricing terms.
Cost of goods sold fell to RUB 43.0 bn from RUB 48.5 bn a year earlier, which drove gross profit up to RUB 14.9 bn from RUB 12.0 bn. However, commercial expenses remain high at RUB 19.2 bn, though below last year's RUB 23.9 bn. Together this produced gross profit but did not prevent an operating loss.
EBITDA of RUB 1.4 bn at a 2.4% margin marks a reversal from minus 17.6% a year earlier, but the absolute level remains low
EBITDA for H1 2026 was RUB 1.4 bn, with a margin of 2.4%. A year earlier EBITDA was negative and the margin was minus 17.6%. The swing into positive territory occurred, but the absolute EBITDA figure remains small relative to revenue and assets.
The operating loss was RUB 9.3 bn versus RUB 21.5 bn a year earlier. The improvement in operating results is largely due to the reversal of impairment of non-financial assets: in the reporting period the group reversed previously recognised impairment of RUB 1,461 mn following a revision of the mine closure and reclamation provision, and recognised impairment of functionally obsolete assets of RUB 17 mn. Without this reversal the loss would have been larger.
Commercial expenses fell to RUB 19.2 bn from RUB 23.9 bn, and general and administrative expenses to RUB 4.1 bn from RUB 4.7 bn. This helped improve the operating result, but the main driver of the EBITDA swing was one-off items rather than cost savings. The sustainability of the margin improvement is questionable.
The net loss narrowed to RUB 8.3 bn from RUB 16.6 bn, with most of the improvement coming from one-off items
The net loss for H1 2026 was RUB 8.3 bn versus RUB 16.6 bn a year earlier. Loss per share narrowed to RUB 12.46 from RUB 24.89. The net margin improved to minus 14.6% from minus 27.9%, but remains negative.
One-off factors made a key contribution to the loss reduction. The group revised its land reclamation provision downward by RUB 2,560 mn following new information on previously closed facilities and updated closure projects for two mines. In addition, impairment of RUB 1,461 mn was reversed. These two items together provided about RUB 4.0 bn of improvement, a significant portion of the loss reduction.
Tax savings also supported the result: the group recorded an income tax benefit of RUB 1,654 mn versus RUB 4,395 mn a year earlier. Without the one-off items the loss would have been substantially closer to last year's level. The sustainability of the current profit improvement is low.
Operating cash flow of RUB 1.9 bn does not cover capital expenditure of RUB 7.8 bn
Operating cash flow for H1 2026 was RUB 1.9 bn versus RUB 9.6 bn a year earlier. This sharp decline reflects weak cash generation from core operations. At the same time, capital expenditure remains high at RUB 7.8 bn, though below last year's RUB 9.8 bn.
The gap between operating cash flow and capital expenditure is RUB 5.9 bn. This gap was financed from accumulated cash: the cash and equivalents balance fell to RUB 5.5 bn from RUB 10.9 bn at the start of the year. Investing activities overall required RUB 6.2 bn of net outflow.
Free cash flow remains negative. If current coal prices and capital expenditure levels persist, the company will continue to draw down its cash reserves. This limits dividend capacity and increases risks to financial stability.
Net debt remains negative: from RUB 5.0 bn on 30 June 2025 to minus RUB 2.8 bn on 30 June 2026
Net debt as of 30 June 2026 was minus RUB 2.8 bn, meaning cash exceeds debt obligations. A year earlier, on 30 June 2025, net debt was positive at RUB 5.0 bn. The reduction in net debt over 12 months was RUB 7.8 bn. Since the start of the year, net debt changed from minus RUB 2.1 bn on 31 December 2025 to minus RUB 2.8 bn on 30 June 2026.
Negative net debt is a safety cushion, but it was formed mainly from previously accumulated cash, which is now being spent. Interest expenses for H1 2026 were RUB 1.3 bn, interest income – RUB 0.6 bn. Net interest expenses weigh on profit.
Debt burden itself is not a problem: debt is small and cash exceeds liabilities. However, if negative free cash flow persists, this cushion will shrink. The key question is how long the company can finance capital expenditure from reserves.
No dividends were paid over the last 12 months, and with a loss no payout is expected
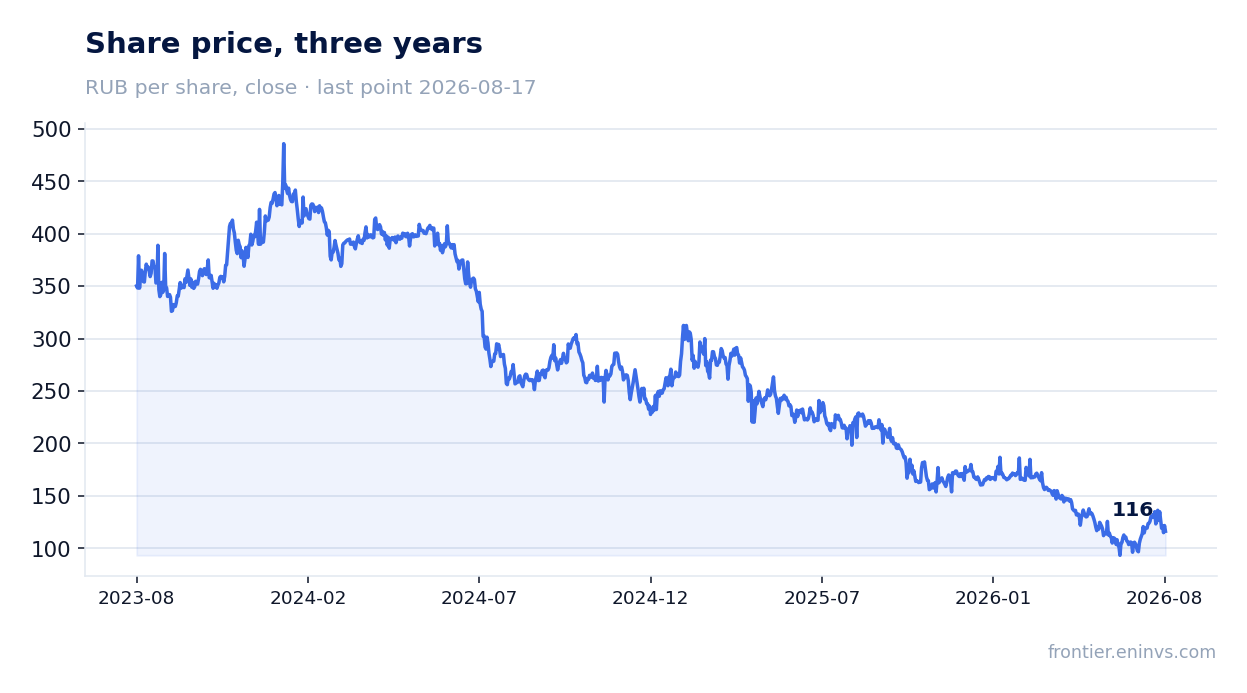
No dividends were paid over the last 12 months. No payments were made in the current calendar year either. The company's dividend history is intermittent: RUB 28.7 per share was paid in 2021, RUB 28.0 in 2022, but payments stopped in subsequent years. The current loss and negative free cash flow make a resumption of payouts unlikely in the near term.
The fair dividend yield for this name, in our estimate, is 12.0%. At the current share price of RUB 121.2, this would correspond to a dividend of about RUB 14.5 per share. However, with a loss and a payout ratio of 0.25 of profit, a dividend is only possible upon a return to profitability. The central bank key rate of 14.0% makes dividend expectations even more cautious.
The main risk to dividends is continued losses and negative free cash flow. Even if coal prices recover, the company will need time to accumulate profit for payouts. Dividends are unlikely in the next 12 months.
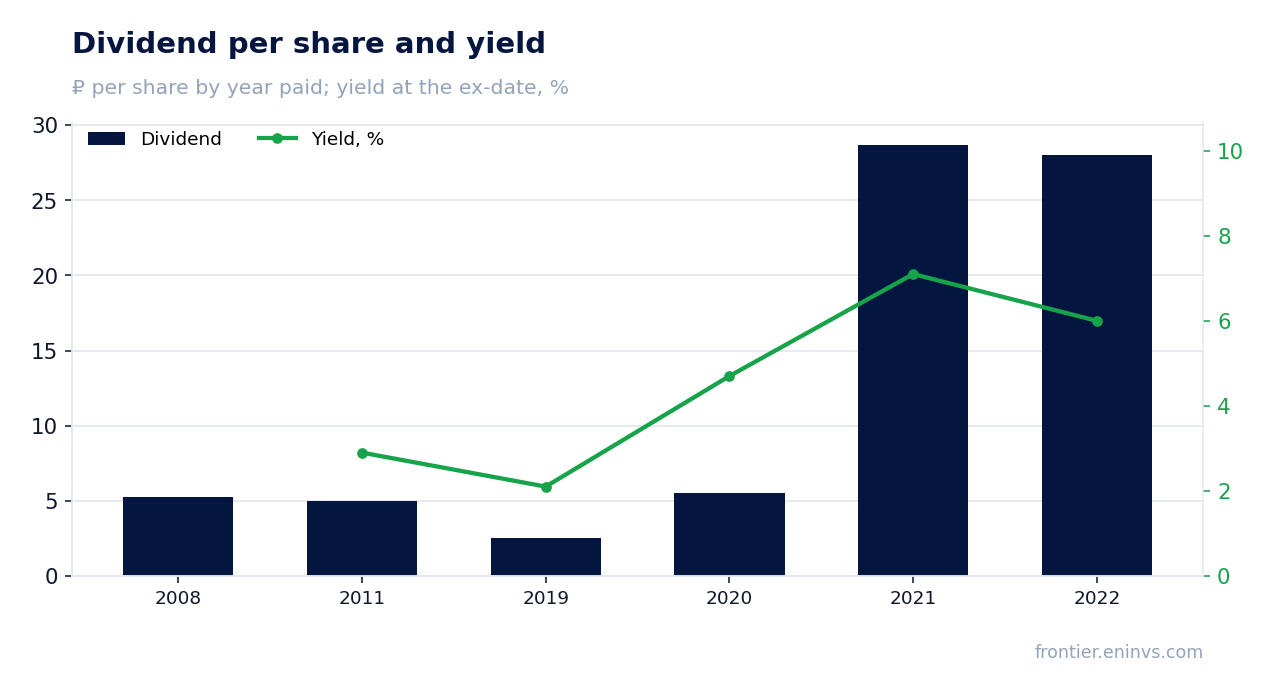
On the portal's model the share is valued 90% below the current price, reflecting weak cash generation
On the portal's model, which re-prices EBITDA at current commodity prices and a target EV/EBITDA, the fair value of the share is 90% below the current market price. This value sits at the lower bound of the model, so it should be treated as a guide rather than a precise estimate. The company's market capitalisation is RUB 86.1 bn.
Such a large gap is explained by the fact that at current coking coal prices and current capital expenditure levels, the company generates very little EBITDA – only RUB 1.4 bn for the half-year. A cash-flow-oriented model finds no support for the current valuation. The market is likely pricing in expectations of a coal price recovery that the model does not incorporate.
Comparing the current valuation with its own history of multiples is not possible due to the lack of comparable data in the FACTS. However, the very fact that the portal's model points to a 90% downside suggests that the current price is not supported by cash flows. This is an important signal for assessing the share's attractiveness.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 86.1 bn ₽ |
| P/B | 0.63 |
| Operating cash flow (LTM) | 11.2 bn |
| ROE | -12.4% |
Dividend per share, ₽, and yield at the ex-date
| Year paid | Dividend | Yield |
|---|---|---|
| 2008 | 5.25 | — |
| 2011 | 5.00 | 2.9% |
| 2019 | 2.50 | 2.1% |
| 2020 | 5.53 | 4.7% |
| 2021 | 28.70 | 7.1% |
| 2022 | 28.00 | 6.0% |
Bottom line
Bottom line: Raspadskaya showed a narrower loss and a swing in EBITDA into positive territory, but this improvement was largely driven by one-off items – an impairment reversal and a revision of the reclamation provision. Operating cash flow of RUB 1.9 bn does not cover capital expenditure of RUB 7.8 bn, and the company is drawing down its cash reserves. No dividends are being paid and none are expected in the near term. On the portal's model the share is valued 90% below the current price. At the current price of RUB 121.2, the share looks unattractive.
Open the company's financial profile RASP →
See also: market overview · valuation map · stock screeners