Yuzhuralzoloto: EBITDA doubles on record gold prices, but the portal's model sees only -8% upside
On July 31, Yuzhuralzoloto released its H1 2026 results: revenue grew 90.5% to RUB 84,124 million, EBITDA jumped 197.2% to RUB 38,069 million, and net profit rose 110.4% to RUB 15,385 million. The growth was driven by record gold prices and higher sales volumes. At the current price, the share looks rather attractive, but the portal's model sees limited upside.
Key takeaways
— Revenue doubled on higher gold prices and sales volumes
— EBITDA tripled, margin expanded to 45.2%
— Net profit rose 110%, but tax burden increased due to one-off write-offs
— Debt fell by RUB 14.7 billion in H1, debt/EBITDA at 1.27
— Operating cash flow grew 10-fold, but capex halved
— Share jumped 21.3% on the release day, but the portal's model sees -8% upside
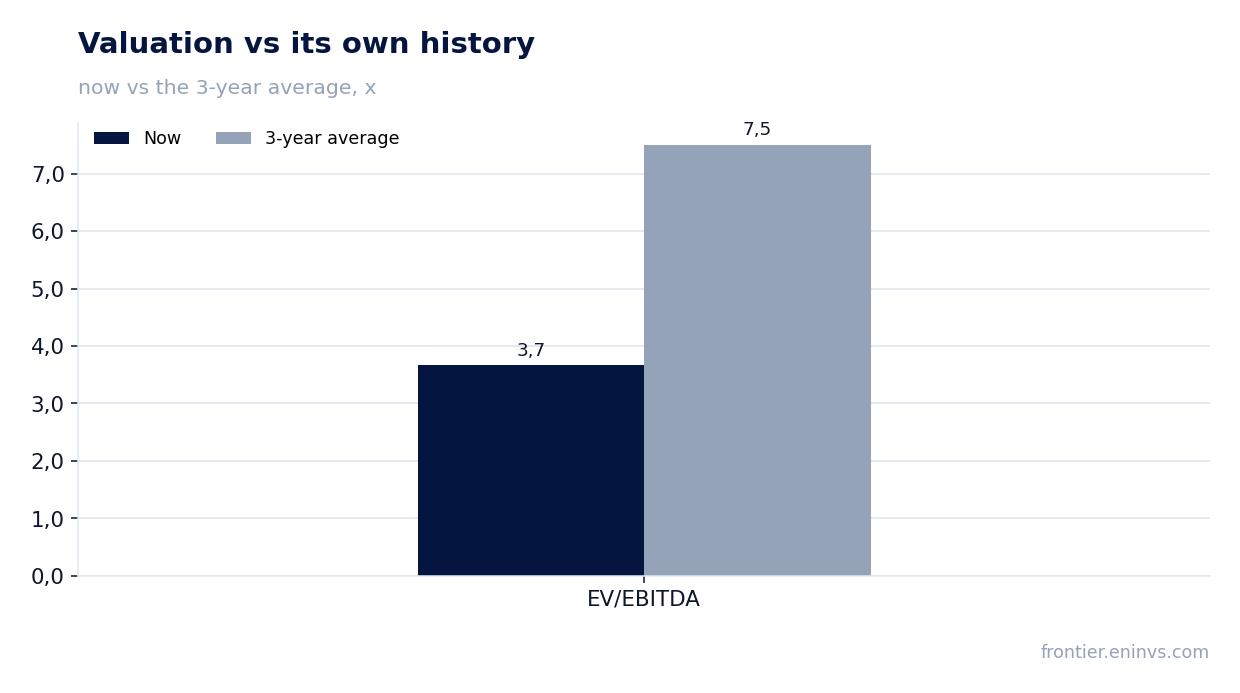
— Company trades at a discount to its own history: EV/EBITDA 3.68 vs 7.5 average
Attractiveness
Key figures, RUB bn
| Metric | H1 2025 | H1 2026 | Change |
|---|---|---|---|
| Revenue | 44.2 | 84.1 | +90.5% |
| EBITDA | 12.8 | 38.0 | +197.2% |
| Operating profit | 7.13 | 29.1 | +307.7% |
| Net profit | 7.31 | 15.4 | +110.4% |
| Operating cash flow | 2.49 | 25.6 | +926.4% |
| Capex | 10.2 | 6.82 | -33.2% |
| EBITDA margin | 28.9% | 45.2% | +16.3 pp |
| Net margin | 16.6% | 18.3% | +1.7 pp |
Revenue doubled on higher gold prices and sales volumes
In H1 2026, Yuzhuralzoloto's revenue reached RUB 84,124 million, up 90.5% year-on-year. Gold sales contributed the bulk – RUB 83,688 million, while silver added only RUB 436 million. Growth was driven by both higher gold prices and larger volumes: 7,307 kg of gold sold versus 5,129 kg in H1 2025.
Segment-wise, the Siberian hub was the main driver: revenue rose from RUB 32,302 million to RUB 63,567 million, volumes from 3,767 kg to 5,537 kg. The Ural hub also grew – from RUB 11,758 million to RUB 20,557 million – but contributed less to the overall increase.
EBITDA tripled, margin expanded to 45.2%
Adjusted EBITDA for H1 reached RUB 38,069 million versus RUB 15,360 million a year earlier – a 2.5-fold increase. EBITDA margin expanded from 28.9% to 45.2%. The margin expansion was driven by gold prices growing faster than costs: cost of sales ex-depreciation rose 55%, while revenue grew 90%.
Within cost of sales, labour costs (up from RUB 7,882 million to RUB 13,792 million) and MET (up from RUB 4,279 million to RUB 9,115 million) increased notably, reflecting both higher volumes and inflation. Still, the operating leverage effect was substantial.
Net profit rose 110%, but tax burden increased due to one-off write-offs
Net profit for H1 reached RUB 15,385 million versus RUB 7,312 million a year earlier (+110.4%). Pre-tax profit grew even faster – from RUB 9,279 million to RUB 24,164 million – but the effective tax rate rose: income tax expense increased from RUB 1,967 million to RUB 8,779 million.
The report discloses a one-off write-off of a deferred tax asset related to an investment in an associate of RUB 4,753 million, which drove the higher tax burden. Without this effect, net profit would have been significantly higher. Net margin still improved from 16.6% to 18.3%.
Debt fell by RUB 14.7 billion in H1, debt/EBITDA at 1.27
Net debt as of June 30, 2026 stood at RUB 83,978 million, down RUB 14.7 billion from the previous reporting date. Over the last 12 months, debt decreased by RUB 4.6 billion. Net debt/EBITDA for the trailing twelve months – 1.27 – is a moderate level for a gold miner.
The debt reduction was supported by strong operating cash flow and lower capital expenditures. The company repaid part of its loans: RUB 27,662 million repaid in H1, while RUB 15,506 million was raised.
Operating cash flow grew 10-fold, but capex halved
Net cash from operating activities in H1 reached RUB 25,567 million versus RUB 2,491 million a year earlier. Growth was driven by higher profit and better working capital management. Operating cash flow before working capital changes rose from RUB 9,603 million to RUB 34,577 million.
Capital expenditures decreased from RUB 12,022 million to RUB 6,875 million – the company scaled back investment after the massive construction of previous years. Free cash flow thus turned strongly positive, enabling debt reduction.
Share jumped 21.3% on the release day, but the portal's model sees -8% upside
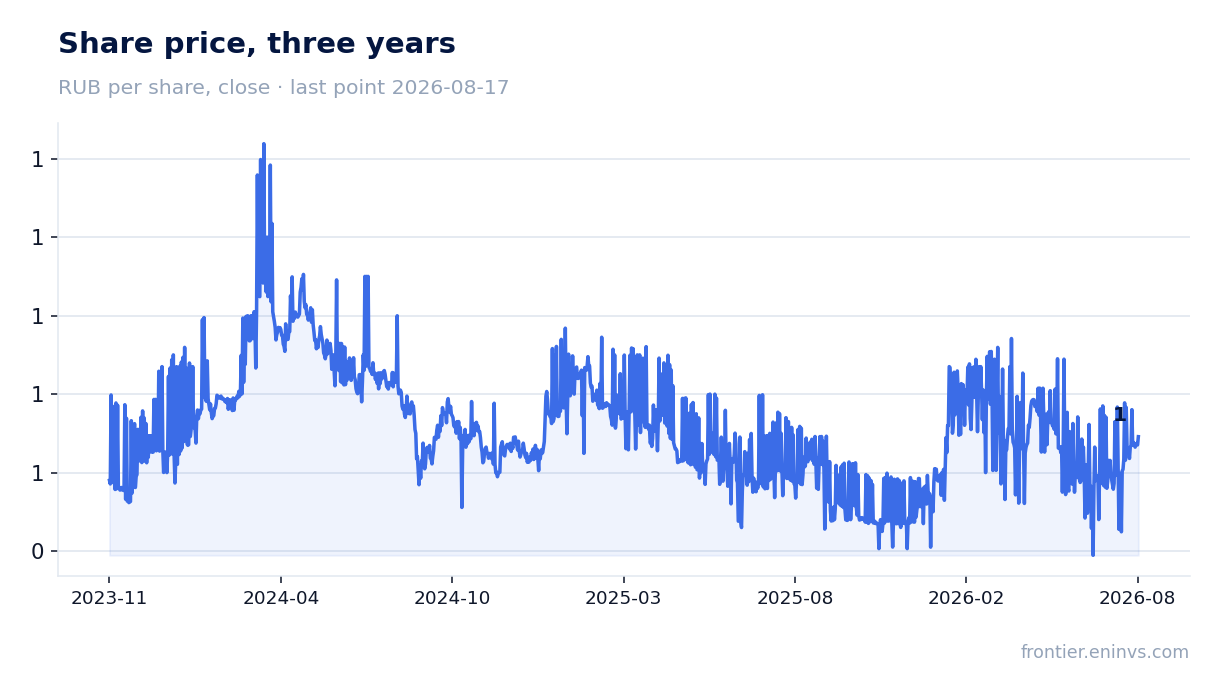
The share price before the release was RUB 0.6316; on the release day it jumped 21.3% and by August 17 added another 9.5%. The market reacted positively to the strong results and debt reduction.
However, according to the portal's model, which re-prices EBITDA at current gold prices and applies a target EV/EBITDA multiple, the fair value of the share is 8% below the current market price. This suggests that after the sharp rally, the stock may be overvalued relative to the portal's own model.
Company trades at a discount to its own history: EV/EBITDA 3.68 vs 7.5 average
EV/EBITDA for the trailing twelve months stands at 3.68, well below the three-year average of 7.5. Even after the 21.3% share price jump on the release day, the valuation remains attractive relative to historical levels.
P/E LTM is 6.65, ROE is 44.4%. The low multiples reflect both high current profitability and market caution about future gold prices and potential capex growth.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 160 bn ₽ |
| P/E (LTM) | 6.7 |
| EV/EBITDA (LTM) | 3.7 |
| P/B | 2.54 |
| Net debt / EBITDA (LTM) | 1.27 |
| Operating cash flow (LTM) | 43.5 bn |
| ROE | 44.4% |
| EV/EBITDA, 3-year average | 7.5 |
Bottom line
Yuzhuralzoloto delivered a strong H1: revenue and EBITDA doubled on record gold prices, debt declined, and free cash flow turned positive. However, part of the profit growth was affected by one-off items – a RUB 4.8 billion DTA write-off reduced net profit, while capex halving may limit future volume growth. The share trades at a discount to its own history (EV/EBITDA 3.68 vs 7.5 three-year average), making it rather attractive, but the portal's model suggests limited upside after the sharp rally. The key question for holders is the sustainability of gold prices and the company's ability to maintain volumes amid lower investment.
Open the company's financial profile UGLD →
See also: market overview · valuation map · stock screeners