Hamkorbank: revenue accelerated to +24.6%, but profit lags – margin compressed to 30.9%
In its Q3 2026 report, Hamkorbank posted revenue of UZS 1,651.1 bn, operating profit of UZS 606.4 bn and net profit of UZS 510.5 bn. Year-on-year revenue growth accelerated to +24.6% from +23.8% in Q2, but net profit rose only +10.7% and the net margin fell to 30.9% from 34.8% a year earlier. With ROE at 8.6% and a dividend yield of 0.88%, the share looks neutral: faster revenue does not offset the margin compression, while the portal's model implies +24% upside to fair value.
Key takeaways
— Revenue accelerated to +24.6% YoY, but profit rose only +10.7% – the margin compressed to 30.9% from 34.8%
— Operating profit of UZS 606.4 bn on revenue of UZS 1,651.1 bn – an operating margin of 36.7%
— Net margin of 30.9% versus 34.8% a year earlier – profit is growing slower than revenue for a third quarter
— ROE of 8.6% on a market cap of UZS 8,518.4 bn – the return on capital remains modest
— Dividend yield of 0.88% over the last 12 months – the payout is symbolic relative to profit
— On the portal's model the share trades at a +24% discount to fair value, but that is our calculation, not a consensus
Attractiveness
Key figures, UZS bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 1 325 | 1 651 | +24.6% |
| Operating profit | — | 606 | — |
| Net profit | 461 | 510 | +10.7% |
| Net margin | 34.8% | 30.9% | -3.9 pp |
Revenue accelerated to +24.6% YoY, but profit rose only +10.7% – the margin compressed to 30.9% from 34.8%
In Q3 2026 Hamkorbank's revenue reached UZS 1,651.1 bn, up 24.6% year on year. That is an acceleration from Q2, when growth was +23.8%. The quarterly revenue trajectory remains strong: from UZS 1,438.1 bn in Q1 to UZS 1,556.2 bn in Q2 and UZS 1,651.1 bn in Q3.
Net profit for the same quarter was UZS 510.5 bn, up only 10.7% year on year. The gap versus revenue comes from net margin compression to 30.9% from 34.8% a year earlier. Profit is growing slower than revenue, and this is not the first quarter of such dynamics: in Q3 2025 the margin was higher.
Operating profit was UZS 606.4 bn, an operating margin of 36.7% of revenue. The gap between operating and net profit of UZS 95.9 bn reflects taxes and other items below the operating line. That is where the main pressure on the margin occurs.
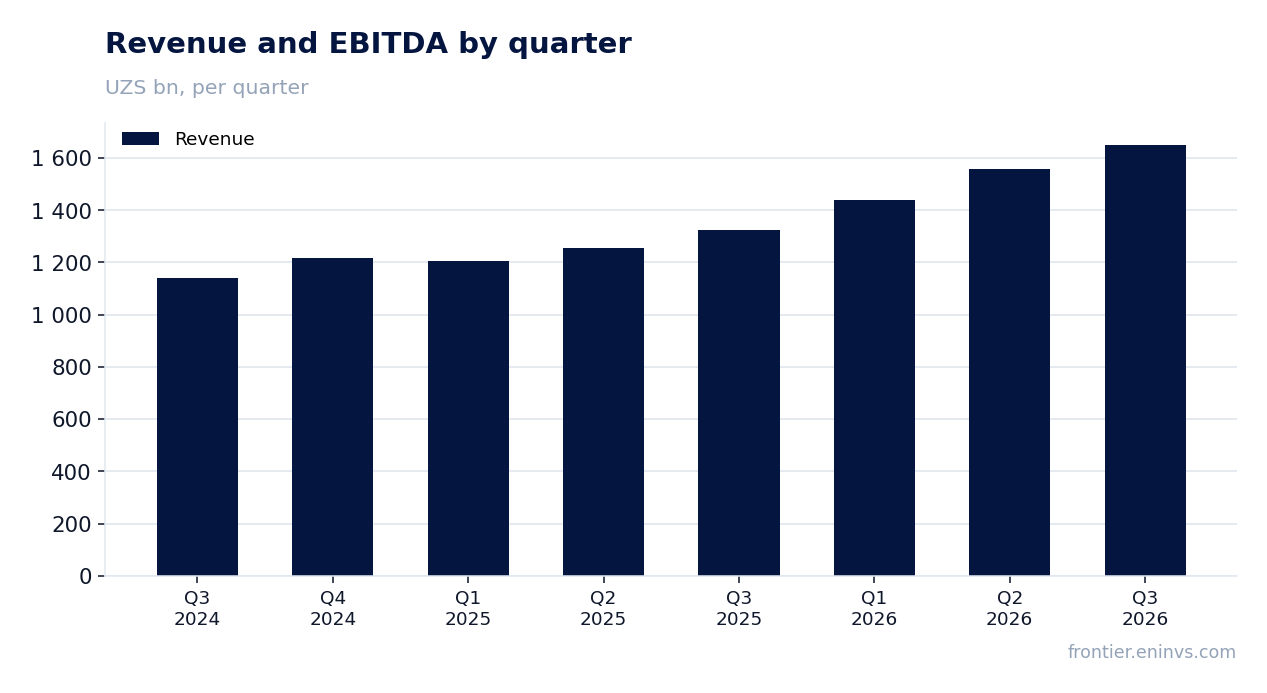
Operating profit of UZS 606.4 bn on revenue of UZS 1,651.1 bn – an operating margin of 36.7%
Operating profit in Q3 2026 was UZS 606.4 bn on revenue of UZS 1,651.1 bn, a margin of 36.7%. For a bank this is a high level, but it is below a year earlier, when revenue was UZS 1,325.2 bn and profit was different.
The gap between operating and net profit – UZS 95.9 bn – reflects taxes and items below the operating line. That is where the main pressure sits: net margin is falling faster than operating margin. While operating margin holds above 36%, net margin is already 30.9%.
For comparison, in Q2 2026 operating profit was UZS 599.0 bn on revenue of UZS 1,556.2 bn, a margin of 38.5%. In Q3 it fell to 36.7%. That is a move down, not up.
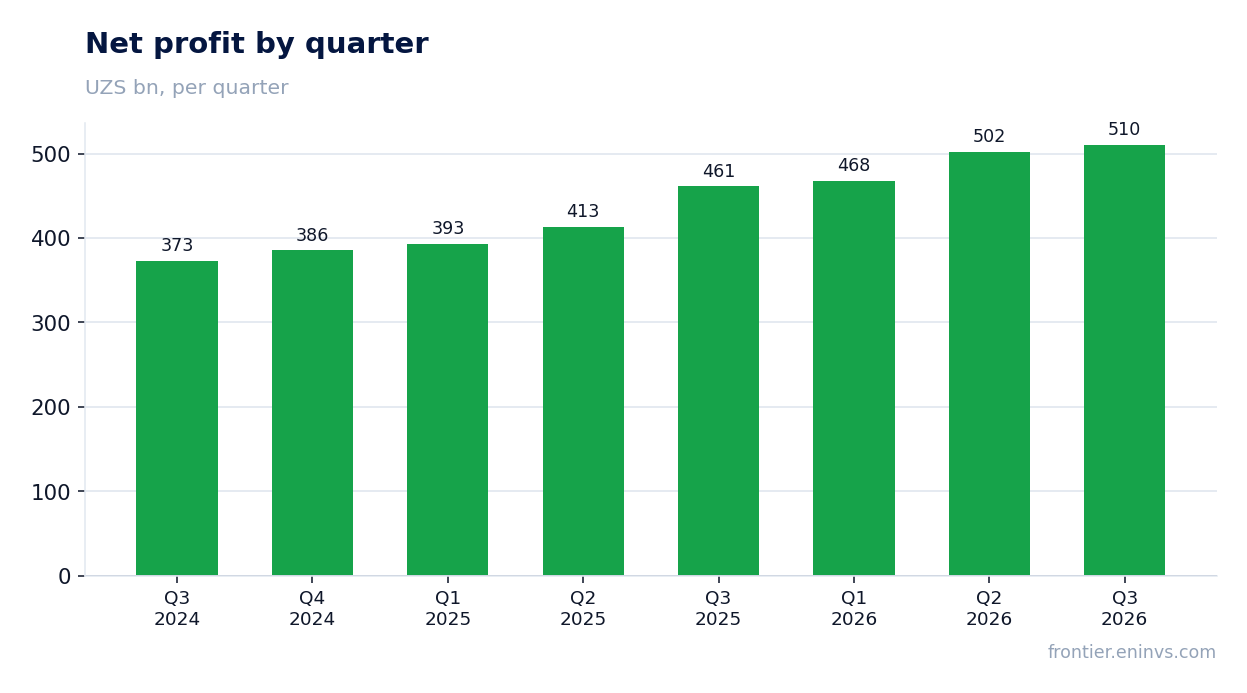
Net margin of 30.9% versus 34.8% a year earlier – profit is growing slower than revenue for a third quarter
Net margin in Q3 2026 was 30.9%, versus 34.8% a year earlier. The 3.9 percentage point compression explains why profit grew only 10.7% while revenue rose 24.6%. This is not a one-off: the margin is declining consistently.
Profit has grown slower than revenue for three consecutive quarters. In Q1 2026 net profit was UZS 467.7 bn, in Q2 – UZS 502.3 bn, in Q3 – UZS 510.5 bn. There is growth, but it is modest relative to revenue dynamics.
Margin compression is the key risk for valuation. If it continues, profit may stop growing even as revenue accelerates. Stabilisation of the margin, not further revenue acceleration, will determine whether the bank can improve its financial result.
ROE of 8.6% on a market cap of UZS 8,518.4 bn – the return on capital remains modest
Hamkorbank's return on equity (ROE) is 8.6%. With a market capitalisation of UZS 8,518.4 bn, this is a modest figure for a bank. For comparison, Q3 profit of UZS 510.5 bn on such a market cap implies an annualised return of about 24% from one quarter alone, but ROE accounts for all capital, not just market valuation.
A low ROE means the bank is not using capital efficiently. This limits the potential for dividend growth and valuation re-rating. Improving ROE requires either higher profit, capital reduction, or both.
On the portal's model, based on the ROE-to-P/B relationship, the share trades at a +24% discount to fair value. This is our own calculation, not a market consensus. It implies the current price does not fully reflect the bank's profitability.
Dividend yield of 0.88% over the last 12 months – the payout is symbolic relative to profit
Hamkorbank's dividend yield over the last 12 months is 0.88%. With a market capitalisation of UZS 8,518.4 bn, this implies about UZS 75 bn was paid in dividends. That is a small amount relative to quarterly profit of UZS 510.5 bn.
The low payout is likely explained by the need to maintain capital. With ROE at 8.6%, the bank does not generate excess capital that can be distributed. Judging by actual payments, the dividend policy is conservative.
For an income-oriented investor, a dividend yield of 0.88% is unattractive. The main return can only come from share price appreciation, not from payouts. This is important to consider when assessing the attractiveness of the stock.
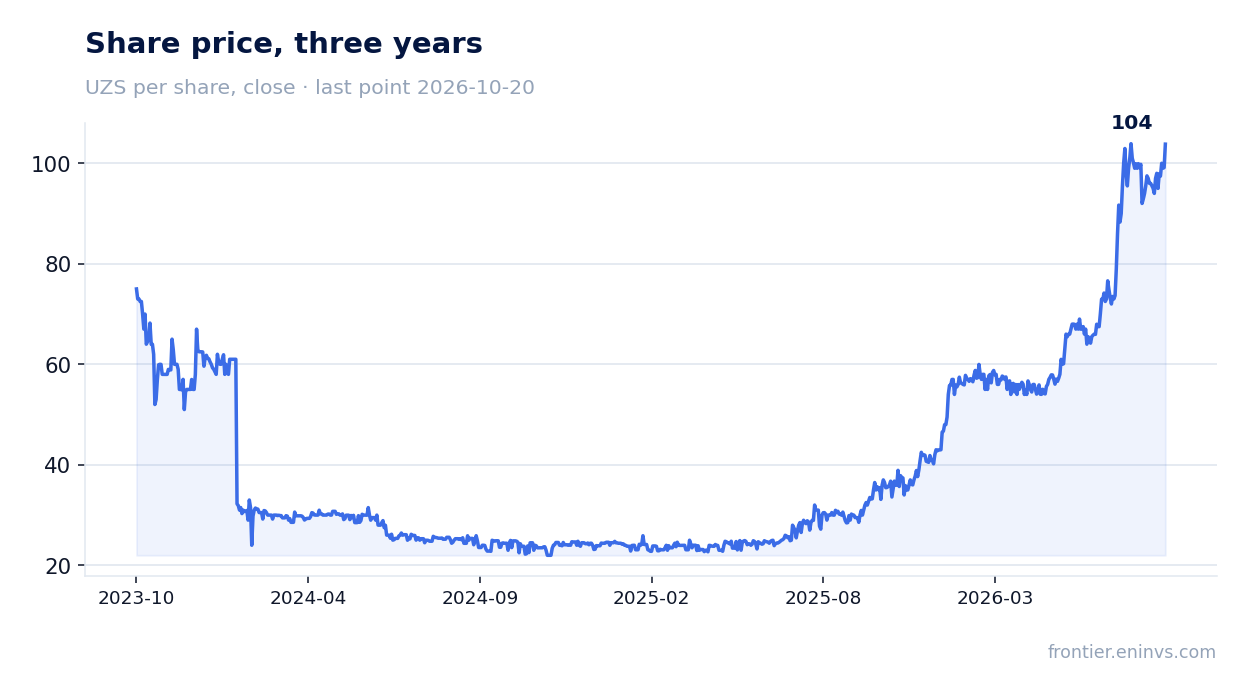
On the portal's model the share trades at a +24% discount to fair value, but that is our calculation, not a consensus
On the portal's model, which compares ROE with P/B, the fair value of Hamkorbank shares is +24% above the current price. This is our own calculation, not a consensus forecast or a target price. The model implies the market undervalues the bank's profitability.
However, the model does not account for the risk of further margin compression. If net margin continues to fall, profit may decline and fair value would be lower. In addition, ROE of 8.6% is a modest figure that limits re-rating potential.
Realising the +24% potential requires margin stabilisation and ROE growth. Without that, the discount could persist for a long time. The model provides a benchmark, not a guarantee.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 8 518 bn UZS |
| P/B | 1.04 |
| ROE | 8.6% |
| Dividend yield (12m) | 0.9% |
Bottom line
The strong point of the report is revenue acceleration to +24.6% YoY, above +23.8% in Q2. The weak point is net margin compression to 30.9% from 34.8%, which meant profit grew only +10.7%. ROE of 8.6% and a dividend yield of 0.88% do not create appeal. The portal's model implies +24% upside, but it requires margin stabilisation. The verdict is neutral: revenue acceleration is offset by margin decline, and the current valuation offers no clear edge.
Open the company's financial profile HAMKOR →
See also: market overview · valuation map · stock screeners