DMCI Holdings: net profit rose 52.1% while quarterly operating profit nearly halved
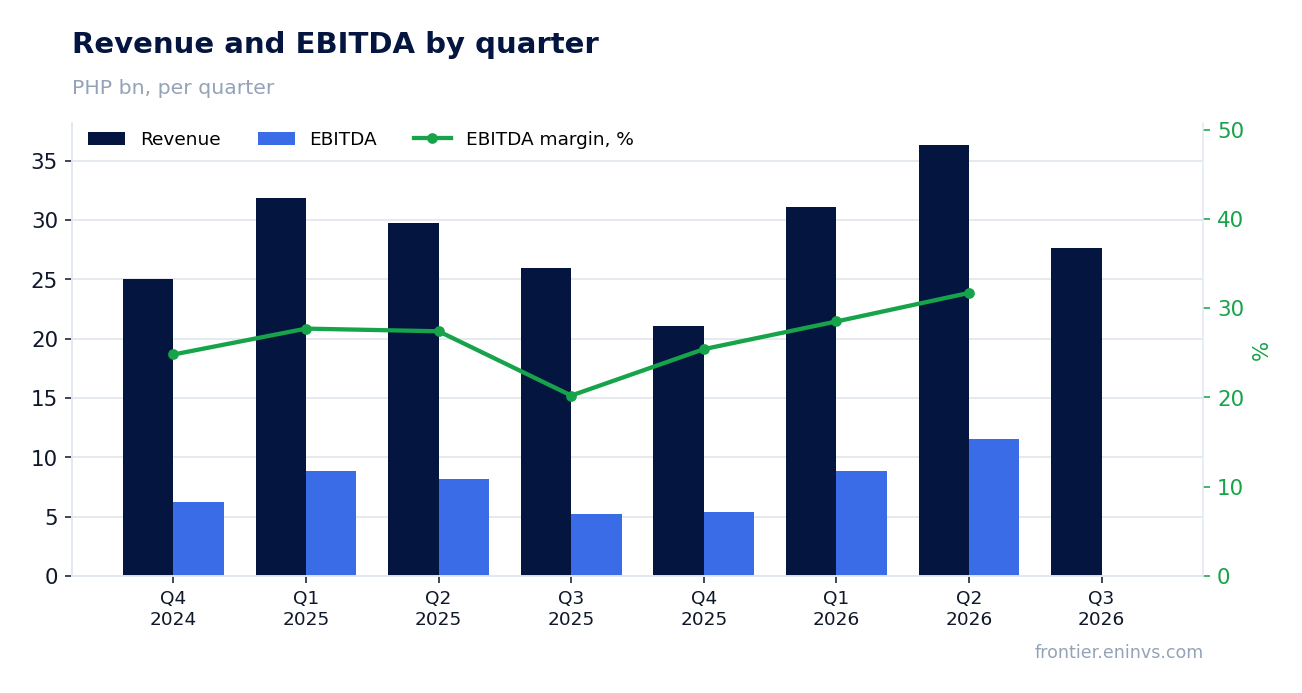
In its Q3 2026 report DMCI Holdings posted revenue of PHP 27,652.1m and net profit of PHP 4,666.7m – up 6.5% and 52.1% year on year respectively. Net margin rose to 16.9% from 11.8% a year earlier, but quarterly operating profit came in at PHP 4,040.1m against PHP 2,307.1m a year earlier, and revenue growth decelerated from 22.2% in Q2 to 6.5%. At a P/E LTM of 5.8 and a dividend yield of 12.0%, the share looks attractive at the current price, though the durability of profit is open to question.
Key takeaways
— Revenue rose 6.5% year on year, but growth decelerated from 22.2% in Q2
— Net profit added 52.1% and net margin rose to 16.9% from 11.8%
— Quarterly operating profit fell to PHP 4,040.1m from PHP 2,307.1m a year earlier
— Leverage at 1.12x EBITDA LTM is moderate, but the debt trend cannot be assessed
— A 12.0% dividend yield against a P/E LTM of 5.8 is the main argument for the share
— On the portal's model the upside to fair value is +7%
Attractiveness
Key figures, PHP bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 26.0 | 27.7 | +6.5% |
| EBITDA | 5.23 | — | — |
| Operating profit | 2.31 | 4.04 | +75.1% |
| Net profit | 3.07 | 4.67 | +52.1% |
| Operating cash flow | 10.4 | — | — |
| Capex | 2.88 | — | — |
| EBITDA margin | 20.2% | — | — |
| Net margin | 11.8% | 16.9% | +5.1 pp |
Revenue rose 6.5% year on year, but growth decelerated from 22.2% in Q2
In Q3 2026 revenue came to PHP 27,652.1m, 6.5% more than a year earlier. That is markedly slower than Q2, when growth reached 22.2%: quarter on quarter revenue fell from PHP 36,350.4m, roughly by a quarter.
The deceleration does not erase the fact that the company is growing: the positive rate has held for two quarters in a row after declines of 2.4% in Q1 2026 and 15.6% in Q4 2025. But the gap between 22.2% and 6.5% shows that the high pace at the start of the year was not sustainable.
The next report matters for judging durability: if Q4 2026 revenue stays around PHP 27–28bn, the annual rate will return to single digits and growth will stop being an argument for the share.
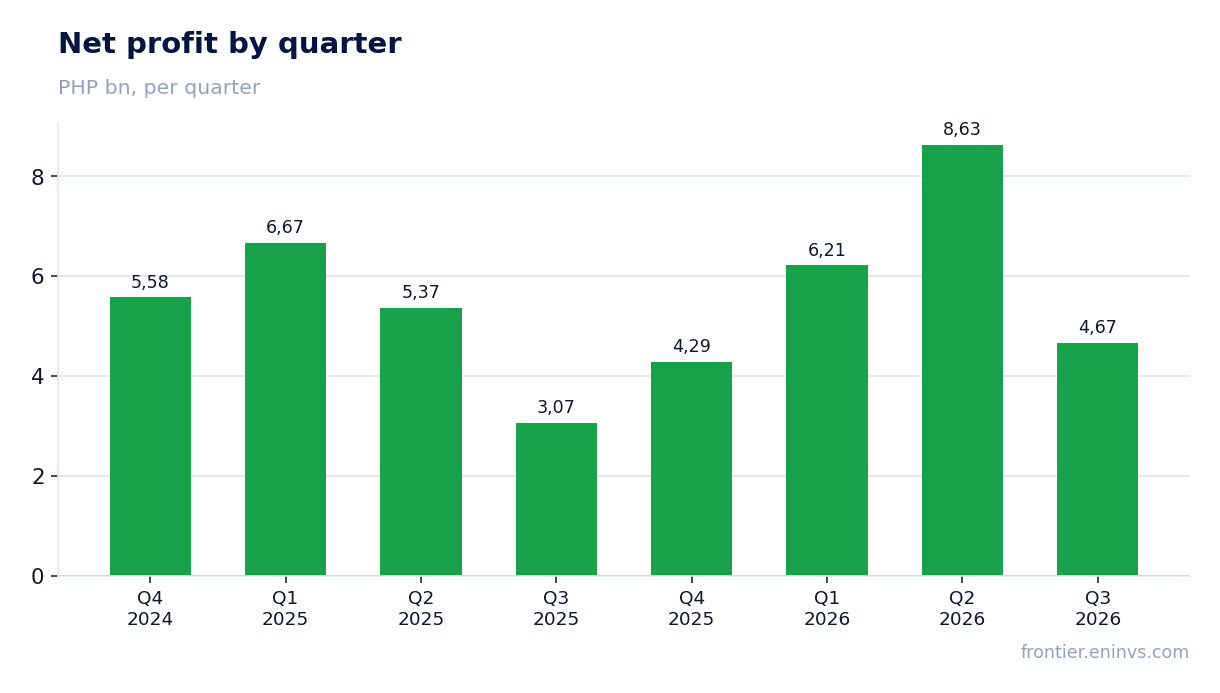
Net profit added 52.1% and net margin rose to 16.9% from 11.8%
Net profit in Q3 2026 was PHP 4,666.7m against PHP 3,068.3m a year earlier – growth of 52.1%. Net margin rose to 16.9% from 11.8%, or by 5.1 percentage points.
Profit growth on revenue growth of 6.5% means most of the gain came not from sales volume but from a lower cost base or one-off items below operating profit. Operating profit for the quarter was PHP 4,040.1m – below net profit, which points to a positive contribution from lines below the operating result.
The durability of this result is the main question. If profit was supported by one-off receipts, there is no reason to expect a repeat next quarter, and the current 16.9% margin would prove overstated.
Quarterly operating profit fell to PHP 4,040.1m from PHP 2,307.1m a year earlier
Operating profit in Q3 2026 was PHP 4,040.1m against PHP 2,307.1m a year earlier. It is the one line in the report that directly shows cost pressure: with revenue up 6.5%, the operating result grew faster but remains below net profit.
The PHP 626.6m gap between operating and net profit means that below the operating line the company received more than it paid in interest and taxes. That is the part that delivered the 52.1% rise in net profit.
For an investor this is a signal: earnings quality is lower than the headline suggests. Operating profit is the more durable base, and its quarterly level of PHP 4,040.1m corresponds to annual operating profit of about PHP 16bn, which against the current market cap of PHP 88,295.2m gives a high return on the operating result.
Leverage at 1.12x EBITDA LTM is moderate, but the debt trend cannot be assessed
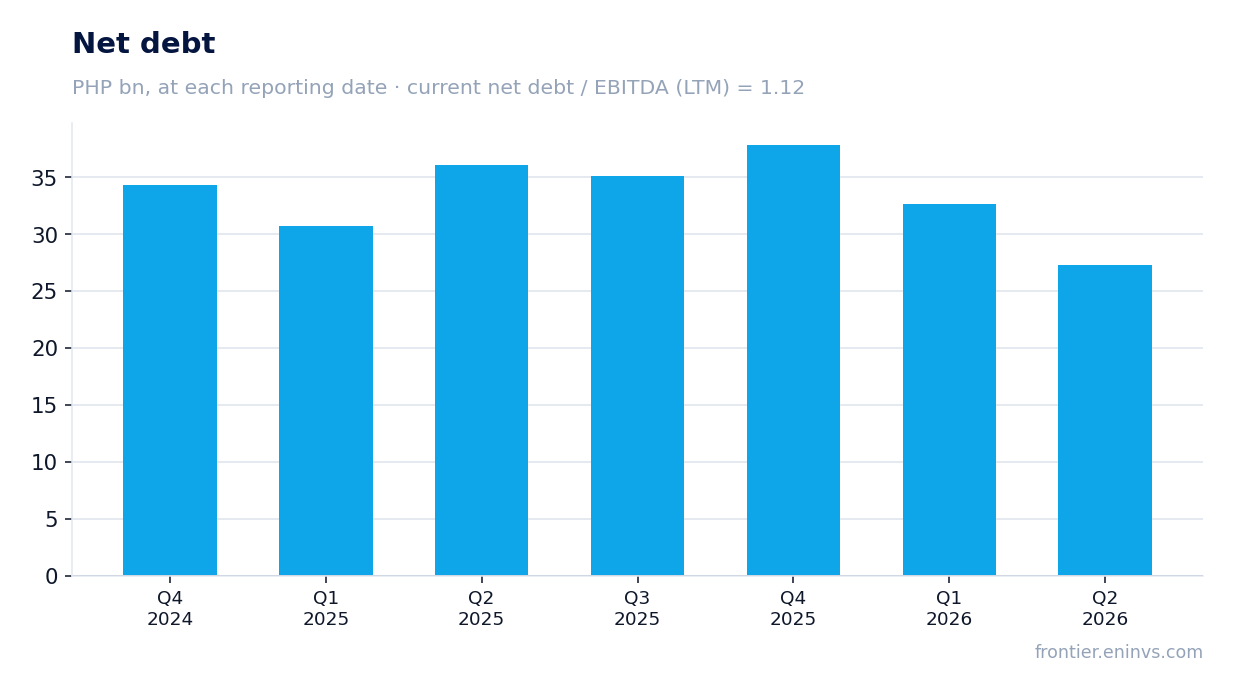
Net debt at the latest annual balance-sheet date was PHP 37,839.4m, equal to 1.12x EBITDA over the last twelve months. That is a moderate level: LTM EBITDA of PHP 33,842.1m covers the debt almost entirely.
Leverage cannot be compared with an earlier period – no earlier value of the ratio is in the facts. All that is known is that net debt moved by quarter: from PHP 34,359.9m at the end of Q4 2024 to PHP 27,253.7m at the end of Q2 2026, so debt declined over that period.
Operating cash flow for the last twelve months is not disclosed, so the ability to service debt from revenue can only be judged by EBITDA. At 1.12x EBITDA, leverage is not a constraint on dividends, but it leaves no room for large investment without new borrowing.
A 12.0% dividend yield against a P/E LTM of 5.8 is the main argument for the share
The dividend yield over the last twelve months is 12.0% – the highest figure in the facts and the main argument for the share. At a market cap of PHP 88,295.2m that yield corresponds to payouts of about PHP 10.6bn a year.
Our estimate for the current year's dividend is about PHP 10–11bn, based on LTM profit of PHP 15,170.8m and a payout ratio of around 70%. The estimate rests on two conditions: profit must not fall below the LTM level, and one-off items must not drain cash flow.
A yield of 12.0% is well above the key rate, which makes the share interesting for income. But the durability of the payout depends on profit: if the one-off receipts that drove the 52.1% rise in net profit do not repeat, the dividend may be smaller.
What would make the payout smaller: a fall in operating profit, higher capital spending, or the need to direct cash to debt service. For now leverage of 1.12x EBITDA leaves room for payouts.
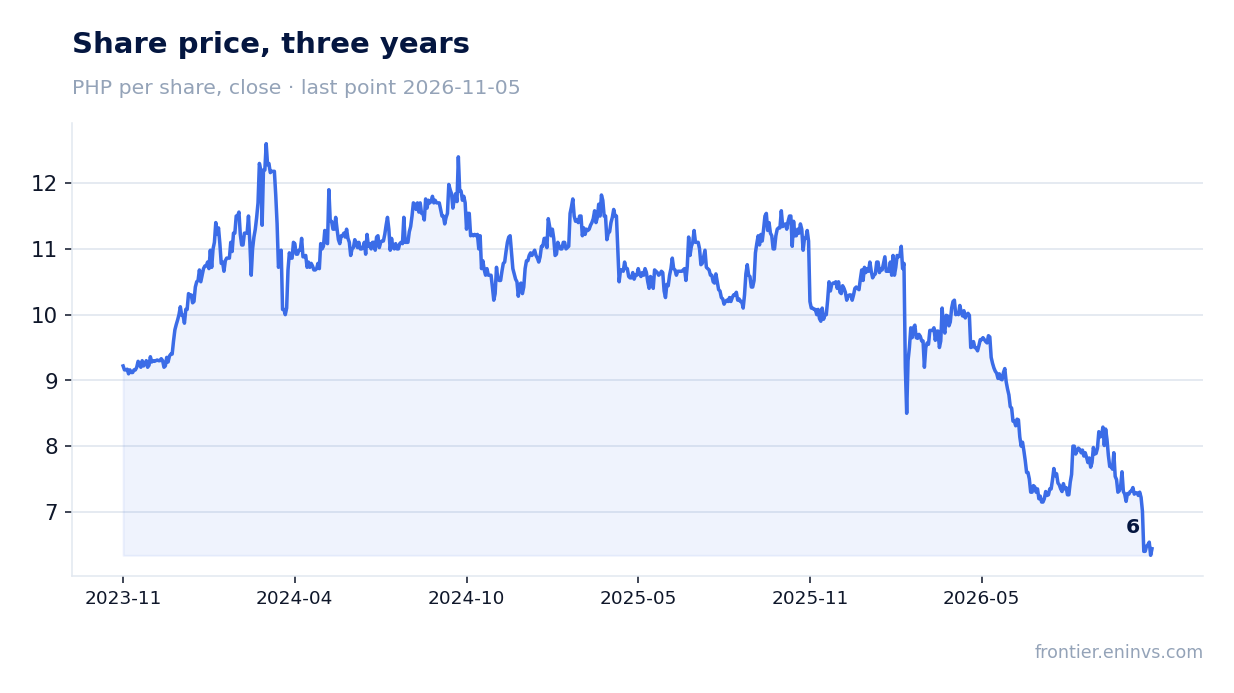
On the portal's model the upside to fair value is +7%
On the portal's model, which compares EBITDA growth with a target multiple and market cap, the upside of the share to fair value is +7%. That is a moderate but positive margin, consistent with low multiples: P/E LTM of 5.8 and EV/EBITDA LTM of 3.7.
The current P/E cannot be compared with its own three-year history – no average is in the facts. But a level of 5.8 is low in itself for a company with a 16.9% net margin and a 12.0% dividend yield.
The portal's model estimate is not a market consensus or a target price. It shows that at the current price the share trades below the fair value calculated by our method, and that supports the attractiveness of the stock.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 88.3 bn PHP |
| P/E (LTM) | 5.8 |
| EV/EBITDA (LTM) | 3.7 |
| P/B | 0.59 |
| Net debt / EBITDA (LTM) | 1.12 |
| ROE | 11.6% |
| Dividend yield (12m) | 12.0% |
Bottom line
The strong side of the report was net profit: PHP 4,666.7m for the quarter, up 52.1%, with a margin of 16.9% against 11.8% a year earlier. But operating profit of PHP 4,040.1m is below net profit, and revenue growth decelerated to 6.5% from 22.2% in Q2 – so part of the result came from one-off items. Leverage of 1.12x LTM EBITDA is moderate, and a 12.0% dividend yield against a P/E LTM of 5.8 remains the main argument. The question for a holder now is whether next quarter's profit will repeat without one-off receipts. The verdict is attractive.
Open the company's financial profile DMC →
See also: market overview · valuation map · stock screeners