Mechel: coking coal rose 18.9% in rouble terms, yet EBITDA stayed negative – volumes and unit costs got in the way
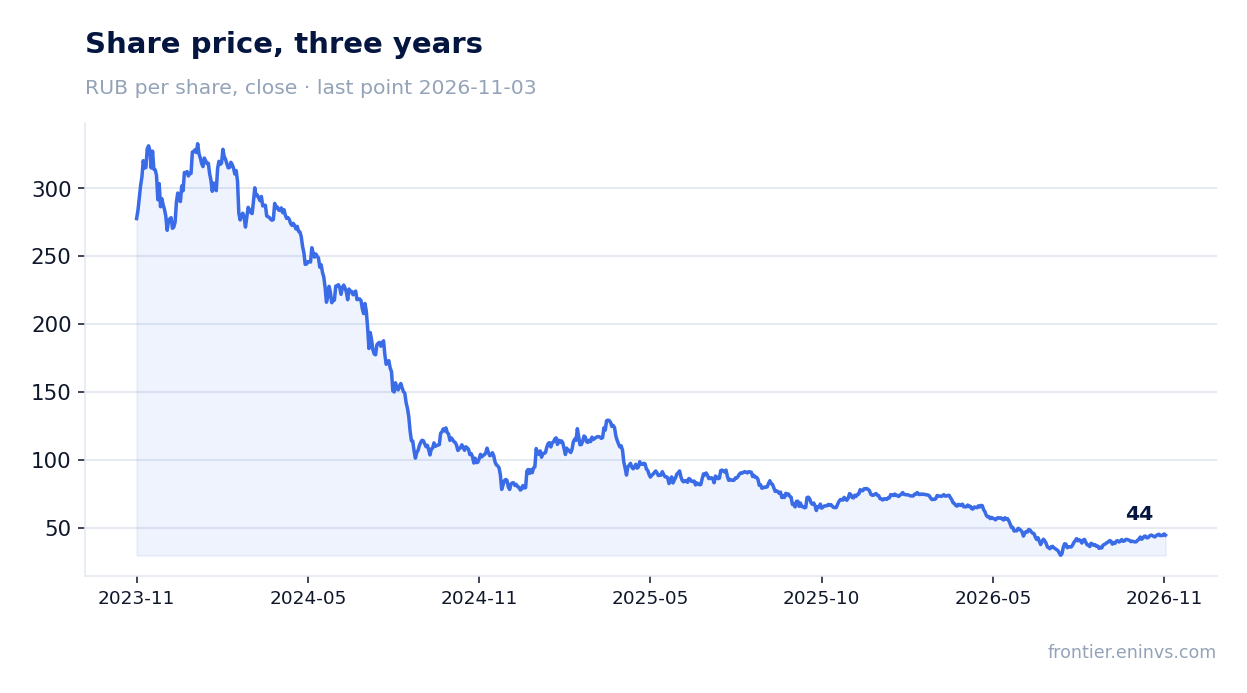
On 28 August Mechel released its Q2 2026 results. The average coking coal price in the period was USD 238 versus USD 185 a year earlier, and in rouble terms, with the rate at 74.6 versus 80.8, the price rose 18.9%. At year-ago volumes and costs our calculation implies revenue of RUB 80,212.5 mn and EBITDA of minus RUB 2,475.5 mn, but reported revenue was RUB 58,675 mn and EBITDA minus RUB 4,875 mn. The net loss reached RUB 21,590 mn, net debt rose to RUB 306.2 bn, and at a price of RUB 45.31 the share looks unattractive: negative EBITDA and leverage outweigh the coal rally.
Key takeaways
— Coking coal rose 18.9% in roubles, yet revenue fell 22.9% – the price gain was outweighed by lower volumes
— At year-ago volumes and costs our calculation implies EBITDA of minus RUB 2,475.5 mn versus the reported minus RUB 4,875 mn
— The mining segment, with revenue of RUB 22,312 mn, posted an operating loss of RUB 5,317 mn; the metallurgical segment lost RUB 11,723 mn
— The RUB 21,590 mn net loss was deepened by RUB 3,948 mn of write-downs, but they do not explain EBITDA
— Net debt rose from RUB 280.9 bn at end-2025 to RUB 306.2 bn, while interest for the half-year reached RUB 26,259 mn
— Quarterly operating cash flow of RUB 13,582 mn does not cover interest and capex of RUB 1,900.5 mn
— No dividends were paid over the last 12 months, and with a loss there is no source for a payout
Attractiveness
Key figures, RUB bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 76.1 | 58.7 | -22.9% |
| EBITDA | -6.54 | -4.88 | — |
| Operating profit | -11.3 | -8.50 | — |
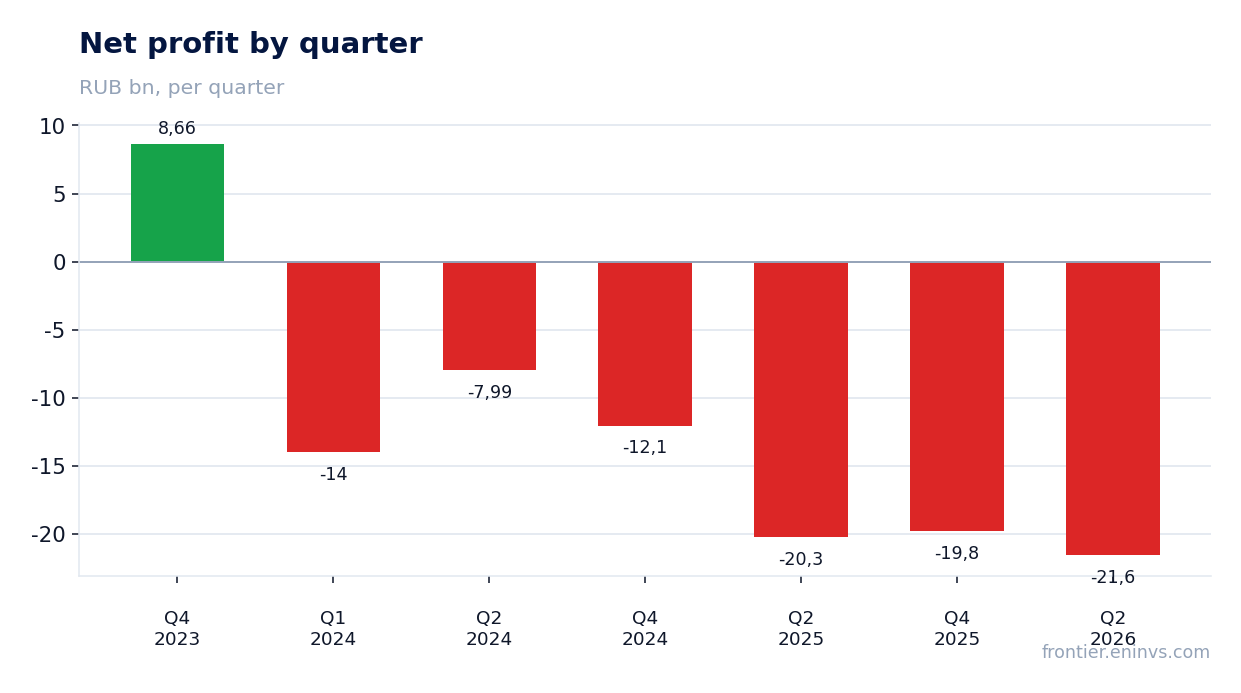
| Net profit | -20.3 | -21.6 | — |
| Operating cash flow | 16.6 | 13.6 | -18.3% |
| Capex | 3.20 | 1.90 | -40.6% |
| EBITDA margin | -8.6% | -8.3% | +0.3 pp |
| Net margin | -26.6% | -36.8% | -10.2 pp |
Coking coal rose 18.9% in roubles, yet revenue fell 22.9% – the price gain was outweighed by lower volumes
The average coking coal price in the reported period was USD 238 versus USD 185 a year earlier, up 28.7%. Over the same period the rouble strengthened from 80.8 to 74.6 per dollar, so in rouble terms the price added 18.9%. Spot is now USD 258.9, another 8.8% above the quarterly average.
Revenue in Q2 2026 was RUB 58,675 mn, 22.9% less than a year earlier. The price rose, so volumes sold must have fallen by more than the price gain compensated. The company's release explicitly cites lower orders from large buyers and weaker demand for construction steel, as well as logistical constraints.
The Russian CRC price fell 13.6% over the same period to RUB 72,072, and spot is now RUB 70,050, another 2.8% lower. The metallurgical segment, with RUB 73,240 mn of half-year revenue, was working against a falling domestic market, the second source of revenue weakness.
Commodity prices: period average and now
| Benchmark | Year ago | Q2 2026 | YoY | Spot 2026-11-06 |
|---|---|---|---|---|
| Coking coal, USD | 185,0 | 238,0 | +28,7% | 258,9 |
| CRC (Russia), RUB | 83 459 | 72 072 | -13,6% | 70 050 |
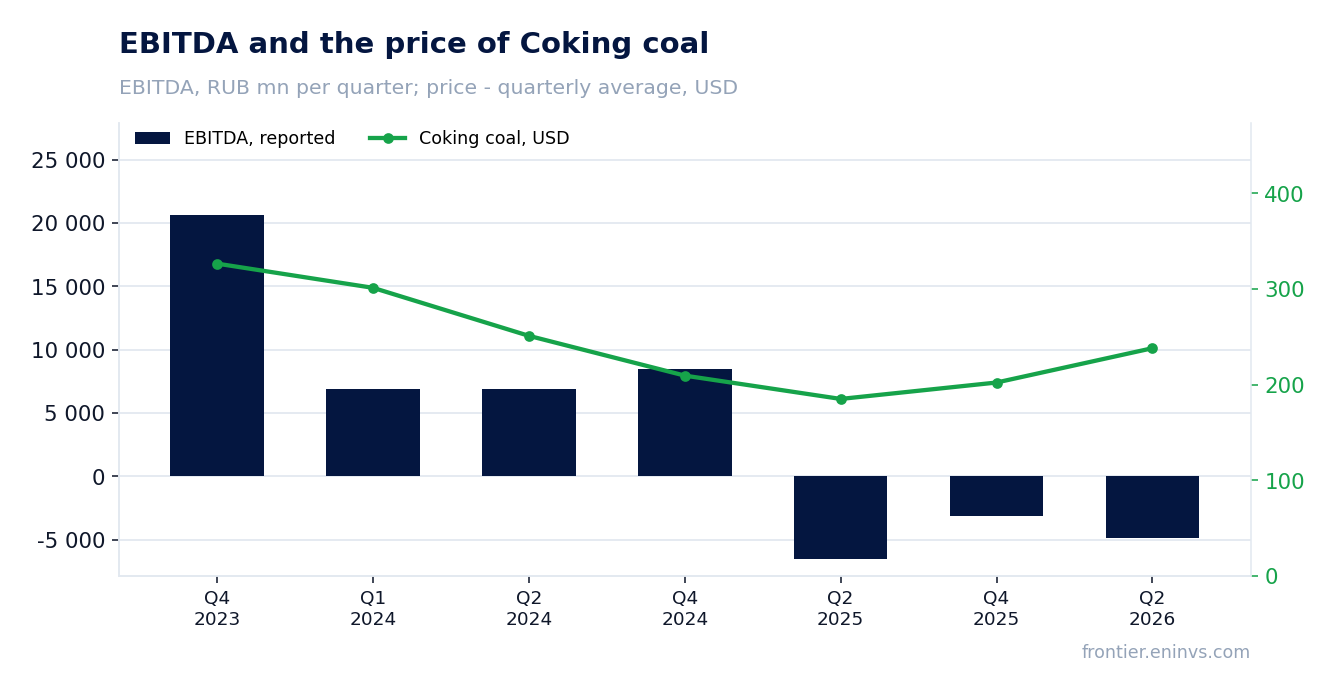
At year-ago volumes and costs our calculation implies EBITDA of minus RUB 2,475.5 mn versus the reported minus RUB 4,875 mn
Taking Q2 2025 volumes and non-commodity costs and substituting only the new coal and CRC prices gives revenue of RUB 80,212.5 mn and EBITDA of minus RUB 2,475.5 mn. Actual revenue was RUB 21,537.5 mn lower, and actual EBITDA RUB 2,399.5 mn lower.
The gap is explained by sales volumes, realised prices against the benchmark and the revenue mix. In the mining segment, half-year revenue from coal and middlings was RUB 11,719 mn versus RUB 9,583 mn a year earlier, but coke revenue fell from RUB 5,457 mn to RUB 2,653 mn and freight services from RUB 10,868 mn to RUB 7,502 mn. The coal price rose while the associated sales shrank.
EBITDA in these calculations is the operating loss of RUB 8,504.5 mn plus depreciation of RUB 3,629 mn. Interest and FX differences are not in it and explain only net profit. The gap to the price-implied figure therefore has to be sought in production and sales, not in financial lines.
What the prices implied and what the company earned
| Base (Q2 2025) | Implied at period prices | Reported | Reported vs implied | |
|---|---|---|---|---|
| Revenue, RUB mn | 76 145 | 80 212 | 58 675 | -26,9% |
| EBITDA, RUB mn | -6 543 | -2 476 | -4 875 | — |
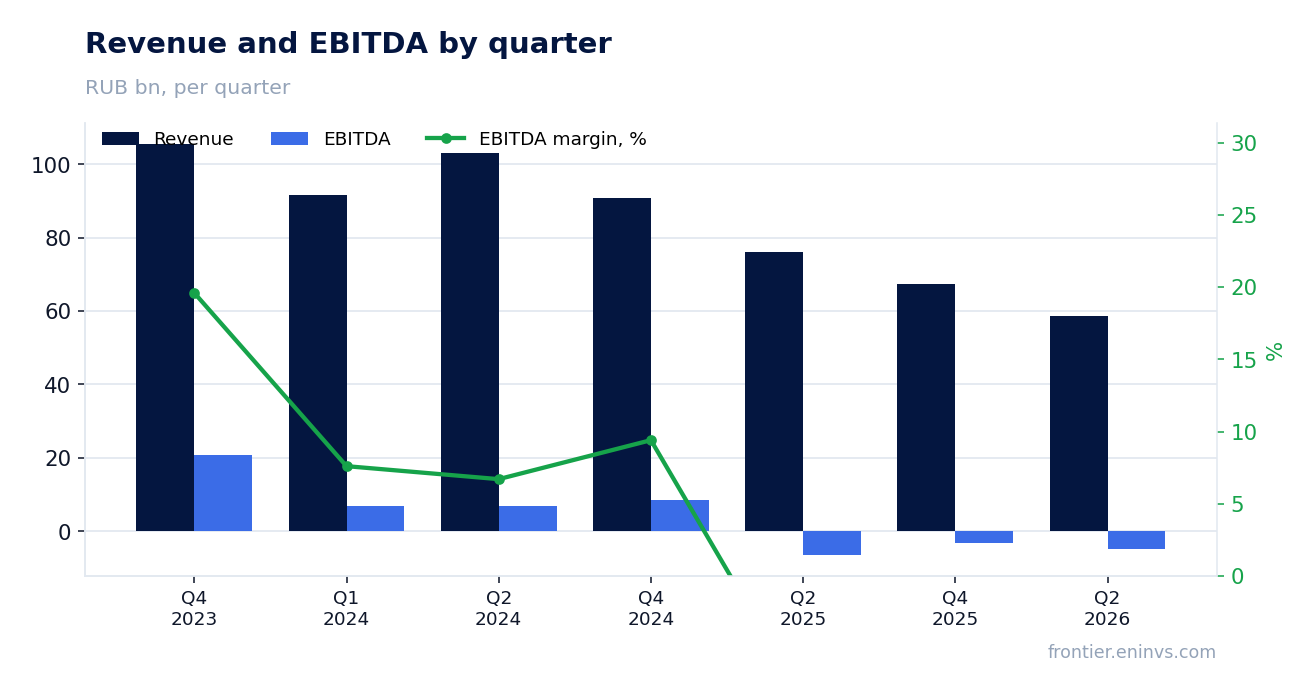
The mining segment, with revenue of RUB 22,312 mn, posted an operating loss of RUB 5,317 mn; the metallurgical segment lost RUB 11,723 mn
In H1 2026 the mining segment generated revenue of RUB 22,312 mn and an operating loss of RUB 5,317 mn with depreciation of RUB 3,401 mn. A year earlier, on revenue of RUB 26,568 mn, the loss was RUB 21,620 mn, but that included a RUB 14,427 mn impairment of goodwill and other non-current assets. Now the write-down was RUB 803 mn, so the mining loss narrowed even as revenue fell.
The metallurgical segment, on revenue of RUB 73,240 mn, posted an operating loss of RUB 11,723 mn versus a loss of RUB 262 mn a year earlier. Its gross profit turned negative at RUB 1,085 mn versus plus RUB 13,375 mn a year earlier – the main source of the deterioration in the consolidated result.
The power segment stayed profitable at the operating level: revenue of RUB 21,798 mn, gross profit of RUB 10,715 mn, operating loss of RUB 907 mn. It could not offset the losses of the other two segments.
The RUB 21,590 mn net loss was deepened by RUB 3,948 mn of write-downs, but they do not explain EBITDA
In the Q2 2026 report the net loss was RUB 21,590 mn versus RUB 20,255.5 mn a year earlier. The net margin worsened from minus 26.6% to minus 36.8%.
The issuer's release lists the one-off items: impairment of goodwill and other non-current assets of RUB 803 mn, a write-down of inventories to net realisable value of RUB 2,458 mn and a change in the allowance for expected credit losses of RUB 687 mn. Together that is RUB 3,948 mn.
These items sit within commercial, selling and operating expenses, i.e. above operating profit, and are therefore already inside EBITDA. They explain part of the loss but not the gap to the price-implied figure: without them EBITDA would still be negative. Interest payable for the half-year was RUB 26,259 mn and explains the net loss, but not EBITDA.
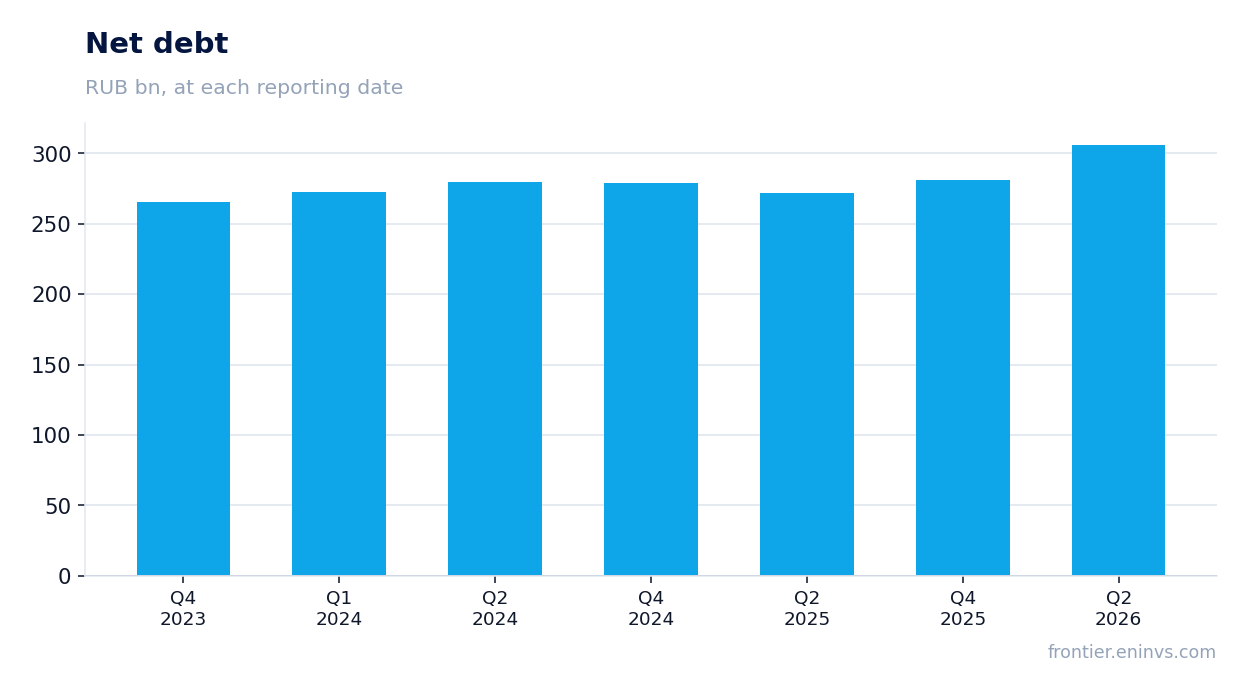
Net debt rose from RUB 280.9 bn at end-2025 to RUB 306.2 bn, while interest for the half-year reached RUB 26,259 mn
Net debt at 30 June 2026 was RUB 306.2 bn versus RUB 280.9 bn at 31 December 2025, an increase of RUB 25.3 bn. Over 12 months debt added RUB 34.0 bn – from RUB 272.2 bn at 30 June 2025.
Financial expenses in H1 2026 were RUB 26,259 mn, of which interest on loans and borrowings was RUB 20,085 mn and lease interest RUB 2,091 mn. With negative EBITDA, debt is not serviced out of operating profit.
The release reports breaches of payment obligations under certain loan agreements with foreign banks and states that debt repayable on demand amounted to RUB 245,692 mn. In April 2026 agreements were signed with one Russian bank to extend the full repayment date of RUB 17,216 mn of loans to September 2027. Management estimates an additional financing need of about RUB 47 bn in H2 2026 and H1 2027.
Quarterly operating cash flow of RUB 13,582 mn does not cover interest and capex of RUB 1,900.5 mn
Operating cash flow in Q2 2026 was RUB 13,582 mn and capex RUB 1,900.5 mn. For the half-year, per the cash flow statement, operating cash flow was RUB 27,164 mn, investment in fixed assets RUB 3,801 mn and interest paid RUB 14,262 mn.
Capex was cut: RUB 3,801 mn for the half-year versus RUB 6,395 mn a year earlier. The company plans up to 85 units of large mining equipment in 2026, a significant part already commissioned in Q2, mostly under finance leases. That shifts the burden from capex to lease payments.
Operating cash flow is supported by working capital release: over the half-year receivables fell RUB 5,055 mn, inventories RUB 4,660 mn, while payables rose RUB 12,591 mn. That source is finite, and with negative EBITDA it does not create a base for sustainable debt service.
No dividends were paid over the last 12 months, and with a loss there is no source for a payout
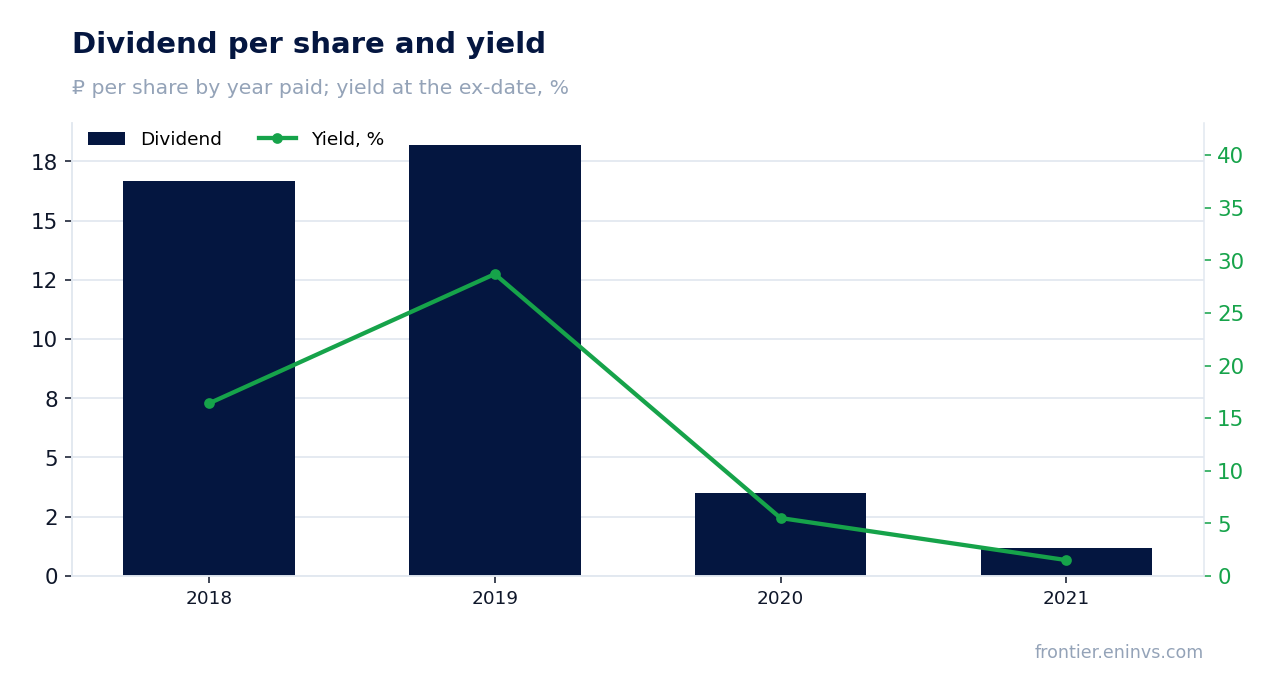
No dividends were paid over the last 12 months, and the trailing yield is zero. The last calendar-year payments date to 2021 – RUB 1.17 per share, with RUB 16.66 and RUB 18.21 per share paid in 2018 and 2019 respectively.
Our estimate of the annual dividend under the canonical model is RUB 0.0 per share, i.e. no payout is assumed. The model starts from a profit base of minus RUB 82,429 mn; with negative profit a payout ratio of 0.5 yields no positive amount.
The yield we consider fair for this name is 12.0% against a key rate of 14.0%. A dividend requires positive profit, and with current prices and RUB 306.2 bn of debt none is visible. The payout could also be constrained by the need to direct cash flow to debt service and to fund about RUB 47 bn of additional financing needs.
At today's prices the portal's spot model shows EBITDA of minus RUB 5,136.7 mn versus minus RUB 12,598 mn over 12 months
Under the portal's spot model, annual EBITDA at today's commodity prices is minus RUB 5,136.7 mn versus minus RUB 12,598 mn over the last 12 months, i.e. 59.2% higher. Coal prices have risen and that improves the base, but it remains negative.
With negative EBITDA the EV/EBITDA multiple is meaningless and the share cannot be valued on it. A market capitalisation of RUB 24,723.7 mn against RUB 306.2 bn of net debt means the enterprise value consists almost entirely of debt.
On the portal's model the upside of the share to fair value is estimated at minus 90%, but the value sits on the model's clamp, so it is a bound, not an estimate. The benchmark shows that at current prices and debt the market pays more for the share than the model supports. Only a sustained rise in the coking coal price above USD 258.9 alongside a recovery in production volumes could change the picture.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 24.7 bn ₽ |
| Operating cash flow (LTM) | 40.3 bn |
| ROE | 38.8% |
Dividend per share, ₽, and yield at the ex-date
| Year paid | Dividend | Yield |
|---|---|---|
| 2018 | 16.66 | 16.4% |
| 2019 | 18.21 | 28.7% |
| 2020 | 3.48 | 5.5% |
| 2021 | 1.17 | 1.5% |
Bottom line
The strength of the report remains the price: coking coal rose 18.9% in roubles, and spot is another 8.8% above the quarterly average. But revenue fell 22.9%, EBITDA stayed negative, and at year-ago volumes and costs our calculation implies minus RUB 2,475.5 mn versus the reported minus RUB 4,875 mn – the gap came from volumes, realised prices and the sales mix. Net debt rose to RUB 306.2 bn, half-year interest was RUB 26,259 mn, and there are no dividends and, by our estimate, none coming. For a holder the key question is not the coal price but the company's ability to restore production and service debt; for now the share looks unattractive.
Open the company's financial profile MTLR →
See also: market overview · valuation map · stock screeners