MTS Bank 2Q2026: net profit up 90%, and half of the increase came from tax
MTS Bank published its interim IFRS statements for 1H2026, signed on 24 August, and on 25 August its parent MTS repeated the figures in its own release. Net profit for the second quarter almost doubled. Below is a breakdown of where this growth came from and what is happening to the bank's balance sheet.
Profit is up 90%, but before tax the growth is about half as strong
Net profit for the second quarter was RUB 4,733 mn versus RUB 2,495 mn a year earlier, up 89.7%. Profit before tax grew far more modestly, from RUB 3,942 mn to RUB 5,689 mn, up 44.3%.
The difference came from tax. Income tax expense was RUB 956 mn versus RUB 1,447 mn, and the effective rate fell from 36.7% to 16.8%. About half of the increase in net profit is explained by this rather than by the bank's operations.
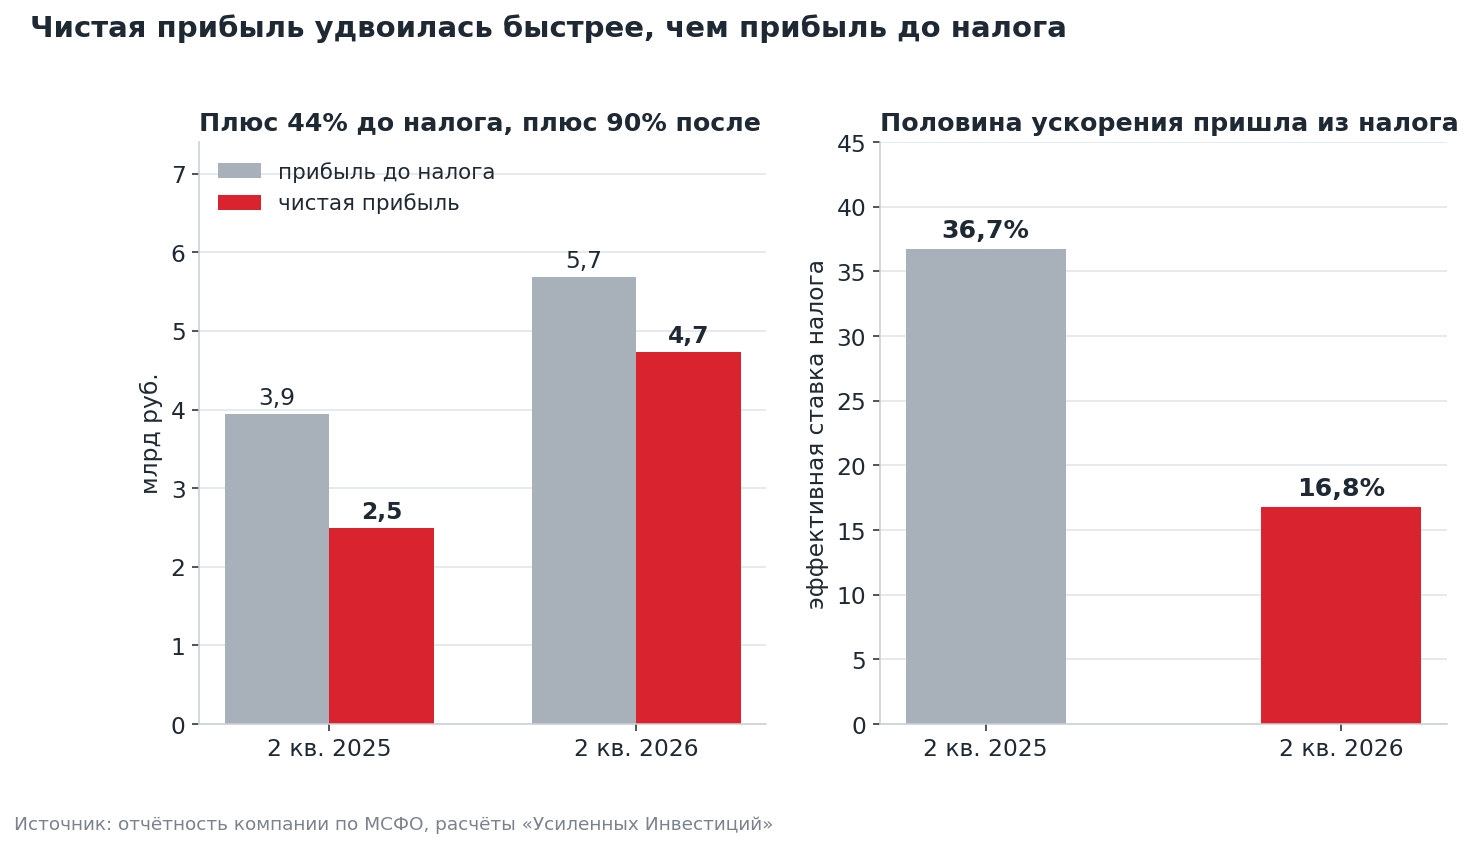
For the half-year the bank earned RUB 7,240 mn versus RUB 3,467 mn. Earnings per share were RUB 97 for the quarter and RUB 152 for the half-year, after deducting coupons on perpetual bonds.
The margin grew because funding got cheaper, not because of new lending
Net interest income for the quarter was RUB 14,398 mn versus RUB 10,681 mn, up 34.8%. The source of growth is clear. Interest expense fell from RUB 24.0 bn to RUB 16.3 bn, while interest income declined from RUB 35.0 bn to RUB 31.1 bn.
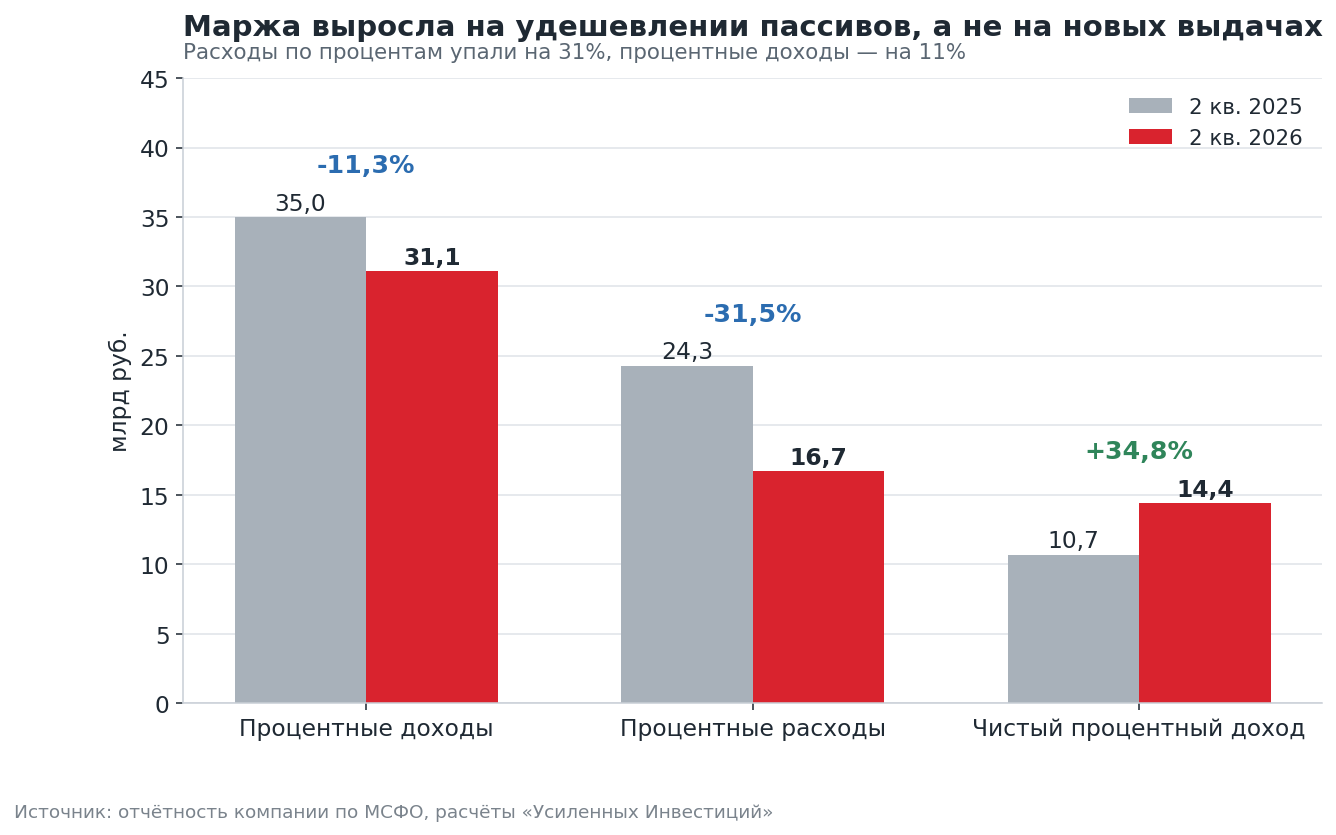
The bank is at a convenient point in the cycle. Liabilities reprice faster than assets, and the cut in the key rate (in July 2026 the central bank lowered it to 14.00%) works in favour of the margin. By nature the effect is temporary, since the loan portfolio will gradually reprice as well.
Fees are below last year's for the fourth quarter in a row, and expenses rose by 34%
Net fee and commission income was RUB 3,468 mn versus RUB 3,794 mn a year earlier. Fee income barely changed, RUB 5,871 mn versus RUB 5,913 mn, while fee expenses rose to RUB 2,403 mn. Fees have now stayed below the prior-year level for the fourth quarter in a row.
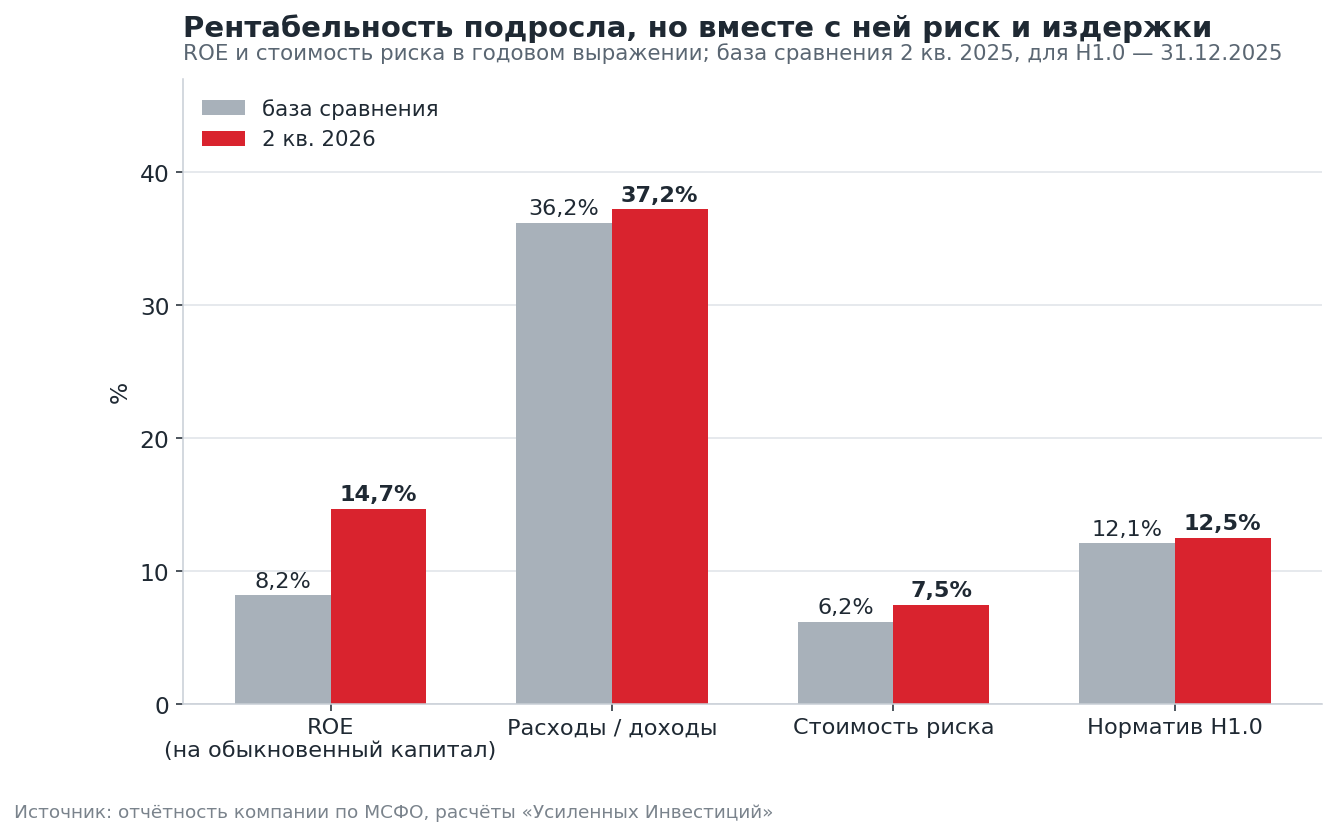
Operating expenses rose from RUB 5,627 mn to RUB 7,560 mn, up 34.4%. The cost-to-income ratio rose from 36.2% to 37.2%. Part of the margin gain went into costs.
Other net income gained 72% and reached RUB 2,443 mn, which noticeably supported the quarter.
The retail portfolio has fallen below RUB 307 bn, and corporate borrowers are taking its place
Gross loans to customers barely changed, RUB 374.2 bn versus RUB 382.6 bn at the end of 2025. The structure, however, has turned around.
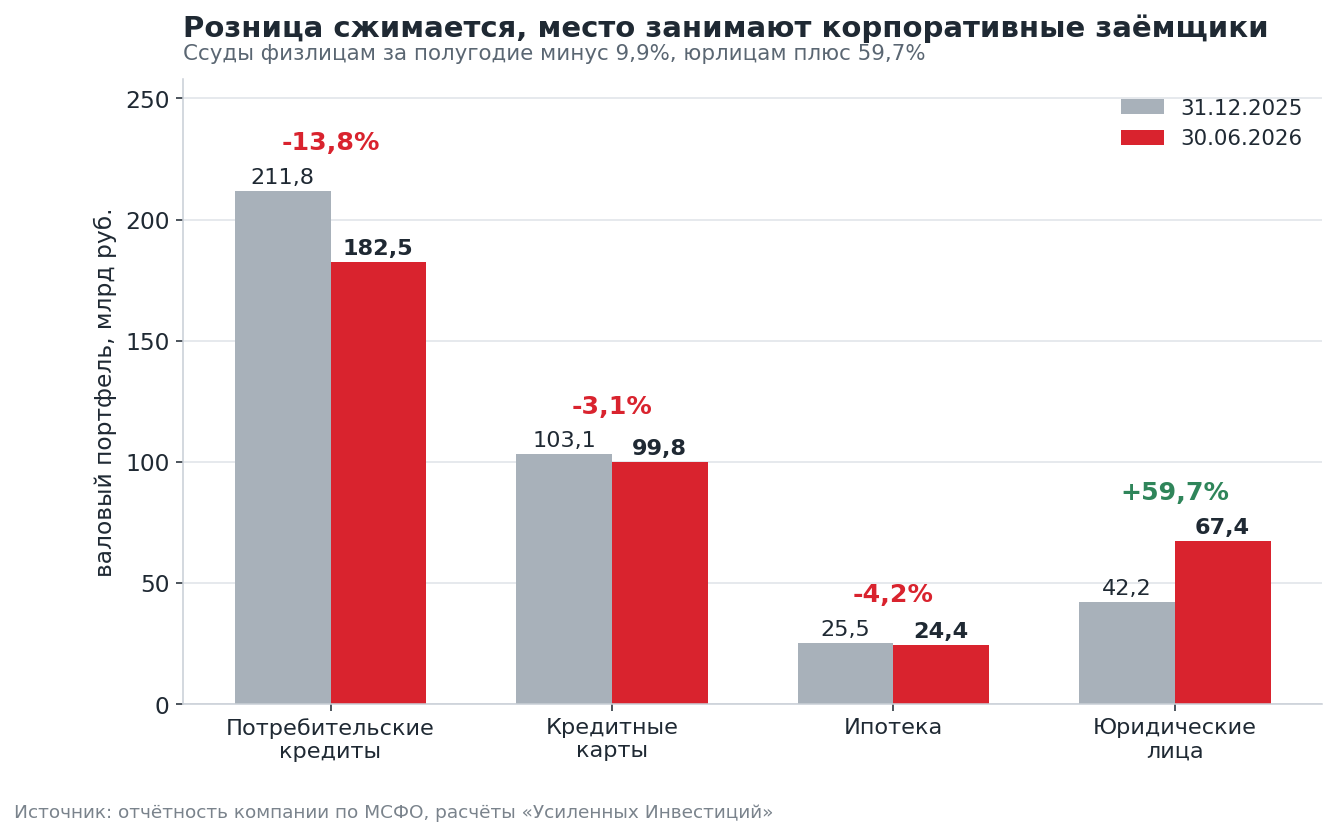
Loans to individuals fell from RUB 340.4 bn to RUB 306.8 bn, down 9.9% over the half-year. The main hit came from consumer loans, down 13.8%. Loans to legal entities over the same period grew from RUB 42.2 bn to RUB 67.4 bn, up 59.7%. Within the corporate block, manufacturing grew from RUB 8.0 bn to RUB 31.7 bn, and transport and communications from RUB 1.8 bn to RUB 6.2 bn.
A monoline retail lender is turning into a universal bank before our eyes. For an investor this is a change in risk profile. A corporate portfolio behaves differently from a card portfolio, and the bank has less accumulated statistics on it.
Provisions were cut together with the portfolio, and retail coverage fell to 9.7%
The allowance for expected credit losses decreased from RUB 43.8 bn to RUB 34.5 bn. Retail portfolio coverage declined from 11.6% to 9.7%. The annualised cost of risk on interest-earning assets stays at about 7.5% versus 6.2% a year earlier.
Provision charges for the quarter were RUB 7,087 mn versus RUB 5,979 mn. Part of the decline in the balance-sheet allowance is explained by write-offs and the shrinking of the portfolio itself, but the safety margin in coverage has become thinner.
Related parties account for 6.6% of the portfolio with almost no provision
Loans to related parties at 30 June are RUB 24,868 mn out of RUB 374,216 mn gross. The allowance against them is RUB 129 mn, or about 0.5%, versus a portfolio average of 9.2%. Over the half-year this position grew from RUB 21,314 mn.
Separately, the bank discloses that the debt of one borrower group of RUB 24,813 mn exceeds 10% of the group's capital. This figure almost exactly matches the volume of related-party transactions.
Capital is not growing, and the N1.0 ratio holds at 12.53%
Capital attributable to shareholders was practically unchanged over the half-year, RUB 126.2 bn versus RUB 126.3 bn. The profit of RUB 7.2 bn was absorbed by negative revaluation of securities, coupons on perpetual bonds of RUB 1.6 bn and dividends of RUB 3.6 bn declared in June.
Annualised return on common equity for the quarter is about 14.7% versus 8.2% a year earlier. Authors' estimate: profit is taken net of coupons on perpetual bonds.
The N1.0 capital adequacy ratio was 12.53% versus 12.11% at the end of 2025. Own funds under the central bank methodology declined from RUB 104.3 bn to RUB 101.7 bn, while the ratio rose thanks to lower risk-weighted assets. Group assets decreased from RUB 754.5 bn to RUB 692.8 bn.
EU sanctions in July and a price of one third of capital
In subsequent events the bank reports that in July 2026 it was included in the EU's 21st sanctions package and assesses the impact as insignificant. In the same month the 001P-05 bond issue of RUB 3 bn was redeemed.
At a price of about RUB 900 and 37.5 mn shares, the bank's market capitalisation is about RUB 33.8 bn. Common shares account for RUB 106.7 bn of capital after deducting the perpetual bonds recorded within equity instruments. This gives 0.32 of capital. Over the last 12 months the bank earned about RUB 15 bn attributable to common shares, so the market capitalisation amounts to a little over two years of earnings.
For comparison, in July 2025 the bank placed an additional share issue at RUB 1,380.5 per share. The current price is more than a third below that. The dividend of RUB 96.12 declared for 2025 yields about 11% on today's price.
If the 2Q pace holds, the year would bring about RUB 16 bn and a dividend of about RUB 107
The half-year closed with a profit of RUB 7.24 bn. From here everything depends on two things: whether the interest margin holds and whether tax returns to a normal rate. Three scenarios are calculated from the 1H fact.
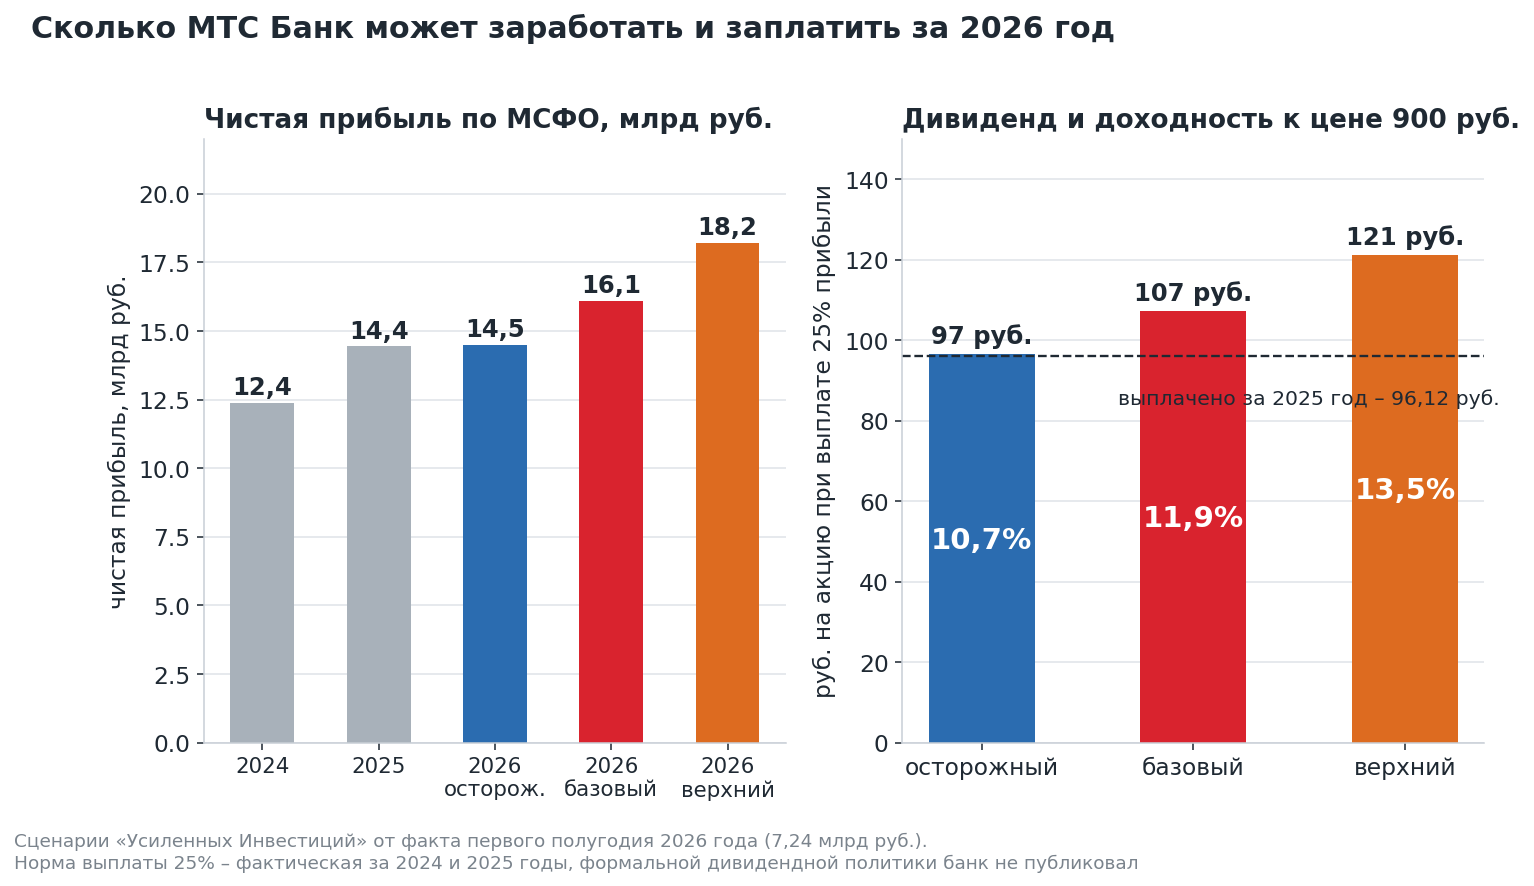
The cautious scenario assumes that the second half repeats the first. Profit for the year comes to RUB 14.5 bn, almost level with last year's RUB 14.4 bn. The base case assumes quarterly pre-tax profit stays at the second-quarter level and the effective tax rate returns to 22%. The year closes at about RUB 16.1 bn. The upper case keeps both the margin expansion and the low tax burden and gives RUB 18.2 bn.
For 2024 and 2025 the bank directed exactly a quarter of IFRS net profit to dividends. It has not published a formal dividend policy, but if this norm is kept, the dividend for 2026 falls in the range of RUB 97–121 per share, that is 10.7–13.5% on a price of about RUB 900. The payout is usually announced at the end of June and the money arrives in July, so the horizon here is almost a year.
The calculation breaks down in several places. The N1.0 ratio is 12.53%, and own funds under the central bank methodology fell from RUB 104.3 bn to RUB 101.7 bn over the half-year. The corporate portfolio added 60% in six months and requires capital, so the board may prefer to keep profit in the bank. Coupons on perpetual bonds of about RUB 3.1 bn a year are paid before the dividend. Finally, the source of the margin growth is itself temporary. Liabilities have already repriced following the key rate, the loan portfolio will reprice later, and then interest income will stop pulling profit up.
Tickers
Companies mentioned: MTS Bank, MTS. Extended cards with financial history and multiples are on our Frontier portal.
Summary
The quarter looks like a turnaround. The margin recovered, profit almost doubled, and return on capital is back to double digits. The quality of this turnaround is lower than the headline figure. Half of the profit growth came from tax, fees continue to shrink, costs are growing faster than income, and provision coverage of the retail portfolio has fallen noticeably. A valuation of one third of capital leaves a cushion in case the shift to corporate lending goes without surprises.
See also: market overview · valuation map · stock screeners