MTS 2Q2026: net profit up 24-fold, of which RUB 55.8bn came from the tower stake sale
On 25 August MTS published its results for the second quarter of 2026. Revenue grew 9.2%, OIBDA 16.3%, and net profit rose 23.9 times. Below is a breakdown of what produced this growth and what it means for a shareholder.
Revenue grew 9.2% and rests on telecom
Consolidated revenue for the second quarter was RUB 213.5bn against RUB 195.4bn a year earlier. For the half-year it was RUB 414.7bn against RUB 370.9bn, up 11.8%. The subscriber base in Russia grew by 1.2mn to 84.1mn. Paid TV users reached 15.9mn, one million more.
The breakdown by segment shows that telecom carried the quarter. It added RUB 14.9bn of revenue, while fintech subtracted RUB 2.6bn.
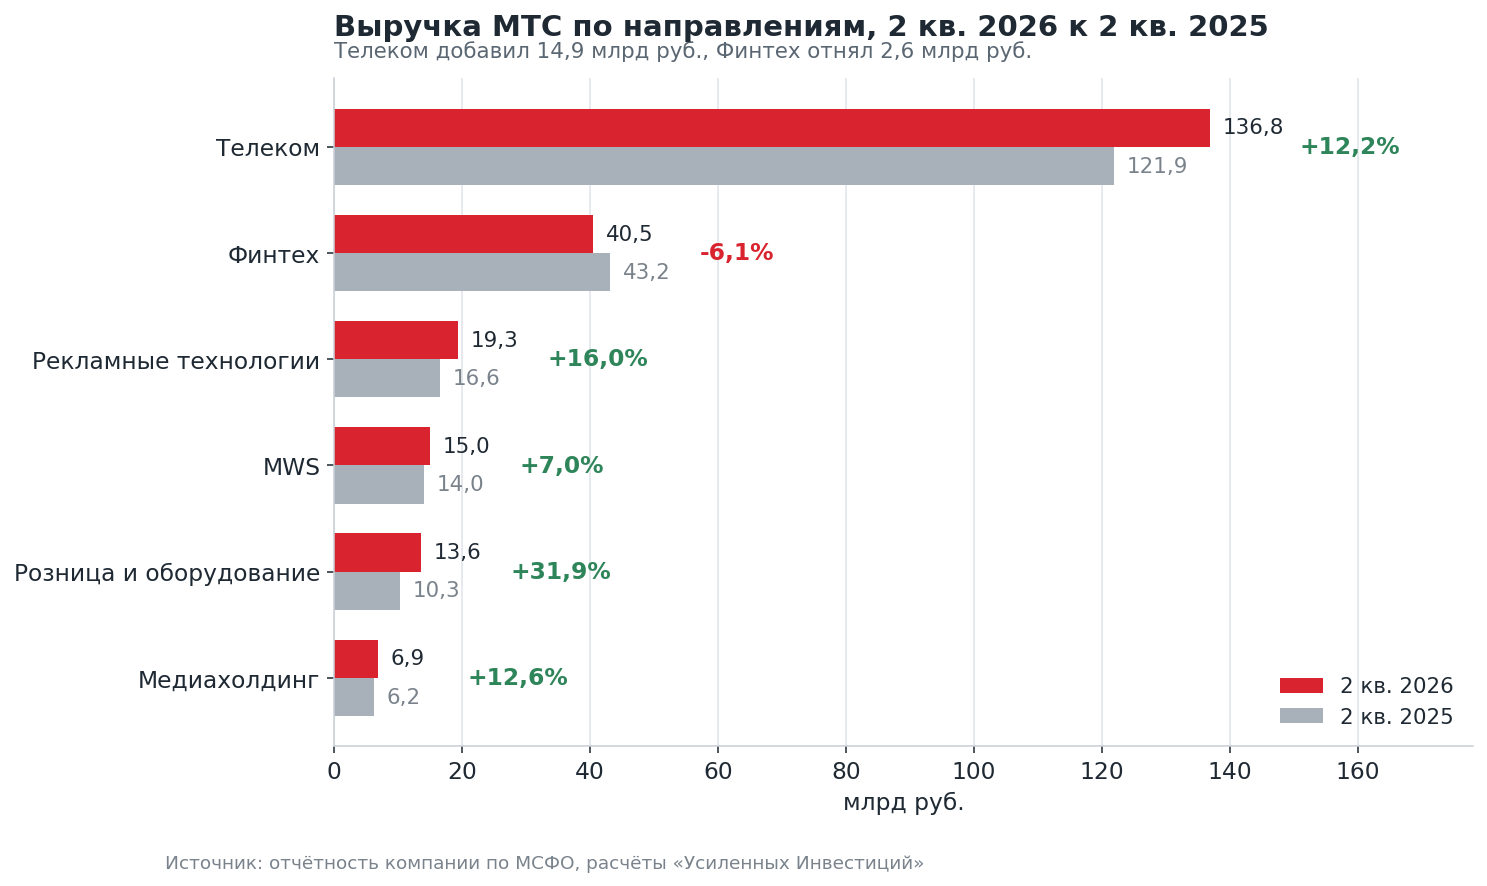
Within telecom, the fastest growth came from the interoperator business, up 36.8% to RUB 24.9bn. The core B2C business added a modest 5.8%, with mobile services up only 4.7%, below inflation. The advertising block is mixed. Marketing technology grew 36.4% to RUB 13.6bn, while advertising proper lost 14.3% and fell to RUB 5.7bn.
OIBDA up 16.3% on frozen commercial and administrative costs
Quarterly OIBDA was RUB 84.6bn against RUB 72.7bn. The main source of the outpacing growth is visible in the income statement. Selling, general and administrative expenses were RUB 35.1bn against RUB 34.8bn a year earlier, an increase of just 0.9%. For the half-year they rose 6.5% while revenue grew 11.8%.
Operating profit rose 22.4% to RUB 48.2bn. This is a high-quality result and does not depend on one-off items.
Of RUB 66.9bn profit, RUB 55.8bn came from the sale of a stake in the towers
Net profit attributable to shareholders for the quarter was RUB 66.9bn against RUB 2.8bn a year earlier. The line "other non-operating income" shows RUB 55.8bn against RUB 1.6bn last year. This is the result of selling a 49.9% stake in the Tower Infrastructure Company to the closed-end fund Investments 18.
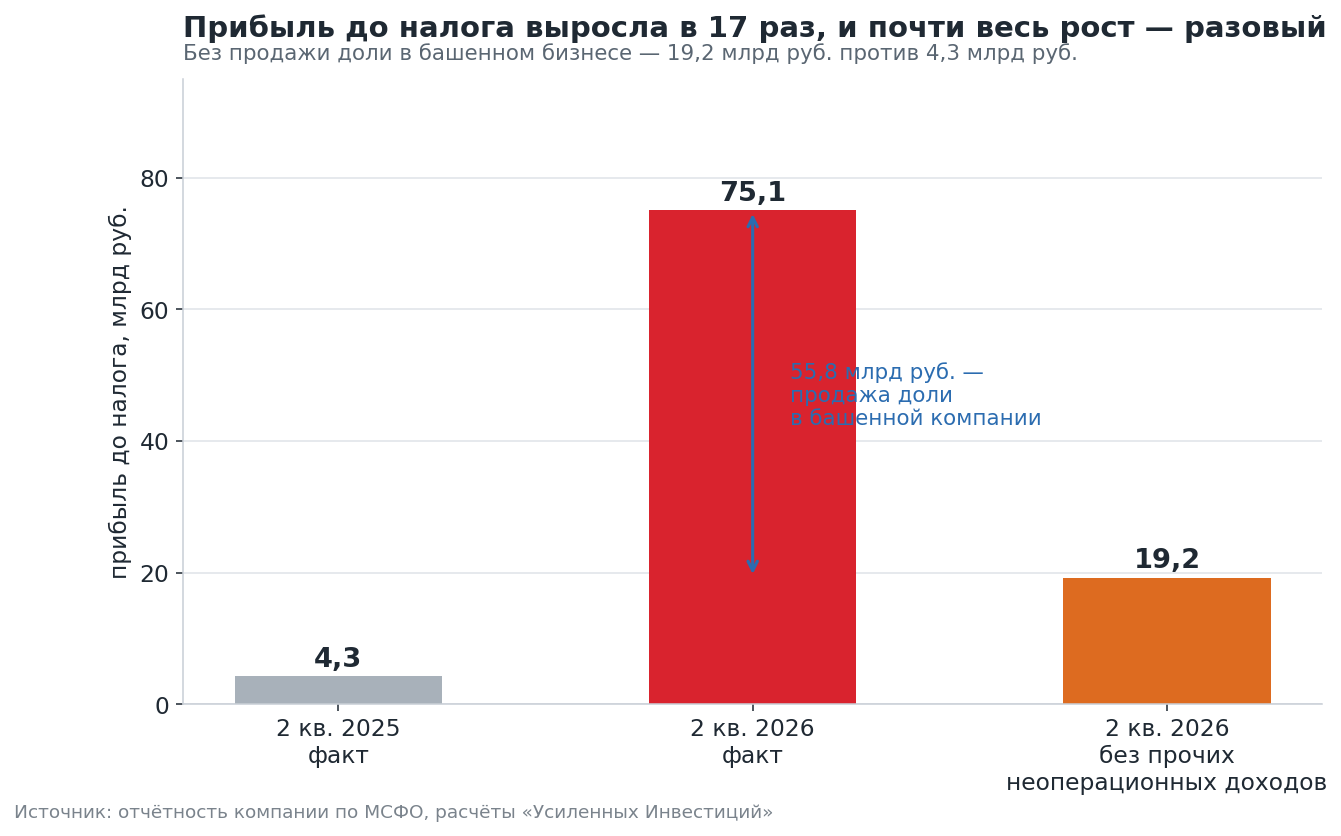
Without this item, profit before tax would have been RUB 19.2bn against RUB 4.3bn. That is still a fourfold increase, and its second source is fairly sustainable. Finance costs fell from RUB 39.7bn to RUB 33.1bn, down 16.6% on the lower key rate. The effective rate on debt fell by 5.8 percentage points over the year.
Earnings per share for the quarter were RUB 40.05 against RUB 1.68. For the half-year the company earned RUB 74.0bn against RUB 7.7bn.
Debt of 1.6x OIBDA is calculated without leases and with the cash of MTS Bank netted off
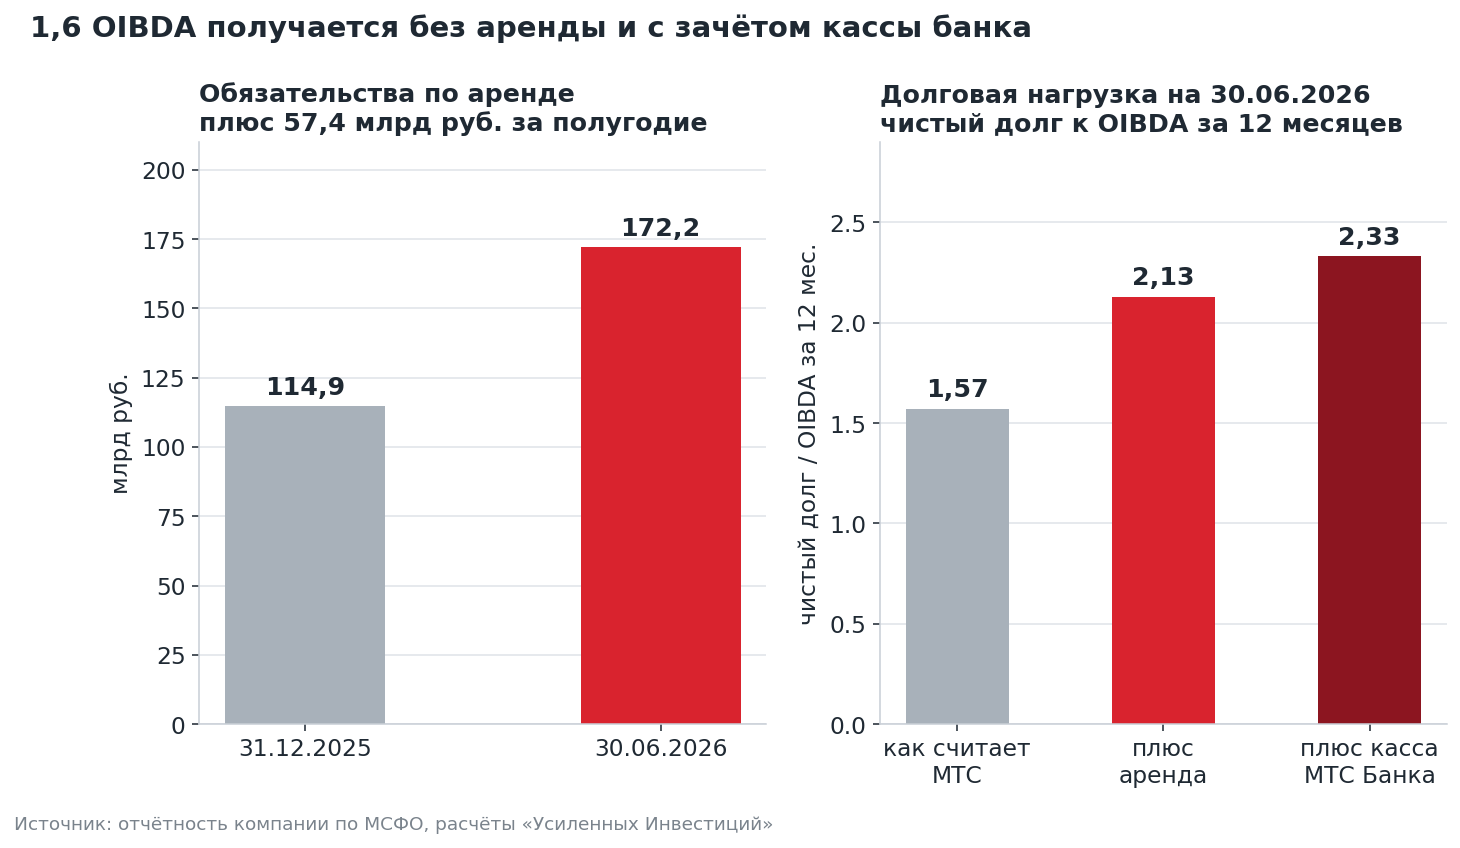
Net debt at 30 June was RUB 474.1bn, 10.1% above last year. Total debt was RUB 717.5bn, half in bonds and half in loans. The company puts the ratio of net debt to 12-month OIBDA at 1.6x and stresses that this is the lowest level since 2021.
The caveat in the footnote is material. The metric is calculated without lease liabilities. Over the half-year they rose from RUB 114.9bn to RUB 172.2bn, an increase of RUB 57.4bn. The sale of the tower stake removed part of the debt and at the same time turned owned infrastructure into leased infrastructure. Including leases, the leverage is 2.13x OIBDA.
The second caveat sits in the formula itself. MTS net debt is calculated as debt obligations minus cash minus short-term financial investments, and both deducted lines are consolidated, that is, they include the liquidity of MTS Bank. At 30 June the group's cash was RUB 64.5bn, while the bank's own reporting shows RUB 60.6bn. The cash of the subsidiary bank is deducted from the telecom's debt even though the telecom cannot access it. This was also the case before: at 31 December 2025, of the group's RUB 78.0bn of cash the bank held RUB 72.1bn, and at 31 March 2026, of RUB 130.1bn it held RUB 125.1bn.
If the bank's cash is put back, net debt comes to RUB 534.7bn, and together with leases to RUB 706.9bn. This is 2.33x OIBDA for the last 12 months instead of the 1.6x in the company's presentation. Part of the short-term financial investments that are also deducted is the bank's securities portfolio of RUB 238.4bn, so 2.33x is also a conservative estimate.
The dividend for 2025 is larger than what is left after construction and interest
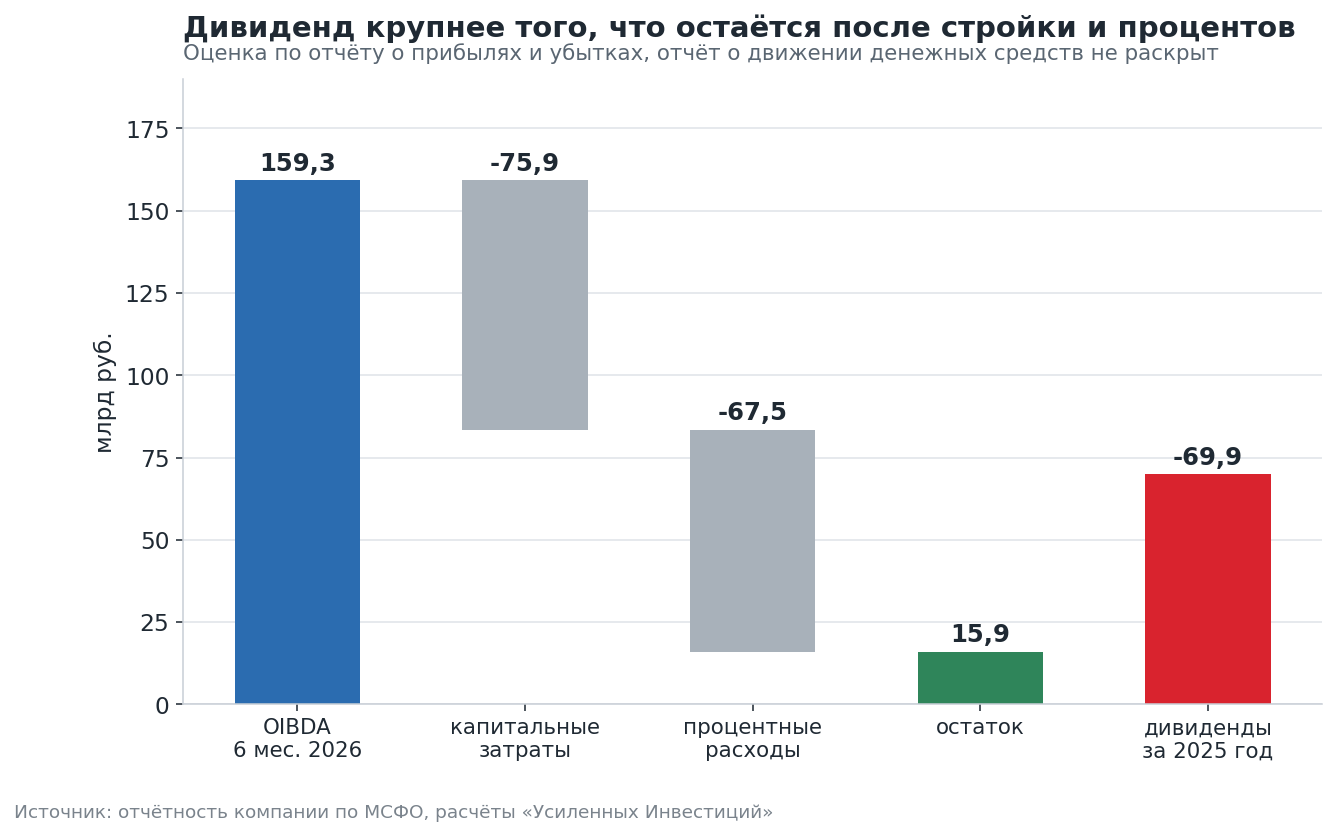
In August MTS completed the payment of RUB 35 per share, with total declared dividends of RUB 69.9bn. Capital expenditure for the half-year grew 21.6% to RUB 75.9bn, and the company states directly that it is investing more actively in infrastructure and the move to 5G.
The cash flow statement for the half-year is absent from the disclosure, so free cash flow has to be estimated indirectly. If capex and finance costs are subtracted from half-year OIBDA of RUB 159.3bn, about RUB 16bn remains before taxes and working capital. The dividend is four times larger.
The gap is closed by asset sales and new debt. Over the half-year the company placed three fixed-coupon bond issues at 13.55-13.90% for RUB 50bn, two floaters for another RUB 50bn, and signed a syndicated loan of RUB 40bn with an option to increase it to RUB 70bn. The MTS Savings service raised RUB 21bn from 96.3 thousand clients.
Shareholders' equity has only just come out of negative territory: RUB 4.1bn at 30 June against minus RUB 11.7bn at the end of 2025.
The press release itself contains two rough spots worth knowing about
The first concerns provisions. In the quarterly column, the line "expected credit losses" for the second quarter equals the half-year figure, RUB 19,688mn. In the first-quarter report there was no separate provisions line; they were included in "other operating expenses" at RUB 10,022mn. On subtraction, the entire half-year provision mechanically landed in the second quarter, and the difference was absorbed by other operating income, plus RUB 11,475mn. The sum of the two lines for the quarter and operating profit do not change as a result, but the provision cannot be compared directly with last year's RUB 5,535mn.
The second is simpler. Page 14 of the press release is titled "Consolidated statements of cash flows" but in fact repeats the income statement. There are no cash flows in the disclosure.
Valuation of 3.3x OIBDA and a new dividend policy in the autumn
At a price of about RUB 180 per share, MTS's market capitalisation is around RUB 360bn. With net debt and leases, enterprise value comes to roughly RUB 1.0tn, about 3.3x OIBDA for the last 12 months. The dividend paid in August gives 19% on the current price, but this is a yield for a past period.
The key fork is stated in the release itself. The company is at the final stage of approving a new dividend policy, with the parameters due to go to the Board of Directors in autumn 2026. For the last three years the payout has been exactly RUB 35 per share. The gap between the dividend and cash flow, rising capex and almost zero equity make a downward revision a fairly likely scenario, and the current valuation of the share depends on it.
Tickers
Companies mentioned: MTS, MTS Bank. Extended cards with financial history and multiples are available on our Frontier portal.
Summary
Operationally the quarter is strong. Revenue is growing 9%, OIBDA 16% with almost frozen administrative costs, and the cost of debt is falling along with the rate. The 24-fold growth in profit, however, was created by the sale of a stake in the tower business, and the decline in leverage was partly paid for by growing lease liabilities. For a shareholder, the main question lies not in the report but in the autumn dividend policy.
See also: market overview · valuation map · stock screeners